
 High-Sensitivity Luminometers Market | 2026-2036
High-Sensitivity Luminometers Market Size, Share, and Industry Trends Forecast 2026-2036
High-Sensitivity Luminometers Market Analytics
German precision optics manufacturing is expanding its dedicated cleanroom capacity for photon-counting detector assemblies. Thermo Fisher Scientific leverages backward integration into cooled-CCD sensor sourcing to protect margin pools on high-end systems. PerkinElmer anchors its position through long-term service contracts with national cancer institutes across Western Europe. Berthold Technologies specializes in military-specification luminometers that satisfy NATO-standard environmental tolerance requirements.
High-sensitivity luminometers are analytical instruments that quantify chemiluminescent or bioluminescent signals at detection thresholds below one femtomole, employing photomultiplier tubes or avalanche photodiodes cooled to minus twenty degrees Celsius to minimize dark-current noise. These systems enable quantitative measurement of ATP, luciferase reporter gene expression, and immunoassay endpoints in pharmaceutical quality control and clinical microbiology laboratories. Multi-mode configurations that integrate absorbance and fluorescence modules command premium positioning because laboratories prioritize capital efficiency over single-function devices. Pharmaceutical companies represent the fastest-growing end-user category as outsourced drug discovery campaigns in India and South Korea multiply contract screening volumes. Portable luminometers for field-based environmental monitoring remain a niche segment constrained by battery-limited cooling performance and lower dynamic range.
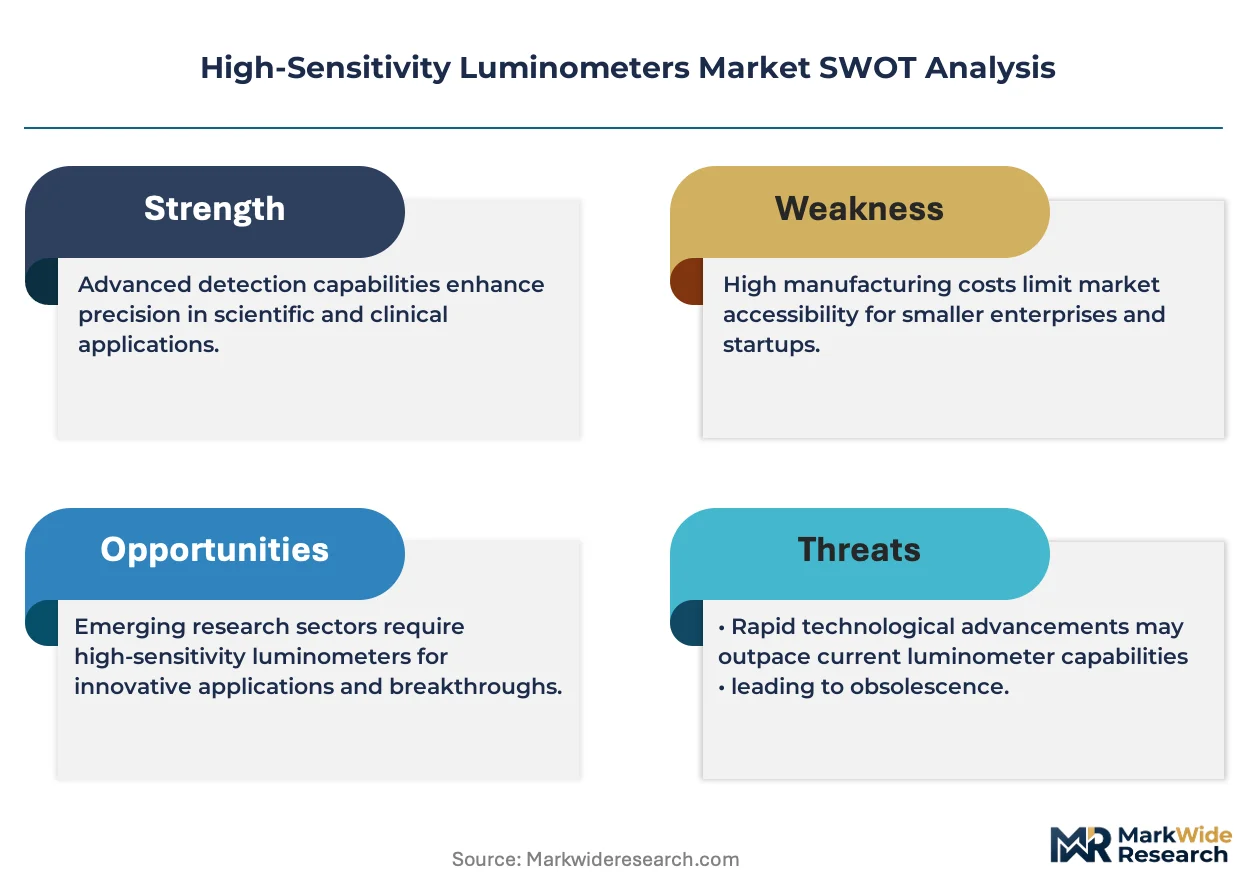
FDA 21 CFR Part 11 electronic records requirements shape software architecture decisions for instruments deployed in US pharmaceutical manufacturing quality labs. EMA's In Vitro Diagnostic Medical Devices Regulation and REACH substance restrictions on mercury-containing detectors jointly redirect European manufacturers toward solid-state photon-counting architectures. India's CDSCO medical device rules and BIS electromagnetic compatibility standards create layered compliance obligations for import-dependent healthcare facilities. Stakeholders must monitor divergence between FDA and EMA validation protocols for chemiluminescent immunoassays, as dual-certification burdens could reshape supplier selection criteria for multinational instrument vendors.
Market Dynamics
Consolidation of pharmaceutical quality control operations around multi-mode detection platforms is compressing replacement cycles for single-function luminometers, while cooled-CCD sensor shortages are forcing manufacturers to reconfigure supply chains for photon-counting architectures.
Growth Catalysts
- FDA 21 CFR Part 11 compliance mandates:Electronic records requirements for pharmaceutical manufacturing quality labs are accelerating instrument replacement cycles as legacy systems face validation obsolescence.
- Contract research organization fleet consolidation:Germany's Rhine-Main biotech cluster is driving demand for high-throughput multi-mode systems capable of ATP, luciferase, and immunoassay workflows on single platforms.
- Biologics testing expansion:Tightened FDA guidance on analytical instrument validation is forcing biopharmaceutical manufacturers to upgrade detection sensitivity thresholds for quality control protocols.
Market Restraints
- Mercury detector phase-out under REACH:ECHA substance restrictions are compelling European manufacturers to abandon legacy photomultiplier tube architectures before solid-state alternatives achieve cost parity.
- Liquid helium supply concentration:Cryogenic cooling systems depend on concentrated helium sourcing from Qatar and the United States, exposing production schedules to export quota volatility.
- Portable segment battery constraints:Field-based environmental monitoring applications remain limited by lithium-ion power density insufficient to sustain thermoelectric cooling at minus twenty degrees Celsius for extended deployment.
Strategic Opportunities
- India CDSCO medical device rule harmonization:Streamlined import pathways for analytical instruments are opening procurement channels for hospital laboratory networks previously dependent on refurbished equipment.
- Photon-counting avalanche photodiode convergence:Integration of solid-state detectors with artificial intelligence-based signal processing is enabling femtomole-level quantification without cryogenic cooling infrastructure.
- South Korean CRO screening volume multiplication:Outsourced drug discovery campaigns are generating demand for compact benchtop systems optimized for 384-well plate throughput in limited laboratory footprints.
Industry Challenges
- Photonics engineering talent scarcity:Design of cooled-CCD sensor assemblies requires specialized expertise in precision optics cleanroom manufacturing, with limited training pipeline capacity in German technical universities.
- Dual-certification validation burden:Divergence between FDA and EMA chemiluminescent immunoassay protocols is forcing multinational vendors to maintain parallel software architectures, extending development timelines.
- Legacy system integration complexity:Pharmaceutical quality labs face data migration challenges when connecting new luminometer platforms to existing laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Sensitivity Luminometers Market |
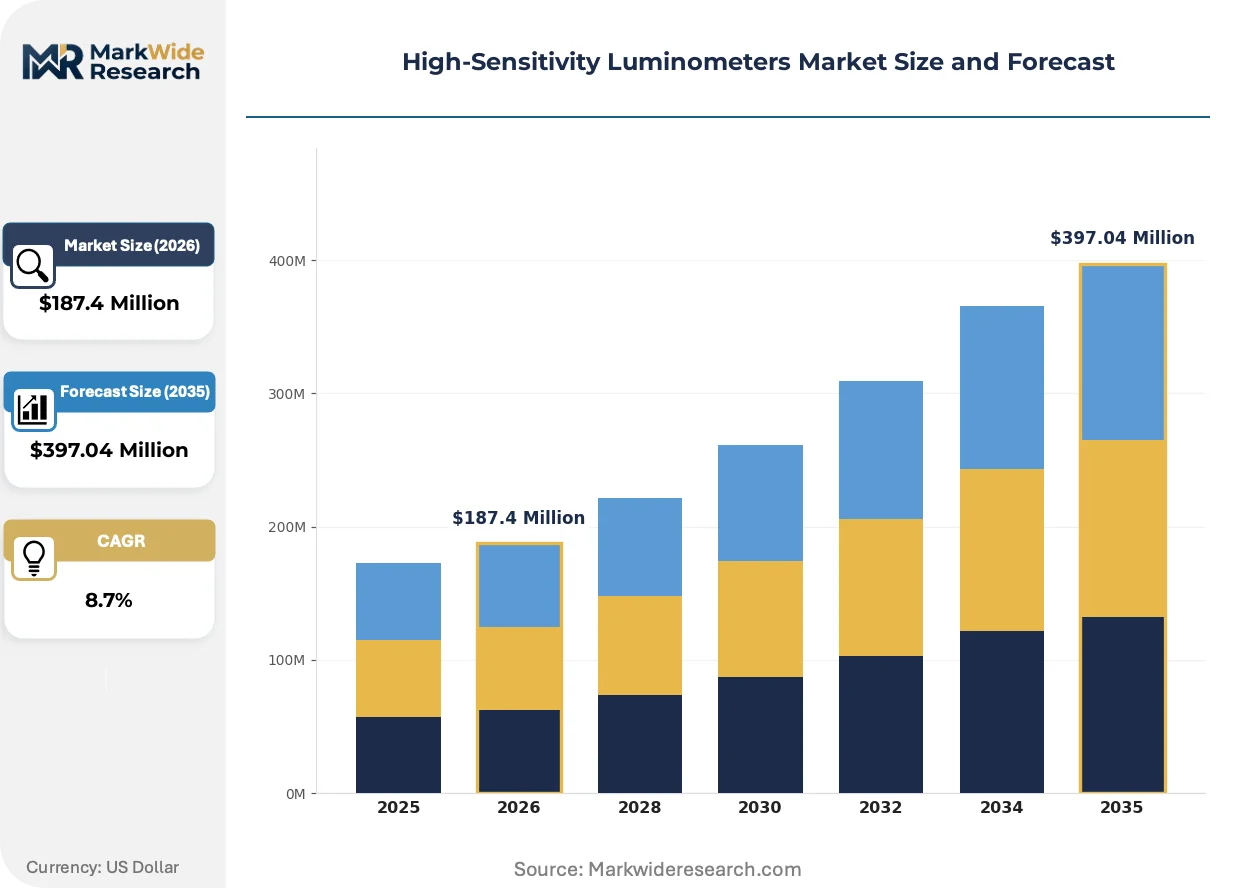
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Mode, Dual-Mode, Multi-Mode, Portable End User: Research Laboratories, Healthcare Facilities, Pharmaceutical Companies, Academic Institutions Technology: Photon Counting, Luminol-Based, LED-Based, Chemiluminescent Application: Drug Discovery, Clinical Diagnostics, Environmental Monitoring, Food Safety |
| Companies Covered | Thermo Fisher Scientific, PerkinElmer, Promega Corporation, Berthold Technologies, Bio-Rad Laboratories, Agilent Technologies, Tecan Group, BioTek Instruments, Analytik Jena, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Sensitivity Luminometers Market Evolving Landscape
Detection hardware architectures are converging with computational signal processing, while regulatory frameworks on both sides of the Atlantic are hardening validation requirements for biologics manufacturing quality control.
Solid-state photon-counting detectors are integrating avalanche photodiode arrays with on-chip temperature stabilization to eliminate cryogenic cooling requirements. Pharmaceutical quality control laboratories in North America are adopting these platforms at accelerated replacement cycles. This convergence is integrating previously separate capital equipment categories into unified multi-mode detection workflows.
EMA's In Vitro Diagnostic Medical Devices Regulation is mandating enhanced clinical evidence requirements for analytical instruments used in diagnostic workflows. European manufacturers are restructuring quality management systems to accommodate notified body oversight expansion. In vitro diagnostic segments in Germany and France are responding by consolidating supplier relationships with established CE-marked vendors possessing dedicated regulatory affairs capabilities.
Service contract unbundling is separating hardware procurement from maintenance and calibration agreements in academic and government laboratory segments. National cancer institutes across Western Europe are negotiating multi-year service tiers independent of initial capital purchases. This behavioral shift is most visible in Switzerland and the Netherlands, where core facility funding models prioritize operational expenditure flexibility over bundled capital allocations.
High-Sensitivity Luminometers Market Segmentation
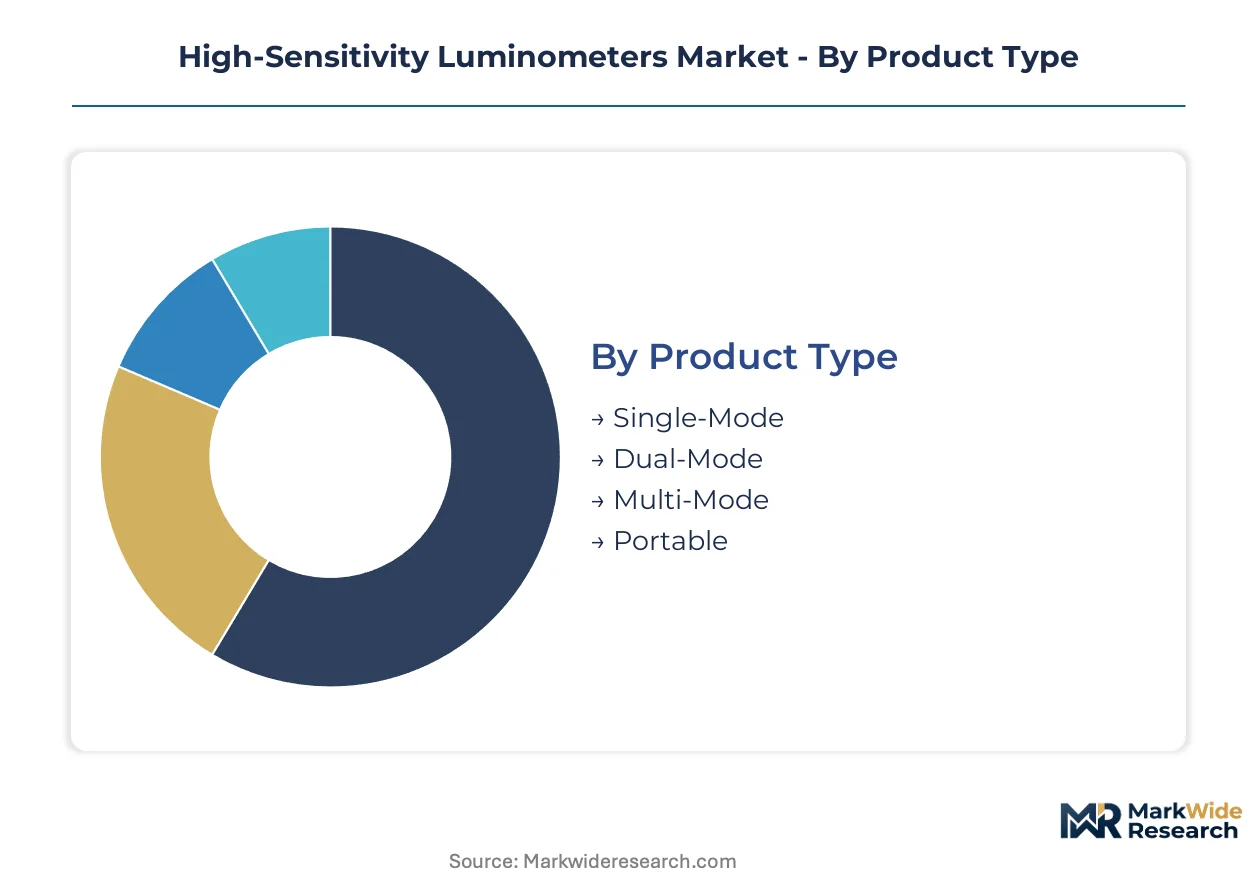
Segmentation in high-sensitivity luminometers reflects divergent capital deployment strategies across end-use environments. Standalone systems dominate pharmaceutical quality control, while embedded configurations integrate into automated screening platforms. Understanding these structural splits illuminates procurement patterns and replacement cycle dynamics.
Product Type:
Integration depth varies sharply across product architectures, with modular multi-mode systems embedding into high-throughput workflows while single-function units retain standalone deployment.
- Multi-Mode:Systems integrating absorbance, fluorescence, and luminescence modules on unified optical benches. Pharmaceutical companies in Germany's Rhine-Main cluster deploy these for consolidated ATP, luciferase, and immunoassay workflows on single capital platforms. Demand concentrates where laboratory footprint constraints and capital efficiency priorities intersect.
- Single-Mode:Dedicated luminometers optimized for specific detection chemistries with simplified optical paths. Academic core facilities in Switzerland and the Netherlands favor these for unbundled service contract flexibility. Procurement focuses on operational expenditure control over bundled capital allocations.
- Dual-Mode:Intermediate configurations pairing luminescence with one secondary detection modality. Contract research organizations in South Korea specify these for 384-well plate screening within limited bench space.
- Portable:Battery-powered units with thermoelectric cooling for field deployment. Environmental monitoring agencies deploy these despite lithium-ion power density constraints on sustained minus-twenty-degree operation.
Multi-Mode leads volumes today; Portable is gaining share fastest.
End User:
Customer type determines sensitivity specifications and validation requirements, with regulated manufacturers demanding femtomole thresholds that academic users rarely specify.
- Pharmaceutical Companies:Biologics manufacturers requiring FDA 21 CFR Part 11 compliant electronic records and EMA-validated detection protocols. Tightened FDA guidance on analytical instrument validation is accelerating replacement cycles for legacy systems. Outsourced drug discovery campaigns in India and South Korea are multiplying contract screening volumes.
- Research Laboratories:National cancer institutes across Western Europe negotiating multi-year service tiers independent of initial capital purchases. Core facility funding models prioritize operational expenditure flexibility over bundled allocations.
- Healthcare Facilities:Hospital laboratory networks in India navigating CDSCO medical device rules and BIS electromagnetic compatibility standards for import-dependent procurement.
- Academic Institutions:University core facilities constrained by grant-funded capital cycles and shared-instrument access models.
Pharmaceutical Companies command premium pricing tiers; Research Laboratories are expanding procurement most quickly.
Technology:
Detector architecture choices pivot on cooling requirements and REACH substance restrictions, with solid-state alternatives displacing legacy photomultiplier tubes.
- Photon Counting:Avalanche photodiode arrays with on-chip temperature stabilization eliminating cryogenic infrastructure. Manufacturers are integrating artificial intelligence-based signal processing for femtomole-level quantification. North American pharmaceutical quality labs are adopting these at accelerated replacement cycles.
- Chemiluminescent:Conventional architectures employing cooled photomultiplier tubes for amplified signal detection. ECHA mercury restrictions under REACH are compelling European manufacturers to abandon these before solid-state alternatives achieve cost parity.
- Luminol-Based:Oxidation-coupled detection systems for reactive oxygen species quantification in microbiology applications.
- LED-Based:Solid-state excitation sources reducing warm-up time and maintenance intervals in high-throughput environments.
Photon Counting leads technology transitions; LED-Based configurations are penetrating routine screening most rapidly.
Application:
Workflow integration requirements shape instrument specifications, with regulated diagnostics demanding traceable calibration chains that research discovery tolerates.
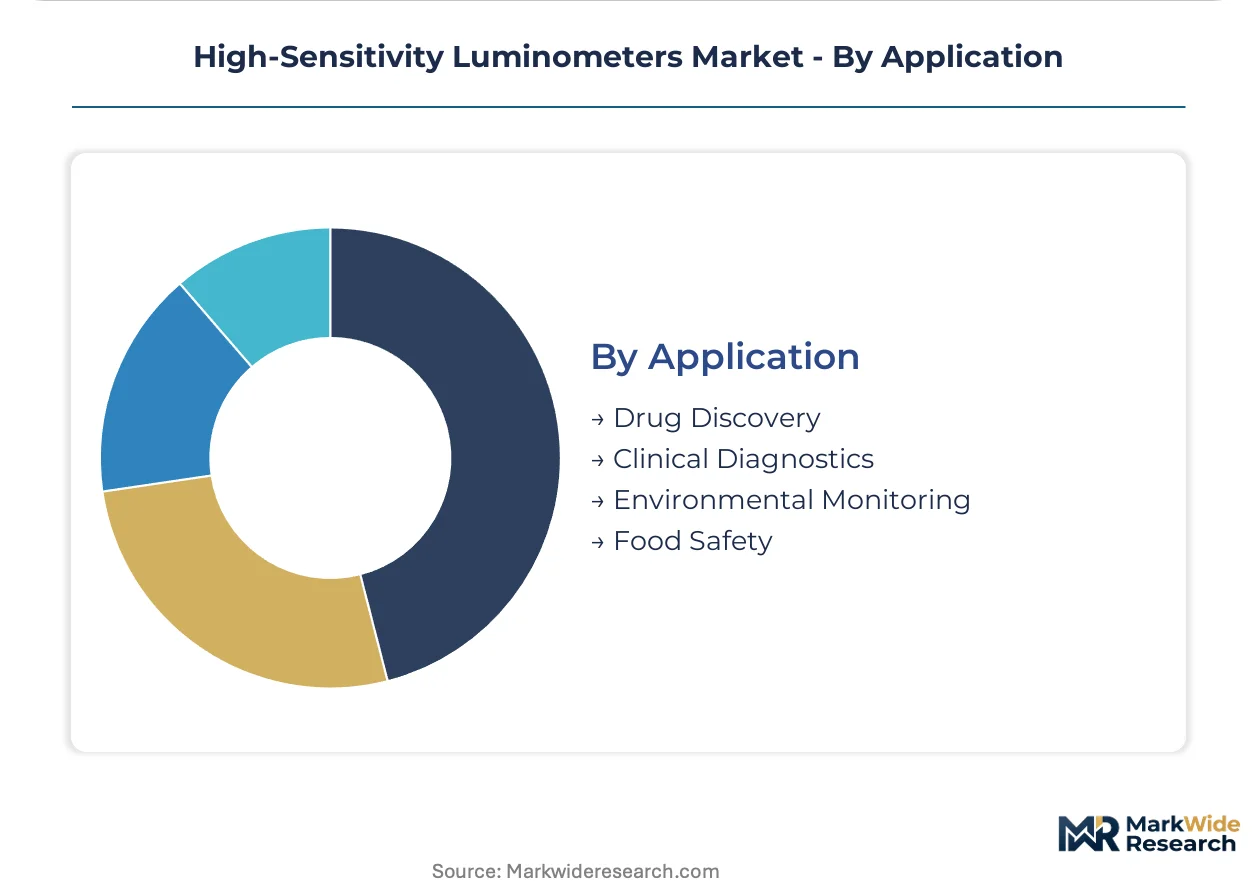
- Drug Discovery:High-throughput luciferase reporter gene assays requiring dynamic range across six orders of magnitude. Outsourced screening campaigns in India and South Korea are generating demand for compact benchtop systems optimized for limited laboratory footprints.
- Clinical Diagnostics:Chemiluminescent immunoassays subject to EMA In Vitro Diagnostic Medical Devices Regulation enhanced clinical evidence requirements. European manufacturers are restructuring quality management systems for notified body oversight expansion.
- Environmental Monitoring:Field-based ATP detection for microbial biomass assessment. Applications remain constrained by battery-limited cooling performance in portable configurations.
- Food Safety:Rapid hygiene verification using bioluminescent ATP detection in processing facilities.
Drug Discovery dominates capital deployment; Clinical Diagnostics is tightening regulatory requirements most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping procurement patterns as pharmaceutical manufacturers migrate quality control operations toward jurisdictions with streamlined validation pathways. Production of high-sensitivity detection systems concentrates where precision optics manufacturing clusters intersect with favorable medical device approval frameworks.
United States
FDA 21 CFR Part 11 electronic records mandates are accelerating replacement cycles for legacy luminometer platforms in pharmaceutical manufacturing quality labs. Biologics manufacturers face tightened guidance on analytical instrument validation, forcing upgrades to femtomole-threshold detection systems. The Greater Boston biotech corridor anchors demand for multi-mode systems capable of unified ATP, luciferase, and immunoassay workflows.
Germany
EMA's In Vitro Diagnostic Medical Devices Regulation is restructuring quality management systems for analytical instrument vendors serving European diagnostic workflows. REACH substance restrictions on mercury-containing detectors are compelling manufacturers to abandon legacy photomultiplier tube architectures. The Rhine-Main biotech cluster drives fleet consolidation among contract research organizations seeking high-throughput screening platforms.
India
CDSCO medical device rules and BIS electromagnetic compatibility standards are creating layered compliance obligations for import-dependent hospital laboratory networks. Streamlined import pathways are opening procurement channels for analytical instruments previously restricted to refurbished equipment. Outsourced drug discovery campaigns in Hyderabad and Bengaluru are multiplying contract screening volumes for compact benchtop systems.
South Korea
MFDS medical device registration requirements are shaping supplier selection criteria for multinational instrument vendors seeking diagnostic market access. Contract research organization screening volume multiplication is generating demand for 384-well plate optimized systems within limited laboratory footprints. The Seoul Capital Area concentrates procurement of portable configurations for field-based environmental monitoring despite battery constraints on sustained cooling performance.
Switzerland
Swissmedic oversight expansion is reinforcing consolidation of supplier relationships with established CE-marked vendors possessing dedicated regulatory affairs capabilities. National cancer institutes are negotiating multi-year service tiers independent of initial capital purchases. Core facility funding models across Basel and Zurich prioritize operational expenditure flexibility over bundled capital allocations.
High-Sensitivity Luminometers Market Competitive Landscape
German precision optics producers anchor one tier; North American diversified life science conglomerates hold another. The vendor base structures around three to five dominant players controlling premium multi-mode system supply, with mid-tier specialists occupying modular configurations and regional fabricators serving price-sensitive academic segments. Strategic archetypes include backward-integrated sensor manufacturers, service-contract anchoring specialists, and military-specification tolerance providers. Capacity expansion in cleanroom photon-counting detector assembly and artificial intelligence signal processing integration represent the dominant competitive vectors.
Among diversified life science conglomerates, Thermo Fisher Scientific exemplifies backward integration archetypes through captive cooled-CCD sensor sourcing. PerkinElmer occupies a position emphasizing long-term service contract anchoring with national research institutes. Berthold Technologies represents military-specification specialists satisfying environmental tolerance requirements for field-deployable configurations. These three anchors illustrate how competitive positioning diverges across integration depth, customer relationship duration, and application environment specialization.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| PerkinElmer |
| Promega Corporation |
| Berthold Technologies |
| Bio-Rad Laboratories |
| Agilent Technologies |
| Tecan Group |
| BioTek Instruments |
| Analytik Jena |
| Others |
Value Network & Pricing Analysis
Backward integration into cooled-CCD sensor sourcing anchors Thermo Fisher Scientific's supply position and pricing power against photon-counting detector shortages. This captive supply strategy insulates margin pools on high-end multi-mode systems while competitors face component cost volatility.
Pricing Analysis
Distributor margins on single-mode luminometers compress as direct-to-OEM channels expand for pharmaceutical fleet contracts. Pricing stratifies across premium multi-mode, standard dual-mode, and economy single-function tiers, with certification grade driving differentiation between FDA 21 CFR Part 11 compliant and research-grade instruments. Cost compression in the portable segment intensifies because lithium-ion battery constraints limit thermoelectric cooling performance. Academic core facilities exhibit highest price sensitivity; biologics manufacturers prioritize detection sensitivity over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for photomultiplier tubes compel manufacturers to qualify both German and Japanese suppliers under REACH mercury restrictions. Precision optics manufacturing concentrates in Germany, sensor fabrication in Japan, and final assembly in the United States. Cryogenic cooling systems draw from concentrated helium sourcing in Qatar and the United States, exposing production schedules to export quota volatility. Distribution runs through authorized service partners for installation and calibration in regulated pharmaceutical environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high-sensitivity luminometers market compounds steadily as biologics testing expansion drives replacement cycle acceleration across pharmaceutical quality control operations.
For Market Incumbents: Extend service contract anchoring with national cancer institutes to lock in multi-year revenue streams against portable segment entrants. Deepen backward integration into solid-state photon-counting detector manufacturing to escape REACH mercury restrictions and photonics engineering talent scarcity. Prioritize artificial intelligence signal processing R&D to differentiate femtomole-level quantification without cryogenic infrastructure. For New Entrants and Emerging Players: Direct-to-researcher digital channels bypass established distributor networks for academic core facility segments in Switzerland and the Netherlands. Target India's hospital laboratory networks navigating CDSCO import pathways as the most penetrable geography. Emphasize unbundled hardware procurement with independent calibration service tiers to match operational expenditure flexibility preferences. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier modular luminometer specialists because pharmaceutical fleet consolidation demands scalable multi-mode platforms with regulatory affairs capabilities. Five-to-ten year viability hinges on photon-counting architecture transitions displacing legacy photomultiplier tubes. Monitor divergence between FDA and EMA chemiluminescent immunoassay protocols as the inflection signal for dual-certification burden winners.| Strategic Initiative | Industry Significance |
|---|---|
| Photon-Counting Detector Integration | Eliminates cryogenic cooling infrastructure for North American pharmaceutical quality labs. |
| Long-Term Service Contract Anchoring | PerkinElmer secures revenue visibility with national cancer institutes across Western Europe. |
| Backward Integration into Sensor Sourcing | Thermo Fisher Scientific protects margin pools against cooled-CCD supply shortages. |
| Regulatory Affairs Capability Buildout | CE-marked vendors capture EMA In Vitro Diagnostic Medical Devices Regulation consolidation. |
| Artificial Intelligence Signal Processing | Enables femtomole-level quantification without liquid helium dependency for field deployment. |
Research Methodology
Multiple input streams — procurement managers at pharmaceutical quality control labs, regulatory affairs leads at instrument manufacturers, biomedical engineers at hospital networks, and aftermarket service heads — were reconciled against FDA 510(k) filings, EMA CE marking databases, CDSCO import records, and German precision optics trade association data. Bottom-up unit demand estimates and top-down market sizing triangulated across these sources.
Data-stream reconciliation applied product type, end user, technology, application, and regional regulatory cluster segmentation across the projection horizon. CAGRs derived from replacement cycle analysis and biologics testing volume elasticity. Forecast inputs incorporated REACH substance restriction timelines and helium supply quota volatility.
The model assumes a particular technology adoption path; alternative pathways for solid-state avalanche photodiode convergence would alter the outlook if cryogenic cooling cost parity arrives faster than projected. Deviation in FDA-EMA protocol harmonization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
North America Surface Analysis Market
Analytical Instruments
Energy Dispersive X-Ray Spectrometer Market
Analytical Instruments
Europe Handheld Spectrum Analyzer Market
Analytical Instruments
Automated Microplate Handling Systems Market
Analytical Instruments
Global TOC Analyzer Market
Analytical Instruments
Africa Digital Thermometer Market
Analytical Instruments
X-Ray Fluorescence Analyzer Market
Analytical Instruments
Battery Testers and Analyzers Market
Analytical Instruments
Turbidimeter Market
Analytical Instruments
Real-Time Spectrum Analysis Market
Analytical Instruments
Lab-On-A-Chip Device Market
Analytical Instruments
Wireless Handheld Spectrometer Market
Analytical Instruments
Global IR Spectroscopy Market
Analytical Instruments
Laser Diffraction Analyzer Market
Analytical Instruments
Portable Gas Analyzer Market
Analytical Instruments
Thermoluminescent Dosimeter (TLD) System Market