
 Organic Meat Products Market | 2026-2036
Organic Meat Products Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Meat Products Market Intelligence
EU Green Deal is realigning the cost-of-entry calculus for organic meat processors across Europe. Tyson Foods Inc. leverages its vertically integrated poultry network to secure USDA Organic feed supply chains at scale. Perdue Farms anchors its competitive position through controlled-environment housing systems that exceed National Organic Program animal welfare benchmarks. JBS S.A. competes in the premium grass-fed segment via dedicated organic cattle sourcing partnerships in Australia and South America.
Organic meat products denote livestock-derived protein from animals raised without synthetic hormones, antibiotics, or genetically modified feed, meeting third-party certification standards for pasture access and chemical-free production. These products serve commercial and retail buyers seeking verified residue-free protein with full supply chain traceability. Beef and poultry command the largest volume shares, with beef margin pools concentrating in premium grass-fed subcategories while poultry benefits from shorter production cycles and lower feed conversion ratios. The distribution channel structure shows supermarkets capturing mainstream volume, though specialty stores and online retailers are gaining traction among subscription-based buyers seeking direct-farm provenance.
USDA Organic certification, EU Green Deal Farm to Fork requirements, and FDA antibiotic residue testing protocols collectively shape product standards, import eligibility, and label claim enforceability across major markets. The National Organic Program's updated livestock standards are tightening outdoor access mandates, forcing processors to reformulate sourcing contracts or risk decertification. Stakeholders must monitor evolving feed cost volatility and certification harmonization gaps between regional standards to sustain margin integrity through the forecast horizon.
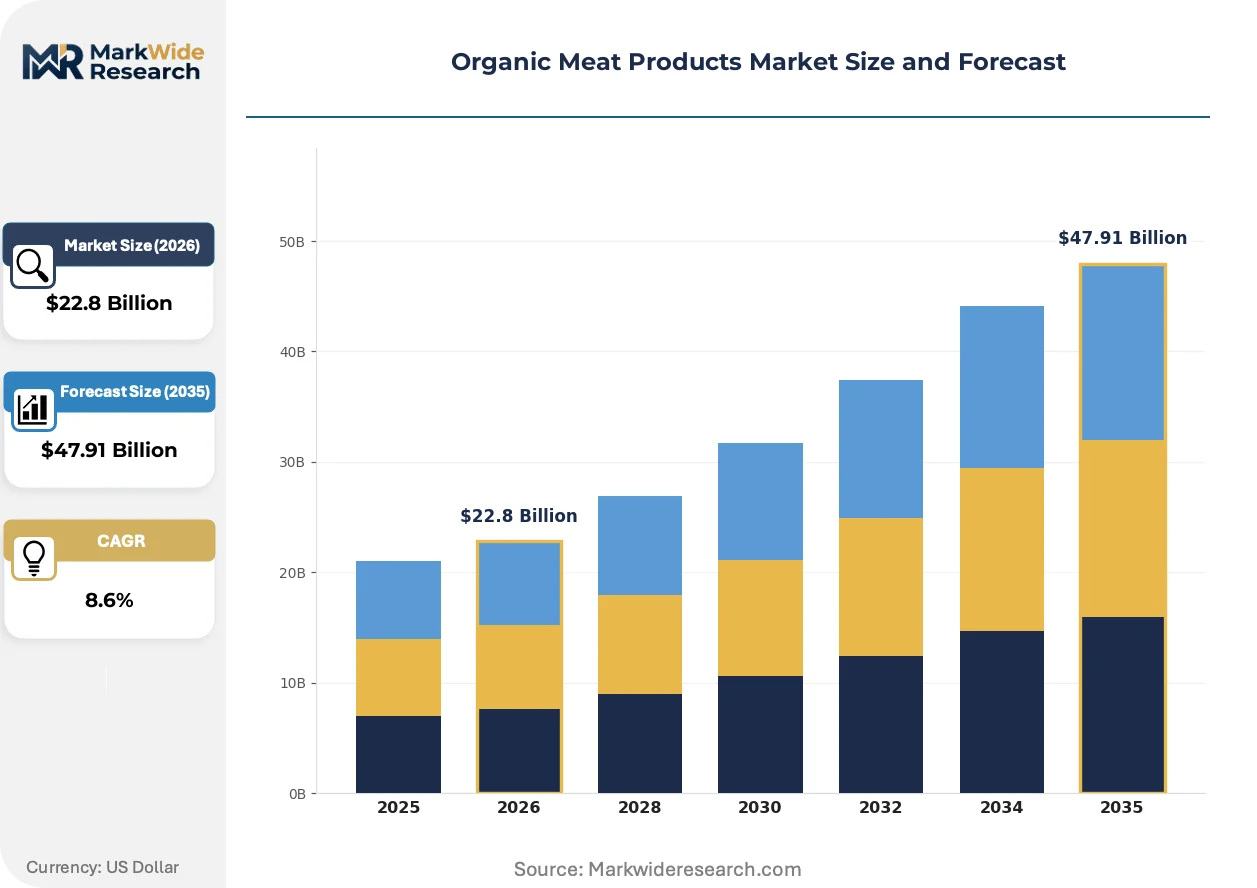
Market Dynamics
The EU Green Deal's Farm to Fork Strategy is tightening chemical residue limits and animal welfare benchmarks, forcing organic meat processors across Europe to reformulate sourcing contracts or risk decertification. This regulatory pressure is reshaping certification requirements across the value chain while concentrating demand in markets with established traceability infrastructure.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:The regulation tightens chemical residue limits and animal welfare benchmarks, creating mandatory demand pull for certified organic protein across European retail channels.
- Grass-fed beef subcategory:Premium positioning in this segment commands sustained margin pools as health-conscious consumers in Germany and France prioritize verified pasture-raised sourcing.
- Controlled-environment housing systems:These technologies exceed National Organic Program animal welfare benchmarks, enabling poultry processors to secure premium shelf placement in North American supermarkets.
Market Restraints
- Organic feed cost volatility:Corn and soybean price swings directly compress processor margins, as certified organic feed commands sustained premiums over conventional alternatives.
- Certification harmonization gaps:Divergent standards between USDA Organic and EU organic regulations create friction for cross-border trade and label claim enforceability.
- Antibiotic-free production cycles:Extended grow-out periods required for organic compliance reduce throughput velocity compared to conventional livestock operations.
Strategic Opportunities
- Subscription-based direct-farm provenance:Online retailers are capturing subscription buyers seeking full supply chain traceability, bypassing traditional supermarket intermediaries.
- EU Green Deal regulatory tailwind:The strategy's chemical residue limits create structural advantage for early-compliant processors in German retail discounter channels.
- Blockchain-IoT convergence:Distributed ledger systems combined with sensor networks enable real-time pasture verification, reducing audit costs for grass-fed certification claims.
Industry Challenges
- National Organic Program outdoor access mandates:Updated livestock standards force processors to reconfigure housing contracts, creating compliance timeline risk for existing certification holders.
- Veterinary skill scarcity:Shortage of practitioners trained in preventive health protocols for antibiotic-free livestock operations constrains herd expansion plans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Meat Products Market |
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $47.91 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Poultry, Lamb Packaging Type: Vacuum Sealed, Tray Pack, Canned, Fresh Distribution Channel: Supermarkets, Specialty Stores, Online Retailers, Farmers Markets Customer Type: Health-Conscious Consumers, Restaurants, Retailers, Food Service Providers |
| Companies Covered | Tyson Foods Inc., Perdue Farms, JBS S.A., Danish Crown, Verde Farms, Meyer Natural Foods, Organic Prairie, Eversfield Organic Ltd., OBE Organic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Meat Products Market Strategic Shifts & Innovations
Clean-label verification technologies are actively reshaping competitive positioning in organic meat, as buyers demand residue-free protein with immutable supply chain documentation. Processors are deploying sensor networks and distributed ledgers to compress audit cycles and reduce certification friction.
Blockchain-enabled traceability platforms is overtaking paper-based chain-of-custody systems in premium organic meat segments. Retailers in Germany and France are adopting these platforms at accelerated pace to satisfy discounter and butcher chain requirements for full provenance documentation. This technology is enabling real-time pasture verification that compresses third-party audit cycles from months to minutes.
REACH chemical residue protocols are extending testing scope to veterinary pharmaceutical metabolites previously unregulated in meat products. The industrial consequence is expanded laboratory capacity requirements for import eligibility into European markets. Beef exporters in Australia and South America are responding by pre-certifying slaughter batches against the tightened EFSA safety thresholds.
Buyer concentration in subscription channels is fragmenting traditional supermarket dominance as direct-farm platforms capture recurring revenue pools. Specialty online retailers are displacing mainstream grocers among health-conscious consumers seeking verified grass-fed and organic poultry with immutable documentation. This channel rotation is most visible in North American urban markets where meal-kit services integrate organic protein into weekly delivery schedules.
Organic Meat Products Market Segmentation
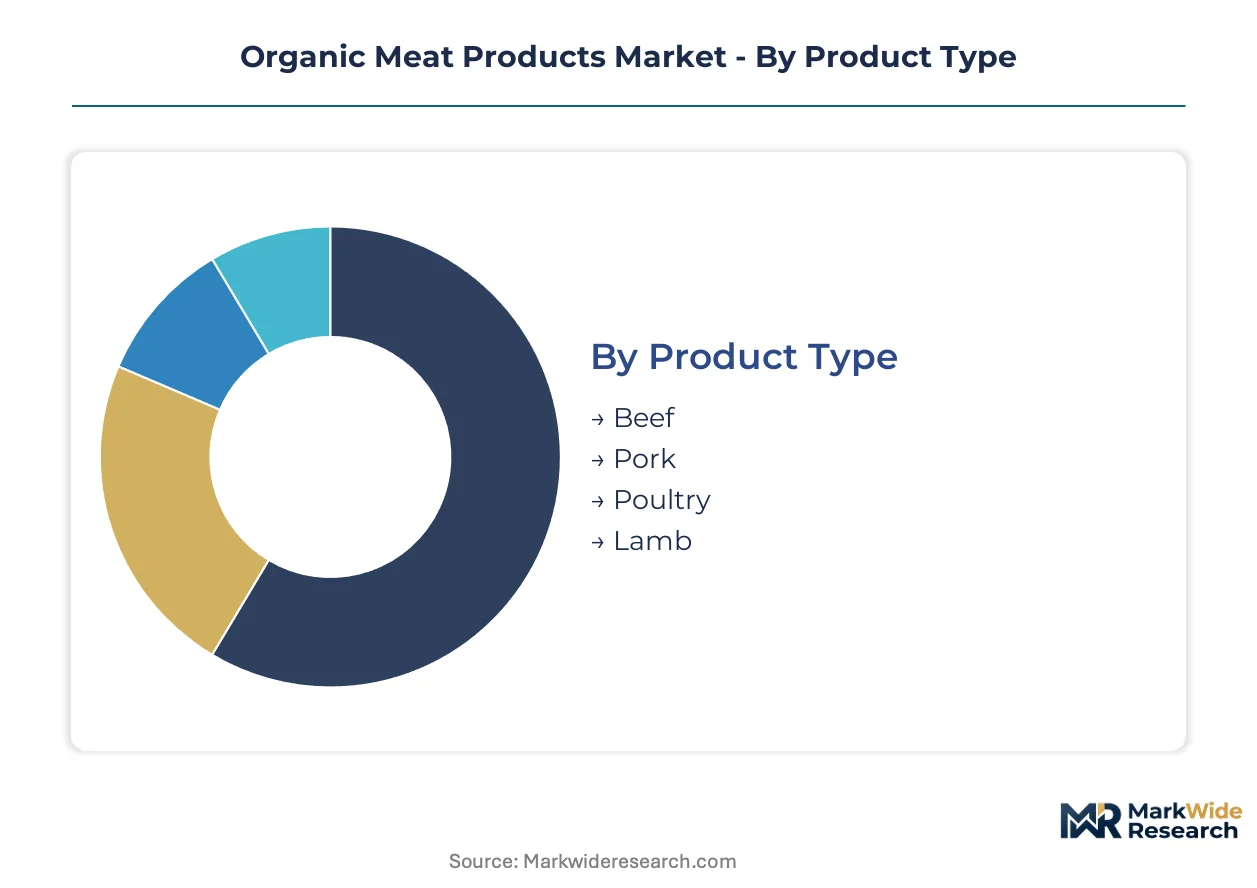
Organic meat segmentation reflects divergent margin pools across species, packaging technologies, and channel access. Certification requirements and shelf-life demands fragment procurement priorities, forcing processors to align production configurations with distinct buyer value chains.
Product Type:
Supply concentration in beef and poultry processing infrastructure shapes regional competitive dynamics.
- Beef:Grass-fed and grain-finished subcategories dominate premium shelf placement. German retail discounters and French premium butcher chains concentrate procurement in verified pasture-raised sourcing with full EFSA traceability documentation.
- Poultry:Shorter production cycles and superior feed conversion ratios compress cost structures versus ruminant species. Controlled-environment housing systems exceeding National Organic Program benchmarks secure premium positioning in North American supermarket channels.
- Pork:Narrower organic conversion rates in swine operations limit supply scalability relative to poultry.
- Lamb:Seasonal production patterns and regional pasture constraints restrict year-round availability in mainstream retail.
Today's leader: Beef. Tomorrow's challenger: Poultry.
Packaging Type:
Cost tier differentiation separates premium preservation technologies from commodity formats.
- Vacuum Sealed:Oxygen-exclusion technology extends shelf life while preserving color stability for retail display. German and French supermarkets prioritize this format for organic beef and lamb with extended distribution radii.
- Fresh:Unprocessed presentation commands highest per-unit margins in direct-farm and farmers market channels. Urban subscription services in North America concentrate demand here for weekly delivery schedules with minimal processing intervention.
- Tray Pack:Modified atmosphere configurations balance visibility with preservation for mainstream supermarket placement.
- Canned:Shelf-stable format serves emergency preparedness and remote distribution use cases with limited organic penetration.
Volume concentrates in vacuum sealed. Margin expansion centers on fresh.
Distribution Channel:
Customer type fragmentation is accelerating channel bifurcation between scale and provenance.
- Supermarkets:Centralized procurement and dedicated organic meat sections capture mainstream volume. German retail discounters have built full traceability systems to satisfy EU Green Deal Farm to Fork requirements.
- Online Retailers:Subscription-based direct-farm platforms bypass traditional intermediaries with immutable blockchain documentation. North American urban markets show fastest adoption among health-conscious consumers seeking weekly protein delivery.
- Specialty Stores:Curated assortment and staff expertise support premium positioning for grass-fed beef and heritage breed poultry.
- Farmers Markets:Face-to-face provenance verification serves local-food advocates with limited geographic scalability.
Supermarkets anchor current volume. Online retailers are climbing the fastest.
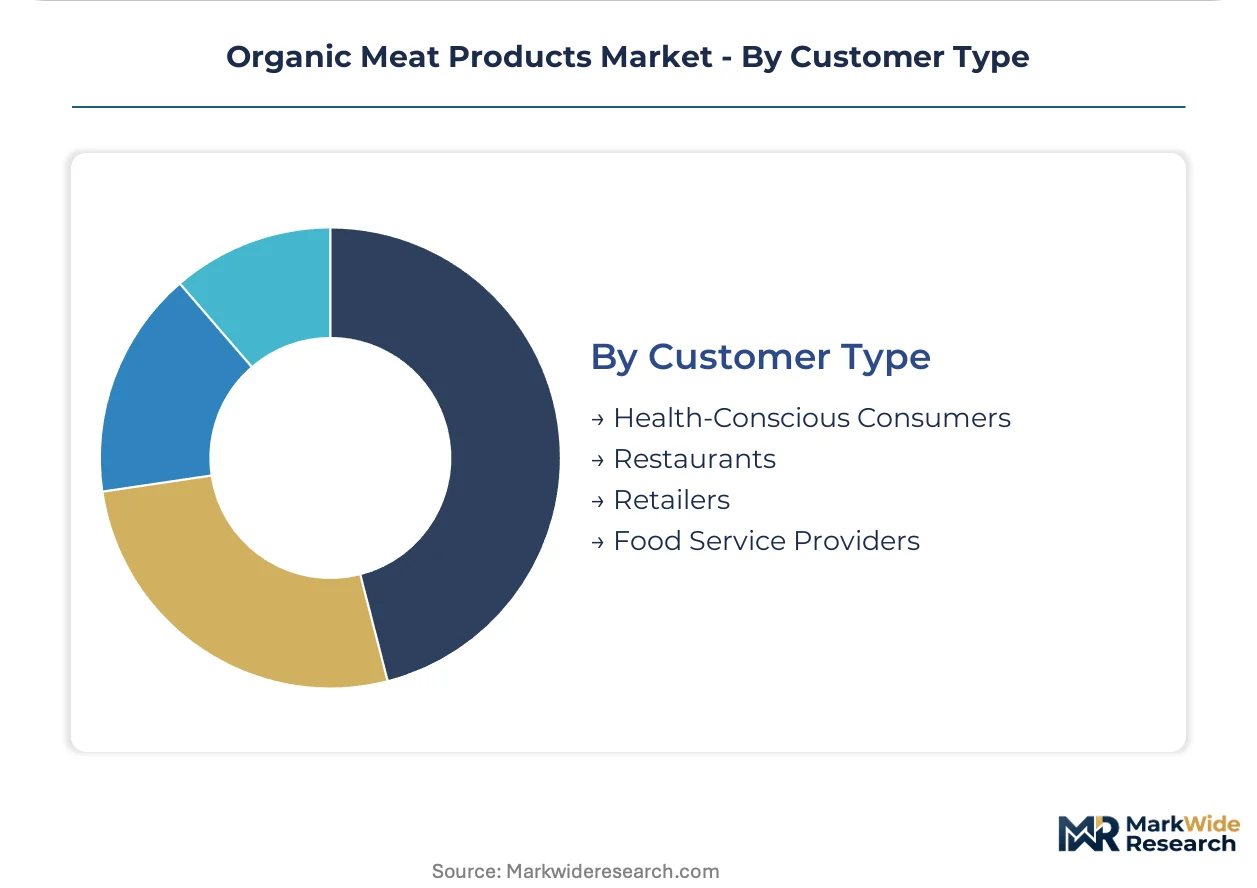
Customer Type:
Application-driven procurement specifications split between residue-sensitive food service and traceability-demanding retail.
- Health-Conscious Consumers:Clean-label verification and hormone-free claims drive premium willingness-to-pay. Subscription channels in France and Germany capture recurring revenue through direct-farm provenance platforms.
- Restaurants:Menu storytelling value and USDA Organic certification requirements concentrate demand in fine-dining and fast-casual segments with transparent sourcing narratives.
- Retailers:Private-label organic meat programs require third-party audit compliance and consistent supply continuity for shelf stability.
- Food Service Providers:Institutional procurement specifications prioritize cost containment within antibiotic-free parameters for school and healthcare contracts.
Health-conscious consumers dominate premium extraction. Restaurants present steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled veterinary practitioners and certified organic livestock managers anchor production capacity across major supply basins. Talent density in pasture management and preventive animal health protocols shapes regional competitive advantage.
United States
Health-conscious consumers in metropolitan corridors accelerate subscription-based organic poultry purchases through direct-farm platforms. USDA National Organic Program updated livestock standards tighten outdoor access mandates, forcing contract reformulations. The Midwest feed grain belt concentrates organic broiler operations near certified feed supply infrastructure.
Germany
Retail discounters and premium butcher chains build dedicated organic meat sections with full blockchain traceability systems. EU Green Deal Farm to Fork Strategy mandates tightened chemical residue limits and animal welfare benchmarks. Bavarian processing clusters integrate vertically with Alpine pasture cooperatives for verified grass-fed beef sourcing.
Australia
Premium grass-fed beef exporters pre-certify slaughter batches against tightened EFSA safety thresholds for European market access. REACH chemical residue protocols extend testing scope to veterinary pharmaceutical metabolites. Queensland and New South Wales rangeland operations scale organic cattle partnerships with South American processors.
Brazil
Grass-fed organic cattle sourcing partnerships expand to serve premium export segments in North America and Europe. The country's national agricultural regulator enforces residue testing alignment with EU import eligibility requirements. Southern pasture regions concentrate organic beef finishing operations near port logistics infrastructure.
France
Urban subscription services capture recurring revenue from health-conscious consumers seeking verified pasture-raised protein with immutable documentation. EFSA safety thresholds shape import procurement specifications for retail chains. Auvergne-Rhône-Alpes clusters link heritage breed poultry operations to Paris metropolitan demand corridors.
Organic Meat Products Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressures intensify as feed cost volatility and certification compliance costs favor scale-advantaged processors. Three archetypes dominate: vertically integrated protein majors with captive organic feed supply, mid-scale regional processors with direct-farm partnerships, and subscription-native digital platforms with blockchain traceability infrastructure. Dominant competitive moves include strategic partnerships for certified pasture access and portfolio diversification into controlled-environment poultry housing.
Among North American protein majors, Tyson Foods Inc., Perdue Farms, and JBS S.A. exemplify divergent strategic postures. Tyson Foods Inc. represents scale-driven vertical integration archetypes with feed supply chain control. Perdue Farms occupies a position emphasizing animal welfare benchmark exceedance through housing technology. JBS S.A. anchors the multinational grass-fed sourcing model with transcontinental cattle partnerships.
| Leading Market Players |
|---|
| Tyson Foods Inc. |
| Perdue Farms |
| JBS S.A. |
| Danish Crown |
| Verde Farms |
| Meyer Natural Foods |
| Organic Prairie |
| Eversfield Organic Ltd. |
| OBE Organic |
| Others |
Cost & Logistics Intelligence
Subscription-based direct-farm buyers in North American metropolitan corridors are compressing traditional supermarket markups and forcing processors toward transparent, certification-anchored pricing models that reward full traceability documentation.
Pricing Analysis
Certification-bundled offerings versus unbundled commodity cuts define the pricing architecture. Three-tier pricing structure across premium grass-fed, standard organic, and economy private-label levels segments buyer willingness-to-pay. Price differentiation rests on USDA Organic versus EU organic certification tier and verified pasture-access documentation. Cost compression in the standard tier is intensifying because organic feed premiums persist above conventional benchmarks. Food service providers exhibit highest price sensitivity, while health-conscious subscription buyers show lowest elasticity.
Supply Chain Analysis
Direct-to-retail channels handle German discounter and North American supermarket volume, while direct-to-consumer platforms serve subscription buyers. Geographic supply concentration centers on the United States, Germany, and Australia for certified organic feed and finished livestock. Raw material dependencies include organic corn, certified soybean meal, and pasture acreage access. Single-source vulnerability in certified organic feed supply creates structural risk for processors without captive grain partnerships. Distribution runs through vertically integrated processor networks and blockchain-enabled direct-farm platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in organic meat rest on controlled-environment housing technologies that compress production cycles while exceeding welfare benchmarks, enabling premium extraction without proportional cost escalation.
For Market Incumbents: Anchor market position through backward integration into certified organic feed supply chains and controlled-environment poultry housing investments. Tyson Foods Inc.'s feed network model offers defensive template against margin compression from volatile grain markets. Certification harmonization investments across USDA Organic and EU Green Deal standards protect cross-border revenue streams from decertification risk. For New Entrants and Emerging Players: The premium-to-economy price gap in grass-fed beef offers entry vector for pasture-verified direct-farm platforms with blockchain documentation. White-space concentrates in North American urban subscription channels and French heritage breed poultry segments. Go-to-market leverage centers on immutable traceability APIs that compress audit cycles for retail chain procurement specifications. For Investors and Strategic Acquirers: Protein majors with captive organic feed infrastructure are the most active acquirer in this space, targeting mid-scale regional processors with established direct-farm partnerships. Long-term viability favors scale-advantaged operators with certification compliance cost absorption capacity. Watch EU Green Deal enforcement timelines as inflection indicator for European market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Feed Supply | Captive corn and soybean sourcing insulates processors from commodity volatility compressing margins. |
| Controlled-Environment Housing Deployment | Perdue Farms' benchmark-exceeding systems secure premium shelf placement in USDA Organic channels. |
| Blockchain-IoT Traceability Platform Launch | German retail discounters adopt real-time pasture verification to satisfy EU Green Deal documentation requirements. |
| Direct-to-Consumer Subscription Channel Entry | Urban meal-kit services in North America capture recurring revenue with weekly organic protein delivery schedules. |
| Cross-Border Certification Harmonization Investment | Dual USDA-EU organic compliance unlocks German and French retail discounter procurement specifications. |
Research Approach
Multiple input streams — processor procurement directors, retail category buyers, feed supply specialists, and veterinary compliance officers — were reconciled against customs trade records, USDA National Organic Program certification databases, and EU Farm to Fork Strategy documentation. Primary fieldwork with controlled-environment housing technology providers and blockchain traceability platform developers informed operational cost structures. Secondary validation drew from SEC filings of protein majors, EFSA safety threshold publications, and organic sector association reports. Bottom-up volume modeling and top-down value triangulation were cross-referenced for convergence.
Historical consumption patterns were cross-referenced against panel input from supply chain stakeholders to construct projection frameworks across the analysis window. Segmentation dimensions modeled include species type, certification tier, packaging technology, and distribution channel configuration. CAGRs were derived from trend extrapolation adjusted for regulatory inflection points. Industry-specific forecast inputs incorporated organic feed price elasticity coefficients and EU Green Deal compliance timeline assumptions.
Caveats apply where feed commodity volatility, veterinary pharmaceutical residue protocol expansions, or National Organic Program standard revisions could materially shift the outlook. Forecasts reflect documented assumptions regarding certification harmonization progress and pasture access mandate enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Canned Beef Market
Meat Products
Saudi Arabia Goat Meat and Cheese Market
Meat Products
United States Frozen Meat Market
Meat Products
Western Europe Ready-To-Eat Meat Market
Meat Products
Middle-East and Africa Animal-Based Meat and Dairy Products Market
Meat Products
Organic Eggs Market
Meat Products
Blended Meat Market
Meat Products
Low Fat Sausage Market
Meat Products
Global Edible Meat Market
Meat Products
Low Fat Beef Market
Meat Products
Bacon Flavors Market
Meat Products
3D Printed Meat Market
Meat Products
Global Poultry Meat Market
Meat Products
India Edible Meat Market
Meat Products
Meat Packaging Market
Meat Products
Bacon Slicers Market