
 Mexico Electric Car Market | 2026-2036
Mexico Electric Car Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Electric Car Market Foresight
Software-defined battery management subscriptions is realigning what automakers monetize beyond the initial vehicle sale. Tesla leverages over-the-air updates to sustain recurring revenue from performance unlocks and range extensions. BYD anchors its Mexico strategy through integrated battery-cell production that controls cost structures. Ford Motor Company competes on fleet-specific telematics packages that differentiate commercial offerings from retail lines.
An electric car is a road vehicle propelled by one or more electric motors drawing energy from rechargeable battery packs, with lithium-ion cells typically delivering energy densities of 150-300 watt-hours per kilogram and operating voltages between 300-800 volts. Its primary commercial purpose is to displace internal combustion engines through zero tailpipe emissions and lower total cost of ownership across duty cycles. SUV configurations currently lead unit sales among vehicle types as Mexican consumers prioritize cabin space and perceived safety. Fast chargers represent the fastest-expanding charging infrastructure category, though home chargers retain the largest installed base and associated margin pool. Solid-state battery technology remains pre-commercial but attracts disproportionate R&D allocation due to its potential to eliminate thermal runaway risks.
Secretaría de Energía (SENER) oversees Mexico's charging infrastructure standards, while NOM-001-SEDE governs electrical installation safety for residential and commercial charging points. The federal EV tax incentive framework reduces acquisition costs and directly shapes demand elasticity among price-sensitive buyer segments. SEMARNAT emissions regulations tighten fleet-average obligations and push manufacturers toward zero-emission vehicle quotas. Stakeholders must monitor whether incoming administrations preserve or modify these incentive structures before committing capital to localized battery assembly.
Market Dynamics
Fleet electrification mandates from ride-sharing operators are compressing payback period calculations for commercial buyers, while NOM-001-SEDE compliance costs reshape residential charging economics. This dual pressure on total cost of ownership is accelerating the displacement of internal combustion vehicles in Mexico's most price-sensitive segments.
Growth Catalysts
- Federal EV Tax Incentive Framework:Acquisition cost reductions directly expand addressable demand among middle-income households in Mexico City and Guadalajara metropolitan zones.
- Lithium-Ion Energy Density Gains:Cell chemistry improvements are extending real-world range without proportional battery weight increases, reducing range anxiety in intercity corridors.
- Bajío Manufacturing Corridor Clustering:Supplier proximity to assembly plants is compressing logistics costs and enabling just-in-sequence battery delivery for localized production.
Market Restraints
- Charging Infrastructure Gaps:Fast charger deployment lags vehicle sales velocity in secondary cities outside the central plateau, creating utilization bottlenecks.
- Lithium Price Volatility:Raw material cost swings transmit directly to pack pricing, undermining OEM margin stability and consumer price predictability.
- Grid Capacity Constraints:SENER distribution network limitations in high-growth zones restrict simultaneous home charging penetration at scale.
Strategic Opportunities
- Yucatán Peninsula Tourism Fleets:Hotel and rental car electrification in Cancún-Mérida corridors remains underpenetrated relative to air quality visibility value.
- Vehicle-to-Grid Integration:Bidirectional charging protocols could monetize idle fleet capacity as distributed storage assets during peak demand windows.
- SEMARNAT Fleet-Average Mandates:Tightening emissions obligations create forced demand pools for zero-emission vehicle credits among legacy manufacturers.
Industry Challenges
- High-Voltage Technician Scarcity:Certified repair capacity for 400-800 volt architectures trails vehicle stock growth, extending service wait times.
- Battery Recycling Infrastructure:End-of-life cell processing capabilities remain undeveloped, creating future liability exposure for first movers.
- Software-Hardware Integration Complexity:Over-the-air update architectures require cybersecurity certifications that extend homologation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Electric Car Market |
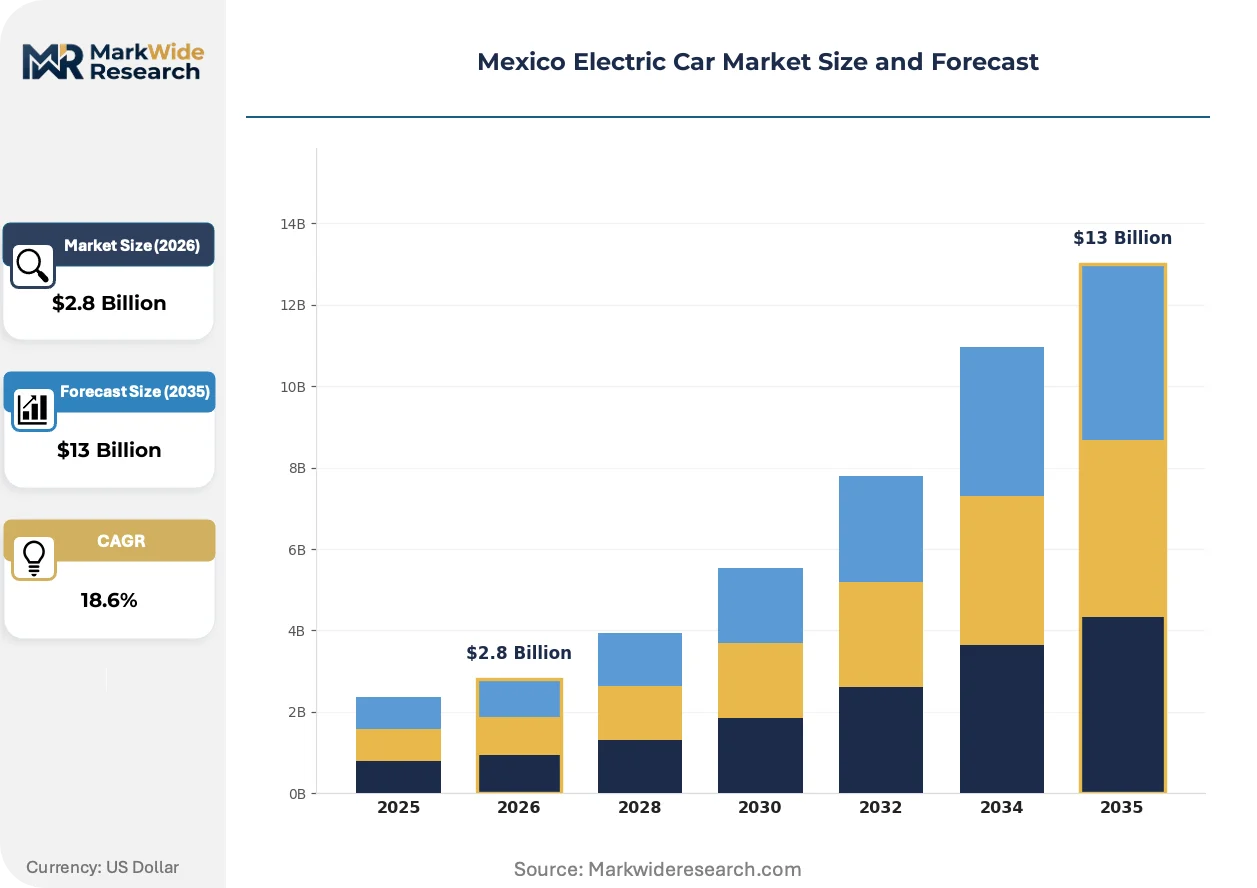
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Pickup Battery Technology: Lithium-ion, Lead-acid, Solid-state, Nickel-metal Hydride Charging Infrastructure: Fast Chargers, Level 2 Chargers, Home Chargers, Public Charging Stations End User: Individual Consumers, Businesses, Government Fleets, Ride-Sharing Services |
| Companies Covered | General Motors Company, Bayerische Motoren Werke AG, BYD, Daimler AG, Geely, Tesla, Toyota Motor Corporation, Kia Corporation, Ford Motor Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Electric Car Market Shifts & Advancements
Battery subscription and software-defined performance models are fragmenting traditional ownership economics. These shifts separate hardware depreciation from feature access, creating recurring revenue architectures that reward data-rich operators over asset-heavy manufacturers.
Solid-state electrolyte research is decentralizing thermal management requirements in next-generation pack designs. Automakers with captive cell development programs are accelerating prototype validation for sulfide-based chemistries. This transition is compressing incumbent liquid-electrolyte supply commitments and forcing tier-one suppliers to dual-source development partnerships.
NOM-001-SEDE amendments are mandating smart load management for residential installations above 7.4 kW. Electrical contractors must now integrate utility-communicating hardware that enables demand-response participation. Commercial charging station operators in Monterrey and Querétaro are absorbing retrofit costs to maintain installation licensing.
Fleet procurement committees are consolidating vehicle decisions under sustainability officers with total cost of ownership mandates. Traditional dealer relationships are ceding influence to direct OEM fleet teams offering telematics-embedded service bundles. This concentration is most visible among Mexico City ride-sharing operators electrifying above fifty-unit thresholds.
Mexico Electric Car Market Segmentation
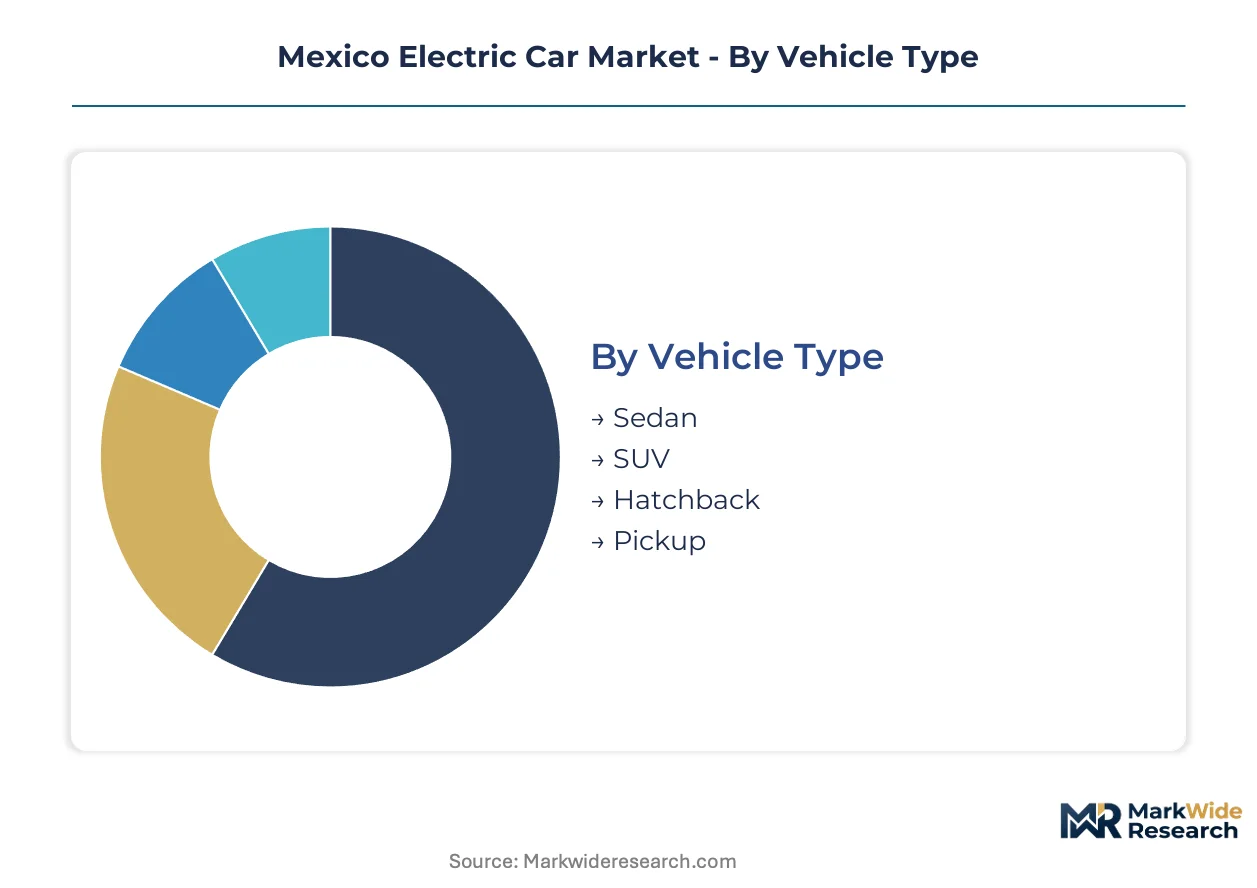
Mexico's electric car segmentation reflects divergent buyer economics across vehicle classes and charging access tiers. Fleet operators prioritize total cost of ownership calculations, while individual consumers respond to cabin configuration and residential charging feasibility.
Vehicle Type:
Buyer decisions in Mexico City and Guadalajara prioritize cabin space and perceived safety ratings over drivetrain efficiency metrics.
- SUV:Elevated seating positions and expanded cargo capacity address family transport needs across uneven urban infrastructure. Demand concentrates in Mexico City metropolitan zones where road quality variability favors higher ground clearance configurations. NOM-001-SEDE residential charging upgrades often accompany SUV purchases due to larger battery capacities.
- Sedan:Lower center of gravity and aerodynamic profiles optimize range efficiency for intercity corridor usage. Bajío manufacturing corridor fleet procurement favors sedan configurations for ride-sharing electrification programs targeting operating cost reduction.
- Hatchback:Compact dimensions suit dense urban parking constraints in Guadalajara and Monterrey central districts.
- Pickup:Commercial fleet applications in construction and logistics sectors drive specialized electrification demand.
SUV leads on scale; sedan leads on momentum among fleet electrification commitments.
Battery Technology:
Cell chemistry selection directly determines pack weight, thermal management requirements, and recycling pathway economics for Mexican assembly operations.
- Lithium-ion:Energy densities of 150-300 watt-hours per kilogram currently dominate pack configurations across all vehicle types. Supplier clustering in the Bajío corridor enables just-in-sequence delivery to localized assembly plants, compressing logistics costs for OEM operations.
- Solid-state:Sulfide-based electrolyte research programs target elimination of thermal runaway risks in next-generation architectures. Pre-commercial status attracts disproportionate R&D allocation from automakers with captive cell development capabilities.
- Lead-acid:Auxiliary power applications and low-speed vehicle segments retain limited deployment.
- Nickel-metal Hydride:Hybrid vehicle architectures continue limited sourcing for transitional powertrain configurations.
Lithium-ion leads on scale; solid-state leads on technology investment intensity.
Charging Infrastructure:
Installation category selection shapes total cost of ownership calculations differently for residential versus commercial buyer segments.
- Home Chargers:Level 1 and Level 2 residential installations retain the largest installed base and associated margin pool across the market. SENER distribution network limitations in high-growth zones restrict simultaneous penetration at scale, creating queuing delays for grid capacity upgrades.
- Fast Chargers:DC rapid charging infrastructure is expanding most quickly along intercity corridors connecting Mexico City to Querétaro and León. Deployment velocity still lags vehicle sales growth in secondary cities outside the central plateau.
- Level 2 Chargers:Workplace and commercial parking installations serve daytime dwell-time charging patterns.
- Public Charging Stations:Destination charging at retail and hospitality locations addresses range anxiety among apartment-dwelling consumers lacking residential installation access.
Home chargers lead on installed base; fast chargers lead on deployment velocity.
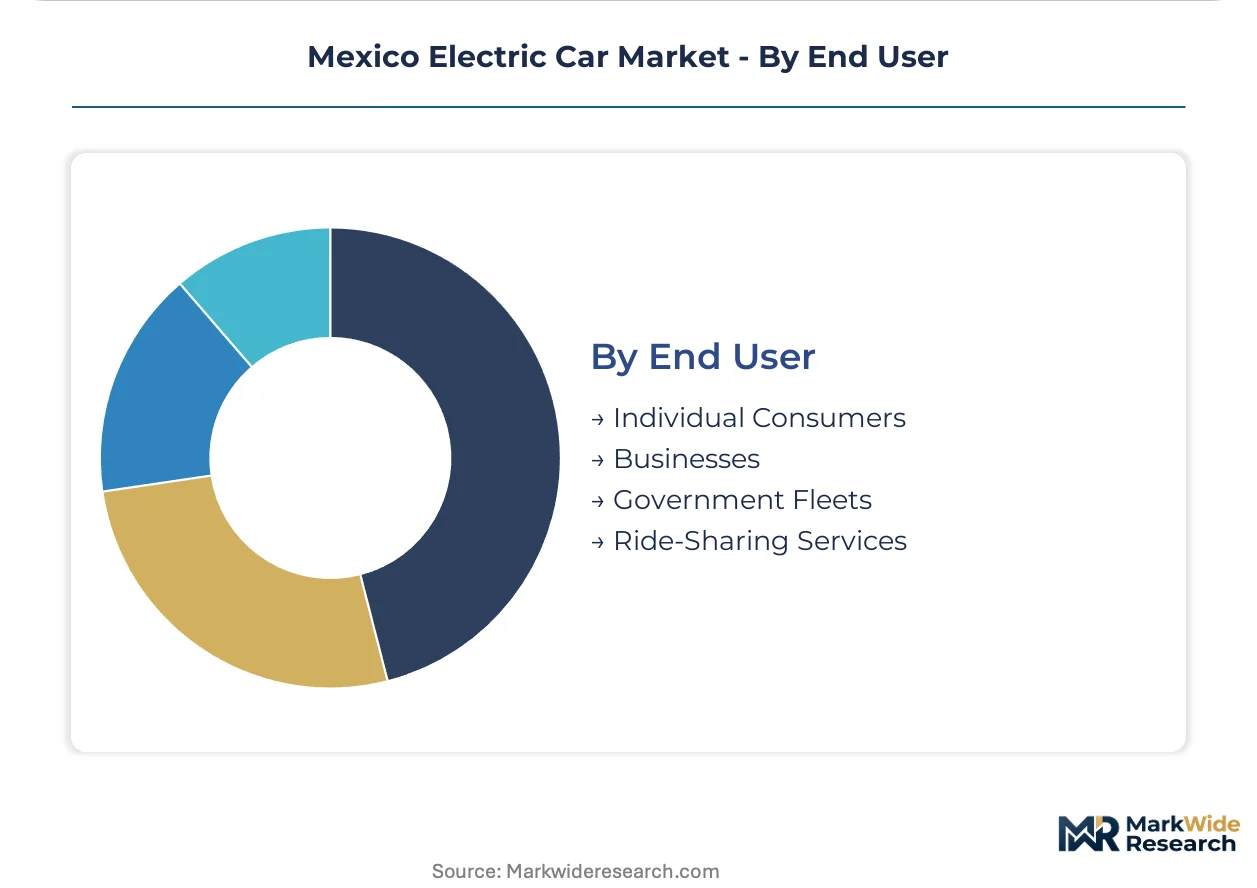
End User:
Procurement authority consolidation under sustainability officers is fragmenting traditional dealer relationships across organizational buyer segments.
- Ride-Sharing Services:Fleet electrification mandates from Mexico City operators compress payback period calculations through high-utilization duty cycles. Direct OEM fleet teams offering telematics-embedded service bundles are displacing traditional dealer channels above fifty-unit procurement thresholds.
- Individual Consumers:Federal EV tax incentive eligibility shapes purchase decisions among middle-income households in metropolitan zones. Range anxiety persists as a constraint for intercity travel patterns beyond central plateau charging coverage.
- Businesses:Corporate fleet electrification targets SEMARNAT emissions compliance and total cost of ownership reduction.
- Government Fleets:Public procurement mandates at federal and state levels create anchored demand pools for domestic assembly sourcing.
Ride-sharing services lead on unit velocity; individual consumers lead on addressable population scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between federal incentive regimes and state-level grid capacity investments are redirecting assembly investments toward sub-regions with streamlined permitting. SENER's distribution network limitations create arbitrage opportunities where localized generation assets accompany manufacturing commitments.
Mexico City Metro
Ride-sharing fleet electrification mandates from Mexico City operators compress payback periods through high-utilization duty cycles. SEMARNAT emissions regulations tighten fleet-average obligations for operators serving the metropolitan zone. Charging infrastructure deployment concentrates along Paseo de la Reforma and Periférico corridors where commercial real estate developers integrate destination charging.
Bajío Region
Supplier clustering near Querétaro and León assembly plants enables just-in-sequence battery delivery for localized production. NOM-001-SEDE amendments mandate smart load management for industrial installations above 7.4 kW. Automotive tier-one suppliers anchor operations in Silao and Irapuato to serve OEM final assembly lines.
Nuevo León
Monterrey-based fleet procurement committees consolidate vehicle decisions under sustainability officers with total cost of ownership mandates. The state's industrial energy tariffs shape operating cost calculations for commercial buyers electrifying above fifty-unit thresholds. Fast charger retrofit costs concentrate along the Monterrey-Saltillo industrial corridor.
Jalisco
Guadalajara metropolitan consumers prioritize cabin space and perceived safety ratings in SUV configurations. Federal EV tax incentive eligibility shapes purchase decisions among middle-income households in Zapopan and Tlajomulco. Residential charging penetration faces SENER distribution network queuing delays in high-growth zones.
Yucatán Peninsula
Hotel and rental car electrification in Cancún-Mérida corridors remains underpenetrated relative to air quality visibility value for tourism-dependent municipalities. Grid capacity constraints restrict simultaneous home charging penetration at scale in coastal development zones. Destination charging at hospitality locations addresses range anxiety among transient vehicle fleets.
Mexico Electric Car Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated battery-cell producers commanding structural advantages in cost structures. The vendor base organizes around three strategic archetypes: captive cell developers controlling upstream chemistry, fleet-focused telematics integrators, and software-defined service architects monetizing recurring revenue. Competitive moves concentrate on backward integration into lithium processing and strategic partnerships for solid-state prototype validation.
Among North American and Asian automakers, General Motors Company, BYD, and Tesla occupy distinct positions within this architecture. General Motors Company exemplifies the legacy OEM archetype navigating fleet-average mandate compliance. BYD anchors the integrated cell production model with captive battery supply chains. Tesla represents the software-defined revenue architect leveraging over-the-air update infrastructures.
| Leading Market Players |
|---|
| General Motors Company |
| Bayerische Motoren Werke AG |
| BYD |
| Daimler AG |
| Geely |
| Tesla |
| Toyota Motor Corporation |
| Kia Corporation |
| Ford Motor Company |
| Others |
Supply & Pricing Matrix
Ride-sharing fleet procurement committees in Mexico City concentrate purchasing power and compress contract structures toward total cost of ownership metrics. This buyer archetype dominance forces pricing models that bundle telematics subscriptions with hardware depreciation schedules across high-utilization duty cycles.
Pricing Analysis
Capacity additions in South Korean and Chinese cell manufacturing are reshaping price floors for lithium-ion packs delivered to Bajío assembly plants. Three-tier pricing structure across premium, standard, and economy levels segments buyers by fleet scale and after-sales service bundling. Cost compression in the economy tier is intensifying because BYD's integrated cell production controls upstream material costs. Ride-sharing operators above fifty-unit thresholds exhibit lowest price sensitivity due to operating cost savings, while individual consumers in Guadalajara metropolitan zones face highest sensitivity to acquisition cost barriers.
Supply Chain Analysis
Lithium carbonate supply rests on Chilean and Australian extraction operations, with Chinese refining capacity processing the majority of battery-grade material. Cathode active materials draw from South Korean precursor specialists and Japanese electrolyte formulators. Single-source vulnerability concentrates in high-purity lithium hydroxide channels where contract durations extend across multi-year offtake agreements. Distribution runs through automotive tier-one suppliers clustered in Silao and Irapuato for just-in-sequence delivery to OEM final assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's electric car market offers margin expansion through software-defined service tiers that separate feature access from hardware depreciation. Battery subscription models and over-the-air performance unlocks create recurring revenue architectures that improve lifetime customer value.
For Market Incumbents: Anchor defensive positioning through captive cell development programs that control lithium-ion cost structures against BYD's integrated model. Secure NOM-001-SEDE certification pipelines for residential charging hardware to maintain installation licensing advantages. Deepen backward integration into cathode active material sourcing to offset raw material volatility transmission to pack pricing. For New Entrants and Emerging Players: Launch via direct fleet sales channels targeting Yucatán Peninsula tourism operators where hotel and rental car electrification remains underpenetrated relative to air quality visibility value. Prioritize vehicle-to-grid integration capabilities that monetize idle fleet capacity as distributed storage assets. Position entry products around SUV configurations where Mexican consumers prioritize cabin space and perceived safety ratings. For Investors and Strategic Acquirers: Integrated battery-cell producers with captive lithium processing are the most active acquirer in this space and command structural valuation premiums. Target acquisition archetypes include solid-state electrolyte research programs with sulfide-based chemistry validation and software-defined vehicle platform specialists. Watch SEMARNAT fleet-average mandate tightening velocity as the inflection indicator for forced demand pool expansion among legacy manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Captive lithium-ion cell sourcing from BYD compresses cost structures for Bajío assembly operations. |
| Software-Defined Vehicle Investment | Over-the-air update architectures enable Tesla-style recurring revenue from performance unlocks and range extensions. |
| Charging Infrastructure Partnership | SENER-compliant fast charger networks along Mexico City-Querétaro corridors reduce fleet range anxiety. |
| Geographic Manufacturing Footprint | Localized battery assembly in the Bajío corridor reduces logistics costs and satisfies government procurement mandates. |
| Platform Standardization | Shared electric architectures across SUV and sedan configurations spread R&D costs across higher production volumes. |
Research Methodology
Direct dialogue with OEM platform engineers, Tier 1 supplier procurement leads, SENER regulatory affairs officers, and Mexico City ride-sharing fleet operators grounded qualitative assessment in operational realities. Secondary validation drew from SEMARNAT emissions filings, SENER distribution network planning documents, vehicle production databases, and federal tax incentive administrative records. Bottom-up channel checks and top-down macroeconomic triangulation converged on segment-level demand estimates.
Bottom-up modeling tracked vehicle class, propulsion architecture, and regional production cluster dimensions across the projection horizon. Top-down constraints incorporated GDP elasticity assumptions and energy price trajectory scenarios. CAGRs derived from fitted growth curves applied to historical registration data and fleet electrification commitment timelines. Lithium price volatility bands and NOM-001-SEDE amendment implementation schedules served as industry-specific forecast sensitivity inputs.
Several conditions sit outside the modeled scope, including incoming federal administration policy shifts on EV tax incentive preservation and unannounced solid-state battery commercialization timelines. Forecasts reflect documented assumptions about charging infrastructure deployment velocity and grid capacity expansion schedules. A small set of named triggers warrants ongoing watch: SEMARNAT mandate stringency adjustments, SENER smart load management enforcement patterns, and lithium carbonate spot price discontinuities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Asia-Pacific Electric Vehicle (EV) Fluids Market
Electric Vehicles
Global Vehicle to Grid Technology Market
Electric Vehicles
Electric Vehicle High-Voltage DC-DC Converter Market
Electric Vehicles
ASEAN Electric Bicycle Market
Electric Vehicles
EV Transmission System Market
Electric Vehicles
Electric Vehicle Battery Cases Market
Electric Vehicles
Electric Water Pump for Electric Vehicles Market
Electric Vehicles
Foldable Electric Car Market
Electric Vehicles
Electric Vehicle Insulation Market
Electric Vehicles
United States Electric Car Market
Electric Vehicles
Hybrid Electric Vehicle Battery Market
Electric Vehicles
Battery Electric Vehicle (BEV) Market
Electric Vehicles
Three Wheel E-Scooter Market
Electric Vehicles
Wireless Electric Vehicle Charging Market
Electric Vehicles
Electric Shuttle Market
Electric Vehicles
E-Bike Battery Pack Market