
 Mexico Digital Twin Market | 2026-2036
Mexico Digital Twin Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Digital Twin Market Insights
Enterprise-grade simulation fidelity is redrawing competitive boundaries in Mexico's digital twin landscape. Siemens leverages its Tecnomatix portfolio to dominate automotive assembly optimization across Bajío plants. PTC sustains its position through ThingWorx integration with existing CAD workflows at Tier 1 suppliers. Ansys specializes in high-fidelity physics modeling for aerospace structural validation near Querétaro.
A digital twin constitutes a virtual replica of physical assets, systems, or processes maintained through real-time sensor telemetry and physics-based simulation engines operating at sub-millisecond synchronization intervals; its primary purpose enables predictive intervention before physical failure occurs. Manufacturing applications anchor current deployment value, with automotive and aerospace lines absorbing the majority of platform licensing. IoT Integration represents the fastest-expanding technology layer, as edge device proliferation across factory floors demands unified data pipelines. Cloud Computing delivery models concentrate margin pools among hyperscale providers, while on-premise legacy installations persist in defense-adjacent facilities.
CRE's interconnection standards and NOM-001-SEDE electrical specifications shape grid-twin data requirements for utility operators. Mexico's national digital strategy and CENACE grid codes mandate telemetry compatibility that filters vendor eligibility for energy infrastructure projects. Stakeholders must weigh sovereign data residency rules against cross-border cloud latency when architecting twin deployments for federally regulated sectors.
Market Dynamics
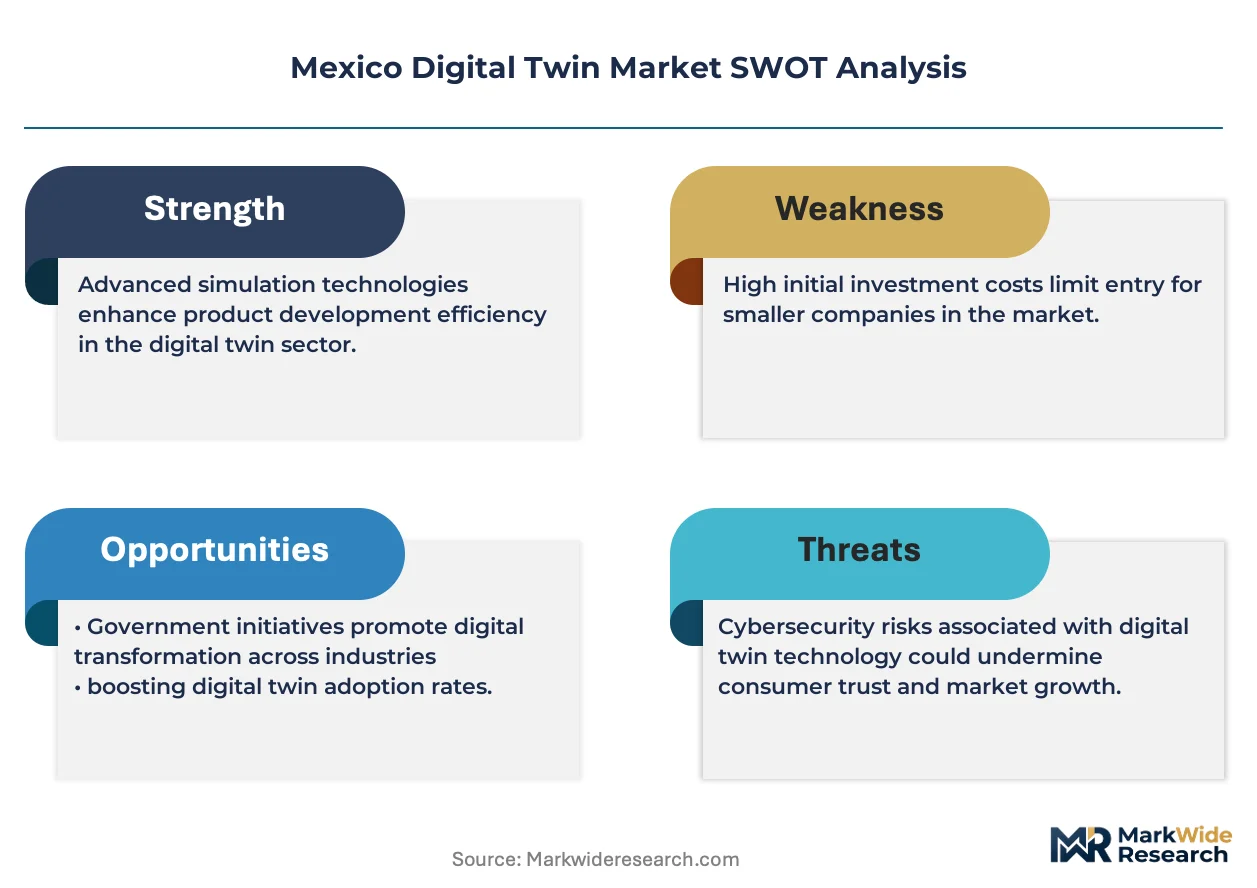
CRE's interconnection standards and CENACE grid codes are compressing vendor qualification timelines for utility-scale digital twin deployments, forcing platform providers to retrofit telemetry architectures for federally mandated data residency.
Growth Catalysts
- NOM Energy Efficiency Standards:CFE's grid modernization mandates compel distribution utilities to deploy asset twins for transformer load balancing and predictive maintenance scheduling.
- Automotive Assembly Telemetry:Bajío-based OEMs are instrumenting welding robots and paint lines with edge sensors feeding real-time physics simulations for quality deviation detection.
- Querétaro Aerospace Cluster:Structural validation requirements for composite airframe manufacturing drive high-fidelity multiphysics modeling adoption among Tier 1 suppliers.
Market Restraints
- Edge Hardware Import Tariffs:Industrial sensor and GPU server duties inflate on-premise twin deployment costs for mid-sized manufacturers.
- Cloud Latency to US Regions:Sovereign data rules blocking cross-border data flows force latency-heavy architectures for real-time simulation synchronization.
- Legacy SCADA Protocol Fragmentation:Proprietary industrial communication stacks resist standard OPC-UA migration, delaying unified data pipeline construction.
Strategic Opportunities
- Monterrey Industrial Hub Expansion:Steel and cement producers in Nuevo León remain underpenetrated for process twin deployments relative to automotive density.
- 5G Private Network Convergence:Telco edge infrastructure partnerships enable sub-10ms synchronization for mobile asset twins in sprawling manufacturing campuses.
- Federal Digital Strategy Incentives:Secretariat of Economy productivity grants subsidize SME pilot programs for manufacturing execution system integration.
Industry Challenges
- Mechatronics Talent Scarcity:Cross-disciplinary engineers capable of bridging physics modeling, sensor integration, and cloud architecture command premium compensation.
- Multi-Vendor Integration Complexity:CAD, IoT platform, and simulation engine interoperability demands custom middleware development extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Digital Twin Market |
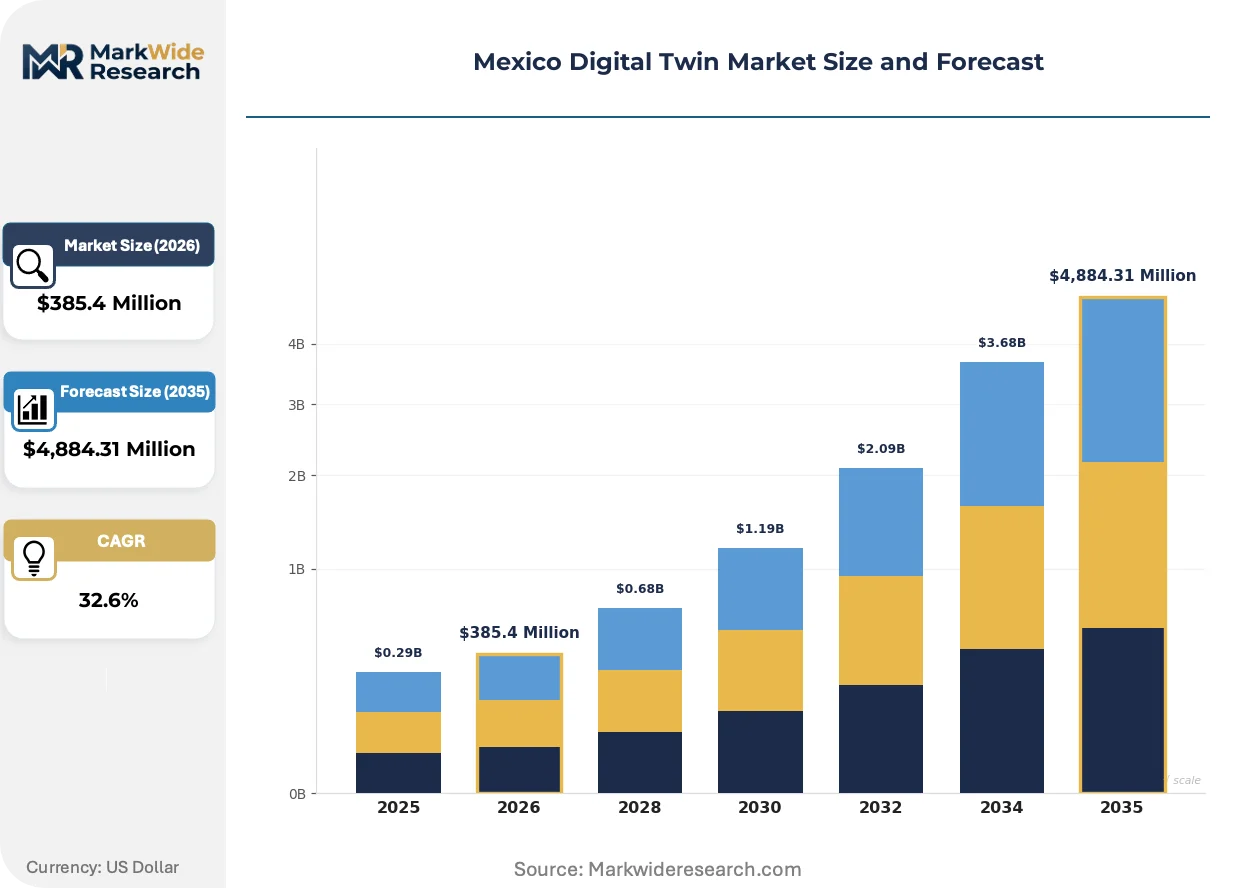
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $4,884.31 Million |
| CAGR (2026 – 2036) | 32.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Manufacturing, Smart Cities, Healthcare, Aerospace Technology: 3D Modeling, Simulation, IoT Integration, Cloud Computing End User: Government, Industrial, Healthcare Providers, Educational Institutions Solution: Real-Time Monitoring, Predictive Maintenance, Asset Management, Performance Optimization |
| Companies Covered | Foxconn, Siemens, GE Vernova, Dassault Systèmes, PTC, IBM, Ansys, AWS, ABB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Digital Twin Market Trends and Innovations
Physics-informed neural networks are compressing simulation runtime from hours to minutes, enabling real-time optimization loops that were computationally prohibitive under traditional finite element approaches.
AI-driven reduced-order modeling is supplanting high-fidelity finite element analysis for operational digital twins. Automotive OEMs in Guanajuato deploy these lightweight surrogates for real-time weld quality prediction. The structural consequence is collapsing hardware requirements for edge deployment, opening twin adoption to smaller Tier 2 suppliers previously priced out by GPU infrastructure costs.
CRE's 2024 interconnection standard revision mandates digital twin submission for grid impact studies on distributed generation projects above 500 kW. Solar and storage developers must model inverter response dynamics under fault conditions before receiving connection approval. The regulation most affects projects in Baja California and Sonora where solar irradiance concentration drives deployment density.
Buyer procurement patterns favor outcome-based service contracts over perpetual software licenses. Manufacturing groups in Tamaulipas and Coahuila negotiate availability guarantees where vendors retain twin infrastructure ownership. This shift concentrates risk with platform providers while accelerating adoption among capital-constrained mid-market manufacturers.
Mexico Digital Twin Market Segmentation
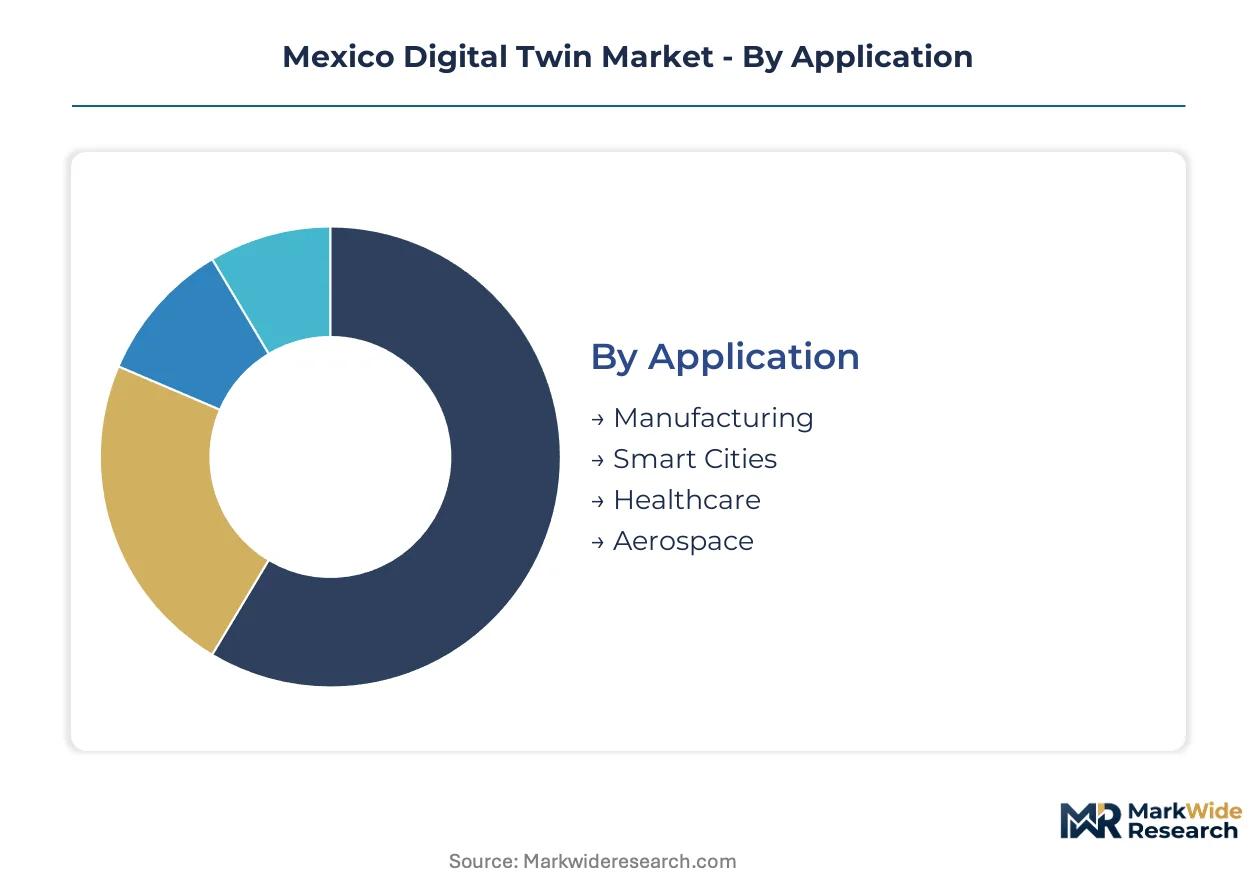
Digital twin deployment patterns in Mexico diverge sharply by application maturity and infrastructure readiness. Channel economics favor integrated platform vendors in automotive-heavy corridors while specialist providers capture aerospace and utility niches requiring regulatory certification.
Application:
Platform licensing flows through systems integrators in manufacturing-dense geographies, while smart city deployments route through federal procurement channels under the national digital strategy.
- Manufacturing:Asset twins synchronize welding robots, paint lines, and assembly fixtures through sub-millisecond telemetry loops. Demand concentrates across Bajío automotive plants and Querétaro aerospace facilities where NOM quality mandates require traceable deviation detection.
- Smart Cities:Urban infrastructure twins model traffic flow, water distribution, and energy consumption at municipal scale. Monterrey and Mexico City pilot programs absorb the majority of government-funded deployments tied to CFE grid modernization timelines.
- Healthcare:Patient-specific organ modeling and hospital facility twins remain nascent, limited by CDMX's concentration of specialized imaging infrastructure and research hospital networks.
- Aerospace:Structural validation twins for composite airframe manufacturing demand high-fidelity multiphysics engines. Querétaro's Tier 1 supplier cluster drives specialized procurement outside general manufacturing channels.
Manufacturing dominates installed base. Smart Cities is where expansion concentrates.
Technology:
Cost tiering separates enterprise-grade physics engines from lightweight SaaS offerings, with mid-market manufacturers gravitating toward subscription-based reduced-order modeling.
- IoT Integration:Edge sensor pipelines and unified data fabrics constitute the fastest-climbing technology layer. Factory floor device proliferation across Guanajuato and Nuevo León demands OPC-UA standardization to overcome legacy SCADA fragmentation.
- Cloud Computing:Hyperscale delivery models aggregate margin pools among providers with sovereign data residency compliance. Latency penalties affect real-time synchronization for twins architected under CRE's cross-border data restrictions.
- Simulation:Physics-based engines execute finite element and computational fluid dynamics at sub-millisecond intervals. On-premise GPU clusters persist in defense-adjacent facilities with air-gapped security requirements.
- 3D Modeling:CAD-native geometry engines maintain geometric fidelity for asset visualization and spatial collision detection. Integration complexity with legacy PLM systems extends deployment timelines for mid-sized suppliers.
Cloud Computing captures the majority of new subscription revenue. IoT Integration faces the steepest talent scarcity constraints.
End User:
Procurement authority and budget scale segment the buyer landscape, with industrial groups negotiating outcome-based contracts while government entities mandate open-data interoperability.
- Industrial:Automotive OEMs and steel producers deploy process twins for availability guarantees and energy optimization. Monterrey's cement and metals cluster remains underpenetrated relative to automotive density in the Bajío.
- Government:CFE distribution utilities and municipal planners mandate telemetry compatibility with CENACE grid codes. Federal productivity grants subsidize SME pilot programs for manufacturing execution system integration.
- Healthcare Providers:Hospital network operators pilot facility twins for HVAC optimization and surgical scheduling. CDMX's private hospital concentration leads regional adoption.
- Educational Institutions:Engineering faculties acquire teaching twins for mechatronics curriculum development. Tecnológico de Monterrey and UNAM anchor demand for academic licensing.
Industrial users dominate current deployment value. Government procurement is where policy-mandated volume expansion concentrates.
Solution:
Application depth separates monitoring-centric offerings from predictive layers requiring historical failure datasets and physics-informed training pipelines.
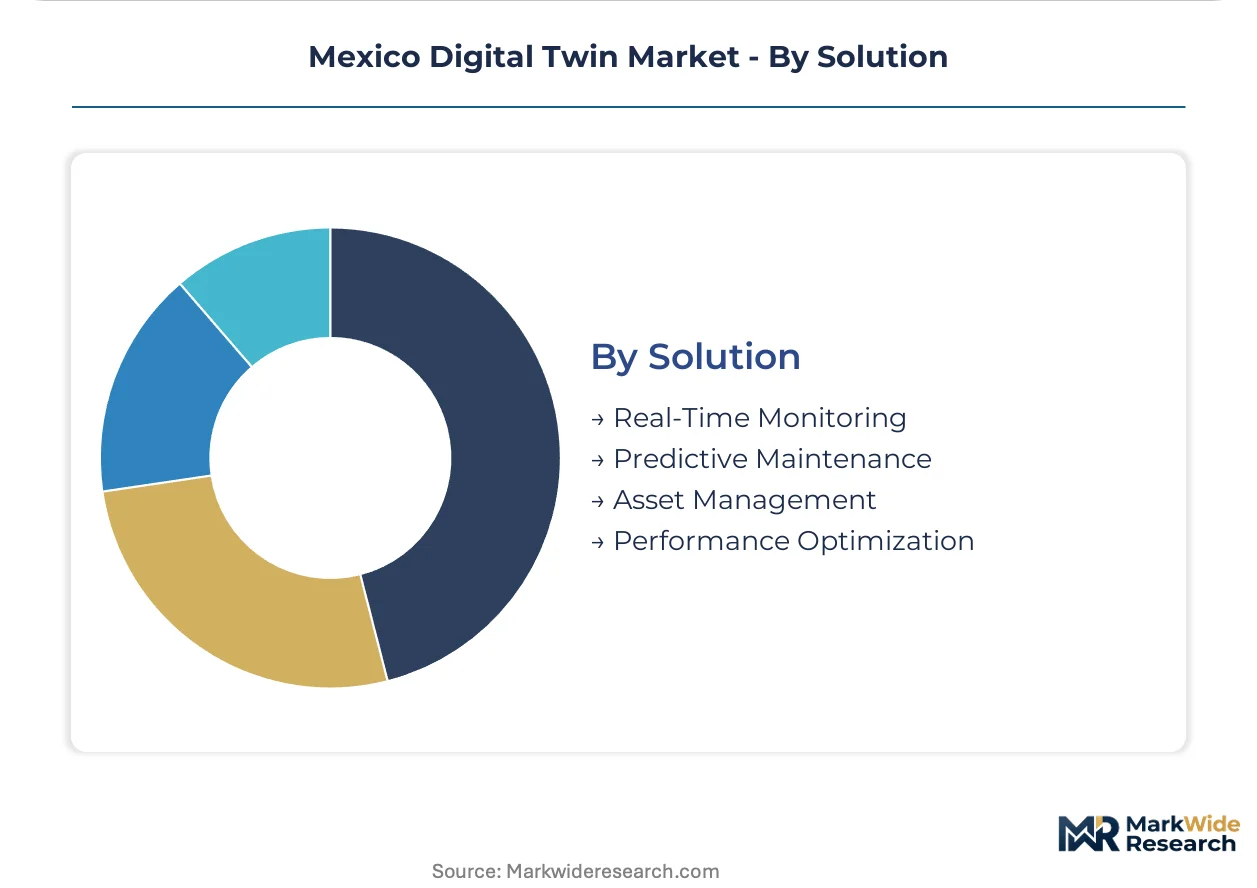
- Predictive Maintenance:Machine learning models trained on vibration, thermal, and electrical signature anomalies forecast bearing failures and transformer overloads. CFE's grid modernization mandates accelerate utility-sector adoption for distribution asset fleets.
- Real-Time Monitoring:Live telemetry dashboards visualize asset state without inference layers. Mid-market manufacturers deploy these as entry-point solutions before graduating to predictive capabilities.
- Asset Management:Lifecycle cost optimization twins track depreciation, maintenance history, and residual value for capital-intensive equipment. Mining and petroleum operators in Coahuila and Tamaulipas drive specialized demand.
- Performance Optimization:Simulation-based tuning of process parameters maximizes throughput and quality yield. Automotive paint line and welding cell optimization absorbs the majority of platform licensing in Guanajuato.
Real-Time Monitoring dominates installed base. Predictive Maintenance is where AI-enabled expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform licensing concentrates in manufacturing corridors where automotive and aerospace clusters drive enterprise-grade deployment density. CFE grid modernization mandates and NOM energy efficiency standards filter vendor eligibility across utility-scale projects. Regional divergence reflects industrial base composition and federal procurement channel access.
Bajío Region
Automotive assembly telemetry and welding robot instrumentation dominate demand across Guanajuato and Querétaro plants. NOM quality mandates require traceable deviation detection for OEM certification. Tier 1 suppliers deploy physics-based simulations for paint line optimization and structural validation workflows.
Nuevo León
Steel and cement producers in Monterrey's industrial hub remain underpenetrated relative to automotive density elsewhere. CENACE grid codes mandate telemetry compatibility for CFE distribution asset twins. Process twin deployments for energy optimization lag behind assembly line sophistication in neighboring states.
Mexico City Metro
Smart city pilots for traffic flow and water distribution modeling absorb federal procurement funding under the national digital strategy. Municipal planners negotiate open-data interoperability requirements with platform vendors. CDMX's hospital networks pilot facility twins for HVAC optimization and surgical scheduling infrastructure.
Northern Border States
Solar and storage developers in Baja California and Sonora face CRE's 2024 interconnection standard revision mandating digital twin submission for grid impact studies. Inverter response dynamics under fault conditions require modeling before connection approval above 500 kW. Cross-border data latency complicates real-time synchronization for twins architected under sovereign data rules.
Jalisco
Guadalajara's electronics manufacturing base drives IoT integration demand for edge sensor pipelines and unified data fabrics. Telco edge infrastructure partnerships enable sub-10ms synchronization for mobile asset twins. Engineering faculties at regional universities anchor academic licensing for mechatronics curriculum development.
Mexico Digital Twin Market Competitive Landscape
Concentration sits with integrated industrial software conglomerates that bundle CAD, simulation, and IoT platforms through direct sales channels. Siemens and Dassault Systèmes leverage manufacturing heritage to dominate automotive assembly optimization. PTC sustains position through ThingWorx integration with existing design workflows. Strategic moves center on outcome-based service contracts and 5G private network partnerships for edge latency reduction.
Among diversified technology conglomerates, Siemens, GE Vernova, and IBM occupy positions spanning industrial automation, energy infrastructure, and enterprise cloud services. These firms exemplify the full-stack archetype that combines physics engines with IoT data pipelines. Specialists in high-fidelity multiphysics modeling include Ansys, which anchors the aerospace-structured validation segment near Querétaro. Cloud-native providers such as AWS represent the hyperscale delivery model aggregating subscription revenue through sovereign data residency compliance.
| Leading Market Players |
|---|
| Foxconn |
| Siemens |
| GE Vernova |
| Dassault Systèmes |
| PTC |
| IBM |
| Ansys |
| AWS |
| ABB |
| Others |
Pricing and Supply Chain Analysis
GPU server capacity utilization at hyperscale cloud regions shapes both supply concentration and price floors for Mexican digital twin deployments. CFE's sovereign data residency mandates force latency-heavy architectures that inflate edge infrastructure costs, compressing margins for mid-market manufacturers while concentrating pricing power among compliant hyperscale providers.
Pricing Analysis
NOM-001-SEDE electrical specifications dictate the pricing tier structure for utility-sector digital twin platforms, separating certified grid-twin vendors from uncertified entrants. Three-tier pricing structure across premium physics engines, standard SaaS subscriptions, and economy monitoring dashboards prevails, with differentiation driven by OPC-UA certification level and CENACE telemetry compliance. Pricing pressure stems from edge hardware import tariffs inflating on-premise deployment costs. Mid-sized Tier 2 suppliers exhibit highest price sensitivity, while CFE distribution utilities absorb premium tiers through federal modernization budgets.
Supply Chain Analysis
Just-in-time sensor procurement dominates automotive assembly line deployments, though strategic GPU stockpiling persists among defense-adjacent facilities with air-gapped security requirements. Supply concentrates in the United States, Germany, and Taiwan for industrial edge devices and simulation hardware. Raw material dependencies span silicon wafers, rare earth magnets for servo motors, and specialized composite materials for aerospace validation twins. Single-source vulnerability runs through Taiwan-based GPU foundry concentration. Distribution runs through systems integrators in Bajío manufacturing corridors and direct federal procurement channels for CFE utility projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Outcome-based service contracts represent the fastest-expanding revenue layer, outpacing perpetual software licensing as manufacturing groups negotiate availability guarantees where vendors retain twin infrastructure ownership.
For Market Incumbents: Consolidate through exclusive 5G private network partnerships with Telcel and AT&T Mexico to lock in sub-10ms synchronization capabilities for sprawling manufacturing campuses. Acquire specialist physics-informed neural network startups to compress simulation runtime and defend against cloud-native entrants offering reduced-order modeling at lower price points. Reinforce CENACE certification moats before CRE's next interconnection standard revision. For New Entrants and Emerging Players: Differentiate on sovereign data residency compliance for federally regulated sectors, targeting CFE distribution utilities and defense-adjacent facilities with air-gapped deployment capabilities. Monterrey's steel and cement cluster offers the most penetrable geography, with process twin adoption lagging automotive density by multiple years. Pursue pilot-to-scale contracting anchored by Secretariat of Economy productivity grant eligibility. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors physics-informed AI specialists with proven CENACE compliance and established relationships with Querétaro aerospace Tier 1 suppliers. Long-term viability hinges on migration from perpetual licenses to recurring service revenue with customer retention above renewal thresholds. Watch CRE interconnection standard enforcement intensity as the inflection signal for utility-sector deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| 5G Private Network Partnership | Telcel edge infrastructure enables sub-10ms synchronization for mobile asset twins across Bajío campuses. |
| Physics-Informed AI Acquisition | Neural network startups compress simulation runtime from hours to minutes for real-time optimization loops. |
| CENACE Certification Investment | Grid code compliance filters vendor eligibility for CFE distribution modernization mandates. |
| Outcome-Based Service Transition | Availability guarantees concentrate risk with vendors while accelerating capital-constrained mid-market adoption. |
| Sovereign Data Residency Architecture | CRE cross-border restrictions force compliant cloud deployments for federally regulated energy infrastructure. |
Research Methodology
A spread of perspectives from plant engineers at Bajío automotive OEMs, CFE distribution planning officers, aerospace structural validation leads in Querétaro, systems integration specialists, and hyperscale cloud account executives converged on the working assumptions. Primary fieldwork combined with secondary validation from CENACE grid code filings, CRE interconnection standards, Secretariat of Economy productivity grant disclosures, and customs records for industrial sensor imports. Bottom-up deployment counts triangulated against top-down platform licensing revenue estimates.
Segmentation dimensions modeled span application type, technology layer, end-user procurement authority, and solution depth across the projection horizon. CAGRs derived from fitted growth curves adjusted for NOM energy efficiency standard enforcement timelines and CFE grid modernization budget allocations. Physics-informed neural network adoption rates and 5G private network deployment velocity served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained CENACE certification compliance or CRE data residency rule stability would require recalibration. Forecasts reflect assumptions regarding edge sensor cost trajectories and mechatronics talent pipeline expansion. Revision becomes warranted when GPU import tariff exposure or cross-border cloud latency constraints cross operational viability thresholds for real-time synchronization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Demand Side Platforms (DSP) for Programmatic Advertising Market
Digital Solutions
Global Data Catalog Market
Digital Solutions
Digital Certificates Market
Digital Solutions
Commercial P2P CDN Market
Digital Solutions
Global Cloud Monitoring Tools Market
Digital Solutions
File Sharing Market
Digital Solutions
UX Services Market
Digital Solutions
Global Data Collection and Labeling Market
Digital Solutions
Video Management System Market
Digital Solutions
Life Science Multichannel Campaign Management Market
Digital Solutions
Europe Data Virtualization Market
Digital Solutions
Government Open Data Management Platform Market
Digital Solutions
Cloud E-Signature Tools Market
Digital Solutions
Boat Navigation Software Market
Digital Solutions
Policy Orchestration Market
Digital Solutions
APAC Smart Office Market