
 Digital Twin in Construction Market | 2026-2036
Digital Twin in Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Twin in Construction Market Outlook
The EU Energy Performance of Buildings Directive is broadening the addressable market for construction digital twins across member states. Bentley Systems leverages deep infrastructure modeling heritage to anchor European rail and airport projects. Autodesk competes through dominant position in architectural design-to-fabrication workflows. Siemens Digital Industries Software extends its industrial software stack into building operations, creating captive demand from manufacturing facility clients.
A digital twin in construction constitutes a dynamic virtual replica of a physical building or infrastructure asset, integrating real-time sensor feeds, 3D geometric models, and performance simulation engines to enable predictive maintenance and operational optimization. The technology fuses IoT data streams with building information modeling outputs to mirror structural behavior, energy flows, and occupancy patterns across an asset's lifecycle. Cloud-based deployment now captures the fastest expansion trajectory as engineering consultancies and construction companies shed capital-intensive on-premise infrastructure. Among applications, facility management commands the deepest incumbent spend while safety management represents the emerging margin pool where insurers and liability-conscious developers concentrate new investment. End-user demand skews toward construction companies with multi-project portfolios that require standardized progress tracking across dispersed sites.
Regulatory pressure from the EU Green Deal and national building codes administered by Germany's KBA-adjacent energy agencies is mandating operational carbon disclosure, directly stimulating digital twin adoption for continuous performance verification. The US EPA and OSHA frameworks increasingly reference predictive hazard modeling, creating compliance-driven procurement specifications that favor simulation-capable platforms. Stakeholders must monitor how evolving CE marking requirements for construction product digital passports reshape data architecture standards and interoperability obligations.
Market Dynamics
The EU Energy Performance of Buildings Directive is forcing asset owners to deploy continuous performance verification systems, converting compliance expenditure into operational technology budgets across commercial portfolios.
Growth Catalysts
- EU Green Deal carbon disclosure mandates:Operational reporting requirements under the directive are expanding addressable market for simulation-capable platforms across member states.
- Singapore smart city infrastructure:National urban digitization programs are accelerating platform deployment in public housing and municipal asset management.
- IoT sensor cost compression:Hardware economics are enabling dense environmental monitoring networks that feed real-time data into twin architectures.
Market Restraints
- Cloud infrastructure concentration:Dependence on hyperscale providers creates single-point vulnerability for mission-critical building operations data.
- Interoperability friction from CE marking evolution:Construction product digital passport requirements are generating compliance timeline uncertainty.
- Specialized systems integration talent scarcity:Shortage of engineers capable of bridging BIM, IoT, and simulation domains limits deployment velocity.
Strategic Opportunities
- India industrial corridor buildout:Greenfield manufacturing facility construction is creating demand for integrated asset lifecycle management without legacy system burden.
- Predictive hazard modeling for insurers:Liability-conscious underwriters are mandating simulation-capable platforms for construction risk pricing.
- Edge computing convergence with 5G:Low-latency processing architectures are enabling real-time structural health monitoring for critical infrastructure.
Industry Challenges
- Data architecture standardization delays:Fragmented industry consortium efforts are prolonging interoperability gaps between competing platform ecosystems.
- Capex intensity of sensor network deployment:Dense instrumentation requirements for meaningful twin fidelity demand substantial upfront hardware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Twin in Construction Market |
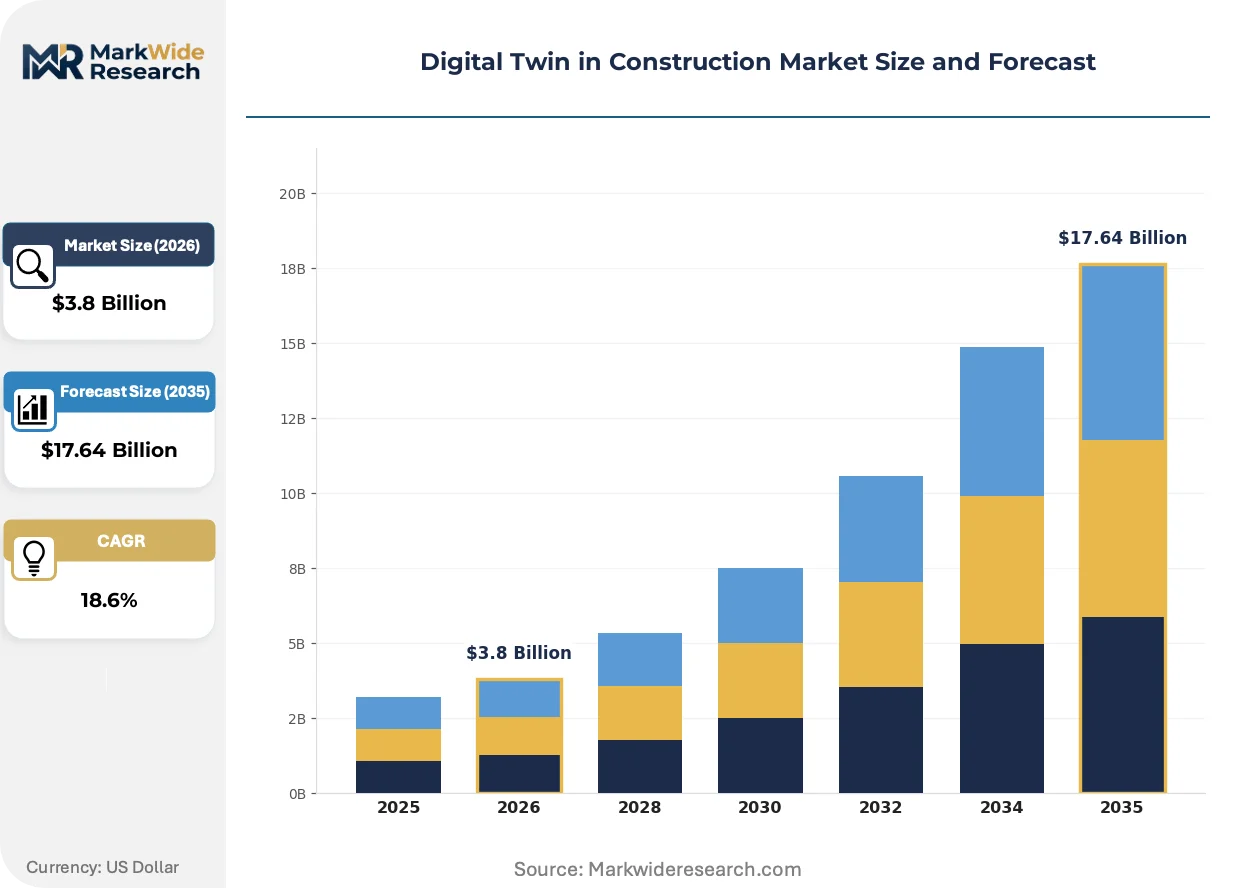
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: 3D Modeling, Simulation, Augmented Reality, Virtual Reality Application: Facility Management, Project Planning, Safety Management, Asset Management End User: Architecture Firms, Construction Companies, Real Estate Developers, Engineering Consultants Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Platforms |
| Companies Covered | Procore, Microsoft Azure Digital Twins, Bentley Systems, Dassault Systèmes, Trimble, Autodesk, PTC ThingWorx, IBM Digital Twin Exchange, Siemens Digital Industries Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Twin in Construction Market Strategic Shifts
Generative design algorithms are compressing engineering cycles while regulatory frameworks harden data architecture requirements. Three developments are restructuring competitive advantage.
AI-powered generative design is rewriting how engineering consultancies approach schematic development. Mid-sized firms in Germany's industrial construction corridor are adopting these tools fastest. The technology is compressing concept-to-bid timelines from months to weeks.
The EU AI Act's risk classification framework is reshaping procurement specifications for automated building control systems. High-risk system designations are triggering human-in-the-loop requirements for critical infrastructure applications. Airport and rail project sponsors are rewriting tender documents to address algorithmic accountability.
Performance-based service contracts are displacing traditional software licensing in facility management procurement. Building owners in Singapore's public housing sector are piloting outcome-linked payment structures. The shift transfers operational risk from asset operators to technology vendors.
Digital Twin in Construction Market Segmentation
Construction digital twins fragment across four technical and commercial dimensions that determine vendor positioning and procurement patterns. Technology choices dictate integration complexity while deployment models reshape capital allocation between asset owners and technology suppliers.
Technology:
Supply concentration in 3D modeling engines anchors platform economics, with specialized simulation vendors capturing premium pricing for physics-based performance prediction.
- 3D Modeling:Geometric fidelity engines form the visual backbone of twin architectures, integrating BIM outputs with real-time mesh updates. Demand clusters in Germany's industrial construction corridor where Siemens and automotive facility builders mandate LOD 400+ standards for fabrication-ready deliverables.
- Simulation:Physics engines model structural behavior, energy flows, and occupancy dynamics across operational lifecycles. Singapore's smart city infrastructure programs are accelerating procurement of thermal and airflow simulation capabilities for public housing estates.
- Augmented Reality:Field overlay systems project twin data onto physical construction sites for progress verification and defect detection.
- Virtual Reality:Immersive walkthrough environments enable stakeholder review of design alternatives before physical commitment.
Today's leader: 3D Modeling. Tomorrow's challenger: Simulation.
Application:
Facility management commands incumbent technology spend while safety management attracts emerging investment from liability-conscious underwriters.
- Facility Management:Operational optimization platforms integrate HVAC, lighting, and security systems through unified control interfaces. Building owners in Singapore's public housing sector are piloting outcome-linked service contracts that transfer operational risk to technology vendors.
- Safety Management:Predictive hazard modeling platforms analyze worker proximity to heavy equipment and structural instability zones. US OSHA framework references to predictive modeling are creating compliance-driven procurement specifications that favor simulation-capable platforms.
- Project Planning:Schedule and resource optimization tools link 4D construction sequencing with cost forecasting.
- Asset Management:Lifecycle tracking systems monitor degradation patterns and maintenance histories for portfolio-level capital planning.
Facility management holds revenue concentration. Safety management is gaining share fastest.
End User:
Construction companies with multi-project portfolios drive standardization requirements while engineering consultancies shape technical specifications.
- Construction Companies:General contractors and specialty trades deploy twins for progress tracking across dispersed sites. EU Energy Performance of Buildings Directive mandates are converting compliance expenditure into operational technology budgets for commercial portfolio operators.
- Engineering Consultants:Design firms leverage generative algorithms to compress concept-to-bid timelines from months to weeks in Germany's industrial corridor.
- Architecture Firms:Design practices use twins for client visualization and design-option comparison.
- Real Estate Developers:Asset owners deploy twins for pre-leasing visualization and operational handover preparation.
Construction companies anchor volume. Engineering consultancies capture margin.
Deployment:
Cloud infrastructure economics are displacing capital-intensive on-premise installations, though hybrid architectures persist for sensitive operational data.
- Cloud-Based:Scalable compute resources eliminate upfront server investment and enable remote collaboration across project teams. Engineering consultancies are shedding on-premise infrastructure fastest as subscription models align costs with project revenue cycles.
- Hybrid:Split architectures process sensitive operational data locally while leveraging cloud resources for simulation and visualization. Critical infrastructure operators in airport and rail projects favor this model for cybersecurity risk mitigation.
- On-Premise:Dedicated hardware installations persist in defense and classified facility construction.
- Mobile Platforms:Field-accessible interfaces extend twin functionality to construction supervisors through tablet and smartphone applications.
Cloud-based deployment is climbing the fastest. Hybrid architectures defend position in critical infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Digital twin technology for construction emerged from German industrial automation heritage before scaling through Singapore's smart city programs and US software ecosystems. Regional deployment patterns now reflect distinct regulatory environments and infrastructure investment cycles. Construction firms adapt platform architectures to local building codes, energy disclosure mandates, and public procurement standards.
Germany
Industrial facility builders in Bavaria and North Rhine-Westphalia drive demand for fabrication-ready digital twins with LOD 400+ geometric standards. The EU Energy Performance of Buildings Directive and national KBA-adjacent energy agency codes mandate operational carbon disclosure, converting compliance budgets into simulation platform procurement. Stuttgart's automotive construction corridor anchors reference architectures for integrated asset lifecycle management.
Singapore
Public housing estates and municipal asset management programs accelerate cloud-based twin deployment across dense urban portfolios. The national smart city infrastructure initiative funds thermal and airflow simulation capabilities for tropical climate optimization. Jurong Lake District and Punggol Digital District serve as testbeds for outcome-linked service contracts that transfer operational risk to technology vendors.
United States
Multi-project construction portfolios in Texas and California require standardized progress tracking across dispersed commercial and industrial sites. OSHA framework references to predictive hazard modeling create compliance-driven procurement specifications favoring simulation-capable platforms. The EPA's evolving building performance disclosure requirements stimulate adoption for continuous verification in federal and institutional construction.
India
Greenfield manufacturing facility construction in Gujarat and Maharashtra creates demand for integrated asset lifecycle management without legacy system burden. The country's national industrial corridor programs embed digital twin specifications into tender documents for new industrial townships. Delhi-Mumbai Industrial Corridor project sponsors specify real-time sensor integration for predictive maintenance from commissioning.
United Arab Emirates
Mega-project developers in Dubai and Abu Dhabi deploy immersive visualization twins for stakeholder engagement and pre-leasing of commercial and residential assets. The country's national building codes and sustainability certification programs increasingly reference operational performance verification. Mohammed bin Rashid Al Maktoum Solar Park and Expo City Dubai infrastructure establish reference implementations for desert climate optimization.
Digital Twin in Construction Market Competitive Environment
Capital-heavy infrastructure software producers compete with asset-light platform designers for construction digital twin market position. The vendor base consolidates around three tiers: diversified industrial software conglomerates with captive manufacturing demand, specialized BIM-to-operations platform vendors, and cloud-native challengers attacking mid-market construction workflows. Strategic archetypes include full-stack lifecycle managers, point-solution simulation specialists, and hyperscale cloud platforms leveraging infrastructure-as-a-service economics. Dominant competitive moves encompass vertical capability acquisitions and strategic partnerships bridging design-to-fabrication workflows.
Among diversified industrial software providers, Siemens Digital Industries Software and Bentley Systems exemplify full-stack lifecycle management archetypes. Autodesk occupies a position anchoring architectural design-to-fabrication workflows. These three entities represent distinct strategic postures: manufacturing facility captive demand exploitation, deep infrastructure modeling heritage, and dominant design software ecosystem leverage respectively.
| Leading Market Players |
|---|
| Procore |
| Microsoft Azure Digital Twins |
| Bentley Systems |
| Dassault Systèmes |
| Trimble |
| Autodesk |
| PTC ThingWorx |
| IBM Digital Twin Exchange |
| Siemens Digital Industries Software |
| Others |
Value Chain & Pricing Dynamics
EU Energy Performance of Buildings Directive mandates for operational carbon disclosure are converting compliance budgets into operational technology procurement, forcing platform vendors to absorb sensor hardware costs upfront while recovering through long-term service contracts. This shift compresses initial license pricing while extending revenue recognition timelines across multi-year facility management agreements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the construction digital twin market, with differentiation anchored in geometric fidelity standards and simulation physics depth. Premium tiers command valuation premiums for LOD 400+ BIM integration and real-time sensor fusion, while economy offerings compete on basic 3D visualization without predictive capabilities. Pricing pressure stems from cloud infrastructure cost compression and open-source simulation engine proliferation, particularly affecting mid-market engineering consultancies. Construction companies with dispersed multi-project portfolios exhibit highest price sensitivity, whereas critical infrastructure operators in airport and rail segments prioritize capability over cost.
Supply Chain Analysis
Regional distribution centers in Germany, Singapore, and the United States anchor hub-and-spoke delivery patterns for digital twin platform deployment, with localization requirements driving in-country cloud infrastructure partnerships. Hardware supply concentrates in China for IoT sensors, Taiwan for edge computing components, and Germany for industrial automation controllers. Raw material dependencies span lithium for battery-backed sensors, rare earth elements for precision positioning hardware, and specialized silicon for thermal simulation processors. Single-source vulnerability in hyperscale cloud infrastructure creates concentration risk for mission-critical building operations data. Distribution runs through systems integration partners who bundle platform licenses with implementation services and ongoing facility management support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The construction digital twin market represents a late-cycle quality story where EU Green Deal carbon disclosure mandates and Singapore smart city specifications are elevating procurement criteria toward simulation-capable, compliance-ready platforms.
For Market Incumbents: Anticipate margin compression from cloud-native challengers by deepening captive demand through backward integration into sensor hardware and edge computing infrastructure. Prioritize certification investment for EU AI Act high-risk system compliance to defend position in airport and rail project tenders against emerging platform vendors. For New Entrants and Emerging Players: Begin with safety management applications for liability-conscious insurers in the United States, where OSHA predictive modeling references create compliance-driven procurement specifications with lower incumbent lock-in. Target India's greenfield industrial corridor buildout with lightweight cloud-native architectures that bypass legacy system integration burdens facing established vendors. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized simulation vendors possessing physics-based performance prediction engines and existing relationships with German automotive facility builders. Long-term viability hinges on regulatory tailwinds from operational carbon disclosure mandates across the analysis window. Watch for CE marking digital passport standardization as the inflection signal determining platform interoperability winners.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies BIM, IoT, and simulation engines to meet EU Energy Performance of Buildings Directive verification requirements. |
| Acquisition of Specialist Firm | Captures physics-based thermal and airflow simulation capabilities demanded by Singapore public housing programs. |
| Strategic Partnership | Links design-to-fabrication workflows for LOD 400+ standards in Germany's automotive construction corridor. |
| Geographic Expansion | Establishes local cloud infrastructure to serve India industrial corridor projects without legacy integration burden. |
| Product Launch | Introduces predictive hazard modeling platforms aligned with US OSHA framework compliance specifications. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with construction company technology officers, engineering consultancy BIM directors, facility management procurement leads, and smart city program administrators with secondary validation against EU regulatory filings, Singapore Land Authority tender documents, US EPA building performance disclosures, and hyperscaler cloud infrastructure investment reports. Bottom-up project pipeline analysis and top-down construction spend allocation models were triangulated to anchor volume estimates.
Segment-weighting approaches distributed value across technology tiers, application categories, end-user archetypes, and deployment models throughout the forecast period. CAGR derivation rested on regulatory mandate implementation timelines, sensor cost compression curves, and cloud adoption elasticity in engineering consultancy segments. Industry-specific inputs incorporated EU Green Deal carbon disclosure phase-in schedules and Singapore smart city infrastructure procurement cycles.
Several conditions sit outside the modeled scope, including potential CE marking digital passport standardization delays, hyperscale cloud provider service disruptions, and geopolitical restrictions on cross-border building operations data flows. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Business Transcription Market
Digital Solutions
Thin Client Market
Digital Solutions
Database Management Platform Market
Digital Solutions
Media Asset Management (MAM) Solutions Market
Digital Solutions
Global Corporate Volunteering Platform Market
Digital Solutions
Middle East and Africa Digital Signage Market
Digital Solutions
India Engineering Research and Development (ER&D) Services Market
Digital Solutions
Qatar ICT Market
Digital Solutions
Content Moderation Services Market
Digital Solutions
Asia Pacific Smart Card Market
Digital Solutions
Digital Commerce Software Market
Digital Solutions
Landing Page Builders Market
Digital Solutions
Account Based Marketing Market
Digital Solutions
Global Product Lifecycle Management Market
Digital Solutions
Docker Monitoring Market
Digital Solutions
GCC and Africa ICT Market