
 Methyl Isobutyl Ketone (MIBK) Market | 2026-2036
Methyl Isobutyl Ketone (MIBK) Market Size, Share, and Industry Trends Forecast 2026-2036
Methyl Isobutyl Ketone (MIBK) Market Analysis
Modular solvent bundling is rebalancing procurement patterns across downstream coating operations. Arkema Group leverages captive acetone feedstock to sustain margin stability in European supply. Sasol anchors its position through Fischer-Tropsch-derived material streams in South African production. Dow Chemical Company competes on Gulf Coast petrochemical integration scale.
Methyl isobutyl ketone is a six-carbon aliphatic ketone produced via acetone condensation over acidic catalysts, serving primarily as a medium-evaporation solvent and extraction agent in industrial formulations. The solvents segment dominates volume flows through paint and lacquer thinning applications where balanced solvency power proves critical. Specialty chemicals applications are expanding fastest as pharmaceutical extraction protocols demand higher-purity grades with controlled moisture specifications.
EPA volatile organic compound rules and REACH substance restrictions jointly constrain formulation flexibility across North American and European supply chains. OSHA permissible exposure limits shape workplace handling requirements and drive investment in closed-system transfer equipment. Buyers must monitor regulatory divergence between jurisdictions as carbon border adjustments begin affecting solvent trade economics.
Market Dynamics
Acetone feedstock volatility and tightening VOC regulations across automotive coating supply chains are forcing reformulation investments and procurement restructuring among downstream solvent buyers.
Growth Catalysts
- REACH substance restrictions:European compliance mandates are filtering out non-compliant producers and consolidating demand among certified suppliers with verified supply chain documentation.
- Pharmaceutical extraction protocols:Higher-purity MIBK grades with controlled moisture specifications are gaining traction in active pharmaceutical ingredient isolation processes.
- Industrial coatings expansion in South Asia:Solvent-grade material absorption is accelerating across manufacturing clusters in India and surrounding production hubs.
Market Restraints
- Acetone price volatility:Crude acetone cost swings transmit directly into MIBK margin compression, squeezing non-integrated producers without captive feedstock.
- EPA VOC rule stringency:Formulation flexibility constraints in North American markets limit solvent blending options for coating manufacturers serving regulated jurisdictions.
- Waterborne coating substitution:Low-VOC aqueous systems are capturing share in architectural and some industrial coating segments where performance specifications permit.
Strategic Opportunities
- Specialty chemicals grade expansion:Pharmaceutical and agrochemical extraction applications offer premium pricing for ultra-high-purity material with batch-traceable certification.
- Carbon border adjustment positioning:EU CBAM implementation creates first-mover advantage for producers with verified low-carbon process credentials and documented Scope 3 emissions.
- Closed-system transfer equipment:OSHA PEL compliance investments open aftermarket service and equipment bundling opportunities around workplace exposure management.
Industry Challenges
- Process safety engineering talent:Specialized expertise in ketone handling, distillation hazard analysis, and reactive chemical management remains scarce across production facilities.
- Multi-jurisdictional certification timelines:Divergent purity specifications between EPA, REACH, and GB standards force parallel qualification runs and extended product registration cycles.
- Legacy storage infrastructure retrofit:Existing tank farms and transfer lines require corrosion-resistant lining upgrades to handle higher-purity grades with stricter moisture limits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methyl Isobutyl Ketone (MIBK) Market |
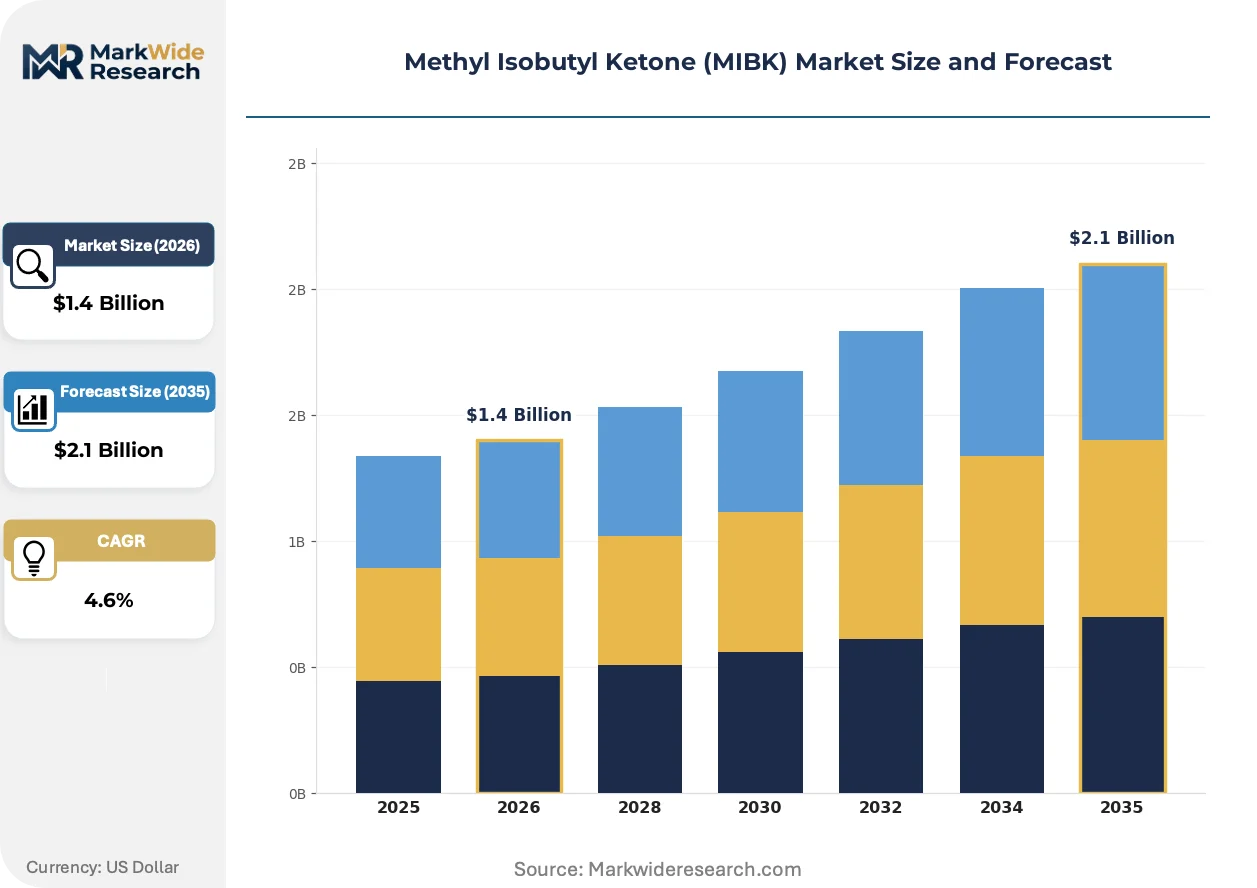
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.1 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvents, Chemical Intermediates, Coatings, Adhesives Application: Paints, Cleaning Agents, Pharmaceuticals, Specialty Chemicals End User: Automotive, Construction, Electronics, Food Industry Distribution Channel: Direct Sales, Distributors, E-commerce, Retail |
| Companies Covered | Arkema Group, Celanese Corporation, Sasol, Eastman Chemical Company, Dow Chemical Company, Kumho P&B Chemicals Inc., Mitsui Chemicals, Shell plc, LCY Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methyl Isobutyl Ketone (MIBK) Market Emerging Trajectories
Process intensification and regulatory harmonization pressures are compressing traditional production economics while opening differentiated pathways for integrated and specialty-focused suppliers.
Membrane separation technology for final-stage moisture removal is consolidating quality control economics for pharmaceutical-grade production. Specialty chemical buyers in Germany and Switzerland are specifying membrane-polished material for extraction protocols. This capability compression is marginalizing thermal drying investments among mid-scale producers without unit operation integration.
REACH authorization list expansion is forcing substance-by-substance requalification across European coating supply chains. Downstream formulators in France and the Netherlands are pre-emptively substituting toward pre-registered ketone grades with sunset date certainty. Automotive OEM coating operations are absorbing compliance costs through solvent system reengineering rather than material switching.
Direct mill-supply contracting is displacing traditional distributor intermediation in high-volume coating operations. Tier-one automotive paint shops in Michigan and Ontario are negotiating frame contracts with terminal storage access. This channel compression is visible most acutely in North American industrial corridors with rail-served chemical terminals and dedicated tank car arrangements.
Methyl Isobutyl Ketone (MIBK) Market Segmentation
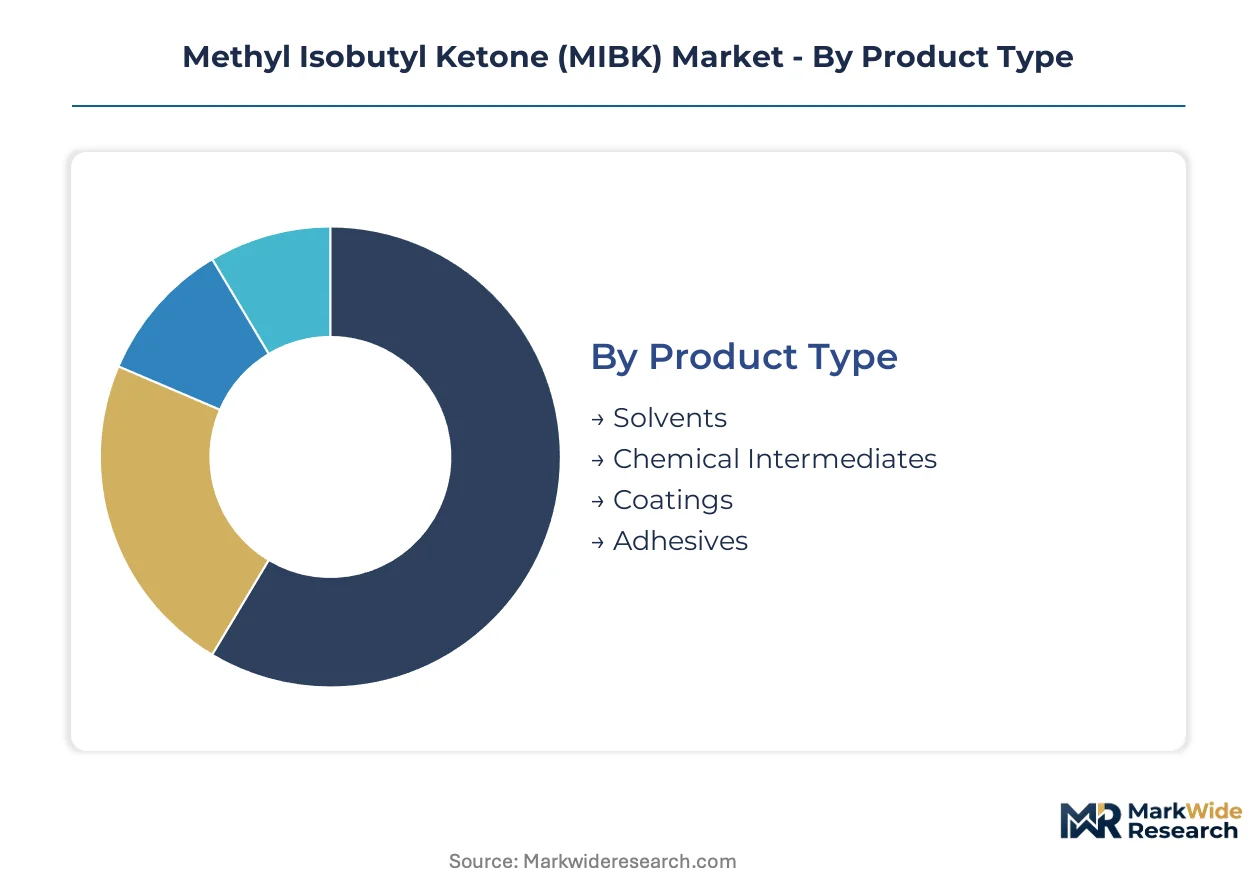
MIBK demand fragments across solvent purity grades, extraction protocols, and coating formulation requirements. Each segment carries distinct specification thresholds that reshape procurement economics and supplier qualification timelines.
Product Type:
Technical specifications separate commodity flows from premium extraction grades.
- Solvents:Medium-evaporation ketone serving paint thinning and lacquer formulation where balanced solvency power controls drying rates. Automotive OEM coating operations in Michigan and Ontario absorb volumes through direct terminal access arrangements.
- Chemical Intermediates:Feedstock for rubber antioxidants and specialty agrochemical synthesis requiring controlled impurity profiles. German and Swiss pharmaceutical extractors specify membrane-polished material for active ingredient isolation protocols.
- Coatings:Industrial protective and decorative finishes where VOC compliance limits blend flexibility.
- Adhesives:Solvent-borne systems for high-performance bonding in automotive assembly.
Solvents leads on scale; chemical intermediates leads on momentum.
Application:
End-use performance requirements stratify purity grades and certification burdens.
- Paints:Architectural and industrial coating formulations where EPA VOC rules constrain solvent selection. Tier-one automotive paint shops reformulate systems rather than switch materials to maintain finish quality.
- Pharmaceuticals:Active pharmaceutical ingredient extraction demanding ultra-high-purity grades with batch-traceable moisture documentation. REACH authorization timelines are forcing pre-emptive requalification toward pre-registered ketone grades.
- Cleaning Agents:Precision degreasing for electronics and metal finishing operations.
- Specialty Chemicals:Agrochemical and fine chemical synthesis with custom specification requirements.
Paints commands volume concentration; pharmaceuticals expands most quickly.
End User:
Industry-specific regulatory exposure and performance tolerances segment buyer priorities.
- Automotive:OEM coating operations facing tightening volatile organic compound limits across assembly plants. Reformulation investments absorb compliance costs while preserving solvent system performance.
- Construction:Architectural coatings and adhesives where waterborne substitution captures share where specifications permit.
- Electronics:Precision cleaning and component manufacturing with residue sensitivity.
- Food Industry:Extraction and processing applications with strict purity and contaminant thresholds.
Automotive anchors procurement scale; electronics climbs fastest on specification intensity.
Distribution Channel:
Channel economics shift with volume scale and geographic concentration of demand.
- Direct Sales:Frame contracts with terminal storage access displacing distributor intermediation in high-volume corridors. Rail-served chemical terminals in North American industrial clusters enable dedicated tank car arrangements.
- Distributors:Regional stocking for mid-scale coating operations without terminal access.
- E-commerce:Small-volume specialty grades with documented certification for laboratory and pilot-scale buyers.
- Retail:Consumer-scale solvent products for maintenance and repair applications.
Direct sales captures volume consolidation; e-commerce gains on specification transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIBK production scaled through German chemical engineering in the mid-20th century before dispersing to acetone-rich petrochemical corridors. Today, supply concentrates where integrated ketone complexes and solvent demand clusters overlap.
United States
Gulf Coast petrochemical integration sustains bulk solvent output for automotive OEM coating operations. EPA VOC rule stringency forces reformulation investments across Michigan and Ontario paint shops. Terminal storage access in Houston and Chicago corridors enables direct mill-supply contracting that displaces traditional distribution.
Germany
Ruhr Valley chemical complexes anchor European ketone production with captive acetone feedstock security. REACH authorization timelines filter non-compliant producers and consolidate demand among pre-registered suppliers. Pharmaceutical extractors in Ludwigshafen and Leverkusen specify membrane-polished grades for active ingredient isolation protocols.
China
Yangtze River Delta manufacturing clusters absorb rising solvent-grade volumes for industrial coatings expansion. GB standards and MEE environmental enforcement tighten process emissions controls across Shandong and Jiangsu production bases. Ningbo and Shanghai terminals serve direct supply contracts with automotive assembly plants.
India
Gujarat chemical parks drive solvent-grade absorption for protective coatings across Mumbai-Pune manufacturing belts. BIS certification requirements extend product registration timelines for imported material. Ankleshwar and Dahej clusters host distillation facilities serving pharmaceutical extraction demand.
Japan
Kansai region precision chemical producers supply ultra-high-purity grades for electronics cleaning and pharmaceutical synthesis. METI chemical management frameworks shape workplace exposure limits and closed-system transfer equipment adoption. Osaka-based formulators serve regional automotive coating operations with moisture-controlled specifications.
Methyl Isobutyl Ketone (MIBK) Market Vendor Landscape
The competitive structure tilts toward integrated petrochemical majors with captive feedstock positions. Three tiers separate Gulf Coast scale players from European specialty-grade refiners and Asian volume exporters. Strategic moves concentrate on backward integration into acetone supply and membrane separation technology licensing for pharmaceutical-grade certification.
Among integrated majors, Arkema Group, Dow Chemical Company, and Sasol exemplify distinct feedstock strategies. Arkema leverages European acetone positions. Dow anchors Gulf Coast petrochemical scale. Sasol draws Fischer-Tropsch-derived streams. Kumho P&B Chemicals Inc. and LCY Group represent Asian volume exporters. Celanese Corporation and Eastman Chemical Company occupy North American specialty solvent positions. Mitsui Chemicals and Shell plc exemplify diversified chemical portfolio approaches.
| Leading Market Players |
|---|
| Arkema Group |
| Celanese Corporation |
| Sasol |
| Eastman Chemical Company |
| Dow Chemical Company |
| Kumho P&B Chemicals Inc. |
| Mitsui Chemicals |
| Shell plc |
| LCY Group |
| Others |
Supply Flow & Price Mechanics
Process safety engineering talent scarcity in the Ruhr Valley and Kansai region feeds directly into labor-cost differentials that separate pharmaceutical-grade premiums from commodity solvent pricing tiers. Acetone feedstock volatility transmits unevenly across these tiers, squeezing margin structures for non-integrated producers while integrated majors capture arbitrage through captive supply positions.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, industrial-solvent, and extraction-commodity levels anchors the market. Price differentiation centers on membrane-polished certification for active ingredient isolation protocols versus standard solvent-grade material for paint thinning applications. Cost compression in the industrial-solvent tier is intensifying because waterborne coating substitution captures share where performance specifications permit. Tier-one automotive paint shops show least price sensitivity due to reformulation lock-in costs, while mid-scale coating operations without terminal access face highest procurement pressure.
Supply Chain Analysis
Specialized expertise in ketone handling and reactive chemical management concentrates in German chemical engineering clusters and Gulf Coast petrochemical corridors. MIBK production draws from acetone-rich feedstock positions in the United States, Germany, and China, with distillation capacity tethered to coastal terminal access for efficient solvent distribution. Single-source vulnerability runs through acetone supply concentration among integrated majors. Distribution runs through direct mill-supply contracting with rail-served chemical terminals displacing traditional distributor intermediation in high-volume North American industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MIBK market reads as a late-cycle quality story where pharmaceutical extraction protocols drive demand-shift toward membrane-polished grades with batch-traceable moisture documentation. Premium specification intensity is concentrating procurement power among certified suppliers with verified supply chain credentials.
For Market Incumbents: Extend membrane separation technology licensing to pharmaceutical-grade producers in Ludwigshafen and Leverkusen, securing royalty streams as REACH authorization timelines filter non-compliant competitors. Deepen backward integration into acetone supply through European captive feedstock positions to defend margin stability against crude acetone cost swings. Waterborne coating substitution in architectural segments threatens volume absorption; counter through closed-system transfer equipment bundling for OSHA PEL compliance investments. For New Entrants and Emerging Players: Begin with specialty chemicals grade production for agrochemical extraction applications in Ankleshwar and Dahej clusters, where BIS certification requirements extend registration timelines for imported material and create local production preference. Target pharmaceutical extractors in Osaka-based precision chemical corridors with ultra-high-purity grades for electronics cleaning protocols. Go-to-market angle: carbon border adjustment positioning with verified low-carbon process credentials for EU CBAM first-mover advantage. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale European solvent refiners without membrane-polishing capability facing REACH consolidation pressure. Long-term viability frames around pharmaceutical-grade certification intensity and regulatory compliance infrastructure rather than commodity solvent scale. Acquisition target archetype: integrated ketone complexes with captive acetone and terminal storage access in rail-served industrial corridors. Signal to watch: EPA VOC rule stringency tightening beyond current formulation flexibility constraints, accelerating solvent system reengineering spend among automotive OEM coating operations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetone | Captive feedstock security insulates margin stability against crude acetone price volatility transmitted from phenol co-production economics. |
| Membrane Separation Technology Licensing | Quality control capability compression marginalizes thermal drying investments among mid-scale producers without unit operation integration. |
| Carbon Border Adjustment Positioning | EU CBAM implementation creates first-mover advantage for producers with documented Scope 3 emissions and verified low-carbon process credentials. |
| Closed-System Transfer Equipment Bundling | OSHA PEL compliance investments open aftermarket service opportunities around workplace exposure management in automotive coating operations. |
| Direct Mill-Supply Contracting | Frame contracts with terminal storage access displace distributor intermediation in Michigan and Ontario high-volume automotive paint corridors. |
Methodological Framework
Bottom-up solvent-grade and pharmaceutical-grade modeling reconciled against top-down acetone feedstock and ketone complex capacity tracking forms the analytical core of this study. Primary interviews with plant managers, procurement leads at downstream OEM coating operations, distribution channel partners, and technical R&D directors in German and Gulf Coast chemical clusters combined with secondary validation from customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings from integrated petrochemical majors. Triangulation across these sources calibrated volume and value estimates.
Input-output matrices mapped acetone condensation capacity through acidic catalyst configurations to downstream solvent demand clusters across the projection horizon. Segmentation dimensions modeled include purity grade tier, end-use industry application, and regional production hub concentration. CAGRs were derived from weighted average growth contributions across automotive coating reformulation investments, pharmaceutical extraction protocol expansion, and industrial coatings absorption in South Asian manufacturing belts. Forecast inputs incorporated REACH authorization timeline impacts and EPA VOC rule stringency trajectories.
Several conditions sit outside the modeled scope, including abrupt regulatory reversals on carbon border adjustment implementation, breakthrough waterborne coating performance parity eliminating solvent-grade demand, and acetone supply disruptions from phenol demand collapse. Forecasts reflect assumptions around continued automotive OEM coating solvent system reengineering rather than material switching. Material deviation in acetone price volatility trajectories or REACH sunset date acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Phenol Market
Organic Chemicals
Gamma-Butyrolactone (GBL) Market
Organic Chemicals
Aspartic Acid Market
Organic Chemicals
Synthetic and Bio-Based Aniline Market
Organic Chemicals
Global Ketones Market
Organic Chemicals
Dioctyl Maleate (DOM) Market
Organic Chemicals
North America Organic Acid Market
Organic Chemicals
US Humate Market
Organic Chemicals
Organic Matting Agent Market
Organic Chemicals
North America Phenol Market
Organic Chemicals
Dioctyl Phthalate Market
Organic Chemicals
Dimethyl Carbonate Market
Organic Chemicals
Acetylacetone Market
Organic Chemicals
2-Fluorobenzotrifluoride Market
Organic Chemicals
4-Tert-Amylphenol Market
Organic Chemicals
Global Carboxylic Acid Market