
 Dioctyl Maleate (DOM) Market | 2026-2036
Dioctyl Maleate (DOM) Market Size, Share, and Industry Trends Forecast 2026-2036
Dioctyl Maleate (DOM) Market Outlook
REACH is decoupling legacy plasticizer economics from European formulation contracts. Celanese Corporation leverages integrated acetyl chain assets to stabilize feedstock exposure across Atlantic markets. Polynt anchors southern European supply through dedicated esterification capacity in Italy. BASF SE differentiates via specialty additive portfolios that bundle DOM with co-plasticizer systems.
Dioctyl maleate functions as a diester plasticizer produced through maleic anhydride esterification with 2-ethylhexanol, yielding a colorless liquid with low volatility and excellent compatibility with polyvinyl chloride resins. Plasticizers command the dominant product type position due to PVC compounding scale, while adhesives represent the fastest-expanding category as solvent-free bonding formulations gain industrial preference. The construction end user segment carries the deepest margin pools through infrastructure-grade volume contracts, whereas automotive electronics wiring harness demand is shifting formulation specifications toward higher thermal stability grades.
EPA oversight of volatile organic compound emissions constrains domestic manufacturing process designs in the United States, while ECHA substance evaluation under REACH governs import and use authorization across European member states. China's MEE enforces dual carbon goals that tighten energy intensity benchmarks for esterification operations in Shandong and Jiangsu provinces. Stakeholders must monitor evolving polymer substitution dynamics as bio-based plasticizer platforms mature and regulatory thresholds for ortho-phthalate alternatives tighten without explicit calendar deadlines.
Market Dynamics
REACH ortho-phthalate restrictions are rewiring European plasticizer procurement toward maleate ester alternatives, while construction sector demand for flexible PVC compounds absorbs incremental DOM capacity across formulation networks.
Growth Catalysts
- REACH Annex XIV Authorization:The European Chemicals Agency's tightening controls on DEHP and DBP are redirecting compounder procurement toward dioctyl maleate as a technically viable drop-in substitute for wire insulation and flooring applications.
- 2-Ethylhexanol Feedstock Abundance:Integrated acetyl chain producers in the US Gulf Coast and Western Europe are stabilizing alcohol supply economics, lowering input cost volatility for esterification operations serving PVC compounders.
- Construction Sector PVC Intensity:Infrastructure-grade cabling and membrane roofing specifications in Germany, China, and the United States are embedding higher plasticizer loadings per linear meter of finished product.
Market Restraints
- Maleic Anhydride Price Volatility:Naphtha-cracker co-product availability fluctuates with benzene demand cycles, compressing margin predictability for non-integrated ester producers.
- Shandong-Jiangsu Supply Concentration:China's dual carbon enforcement has shuttered smaller esterification units, concentrating effective capacity among state-affiliated chemical parks with MEE emissions compliance.
- Bio-Based Plasticizer Substitution:Epoxidized soybean oil and citrate ester platforms are capturing premium sustainability-specified contracts from automotive OEMs with Scope 3 reduction mandates.
Strategic Opportunities
- India BIS Standards Harmonization:The Bureau of Indian Standards' pending alignment with IEC cable specifications creates an opening for maleate plasticizers in domestic wire and harness manufacturing.
- Solvent-Free Adhesive Formulations:Reactive hot-melt systems for automotive interior bonding are absorbing DOM as a viscosity-modifying co-monomer with polyurethane prepolymers.
- EU Green Deal Public Procurement:Construction tender scoring for low-VOC building materials is privileging phthalate-free plasticizer certificates in municipal infrastructure awards.
Industry Challenges
- Esterification Process Energy Intensity:China's MEE dual carbon benchmarks are forcing facility-level heat integration retrofits requiring seven-figure capital deployment per production line.
- REACH SVHC Notification Burden:Substance volume tracking and downstream communication obligations are consuming specialized regulatory affairs capacity at mid-scale compounders without dedicated compliance infrastructure.
- Legacy Phthalate Contamination Testing:Cross-contamination detection at parts-per-billion thresholds is extending batch release timelines for converters serving medical device and toy end-uses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dioctyl Maleate (DOM) Market |
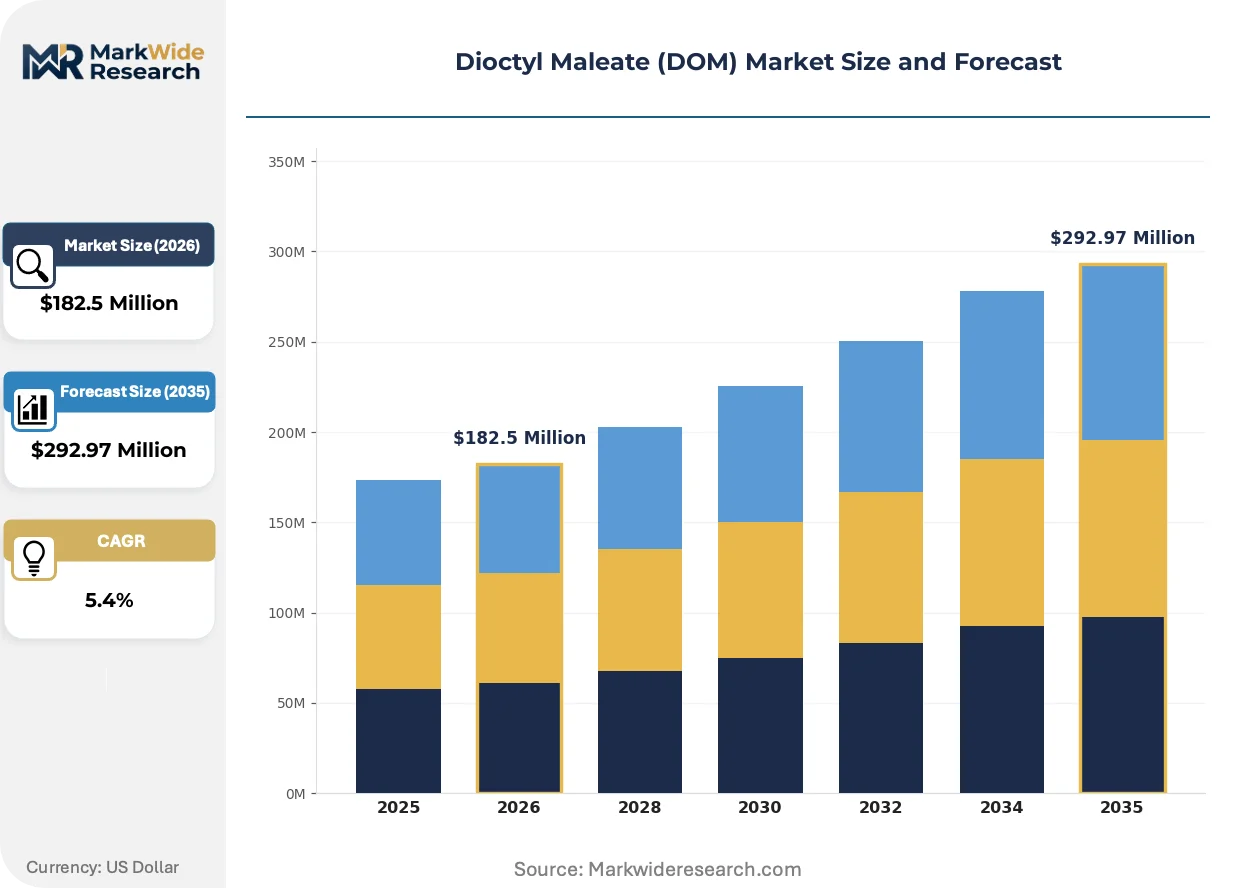
| Market Size in 2026 | $182.5 Million |
| Market Size in 2035 | $292.97 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasticizers, Resins, Adhesives, Coatings Application: PVC Products, Paints, Inks, Textiles End User: Construction, Automotive, Electronics, Consumer Goods Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Celanese Corporation, Polynt, Sigma-Aldrich, Inc., Hallstar Company, Eastman Chemical Company, Nayakem, TCI Chemicals (India) Pvt. Ltd., Prakash Chemicals International Private Limited, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dioctyl Maleate (DOM) Market Strategic Shifts
Reactive extrusion technologies are compressing plasticizer incorporation cycles, while regulatory substance evaluation is forcing reformulation transparency across supply tiers.
Continuous esterification reactor designs with inline acid value monitoring are modularizing production scale economics, allowing regional compounders to match integrated producer cost structures without captive maleic anhydride supply. Mid-scale PVC processors in Poland and the Czech Republic are adopting skid-mounted units for just-in-time plasticizer synthesis. This distributed manufacturing architecture is compressing working capital requirements and shortening specification-to-delivery lead times for custom viscosity grades.
ECHA's 2024-2026 substance evaluation work program is scrutinizing maleate ester metabolite toxicity profiles, forcing registrants to generate extended one-generation reproductive toxicity data packages. The industrial consequence is a bifurcation between legacy registration holders with existing vertebrate study archives and new market entrants facing six-figure testing cost barriers. Automotive wiring harness specifications in Germany are preemptively requiring third-party REACH compliance attestations from all plasticizer tiers.
Specification-driven procurement is consolidating buyer power among tier-1 cable compounders with dedicated technical service teams and formulation co-development contracts. Direct mill-to-compounder relationships are displacing distributor intermediaries for volume PVC applications. This channel compression is most visible in China's Yangtze River Delta, where state-owned resin producers are integrating downstream plasticizer blending capabilities to capture integrated margin pools.
Dioctyl Maleate (DOM) Market Segmentation
Segmentation in dioctyl maleate markets reveals how procurement power, formulation complexity, and regulatory exposure fragment commercial relationships. Buyers sort across product grades, application requirements, and channel preferences that determine margin capture and contract tenure.
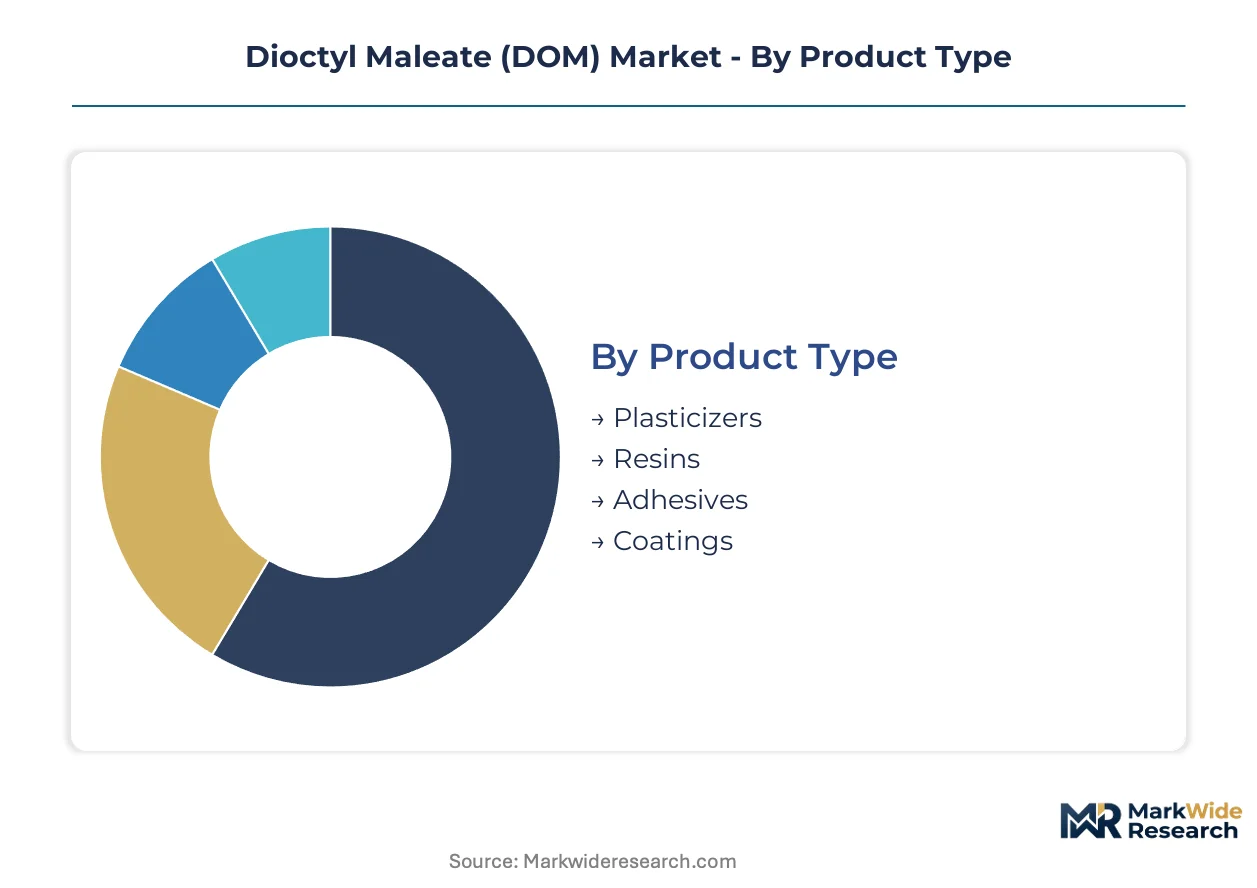
Product Type:
Plasticizer buyers prioritize compatibility coefficients and volatility profiles, while resin and coating formulators emphasize molecular weight distribution and cure kinetics.
- Plasticizers:Dioctyl maleate serves as a diester plasticizer produced through maleic anhydride esterification with 2-ethylhexanol, yielding a colorless liquid with low volatility and excellent compatibility with polyvinyl chloride resins. Construction sector demand for flexible PVC products in Germany, China, and the United States absorbs the dominant share of formulation volume, driven by infrastructure-grade cabling and membrane roofing specifications embedding higher plasticizer loadings per linear meter.
- Adhesives:Reactive hot-melt systems for automotive interior bonding absorb DOM as a viscosity-modifying co-monomer with polyurethane prepolymers. Solvent-free bonding formulations in Germany and the United States are expanding most quickly as industrial preference shifts toward reduced volatile organic compound emissions.
- Resins:Alkyd and polyester resin modification employs maleate esters for air-drying cure acceleration in protective coatings.
- Coatings:Industrial maintenance and marine coating segments specify DOM for gloss retention and substrate adhesion in high-humidity environments.
Volume sits with Plasticizers; growth tilts toward Adhesives.
Application:
PVC compounders command the deepest specification expertise, while paint and textile processors trade formulation flexibility for cost position.
- PVC Products:Wire insulation, flooring, and synthetic leather applications dominate tonnage absorption across European and Asian formulation networks. REACH Annex XIV authorization restrictions on DEHP and DBP are redirecting compounder procurement toward dioctyl maleate as a technically viable drop-in substitute.
- Paints:Architectural and industrial coating segments leverage DOM for pigment wetting and film flexibility in waterborne systems.
- Inks:Flexographic and gravure printing formulations employ maleate plasticizers for substrate adhesion and rub resistance.
- Textiles:Synthetic fiber finishing and fabric coating applications specify DOM for hand modification and durability enhancement.
PVC Products anchor current volume; textile applications are gaining share fastest as technical specifications mature.
End User:
Construction buyers negotiate infrastructure-grade volume contracts with extended tenures, while automotive and electronics segments impose thermal stability and contamination testing requirements.
- Construction:Infrastructure-grade cabling and membrane roofing specifications in Germany, China, and the United States embed higher plasticizer loadings per linear meter. Municipal infrastructure awards under EU Green Deal public procurement scoring privilege phthalate-free plasticizer certificates.
- Automotive:Wiring harness specifications in Germany are preemptively requiring third-party REACH compliance attestations from all plasticizer tiers. Automotive OEMs with Scope 3 reduction mandates are capturing premium sustainability-specified contracts.
- Electronics:Cross-contamination detection at parts-per-billion thresholds extends batch release timelines for converters serving medical device and toy end-uses.
- Consumer Goods:Flexible packaging and household product applications drive specification diversity across mid-scale compounders.
Construction carries the deepest margin pools; automotive electronics demand is climbing the fastest toward higher thermal stability grades.
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and working capital constraints across buyer tiers.
- Direct Sales:Tier-1 cable compounders with dedicated technical service teams and formulation co-development contracts are consolidating procurement through direct mill relationships. State-owned resin producers in China's Yangtze River Delta are integrating downstream plasticizer blending capabilities to capture integrated margin pools.
- Distributors:Regional compounders in Poland and the Czech Republic rely on distributor intermediaries for custom viscosity grades and just-in-time delivery.
- Online Retail:Small-batch and specialty grade procurement is fragmenting toward digital platforms for price transparency.
- Wholesalers:Volume PVC applications in construction sectors maintain traditional wholesale relationships for inventory buffering.
Direct Sales commands volume concentration; Online Retail is expanding most quickly among small-batch formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction sector procurement for flexible PVC cabling and membrane roofing concentrates formulation demand across Germany, China, and the United States. Regulatory divergence on phthalate restrictions and carbon intensity benchmarks is fragmenting regional supply economics. Industrial clusters in Shandong, the US Gulf Coast, and the Rhine-Ruhr corridor anchor effective esterification capacity.
China
Infrastructure-grade cabling and synthetic leather manufacturing in Jiangsu and Zhejiang provinces absorb substantial DOM volume for PVC compounding. The MEE enforces dual carbon goals that tighten energy intensity benchmarks for esterification operations, shuttering smaller units in Shandong. State-affiliated chemical parks in the Yangtze River Delta concentrate compliant capacity with integrated emissions controls.
Germany
Automotive wiring harness specifications and construction membrane roofing drive premium-grade plasticizer procurement from compounders in Bavaria and North Rhine-Westphalia. ECHA REACH Annex XIV authorization restrictions on DEHP and DBP redirect procurement toward maleate ester alternatives. The Rhine-Ruhr industrial corridor hosts integrated acetyl chain producers with captive 2-ethylhexanol supply.
United States
Gulf Coast petrochemical complexes leverage abundant shale-derived feedstock for integrated maleic anhydride and 2-ethylhexanol production. EPA oversight of volatile organic compound emissions constrains domestic manufacturing process designs, favoring larger facilities with advanced scrubbing systems. Texas and Louisiana chemical parks supply regional PVC compounders serving construction and automotive end-uses.
India
Domestic wire and cable manufacturing in Maharashtra and Gujarat is expanding as the Bureau of Indian Standards advances alignment with IEC specifications. CDSCO and BIS regulatory harmonization creates openings for maleate plasticizers in electrical insulation applications. Mumbai-Pune industrial corridor compounders are qualifying alternative plasticizers for export-oriented automotive harness contracts.
Italy
Southern European adhesive and coating formulators in Lombardy and Emilia-Romagna specify DOM for solvent-free bonding systems and alkyd resin modification. EU Green Deal public procurement scoring for low-VOC building materials privileges phthalate-free plasticizer certificates in municipal infrastructure awards. Po Valley chemical processors serve Mediterranean construction and marine coating end-uses.
Dioctyl Maleate (DOM) Market Competitive Environment
US Gulf Coast producers anchor one tier with integrated acetyl chain assets; European specialists hold formulation co-development relationships with tier-1 cable compounders. The vendor base sorts between scale-driven integrated producers and regional esterification specialists serving custom viscosity grades. Three archetypes dominate: petrochemical majors with captive feedstock, mid-scale ester producers with technical service capabilities, and distributor-intermediated regional compounders. Capacity expansion and backward integration into maleic anhydride supply represent the dominant competitive moves.
Within the integrated producer tier, Celanese Corporation exemplifies Gulf Coast petrochemical positioning with acetyl chain asset leverage. BASF SE anchors European specialty additive portfolios that bundle DOM with co-plasticizer systems. Polynt occupies a position among southern European specialists with dedicated Italian esterification capacity serving adhesive and coating formulators.
| Leading Market Players |
|---|
| Celanese Corporation |
| Polynt |
| Sigma-Aldrich, Inc. |
| Hallstar Company |
| Eastman Chemical Company |
| Nayakem |
| TCI Chemicals (India) Pvt. Ltd. |
| Prakash Chemicals International Private Limited |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
REACH Annex XIV authorization compliance gates both qualified supply access and premium-tier pricing power for European compounders, forcing non-compliant producers into spot-market discounting while certified registrants capture infrastructure-grade contract premiums. Buyers in Germany and the United States now segment procurement across lead-time reliability, with municipal tenders under EU Green Deal scoring privileging phthalate-free certificates that command measurable price separation from generic grades.
Pricing Analysis
Lead-time-driven pricing stratification separates just-in-time compounders from inventory-buffered buyers, with premium coefficients applied to sub-48-hour specification-to-delivery cycles. Three-tier pricing structure across REACH-certified premium, standard industrial, and spot-economy levels reflects ECHA registration status and contamination testing depth. Cost compression in standard grades intensifies as Shandong capacity consolidation feeds surplus volume into distributor channels. Tier-1 cable compounders exhibit lowest price sensitivity due to co-development contract tenure, while mid-scale Polish and Czech processors negotiate aggressively on volume scale.
Supply Chain Analysis
Dual-sourcing mandates from automotive OEMs in Germany and construction procurement offices in the United States require qualified backup suppliers for all plasticizer tiers, extending qualification timelines but reducing single-source vulnerability. Effective capacity concentrates in China, Germany, and the United States, with Jiangsu chemical parks, the Rhine-Ruhr corridor, and Texas-Louisiana Gulf Coast sites anchoring maleic anhydride esterification. Feedstock draws from naphtha-cracker co-product streams, shale-derived ethylene chains, and imported 2-ethylhexanol cargoes. Tariff exposure on maleic anhydride imports into the European Union poses structural risk for non-integrated compounders. Distribution runs through direct mill relationships for volume PVC applications and distributor intermediaries for custom viscosity grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive maleic anhydride supply and downstream compounding assets determine margin capture. Players are pursuing upstream control over feedstock economics as the decisive competitive lever.
For Market Incumbents: Lock in long-term 2-ethylhexanol offtake agreements with US Gulf Coast and Rhine-Ruhr acetyl chain producers to neutralize feedstock volatility. Secure ECHA REACH authorization extensions ahead of the substance evaluation work program to maintain registration moats against testing-cost-barriered entrants. Celanese Corporation and BASF SE already demonstrate this positioning through integrated asset leverage and specialty additive bundling. For New Entrants and Emerging Players: The premium-economy price-point gap in Indian wire and cable manufacturing opens white-space opportunity as BIS-IEC harmonization accelerates. Target Maharashtra and Gujarat compounders with technical service partnerships that substitute for unavailable REACH registration archives. Solvent-free adhesive formulations for automotive interior bonding in Italy and Germany offer fastest penetration with lowest incumbent lock-in. For Investors and Strategic Acquirers: ECHA's publication of extended one-generation reproductive toxicity data requirements is the leading indicator that registration-holder consolidation will accelerate. The 5-to-10-year viability window favors acquisition of mid-scale European ester producers with existing vertebrate study archives and Italian or German manufacturing footprints. Watch for CDSCO-BIS alignment announcements in India as the signal that domestic qualification timelines are compressing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Maleic Anhydride | Celanese and BASF anchor margin stability through captive naphtha-cracker co-product supply. |
| REACH Registration Portfolio Expansion | ECHA substance evaluation compliance separates legacy holders from testing-cost-exposed new entrants. |
| Continuous Esterification Reactor Deployment | Skid-mounted modular units in Poland and Czech Republic compress working capital for regional compounders. |
| India BIS Standards Qualification | Mumbai-Pune corridor compounders capture export-oriented automotive harness contract opportunities. |
| Solvent-Free Adhesive Formulation Partnerships | Reactive hot-melt systems with polyurethane prepolymers absorb DOM as viscosity-modifying co-monomer. |
Study Parameters
Independent corroboration across plant managers at esterification facilities, procurement leads at PVC compounders, distribution channel partners, and technical R&D directors underwrites the qualitative findings in this study. Primary interviews with these stakeholders combined with secondary validation from customs/trade data, Cefic sector reports, SEC 10-K filings, and ECHA registration databases established demand-side and supply-side baselines. Bottom-up volume modeling across product grades and top-down macroeconomic alignment verified segmentation splits.
Rate-of-change decomposition across the analysis window separates volume growth from price-mix effects, with CAGRs derived from segment-level regression against construction spending indices and automotive production data. The forecast framework models plasticizer grade tier, adhesive versus resin end-use, regional production hub concentration, and REACH compliance status as primary segmentation dimensions. Maleic anhydride price volatility coefficients and dual carbon enforcement intensity in Shandong-Jiangsu provinces feed scenario-weighted projections.
Inputs from ECHA substance evaluation timelines and MEE emissions compliance records were available through the study window; gaps in proprietary formulation specification data from tier-1 cable compounders introduce uncertainty bands around adhesive segment growth rates. Deviation in REACH SVHC notification enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
High Purity Metal Organics Market
Organic Chemicals
N-Hexanol Market
Organic Chemicals
Organic Matting Agent Market
Organic Chemicals
Synthetic and Bio-Based Aniline Market
Organic Chemicals
Synthetic Antioxidants Market
Organic Chemicals
1,3-Dichloroacetone Market
Organic Chemicals
Acetaldehyde Market
Organic Chemicals
Dioctyl Phthalate Market
Organic Chemicals
Global Carboxylic Acid Market
Organic Chemicals
Trimethylcyclohexanone Market
Organic Chemicals
Behenyl Alcohol Market
Organic Chemicals
Cyclohexanone Market
Organic Chemicals
Soy Chemicals Market
Organic Chemicals
Isophthalic Acid Market
Organic Chemicals
Chlorinated Methane Market
Organic Chemicals
Europe Cycloalkanes Market