
 Global Iron Chelates Market | 2026-2036
Global Iron Chelates Market Size, Share, and Industry Trends Forecast 2026-2036
Global Iron Chelates Market Outlook
Modular micronutrient bundling is decoupling iron chelates from traditional NPK fertilizer packages, letting growers customize foliar programs by crop stage. BASF SE leverages its polymer chemistry heritage to sustain premium positioning in EDDHA formulations. Haifa Group anchors its competitive stance through backward integration into phosphoric acid and potassium sources. Valagro specializes in biostimulant-chelate combinations that differentiate its portfolio from commodity suppliers.
Iron chelates are coordination complexes where a central iron ion binds to multidentate organic ligands such as EDTA, DTPA, or EDDHA, forming water-soluble structures that prevent iron precipitation in alkaline soils and physiological solutions; EDDHA chelates maintain stability up to pH 11, making them essential for calcareous soil agriculture. Iron EDDHA commands the dominant share of margin pools in high-value horticulture, while Iron EDTA competes aggressively on cost in broad-acre field crops. The agriculture end-use segment leads absolute volume, though pharmaceutical-grade specifications for parenteral nutrition applications carry substantially higher unit economics.
The EPA governs agricultural chemical registration and residue tolerances in the United States, while REACH and the EU F-Gas Regulation shape chemical purity and environmental release standards across Europe; China's MEE and SAMR enforce GB fertilizer standards that now mandate declared chelation efficiency on product labels. India's FSSAI and CDSCO maintain separate but converging requirements for food-grade and pharmaceutical-grade iron chelates. Stakeholders must monitor how divergent national purity testing protocols affect cross-border formulation registration costs and inventory pooling strategies.
Market Dynamics
Precision agriculture platforms in Brazil's soybean belt are decoupling iron chelates from commodity NPK bundles, forcing suppliers to rebuild formulation portfolios around crop-stage customization rather than bulk blending economics.
Growth Catalysts
- Soil health subsidies:India's government-backed soil health programs in wheat-producing states are directly subsidizing chelated micronutrient adoption, creating guaranteed offtake channels for domestic blenders.
- REACH compliance tightening:ECHA's evolving purity specifications for fertilizer-grade chelates are disqualifying legacy suppliers and consolidating qualification pools around certified producers.
- Calcareous soil agriculture:EDDHA's stability threshold up to pH 11 is expanding addressable acreage in high-alkalinity regions where conventional iron sources precipitate uselessly.
Market Restraints
- Phosphoric acid cost volatility:Backward-integrated producers with captive phosphoric acid supply enjoy structural cost advantages that independent blenders cannot replicate, compressing margins for non-integrated competitors.
- China GB standard fragmentation:SAMR and MEE enforcement of divergent chelation efficiency testing protocols across provincial jurisdictions creates registration friction and inventory pooling penalties for multinational suppliers.
- Low-cost EDTA substitution:Iron EDTA's aggressive cost positioning in broad-acre field crops constrains EDDHA premium capture outside high-value horticulture segments.
Strategic Opportunities
- Biostimulant convergence:Combining iron chelates with biostimulant actives opens differentiation pathways in specialty crop segments where commodity pricing pressure is weakest.
- Pharmaceutical-grade pivot:Parenteral nutrition applications for iron chelates carry substantially higher unit economics than agricultural grades, rewarding purification capability investments.
- Foliar application channel expansion:Drone-based micronutrient spraying services in Brazil are creating direct-to-grower distribution shortcuts that bypass traditional dealer networks.
Industry Challenges
- Cross-border formulation registration:Divergent national purity testing protocols between EPA residue tolerance frameworks, REACH chelation efficiency standards, and China's GB label declaration mandates multiply compliance timelines and costs.
- Legacy blending infrastructure:Existing NPK bulk blending plants lack precision dosing equipment for micronutrient inclusion at crop-stage-specific rates, requiring capital-intensive retrofitting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Iron Chelates Market |
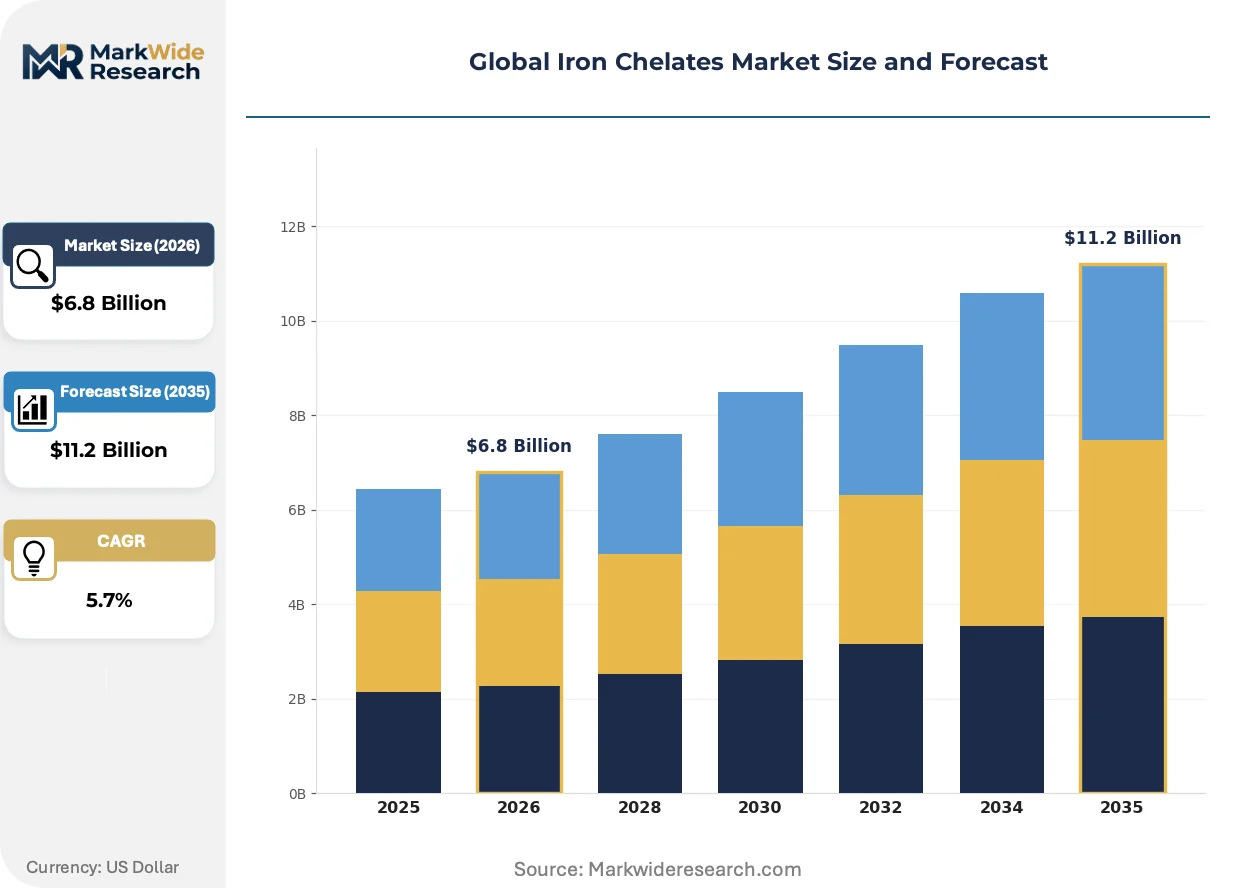
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iron EDTA, Iron DTPA, Iron EDDHA, Iron Tannate End Use Industry: Agriculture, Pharmaceuticals, Food & Beverage, Cosmetics Formulation: Liquid, Granular, Powder, Chewable Distribution Channel: Online, Offline, Direct Sales, Third-Party Retailers |
| Companies Covered | Syngenta, Haifa Group, BASF SE, Tradecorp, Van Iperen International, Nouryon, Valagro, Aries Agro, Yara International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Iron Chelates Market Strategic Shifts
Digital agronomy platforms and polymer chemistry advances are restructuring how iron chelates are formulated, certified, and delivered to end-users across divergent regulatory environments.
Controlled-release polymer encapsulation is automating nutrient availability timing to match crop phenological stages. Large-scale row-crop operators in Brazil's Mato Grosso region are piloting these systems at commercial scale. The technology is automating the shift from calendar-based application schedules to sensor-triggered release, compressing traditional agronomic service margins.
REACH and the EU F-Gas Regulation are mandating stepped reductions in environmental release thresholds for chelating agent production residues. European fertilizer manufacturers face capital-intensive scrubber retrofits or process reengineering to maintain market access. High-value horticulture producers in Spain's Almería greenhouse cluster are absorbing pass-through cost increases while demanding batch-level chelation efficiency certificates.
Modular micronutrient bundling is displacing pre-mixed NPK-micronutrient packages across precision agriculture operations. Growers in India's Punjab and Haryana wheat belts are unbundling inputs to customize foliar programs by growth stage. Dealer networks in these states are restructuring inventory and technical service capabilities to support prescription-based selling rather than commodity volume.
Global Iron Chelates Market Segmentation
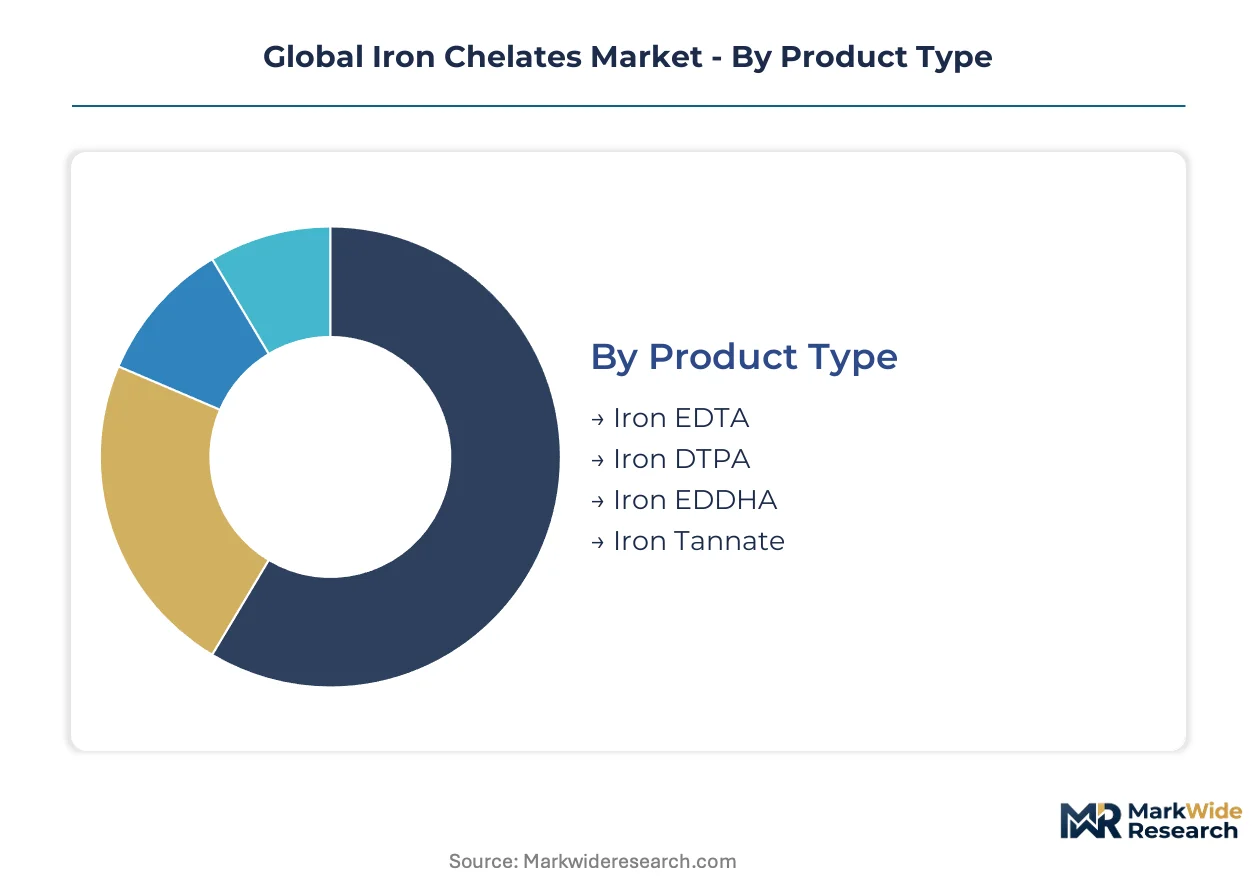
Iron chelate segmentation reveals how formulation chemistry, application context, and delivery format interact to determine margin structure. Suppliers configure product portfolios across these dimensions to match regulatory requirements and end-user technical capabilities.
Product Type:
Integration depth varies sharply across chelating chemistries, with some serving as standalone soil amendments and others embedded in precision fertigation systems.
- Iron EDTA:Ethylenediaminetetraacetic acid complexes offer cost-efficient iron solubility in mildly acidic to neutral conditions. Broad-acre field crops in Brazil's soybean belt absorb substantial volumes where soil pH permits, though precipitation risk above pH 7 limits alkaline deployment.
- Iron EDDHA:Ethylenediamine-N,N'-bis(2-hydroxyphenylacetic acid) maintains chelate integrity up to pH 11, enabling reliable iron availability in calcareous soils where other ligands fail. Spain's Almería greenhouse cluster and India's Haryana wheat belt drive concentrated demand for this premium chemistry.
- Iron DTPA:Diethylenetriaminepentaacetic acid formulations bridge the gap between EDTA economy and EDDHA stability, finding niche application in moderately alkaline hydroponic systems.
- Iron Tannate:Naturally derived polyphenol complexes serve organic-certified agriculture with lower chelation stability but favorable regulatory positioning in EU organic frameworks.
Iron EDTA leads volumes today; Iron EDDHA is gaining share fastest.
End Use Industry:
Cost tier stratification separates commodity agricultural applications from pharmaceutical and cosmetic segments where purification standards multiply unit economics.
- Agriculture:Foliar feeding and soil amendment applications consume the majority of tonnage, with precision agriculture platforms in Brazil and government-subsidized soil health programs in India's Punjab driving formulation customization by crop phenological stage.
- Pharmaceuticals:Parenteral nutrition applications for iron deficiency anemia treatment demand pharmaceutical-grade specifications with batch-level purity certificates, commanding substantially elevated pricing compared to agricultural grades.
- Food & Beverage:Fortification applications in flour milling and beverage processing require food-grade chelates meeting FSSAI, FDA, or EFSA purity thresholds depending on jurisdiction.
- Cosmetics:Topical and hair care formulations utilize iron chelates for color stability and oxidative control, with REACH-compliant sourcing mandatory for EU market access.
Agriculture dominates absolute volume; Pharmaceuticals delivers the steepest margin expansion trajectory.
Formulation:
Application method determines physical form selection, with liquid concentrates displacing solids in precision delivery systems.
- Liquid:Ready-to-use or dilutable concentrates integrate seamlessly with drone-based spraying services and fertigation infrastructure, expanding fastest in Brazil's Mato Grosso commercial farming operations.
- Granular:Slow-release granules suit conventional broadcasting equipment in broad-acre wheat production across India's northern states.
- Powder:Dry soluble powders retain relevance for manual mixing in smallholder contexts and for export logistics efficiency.
- Chewable:Palatable solid formats serve pediatric and geriatric pharmaceutical applications where swallowing conventional tablets presents difficulty.
Liquid formulations are expanding most quickly; Granular retains foundational volume in traditional agricultural markets.
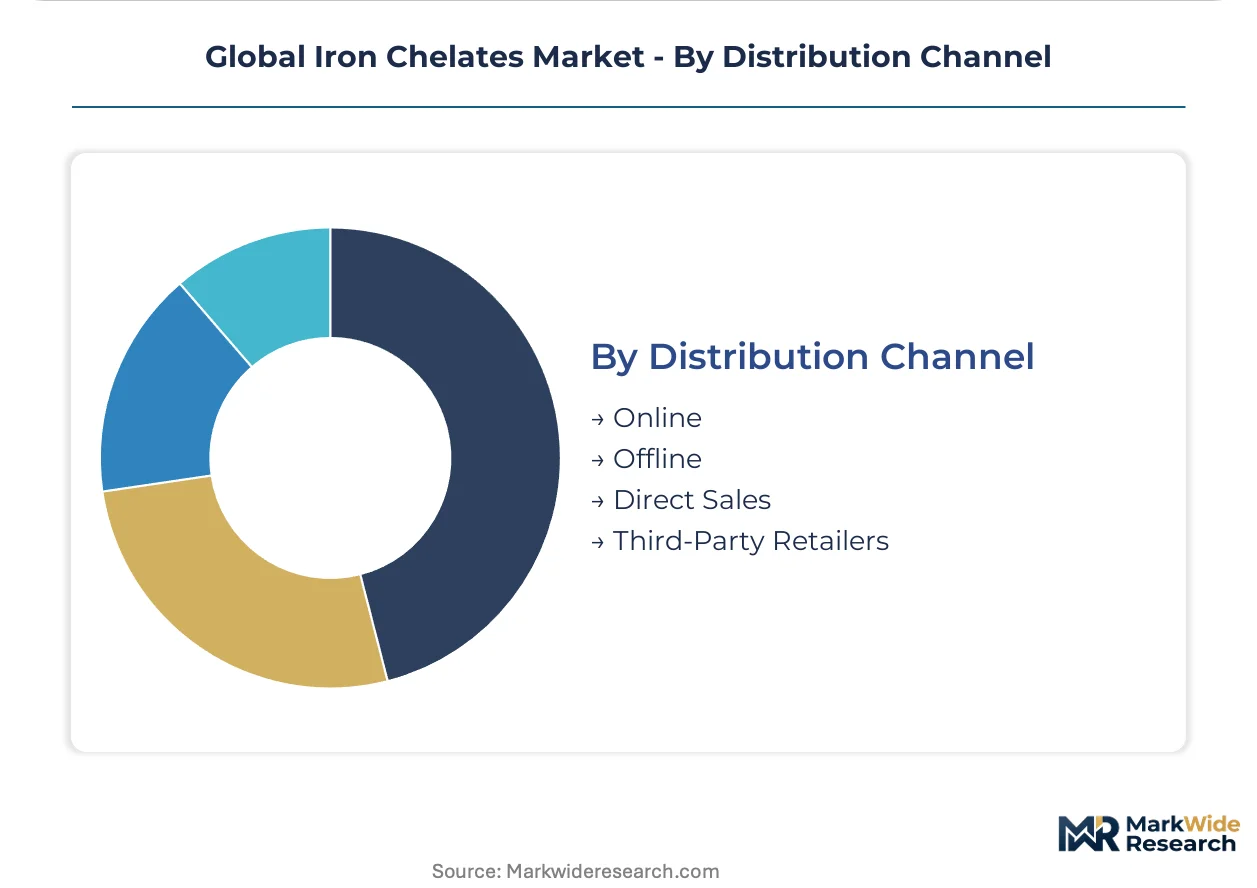
Distribution Channel:
Customer type and technical service requirements reshape channel economics, with direct relationships displacing intermediary layers where agronomic consultation adds value.
- Online:E-commerce platforms aggregate smallholder and specialty crop grower demand, particularly in India's fragmented agricultural input market.
- Offline:Dealer networks with soil testing and prescription capabilities maintain relevance where technical selling differentiates commodity from premium formulations.
- Direct Sales:Large-scale row-crop operators in Brazil and greenhouse consortia in Spain negotiate directly with manufacturers for volume commitments and custom blending.
- Third-Party Retailers:Agricultural cooperatives and garden center chains handle packaged consumer quantities with limited technical support.
Direct Sales channels are climbing the fastest; Offline dealer networks still anchor volume in established agricultural markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered synthetic chelating agent chemistry during the mid-twentieth century, establishing the technical foundation for modern agricultural and pharmaceutical iron chelate production. Industrial clusters in Ludwigshafen and Leverkusen scaled EDDHA and EDTA manufacturing to serve European calcareous soil agriculture and parenteral nutrition markets.
United States
Precision agriculture adoption in California's Central Valley and Florida's citrus belt drives foliar-applied micronutrient demand. EPA residue tolerance frameworks govern agricultural chemical registration, while FDA maintains pharmaceutical-grade specifications for parenteral nutrition applications. The Midwest corn-soybean corridor concentrates bulk blending operations that increasingly unbundle iron chelates from standard NPK packages.
Brazil
Mato Grosso's commercial soybean operations deploy drone-based spraying services that bypass traditional dealer networks for micronutrient procurement. ANVISA regulates agricultural chemical imports while state-level environmental agencies enforce application buffer zones. The Cerrado region's high-pH soils sustain premium EDDHA demand despite aggressive Iron EDTA cost competition in broad-acre field crops.
India
Punjab and Haryana wheat belts absorb subsidized chelated micronutrients through government soil health programs. FSSAI and CDSCO maintain converging purity requirements for food-grade and pharmaceutical-grade iron chelates. Dealer networks in these northern states restructure technical service capabilities to support prescription-based selling rather than commodity volume.
China
Shandong and Jiangsu provinces host phosphoric acid and chelating agent manufacturing clusters serving domestic fertilizer blenders. SAMR and MEE enforce GB standards mandating declared chelation efficiency on product labels, though provincial testing protocol divergence creates registration friction. The Yangtze River Delta concentrates pharmaceutical-grade purification capacity for export markets.
Spain
Almería's greenhouse cluster demands batch-level chelation efficiency certificates for high-value horticulture production. REACH and the EU F-Gas Regulation mandate stepped reductions in environmental release thresholds for chelating agent production residues. EDDHA stability up to pH 11 enables reliable iron availability in the region's calcareous substrate cultivation systems.
Global Iron Chelates Market Competitive Environment
Premium-margin players sit above commodity-margin players across chelation chemistry tiers, with EDDHA specialists commanding structural advantages in high-alkalinity agriculture while EDTA blenders compete on cost in pH-neutral broad-acre markets. The vendor base organizes into three strategic archetypes: backward-integrated phosphate-chemical conglomerates, biostimulant-chelate combination specialists, and regional blending operations with distribution density. Dominant competitive moves include captive phosphoric acid supply integration and precision agriculture platform partnerships that disintermediate traditional dealer layers.
Within the polymer chemistry heritage tier, BASF SE anchors premium positioning through EDDHA formulation expertise. Haifa Group exemplifies backward-integrated strategy with upstream control over phosphoric acid and potassium sources. Valagro occupies the biostimulant convergence position, combining chelate technology with organic active differentiation. These three represent distinct competitive vectors rather than overlapping market contests.
| Leading Market Players |
|---|
| Syngenta |
| Haifa Group |
| BASF SE |
| Tradecorp |
| Van Iperen International |
| Nouryon |
| Valagro |
| Aries Agro |
| Yara International |
| Others |
Value Chain & Pricing Dynamics
Captive phosphoric acid integration anchors both cost position and pricing power across the iron chelates value chain, with backward-integrated producers in Germany and China commanding structural advantages that independent blenders cannot replicate. This upstream control translates directly into margin resilience when raw material volatility compresses returns for non-integrated competitors.
Pricing Analysis
Three-tier pricing structure across premium EDDHA, standard DTPA, and economy EDTA levels stratifies the market by chelation stability and application context. Price differentiation rests on chelation efficiency certification and REACH-compliant purity grades, with EDDHA formulations commanding substantial premiums in Spain's Almería greenhouse cluster. Cost compression in EDTA agricultural grades is intensifying because Brazilian soybean operators unbundle micronutrients from NPK bundles and drive volume-based procurement. Broad-acre field crop managers exhibit the highest price sensitivity, while pharmaceutical-grade buyers prioritize batch-level purity certificates over unit cost.
Supply Chain Analysis
Freight cost differentials between liquid concentrate and dry powder formats reshape procurement patterns for Brazilian drone-spraying services and Indian dealer networks. Manufacturing concentrates in Germany, China, and Israel draws from phosphoric acid, ethylenediamine, and salicylic acid feedstocks. Single-source vulnerability in EDDHA ligand production creates concentration risk for premium horticulture supply. Distribution runs through direct manufacturer relationships with large-scale operators, supplemented by technical dealer networks in India's wheat belt and third-party retailers for smallholder segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The iron chelates market functions as a stable compounder anchored by irreversible soil alkalinization trends that expand EDDHA-addressable acreage faster than substitution technologies can displace demand.
For Market Incumbents: Anchor defensive positioning through captive phosphoric acid supply and EDDHA formulation patents that block commodity encroachment into high-value horticulture. Invest in batch-level chelation efficiency certification infrastructure to meet Spain's Almería greenhouse cluster demands. Counter drone-based distribution disintermediation in Brazil by embedding technical agronomists directly into precision agriculture platforms. For New Entrants and Emerging Players: Smallholder cooperatives in India's fragmented northern states represent the most penetrable buyer archetype currently underserved by prescription-based dealer capabilities. Target white-space opportunities in pharmaceutical-grade purification for parenteral nutrition applications where unit economics reward capability investments. Pursue biostimulant-chelate combination formulations that open differentiation pathways in specialty crop segments with limited commodity pricing pressure. For Investors and Strategic Acquirers: Consolidation pressure builds where provincial regulatory fragmentation in China multiplies compliance costs for multinational suppliers lacking local formulation assets. Frame long-term viability around soil health program permanence in India's wheat belt and calcareous soil expansion in Brazil's Cerrado. Monitor ECHA purity specification evolution as the critical inflection signal for supplier qualification pool consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphoric Acid | Captive supply of this critical feedstock insulates Haifa Group and similar producers from raw material volatility. |
| Pharmaceutical-Grade Purification Investment | Batch-level purity capability unlocks parenteral nutrition segments with substantially elevated unit economics. |
| Drone-Based Distribution Partnerships | Direct-to-grower channels in Brazil's Mato Grosso bypass traditional dealer networks and compress service margins. |
| Biostimulant-Chelate Combination Development | Valagro's organic active differentiation creates pricing power in specialty crop segments resistant to commodity pressure. |
| REACH Compliance Certification Infrastructure | Batch-level chelation efficiency certificates meet Spain's Almería greenhouse demands and disqualify legacy suppliers. |
Study Parameters
Multiple input streams — primary interviews with fertilizer blenders, phosphoric acid procurement leads, and precision agriculture platform operators, alongside secondary validation through customs data, ECHA registration databases, and SEC filings from listed chemical producers — were reconciled to construct market estimates. Bottom-up tonnage modeling across chelation chemistry tiers was cross-checked against top-down value projections derived from pricing intelligence in premium horticulture and pharmaceutical-grade segments.
Data-stream reconciliation applied analytical frameworks across the projection horizon without year-specific anchoring, modeling volume and value trajectories by chelation chemistry, end-use industry, formulation format, and regional regulatory cluster. CAGRs emerged from segment-level growth rate synthesis calibrated to soil health program permanence in India, precision agriculture adoption curves in Brazil, and REACH specification evolution timelines in Europe. Industry-specific forecast inputs included phosphoric acid cost indices and chelation efficiency testing protocol harmonization progress.
Inputs from primary stakeholder interviews and published regulatory filings were available through the study window; gaps in real-time drone-spraying service procurement data and provincial-level China enforcement patterns introduce uncertainty bands around distribution channel forecasts. Forecasts reflect assumptions regarding subsidy program continuity and ECHA specification stability. A model refresh is warranted upon material change in India's soil health program funding or EDDHA ligand patent expiration schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Iodoacetonitrile Market
Chemical Intermediates
Ph Controlling Agents Market
Chemical Intermediates
Dimethyl Dicarbonate Market
Chemical Intermediates
Metaphenoxy Benzaldehyde (MPBD) Market
Chemical Intermediates
Thioesters Market
Chemical Intermediates
Acetamide MEA Market
Chemical Intermediates
Lauoryl Chloride Market
Chemical Intermediates
Organometallic Compounds Market
Chemical Intermediates
API Intermediate Market
Chemical Intermediates
Isosafrole Market
Chemical Intermediates
Glycidyl Methacrylate Market
Chemical Intermediates
Copper Chemicals Market
Chemical Intermediates
Butadiene Derivatives Market
Chemical Intermediates
Ethylene Diamine Tetra Acetic Acid (EDTA) Market
Chemical Intermediates
Polyamide Intermediate Chemicals Market
Chemical Intermediates
Global Biochemical Reagents Market