
 Rare Earth Polishing Materials Market | 2026-2036
Rare Earth Polishing Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Rare Earth Polishing Materials Market Insights
China's Inner Mongolia processing corridor is rewriting supply availability for rare earth polishing powders. Shin-Etsu Chemical Co., Ltd. leverages captive rare earth separation to sustain oxide purity grades for semiconductor clients. Solvay S.A. competes through European-sourced cerium feedstock that navigates China's export licensing regime. Fujimi Incorporated anchors Japanese optical polishing demand with sub-micron particle control.
Rare earth polishing materials are finely milled oxide compounds, predominantly cerium oxide with particle sizes below one micrometer, formulated into aqueous slurries for chemical mechanical planarization and precision surface finishing. Cerium oxide dominates product type demand due to its selective reactivity with silicon dioxide surfaces at neutral pH. Electronics applications are outpacing optical components as wafer node shrinkage intensifies planarization cycles. Automotive OEMs represent an emerging end user segment as lidar sensor polishing requirements multiply.
China's Ministry of Commerce export licensing and REACH registration in Europe are tightening product traceability and environmental compliance for rare earth processors. The US EPA and OSHA frameworks govern particulate exposure limits in slurry formulation facilities, raising capital requirements for domestic blending operations. Japan's METI critical minerals strategy is accelerating stockpiling directives that reshape procurement timelines for Toshiba and Hitachi Chemical Co., Ltd. Stakeholders must monitor feedstock origin certification as a determinant of market access.
Market Dynamics
China's export licensing regime for rare earth concentrates is compressing feedstock availability for non-domestic processors, forcing semiconductor fabs and optical manufacturers to requalify supply chains around origin-certified oxide streams.
Growth Catalysts
- Wafer node shrinkage:Semiconductor manufacturers below 7nm are multiplying planarization cycles per wafer, consuming cerium oxide slurries at higher volumes per finished substrate.
- REACH registration:European ECHA compliance requirements are filtering out uncertified suppliers, consolidating procurement toward traceable feedstock handlers with documented environmental credentials.
- Lidar sensor proliferation:Automotive OEMs are adding polishing steps for precision optical components in autonomous driving systems, creating incremental demand outside traditional electronics.
Market Restraints
- Feedstock concentration:China's Inner Mongolia corridor controls over 80% of light rare earth separation capacity, exposing non-Chinese processors to licensing delays and quota volatility.
- Substitution limits:Alumina and silica-based slurries lack cerium oxide's selective reactivity with silicon dioxide at neutral pH, preventing direct material swaps in semiconductor planarization.
- Capital intensity:Sub-micron particle classification equipment and cleanroom blending facilities require eight-figure USD investments, elevating barriers for new entrants.
Strategic Opportunities
- European feedstock diversification:Solvay's European-sourced cerium streams demonstrate viable pathways to bypass China's licensing regime for critical semiconductor supply chains.
- Stockpiling mandates:Japan's METI critical minerals strategy is creating forward procurement programs that extend contract durations and stabilize pricing for qualified suppliers.
- Slurry recycling systems:Closed-loop filtration and oxide recovery technologies are emerging as service differentiators for fabs seeking to reduce hazardous waste disposal costs under EPA frameworks.
Industry Challenges
- Particle size control expertise:Maintaining sub-micron distribution consistency across batch scales requires specialized process engineers, creating talent scarcity in non-traditional rare earth processing regions.
- Dual certification timelines:Simultaneous EPA particulate exposure compliance and REACH registration can extend product qualification cycles by 18-24 months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rare Earth Polishing Materials Market |
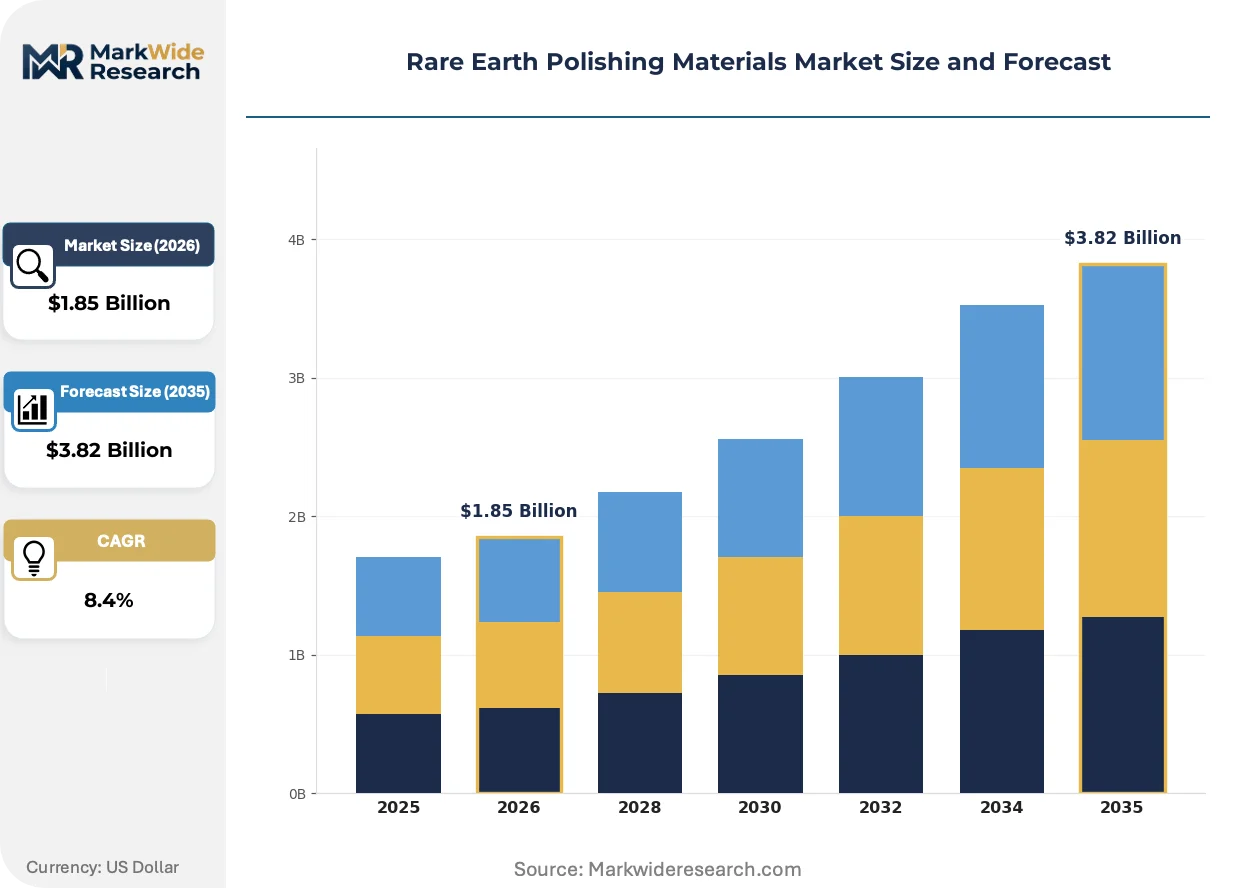
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Oxide, Cerium Oxide, Silicon Dioxide, Zinc Oxide Application: Optical Components, Electronics, Aerospace, Automotive End User: Manufacturers, Research Institutions, Automotive OEMs, Electronics Firms Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Shin-Etsu Chemical Co., Ltd., Solvay S.A., Fujimi Incorporated, Saint-Gobain Ceramics & Plastics, Inc., Showa Denko K.K., 3M Company, Cabot Microelectronics Corporation, Tosoh Corporation, Hitachi Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rare Earth Polishing Materials Market Trends and Innovations
Digital twin technologies are virtualizing slurry formulation workflows, compressing R&D cycles and enabling remote process optimization across geographically dispersed blending facilities.
Cerium oxide nanoparticle synthesis is virtualizing traditional mechanical milling approaches, enabling tighter particle size distributions through chemical precipitation methods. Taiwan Semiconductor Manufacturing Company and Samsung Electronics are qualifying these chemically synthesized slurries for advanced node planarization. The technology is virtualizing capital equipment requirements, allowing smaller batch producers to achieve purity grades previously reserved for integrated mining-chemical conglomerates.
China's Ministry of Commerce export licensing framework is tightening traceability documentation for every kilogram of rare earth concentrate leaving domestic processors. Non-Chinese slurry blenders must now maintain chain-of-custody records spanning mine site to final formulation. Semiconductor fabs in South Korea and Japan are responding by embedding origin certification clauses into multi-year supply agreements.
Consolidated procurement through direct mill relationships is displacing distributor-mediated spot purchasing for high-volume semiconductor clients. Tier-one fabs are negotiating take-or-pay contracts with integrated rare earth-chemical processors, locking in oxide allocation years ahead of delivery. This behavioral shift is most pronounced in Taiwan's Hsinchu Science Park, where foundries have centralized slurry procurement under strategic materials committees.
Rare Earth Polishing Materials Market Segmentation
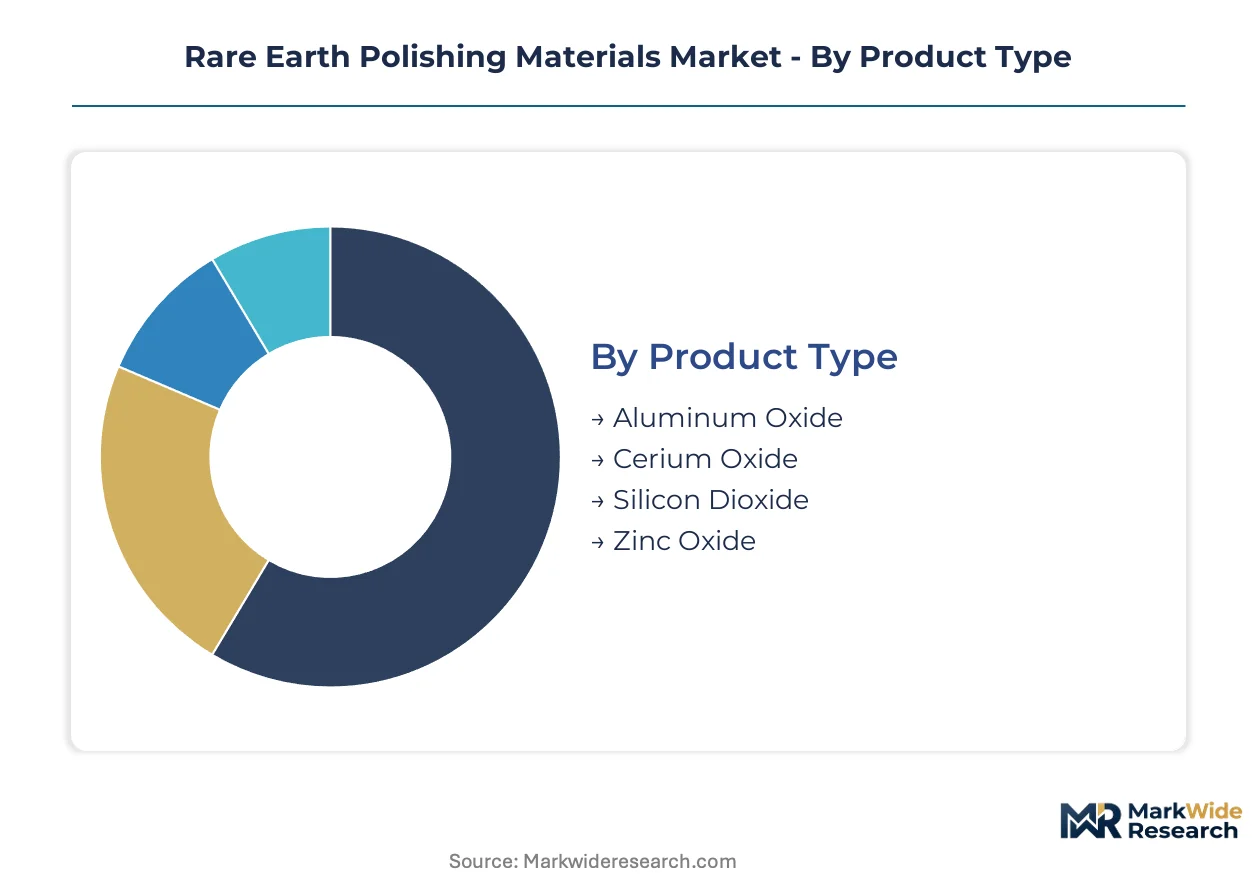
Rare earth polishing materials exhibit distinct performance profiles across product chemistries, creating divergent service requirements and procurement patterns. Semiconductor fabs in Taiwan and South Korea demand sub-micron consistency that drives long-term supplier relationships. Optical manufacturers in Japan prioritize particle distribution stability over volume scale, fragmenting purchasing behavior across end-use segments.
Product Type:
After-sales service intensity varies sharply by oxide chemistry, with cerium oxide formulations requiring continuous technical support for pH stabilization and shelf-life management.
- Cerium Oxide:Chemically synthesized or mechanically milled rare earth oxide with selective reactivity against silicon dioxide surfaces at neutral pH. Taiwan Semiconductor Manufacturing Company and Samsung Electronics consume the highest volumes for advanced node planarization, where batch-to-batch consistency determines yield rates. REACH registration requirements in Europe filter procurement toward handlers with documented environmental credentials.
- Aluminum Oxide:Harder abrasive compound with broader particle size distributions, suited for aggressive material removal in optical glass edging. German precision optics manufacturers in Jena and Wetzlar represent concentrated demand, though substitution pressure from cerium oxide limits growth in semiconductor-adjacent applications.
- Silicon Dioxide:Softer abrasive with lower removal rates, deployed in final polishing stages where surface roughness specifications are tightest. Fujimi Incorporated anchors Japanese demand through proprietary colloidal formulations.
- Zinc Oxide:Niche ultraviolet-absorbing variant for specialized optical coatings, with limited penetration outside research-grade applications.
Cerium oxide holds the largest share; momentum sits with chemically synthesized nanoparticle grades displacing traditional mechanical milling.
Application:
Application segmentation tracks directly to surface finish specifications, with electronics demanding atomic-scale planarization that optical components rarely require.
- Electronics:Chemical mechanical planarization for silicon wafers, compound semiconductors, and display glass. South Korean memory fabs and Taiwanese foundries multiply slurry consumption per wafer as nodes shrink below 7nm, creating the steepest expansion trajectory across all application categories.
- Optical Components:Lens polishing for cameras, microscopes, and laser systems. Hoya Corporation and Canon in Japan maintain captive blending operations for proprietary lens finishing recipes.
- Automotive:Emerging lidar sensor polishing requirements as autonomous driving systems proliferate. German automotive OEMs in Stuttgart and Munich are qualifying cerium oxide slurries for precision optical housing finishes.
- Aerospace:Specialized infrared window and mirror polishing for satellite and aircraft applications, with procurement concentrated through defense contractors in France and the United States.
Electronics commands the dominant revenue position; automotive lidar applications are climbing the fastest as sensor volumes scale.
End User:
End user type determines contract structure, with manufacturers locking in multi-year supply agreements while research institutions purchase spot quantities.
- Electronics Firms:Integrated device manufacturers and foundries with centralized procurement committees. Taiwan's Hsinchu Science Park has shifted toward direct mill relationships, displacing distributor-mediated purchasing for high-volume clients.
- Manufacturers:Precision optics and industrial glass producers with formulation expertise in-house. Schott AG in Germany and Corning in the United States qualify multiple slurry sources to mitigate concentration risk.
- Automotive OEMs:Tier-one suppliers and original equipment manufacturers qualifying polishing materials for emerging sensor applications. Japan's METI stockpiling directives are extending contract durations for qualified suppliers.
- Research Institutions:Universities and national laboratories testing novel oxide formulations, with procurement fragmented across small-batch distributors.
Electronics firms represent the deepest procurement relationships; automotive OEMs are gaining share fastest as lidar polishing requirements formalize.
Distribution Channel:
Channel selection reflects customer scale and technical support requirements, with direct sales dominating semiconductor accounts and distributors serving fragmented optical manufacturers.
- Direct Sales:Integrated rare earth-chemical processors negotiating take-or-pay contracts with tier-one fabs. Shin-Etsu Chemical and Solvay deploy technical service teams at customer sites for formulation optimization.
- Distributors:Regional specialists holding inventory for mid-volume optical and glass manufacturers. Japanese distributors maintain close ties to domestic polishing powder blenders.
- Wholesalers:Bulk oxide handlers supplying commodity grades to industrial glass and ceramics producers with less stringent particle size requirements.
- Online Retail:Limited to research-grade quantities and standardized formulations, with minimal penetration in semiconductor-qualified materials.
Direct sales capture the highest value segment; distributors retain relevance in geographically fragmented optical supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao-Dalian maritime corridor funnels Inner Mongolia's rare earth concentrates to East Asian semiconductor fabs. This logistics backbone concentrates polishing material flows through a handful of port nodes.
China
Inner Mongolia's Baotou processing complex supplies over four-fifths of global light rare earth separation capacity. The Ministry of Commerce export licensing framework now mandates chain-of-custody documentation for every concentrate shipment. Tianjin Port handles the bulk of cerium oxide outbound movement to South Korean and Japanese blenders.
Japan
Tokyo's METI critical minerals strategy directs stockpiling mandates that extend procurement contract durations to three-to-five year terms. The Kanto region's precision optics manufacturers in Saitama and Ibaraki prefectures consume sub-micron cerium formulations for lens finishing. Osaka-based chemical blenders qualify multiple feedstock sources to mitigate concentration risk from Chinese supply.
South Korea
Memory fabs in Icheon and Pyeongtaek multiply planarization cycles per wafer as process nodes shrink below seven nanometers. The central bank's foreign exchange reserves now include rare earth concentrate purchasing facilities. Busan Port's bonded warehousing infrastructure supports just-in-time slurry delivery to the Gyeonggi semiconductor cluster.
Taiwan
Hsinchu Science Park foundries have displaced distributor-mediated purchasing with direct mill relationships under strategic materials committees. The National Development Council subsidizes slurry recycling system deployments to reduce hazardous waste disposal costs. Taichung's precision machinery corridor supplies sub-micron particle classification equipment to domestic blenders.
United States
EPA particulate exposure limits under OSHA frameworks elevate capital requirements for domestic slurry formulation facilities. The Mountain Pass mine in California ships concentrates to Estonian separation plants to circumvent Chinese licensing delays. Arizona's emerging semiconductor fabs in Phoenix-Tempe are qualifying non-Chinese oxide streams for advanced node production.
Rare Earth Polishing Materials Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in feedstock and formulation. The vendor base organizes around three archetypes: integrated mining-chemical conglomerates with captive separation capacity; regional blenders sourcing oxide through distributor networks; and specialized nanoparticle synthesis houses. Consolidation pressures favor players with backward integration into rare earth concentrate supply. Competitive positioning hinges on REACH registration completion and EPA compliance certification rather than price alone.
Among Japanese chemical conglomerates, Shin-Etsu Chemical Co., Ltd. and Fujimi Incorporated occupy positions defined by sub-micron particle control expertise. Solvay S.A. represents the European-sourced alternative archetype, demonstrating viable pathways to bypass Chinese export licensing through non-Asian feedstock streams. These three exemplify how geographic diversification in raw material procurement now determines market access more than formulation technology.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co., Ltd. |
| Solvay S.A. |
| Fujimi Incorporated |
| Saint-Gobain Ceramics & Plastics, Inc. |
| Showa Denko K.K. |
| 3M Company |
| Cabot Microelectronics Corporation |
| Tosoh Corporation |
| Hitachi Chemical Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in European cerium separation facilities is compressing spot oxide availability and forcing semiconductor blenders toward multi-year offtake commitments at fixed premiums. This utilization squeeze simultaneously elevates supplier bargaining power and accelerates procurement centralization among fabs with balance-sheet capacity to pre-pay.
Pricing Analysis
Volume-discount tiering structures dominate procurement, with semiconductor fabs capturing 15-25% unit cost reductions at annual volumes exceeding 500 metric tons. Price differentiation hinges on REACH registration completion and sub-micron particle consistency certification. Pricing pressure stems from China's export licensing delays that extend lead times for non-captive processors. Research institutions exhibit highest price sensitivity due to fragmented small-batch purchasing, while Taiwanese foundries prioritize supply security over unit economics.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for oxide blenders serving Arizona's emerging semiconductor cluster. Geographic supply concentrates in China's Inner Mongolia corridor, South Korea's Busan bonded warehousing zone, and Japan's Kanto chemical processing belt. Raw material dependencies span rare earth concentrate from Bayan Obo mines, hydrochloric acid for separation chemistry, and deionized water for slurry formulation. Distribution runs through direct mill relationships displacing distributor networks for high-volume electronics clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as automotive lidar sensor polishing requirements formalize qualification protocols previously confined to semiconductor applications. Penetration tailwinds from sub-7nm node shrinkage multiply planarization cycles per wafer beyond historical consumption curves.
For Market Incumbents: Insulate oxide allocation through backward integration into rare earth concentrate offtake agreements with Australian and Canadian mining projects. Prioritize EPA particulate exposure compliance certification to capture Arizona fab demand as US-based production scales. Cerium oxide substitution attempts by alumina slurry developers represent the primary technology threat requiring continuous R&D monitoring.
For New Entrants and Emerging Players: Build out nanoparticle synthesis capabilities to serve mid-tier optical manufacturers bypassed by integrated conglomerates focused on semiconductor volumes. Automotive lidar polishing in Stuttgart and Munich represents the most penetrable white-space segment with formalizing specifications and limited qualified suppliers. A technical service partnership model with regional distributors accelerates qualification timelines without capital-intensive direct sales infrastructure.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated rare earth-chemical processors with captive separation capacity and multi-year foundry contracts. Long-term viability over a 5-10 year window favors handlers with documented chain-of-custody systems compliant with China's export licensing framework. The signal to watch is Japan's METI stockpiling directive expansion beyond current critical minerals lists to include polishing-grade cerium oxide.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Concentrate Supply | Captive feedstock from Australian mines bypasses China's Ministry of Commerce licensing delays for non-domestic processors. |
| REACH Registration Completion | ECHA compliance documentation filters European procurement toward handlers with verified environmental credentials and traceable supply chains. |
| Nanoparticle Synthesis Technology Deployment | Chemical precipitation methods enable tighter particle distributions previously achievable only through capital-intensive mechanical milling infrastructure. |
| Slurry Recycling System Implementation | Closed-loop filtration reduces hazardous waste disposal costs under EPA frameworks while creating service differentiation for fabs. |
| Direct Mill Relationship Establishment | Take-or-pay contracts with tier-one foundries lock in oxide allocation years ahead of delivery, displacing distributor-mediated spot purchasing. |
Research Methodology
A spread of perspectives from semiconductor fab procurement directors, rare earth separation plant managers, optical manufacturer R&D heads, and slurry formulation chemists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC filings of listed chemical processors, customs trade data tracking concentrate flows through Tianjin and Busan ports, and ECHA REACH registration databases. Bottom-up demand modeling from individual fab consumption rates triangulated against top-down rare earth oxide production estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeling across product chemistry, application end-use, and regional production hub. CAGRs were derived from weighted average growth assumptions applied to base-year consumption estimates. Industry-specific forecast inputs included wafer node transition timelines from foundry capital expenditure disclosures and automotive lidar sensor shipment projections from Tier 1 supplier qualification schedules.
Practitioners should monitor China's export licensing quota announcements and EPA particulate exposure rulemakings for early signals requiring forecast reassessment. Forecasts reflect assumptions regarding continued semiconductor node shrinkage and formalization of automotive optical polishing standards. Material shifts in rare earth concentrate trade policy or substitution breakthroughs in alumina-based planarization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
RDP Powder Market
Abrasives
Tile Abrasion Testing Market
Abrasives
Carbide Grinding Wheel Market
Abrasives
Abrasive Blasting Nozzle Market
Abrasives
Polishing Powder Market
Abrasives
Surface Conditioning Wheels Market
Abrasives
Asia-Pacific Abrasives Market
Abrasives
Glass Abrasives Market
Abrasives
Abrasive Cloth Market
Abrasives
Global Rubber Bonded Abrasive Market
Abrasives
Abrasive Grains Market
Abrasives
Tungsten Carbide Balls Market
Abrasives
New Zealand Abrasives Market
Abrasives
Tungsten Carbide Band Saw Blade Market
Abrasives
Non-Woven Abrasives Market
Abrasives
Abrasive Base Paper Market