
 Banking Credit Analytics Market | 2026-2036
Banking Credit Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Banking Credit Analytics Market Analysis
Asset-light SaaS delivery models are reconfiguring competitive dynamics in banking credit analytics, lowering capital barriers for mid-tier vendors. Moody's Analytics leverages its proprietary sovereign risk databases to anchor enterprise relationships. FICO sustains pricing power through its dominance of bureau-agnostic scoring algorithms. Experian differentiates via real-time alternative data ingestion capabilities.
Banking credit analytics encompasses statistical modeling, machine learning algorithms, and data infrastructure used to quantify borrower default probability, loss given default, and exposure at default for lending decisions. These systems process structured credit bureau files alongside unstructured behavioral signals to generate regulatory-compliant risk capital estimates. Cloud-based deployment now leads growth as retail banks and credit unions migrate core risk systems away from on-premises mainframes. Risk assessment and credit scoring together capture the deepest margin pools, while fraud detection segments expand fastest as real-time transaction monitoring becomes mandatory.
Basel III frameworks in the United States, the EU's Capital Requirements Regulation, and India's RBI prudential norms collectively elevate demand for auditable, transparent credit models. The SEC's climate disclosure rules and the EU's CSRD now extend credit analytics into transition risk quantification for corporate loan books. Stakeholders must decide whether to build in-house model governance infrastructure or embed vendor-managed compliance layers as regulatory granularity intensifies.
Market Dynamics
Cloud-native migration is compressing deployment cycles from 18 months to 6 weeks, forcing incumbent vendors to dismantle monolithic architectures while fintech challengers scale without legacy technical debt. This structural velocity advantage is redistributing procurement power toward mid-tier banks and credit unions.
Growth Catalysts
- Basel III Finalization:US Federal Reserve implementation of output floor requirements is mandating granular probability-of-default models across all material portfolios.
- Alternative Data Proliferation:Utility payment histories and behavioral biometrics are expanding scoring coverage to thin-file borrowers previously excluded from formal credit.
- India Stack Integration:Account Aggregator framework enables consent-based financial data sharing, accelerating real-time credit decisioning for retail and MSME segments.
Market Restraints
- Model Risk Management Costs:SR 11-7 supervisory guidance requires independent validation teams, adding 15-20% overhead to implementation budgets.
- Cloud Concentration Risk:Three hyperscale providers dominate banking-grade infrastructure, creating systemic dependency for critical risk systems.
- Explainability Constraints:Deep learning architectures face rejection by model governance committees due to black-box opacity under regulatory scrutiny.
Strategic Opportunities
- Climate Risk Quantification:EU CSRD disclosure mandates are extending credit analytics into transition risk modeling for carbon-intensive corporate exposures.
- Embedded Finance Convergence:BNPL providers and vertical SaaS platforms require white-labeled scoring APIs, opening distribution beyond traditional banking channels.
- Synthetic Data Generation:Privacy-preserving simulation techniques are enabling model development without raw PII access, unlocking cross-border data collaboration.
Industry Challenges
- Quantitative Talent Scarcity:PhD-level expertise in causal inference and adversarial robustness commands premium compensation, constraining vendor scaling.
- Legacy Core Integration:COBOL-based loan origination systems require expensive middleware layers to consume modern API-first scoring engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Banking Credit Analytics Market |
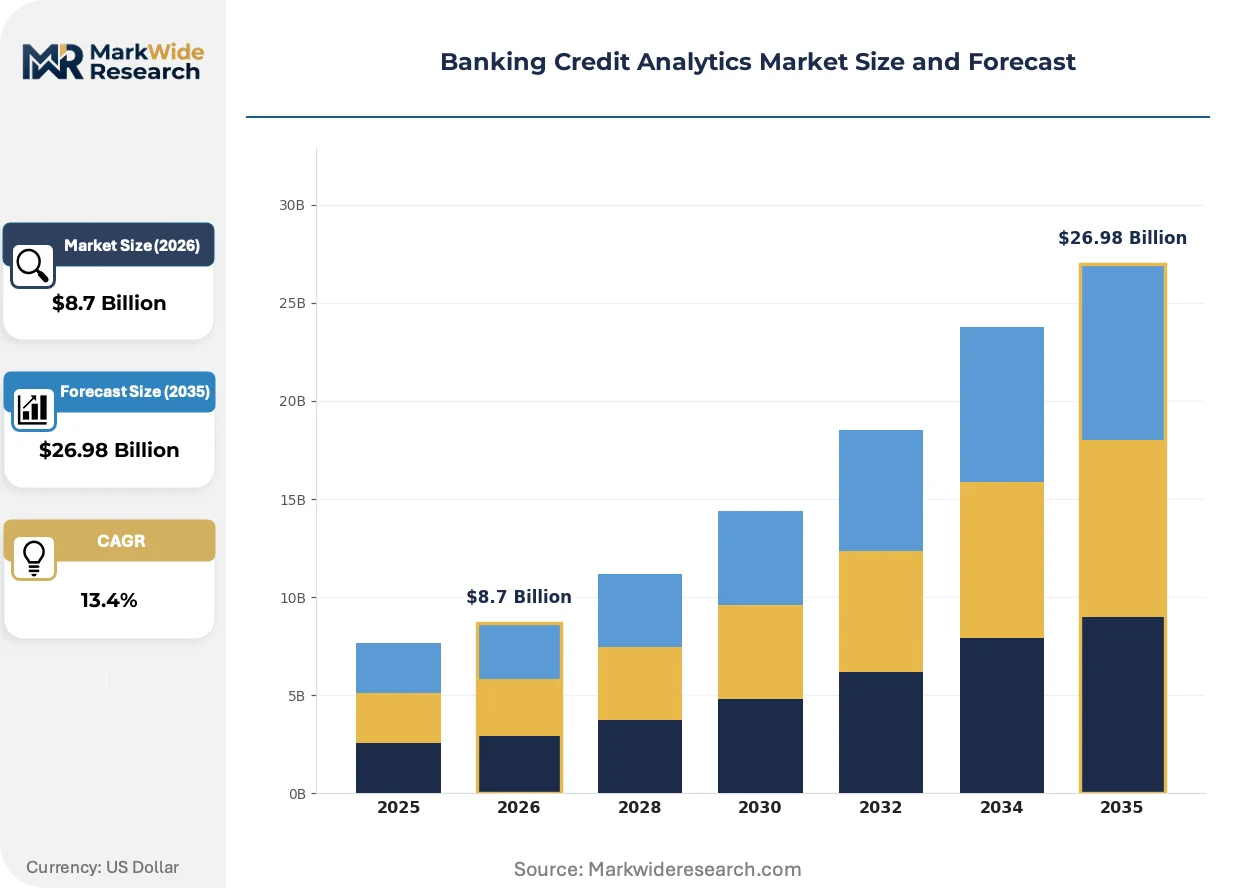
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Analysis Type: Risk Assessment, Credit Scoring, Fraud Detection, Portfolio Management Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Retail Banks, Credit Unions, Investment Banks, Private Equity Service Type: Consulting, Implementation, Support, Training |
| Companies Covered | Moody's Analytics, Experian, Fiserv, Equifax, TransUnion, Finastra, S&P Global, Bloom Credit, FICO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Banking Credit Analytics Market Emerging Trajectories
Real-time inference architectures are displacing batch processing as the default paradigm, compressing decision latency from days to milliseconds. This shift is redefining competitive advantage around data velocity rather than model sophistication alone.
Federated learning is digitizing multi-party model training without centralizing sensitive borrower data. Consortiums of regional banks in Germany are pooling gradient updates while keeping raw records within national borders. This architecture is compressing compliance costs for cross-border credit operations while preserving data sovereignty requirements.
The EU AI Act risk-classification framework is forcing recalibration of automated lending algorithms across the 27 member states. High-risk system designations now trigger conformity assessment obligations, mandatory human oversight protocols, and post-market monitoring requirements. Retail credit scoring engines face the most intensive scrutiny, with vendors restructuring product roadmaps to embed explainability-by-design.
Subscription-based procurement is displacing perpetual license arrangements as credit unions and community banks seek operational expenditure flexibility. Tier-2 institutions in the United States are consolidating vendor relationships around platform solutions that bundle scoring, monitoring, and regulatory reporting. This concentration is visible most acutely in the Southeast and Midwest regions where IT headcount constraints favor managed service models.
Banking Credit Analytics Market Segmentation
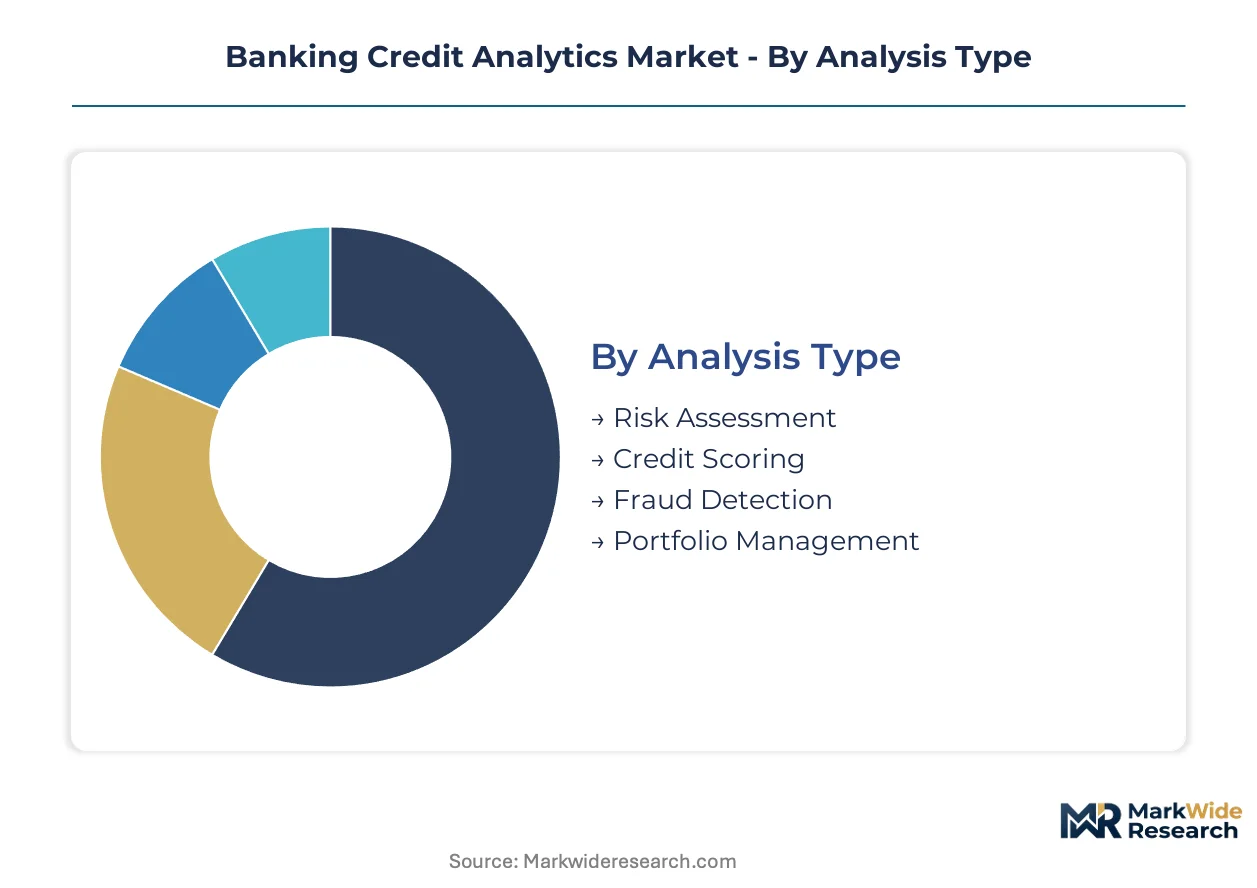
Segmentation in banking credit analytics reveals divergent procurement rhythms across deployment modes and user sophistication. Credit scoring platforms refresh algorithms quarterly while fraud detection systems require continuous model retraining. Understanding these cycle-time differentials shapes vendor resource allocation and partnership structuring.
Analysis Type:
Risk assessment models turn over slowest due to regulatory lock-in periods, while fraud detection engines cycle fastest as attack vectors mutate weekly.
- Risk Assessment:Probability-of-default and loss-given-default calculations form the regulatory backbone for Basel III capital adequacy compliance. United States commercial banks concentrate procurement here as Federal Reserve output floor requirements tighten. Model validation overhead stretches implementation timelines to 18 months.
- Credit Scoring:Bureau-agnostic algorithms and alternative data ingestion power real-time lending decisions for thin-file borrowers. Germany's regional banks drive demand expansion through consortium-based federated learning deployments. Explainability mandates under EU AI Act reshape product architecture.
- Fraud Detection:Real-time transaction monitoring with behavioral biometrics and anomaly detection. Indian digital lenders prioritize this segment following Account Aggregator framework rollout.
- Portfolio Management:Concentration risk analytics and stress testing for corporate loan books. Climate transition risk quantification gains traction among EU institutions facing CSRD disclosure mandates.
Risk assessment dominates installed base. Fraud detection is where expansion concentrates.
Deployment Model:
Cost tier stratification separates capital-intensive on-premises builds from operational expenditure-friendly SaaS arrangements.
- On-Premises:Legacy mainframe architectures persist among tier-1 banks with dedicated data center footprints and specialized hardware requirements. Regulatory data residency mandates in Switzerland and Saudi Arabia sustain niche demand despite cloud migration pressure.
- Cloud-Based:Hyperscale infrastructure delivers elastic compute for Monte Carlo simulations and machine learning training pipelines. United States credit unions in the Southeast and Midwest favor this model to circumvent IT headcount constraints.
- Hybrid:Sensitive borrower data remains on-premises while compute-intensive scoring runs in cloud burst configurations. German savings banks deploy this architecture to satisfy data sovereignty requirements.
- SaaS:Subscription pricing with embedded model governance and regulatory reporting modules. India's MSME-focused lenders adopt white-labeled scoring APIs through this delivery mode.
On-premises retains the largest legacy footprint. Cloud-based deployments are climbing the fastest.
End User:
Customer type determines solution complexity, with investment banks demanding bespoke quant infrastructure and retail banks prioritizing standardized platforms.
- Retail Banks:High-volume consumer lending drives demand for automated decision engines with sub-second inference latency. United States regional banks consolidate vendor relationships around bundled scoring and monitoring solutions.
- Credit Unions:Member-owned structures favor managed service models with operational expenditure flexibility. Community banks in the American Midwest exhibit similar procurement patterns.
- Investment Banks:Structured credit and derivatives exposure require Monte Carlo-based counterparty risk engines. London and New York trading floors concentrate specialized vendor relationships.
- Private Equity:Portfolio company monitoring and leveraged lending due diligence create demand for cash flow forecasting tools. Due diligence automation for mid-market buyouts expands fastest.
Retail banks anchor volume demand. Private equity represents the steepest expansion trajectory.
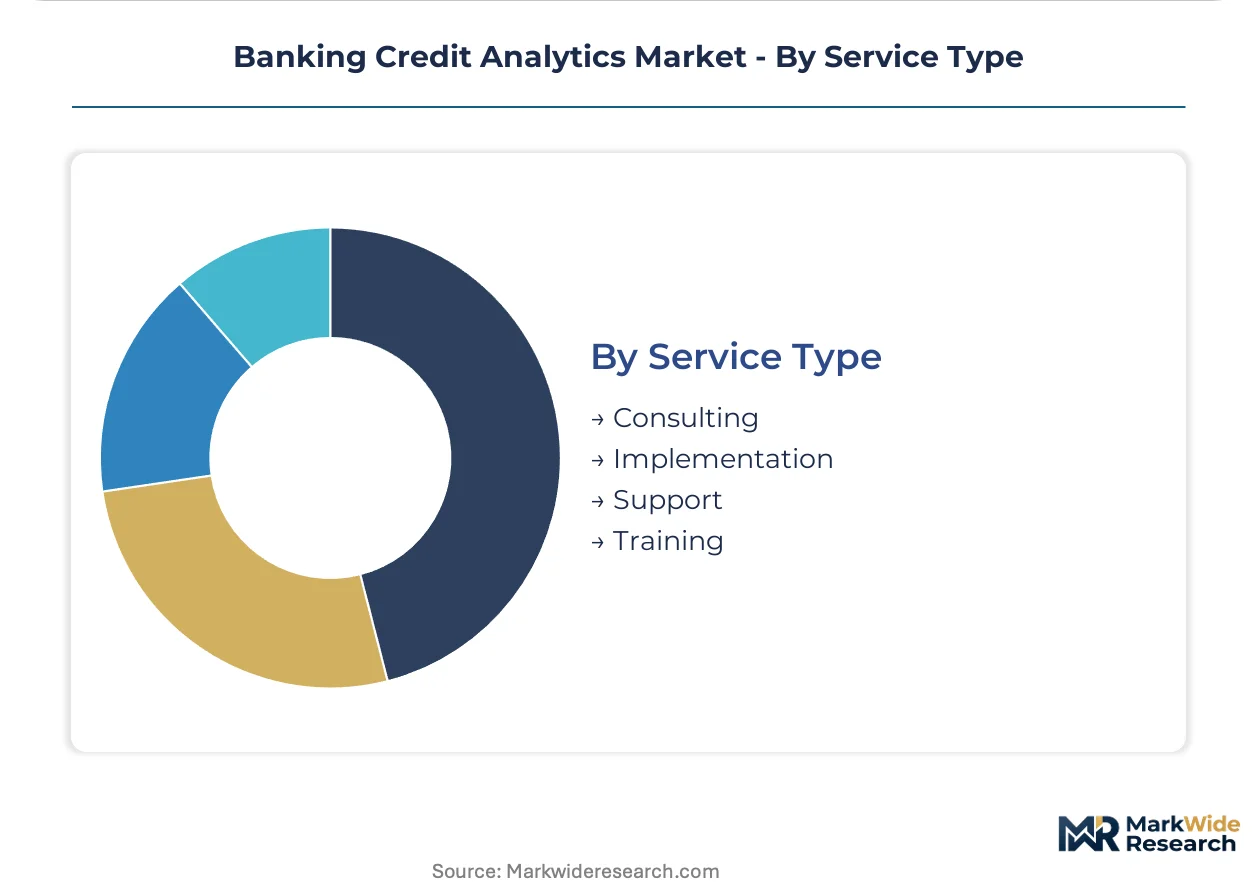
Service Type:
Margin concentration follows implementation complexity, with consulting commanding premium pricing and support generating recurring revenue.
- Consulting:Model development, validation, and regulatory interpretation for Basel III and climate risk frameworks. PhD-level quantitative expertise scarcity sustains rate premiums.
- Implementation:System integration with legacy COBOL-based loan origination platforms and middleware deployment. India's digital lenders drive volume as legacy modernization accelerates.
- Support:Ongoing model monitoring, recalibration, and regulatory audit preparation. Tier-2 institutions in Germany favor outsourced validation to circumvent talent constraints.
- Training:Model risk management education and vendor platform certification programs. United States community banks invest here to satisfy SR 11-7 supervisory guidance requirements.
Support services dominate recurring revenue. Consulting captures the deepest margin pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net technology exports from the United States and Germany offset import dependence on Indian software services and Chinese data infrastructure. Capital flows concentrate where regulatory mandates for Basel III compliance intersect with cloud-native modernization budgets.
United States
Commercial banks drive demand for probability-of-default models as Federal Reserve output floor requirements tighten. SEC climate disclosure rules extend analytics into transition risk quantification for corporate loan books. New York and Chicago trading floors anchor specialized vendor relationships for structured credit exposure.
Germany
Regional savings banks deploy federated learning architectures to pool model training without centralizing borrower data. EU AI Act risk-classification mandates force recalibration of automated lending algorithms with explainability-by-design requirements. Frankfurt and Munich clusters concentrate compliance-focused implementation services.
India
Digital lenders prioritize real-time credit decisioning following RBI Account Aggregator framework rollout. MSME-focused institutions adopt white-labeled scoring APIs through subscription delivery models. Mumbai and Bangalore fintech corridors accelerate cloud-native platform adoption for thin-file borrower segments.
United Kingdom
Open Banking regulations mandate standardized data sharing APIs, compressing decision latency for retail lending operations. Prudential Regulation Authority capital adequacy rules sustain demand for auditable risk capital estimation. London's Square Mile concentrates investment bank procurement for counterparty risk engines.
Japan
Regional banks modernize legacy mainframe architectures through hybrid cloud burst configurations for compute-intensive scoring. METI guidelines on AI governance shape model risk management protocols for automated underwriting. Tokyo and Osaka financial districts lead consortium-based data collaboration initiatives.
Banking Credit Analytics Market Vendor Landscape
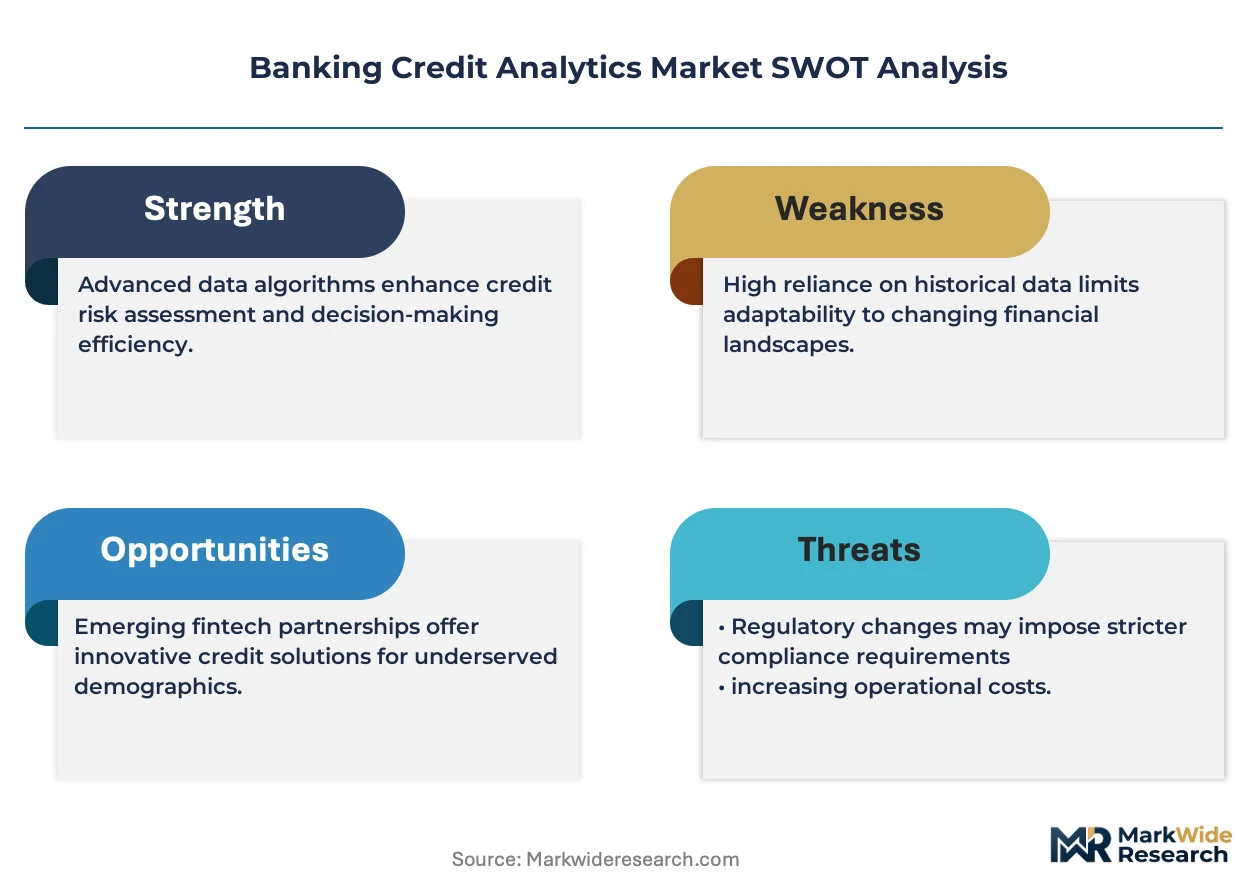
On the supply side, the industry is consolidating around platform bundling as mid-tier vendors capture procurement power from cloud migration. Incumbent vendors dismantle monolithic architectures while fintech challengers scale without legacy technical debt. Three strategic archetypes dominate: credit bureau incumbents with proprietary data moats, SaaS-native challengers with API-first delivery, and consulting-anchored validators with regulatory interpretation expertise. Competitive moves concentrate on strategic partnerships for alternative data access and vertical integration into model governance layers.
Within the credit bureau archetype, Moody's Analytics, Experian, and FICO occupy positions defined by data asset differentiation. Moody's Analytics exemplifies the sovereign risk database anchor. Experian represents real-time alternative data ingestion capabilities. FICO anchors bureau-agnostic algorithmic scoring dominance.
| Leading Market Players |
|---|
| Moody's Analytics |
| Experian |
| Fiserv |
| Equifax |
| TransUnion |
| Finastra |
| S&P Global |
| Bloom Credit |
| FICO |
| Others |
Supply Flow & Price Mechanics
Cloud concentration risk across three hyperscale providers determines both pricing tier spreads and supply chain shape in banking credit analytics. Regulatory data residency mandates in Switzerland and Saudi Arabia sustain premium on-premises pricing while cloud-native SaaS tiers compress margins through operational expenditure flexibility.
Pricing Analysis
Tier-1 commercial banks anchor three-tier pricing structure across premium, standard, and economy levels. Premium tiers bundle embedded model governance and regulatory reporting modules; standard tiers offer bureau-agnostic scoring algorithms; economy tiers deliver white-labeled API access for embedded finance providers. Price differentiation rests on certification grade for Basel III compliance and volume scale of loan originations. Cost compression in standard tiers is intensifying because mid-tier vendors scale without legacy technical debt. Credit unions in the American Midwest exhibit highest price sensitivity; investment banks in London and New York show lowest sensitivity due to bespoke quant infrastructure requirements.
Supply Chain Analysis
Amazon Web Services, Microsoft Azure, and Google Cloud Platform hold dominant capacity for banking-grade infrastructure. Geographic supply concentrates in the United States, Germany, and India where regulatory mandates intersect with cloud-native modernization budgets. Raw material dependencies include proprietary sovereign risk databases, alternative data ingestion pipelines, and federated learning coordination layers. Single-source vulnerability runs through hyperscale provider concentration for critical risk systems. Distribution runs through direct enterprise sales for tier-1 banks and channel partnerships for regional credit unions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Banking credit analytics functions as a defensive-moat market where regulatory entrenchment creates structural switching costs. Incumbents leverage model validation lock-in periods and compliance certification cycles to cement enterprise relationships.
For Market Incumbents: Build data network effects by deepening alternative data partnerships and federated learning consortium participation. Incumbents should consolidate model governance layers to capture regulatory interpretation revenue as EU AI Act conformity assessments intensify. Threat from SaaS-native challengers demands dismantling monolithic architectures for API-first delivery. Capacity addition in India's fintech corridors captures Account Aggregator framework rollout momentum.
For New Entrants and Emerging Players: Southeast Asia's thin-file credit markets offer underpenetrated white-space for real-time scoring APIs. New entrants should target MSME-focused lenders in Indonesia and Vietnam with consent-based data sharing architectures. White-labeled embedded finance scoring for BNPL providers opens distribution beyond traditional banking channels. Go-to-market angle: privacy-preserving synthetic data generation for cross-border model collaboration without raw PII access.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform bundling specialists with regulatory interpretation expertise. Long-term viability centers on vendors embedding compliance layers as regulatory granularity intensifies across jurisdictions. Acquisition target archetype: consulting-anchored validators with PhD-level quantitative talent and existing Basel III validation relationships. Signal to watch: tier-2 institution procurement consolidation around bundled scoring and monitoring solutions in the American Southeast and Midwest.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Bundling scoring, monitoring, and regulatory reporting captures tier-2 institution procurement consolidation. |
| Strategic Partnership | Alternative data access agreements with utility providers and telecom operators expand thin-file coverage. |
| Acquisition of Specialist Firm | Consulting-anchored validators with SR 11-7 expertise command premium pricing in model risk management. |
| Geographic Expansion | India's Account Aggregator framework and MSME lending acceleration create cloud-native platform demand. |
| Product Launch | Explainability-by-design scoring engines satisfy EU AI Act high-risk system conformity obligations. |
Methodological Framework
The analysis maps risk assessment algorithms, credit scoring platforms, fraud detection engines, and portfolio management tools, each validated through chief risk officers, model validation directors, regulatory affairs leads, and fintech product managers. Primary interviews with these stakeholders combined with secondary validation against SEC filings, ECB supervisory guidance documents, RBI prudential norms, and Basel Committee technical standards. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against capital expenditure disclosures from major commercial banks anchored volume estimates.
Assumptions held fixed include regulatory implementation timelines for Basel III output floors and EU AI Act risk classifications; variables included cloud migration velocity and alternative data ingestion adoption rates. The analytical framework modeled deployment model, end user sophistication tier, analysis type cycle time, and regional regulatory cluster across the projection horizon. CAGRs derived from elastic compute demand curves and SaaS pricing elasticity estimates. Industry-specific inputs encompassed Monte Carlo simulation throughput requirements and federated learning consortium participation rates.
Practitioners should monitor Federal Reserve output floor implementation delays, EU AI Act enforcement granularity, and hyperscale provider service continuity events for early signals of forecast revision. Quarterly review of tier-2 institution vendor consolidation patterns and climate risk quantification mandate expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Latin America Data Analytics in Banking Market
Banking
Investment Banking Market
Banking
Smart Machines in Banking Market
Banking
E-Banking Market
Banking
Blockchain in Retail Banking Market
Banking
Machine Learning in Banking Market
Banking
Singapore Data Analytics in Banking Market
Banking
Banking CRM Software Market
Banking
Automated Teller Machine (ATM) Market
Banking
Banking Maintenance Support and Services Market
Banking
Digital LED Retail Banking Market
Banking
Retail Banking IT Spending Market
Banking
Middle East Data Analytics in Banking Market
Banking
China Bank Kiosk Market
Banking
Biometric Banking Wristband Market
Banking
Predictive Analytics in Banking Market