
 Blockchain in Banking Market | 2026-2036
Blockchain in Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Blockchain in Banking Market Outlook
Enterprise-grade security certification is redrawing procurement standards for blockchain infrastructure in banking. Ripple leverages its native settlement protocol to anchor cross-border payment corridors across Asia-Pacific correspondent networks. Mastercard competes through proprietary blockchain APIs that integrate with existing card rails, while Circle specializes in fiat-backed stablecoin infrastructure for treasury operations.
Blockchain in banking denotes cryptographically linked distributed ledgers that enable peer-to-peer transaction validation without central intermediaries, typically employing consensus mechanisms such as proof-of-stake or Byzantine fault tolerance to achieve finality within seconds to minutes. Its primary commercial purpose centers on reducing settlement latency, counterparty risk, and reconciliation costs across payment, lending, and securities workflows. Payment processing commands the largest revenue pool among service types due to persistent friction in correspondent banking, while smart contracts represent the fastest-expanding segment as programmable escrow and automated compliance logic gain traction. Hybrid blockchain deployments now dominate technology selection among Tier 1 institutions seeking to balance transparency with data confidentiality.
FDA guidelines on digital asset custody, SEC disclosure requirements for crypto holdings, and EU MiCA licensing standards collectively shape product roadmaps and vendor qualification criteria for banking blockchain deployments. Basel Committee prudential frameworks further constrain how institutions capitalize on-chain exposures, filtering technology choices toward audited, permissioned architectures. Stakeholders must weigh regulatory convergence timelines against the technical debt of early platform commitments.
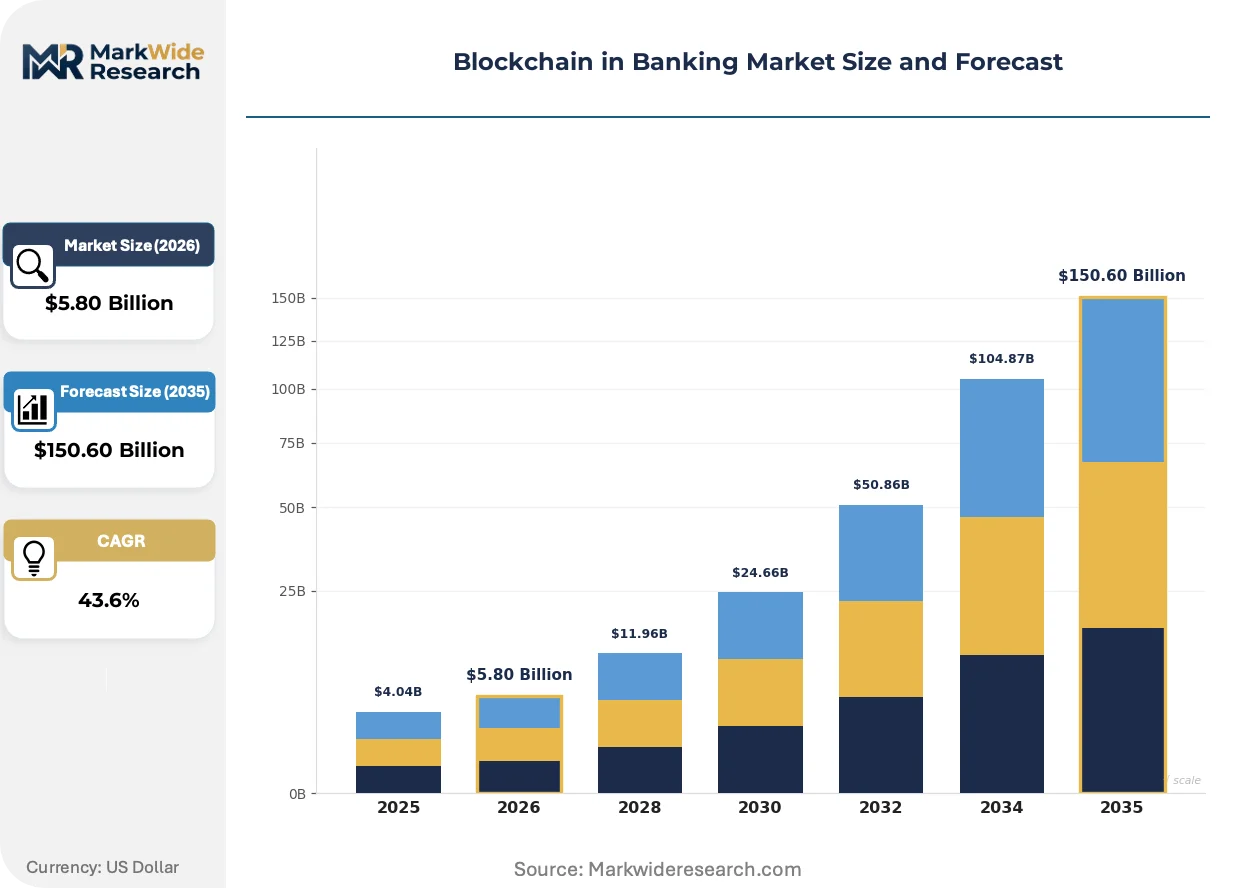
Market Dynamics
Correspondent banking networks are dismantling legacy SWIFT correspondent relationships in favor of atomic settlement rails, compressing cross-border payment latency from days to seconds while forcing infrastructure reinvestment cycles.
Growth Catalysts
- EU MiCA Licensing Mandates:European banks must upgrade custody and disclosure architectures ahead of enforcement deadlines, creating procurement windows for compliant ledger infrastructure.
- Atomic Settlement Protocols:Distributed finality mechanisms eliminate nostro-vostro prefunding requirements, unlocking trapped liquidity across Asia-Pacific payment corridors.
- Singapore MAS Sandboxes:Live production waivers have accelerated deployment of wholesale CBDC networks and tokenized deposit pilots among ASEAN correspondent banks.
Market Restraints
- Basel Committee Capital Charges:Prudential frameworks impose punitive risk-weighting on unregulated crypto-asset exposures, filtering technology choices toward audited permissioned architectures.
- Quantum Vulnerability Windows:Elliptic curve cryptography underlying current ledger signatures faces theoretical decryption threats from advancing quantum computing programs.
- Interoperability Protocol Fragmentation:Competing settlement standards across Ripple, Hyperledger Fabric, and R3 Corda create integration complexity and vendor lock-in risks.
Strategic Opportunities
- Programmable Escrow Smart Contracts:Automated compliance logic and conditional payment release are displacing manual trade finance documentation across commodity trading workflows.
- Tokenized Securities Settlement:DLT-based clearing models compress T+2 cycles to T+0, targeting repo markets and corporate bond issuance in Switzerland and Luxembourg.
- India RBI Wholesale CBDC Pilots:The central bank's phased e-rupee expansion creates vendor qualification pathways for domestic and foreign ledger infrastructure providers.
Industry Challenges
- Distributed Systems Engineering Talent Scarcity:Banks face acute shortages of developers proficient in Byzantine fault tolerance consensus design and zero-knowledge proof implementation.
- Core Banking Integration Complexity:COBOL-era ledger systems require expensive middleware layers to interface with modern DLT nodes, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blockchain in Banking Market |
| Market Size in 2026 | $5.80 Billion |
| Market Size in 2035 | $150.60 Billion |
| CAGR (2026 – 2036) | 43.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Processing, Smart Contracts, Identity Verification, Asset Management Technology: Private Blockchain, Public Blockchain, Hybrid Blockchain, Distributed Ledger Technology Customer Type: Retail Banks, Investment Banks, Credit Unions, Fintech Companies Deployment: Cloud-Based, On-Premises, Hybrid Deployment, Managed Services |
| Companies Covered | Ripple, PayPal, Coinbase Global Inc., Fiat24, Mastercard, Galaxy Digital Inc., Block Inc., Nubank, Circle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blockchain in Banking Market Strategic Shifts
Enterprise blockchain infrastructure is converging around hybrid architectures that partition sensitive transaction data from transparent settlement records, reshaping procurement criteria for Tier 1 institutions.
Confidential computing enclaves are miniaturizing the trusted execution footprint required for private smart contract validation. Tier 1 banks in Switzerland and Singapore are deploying these modules for collateral management workflows. The technology is miniaturizing compliance overhead by embedding regulatory logic directly into hardware-isolated execution environments.
SEC disclosure requirements for material crypto-asset holdings are forcing quarterly transparency protocols that exceed traditional banking standards. Institutions must now maintain real-time attestation systems for on-chain treasury positions. US-domiciled banks are responding by segregating digital asset operations into separately capitalized subsidiaries.
Corporate treasury departments are unbundling payment execution from relationship banking, selecting settlement rails based on speed and cost rather than correspondent network depth. This pattern is displacing long-standing correspondent banking fee structures. The shift is most visible among multinational commodity traders operating across Singapore, Dubai, and London payment corridors.
Blockchain in Banking Market Segmentation
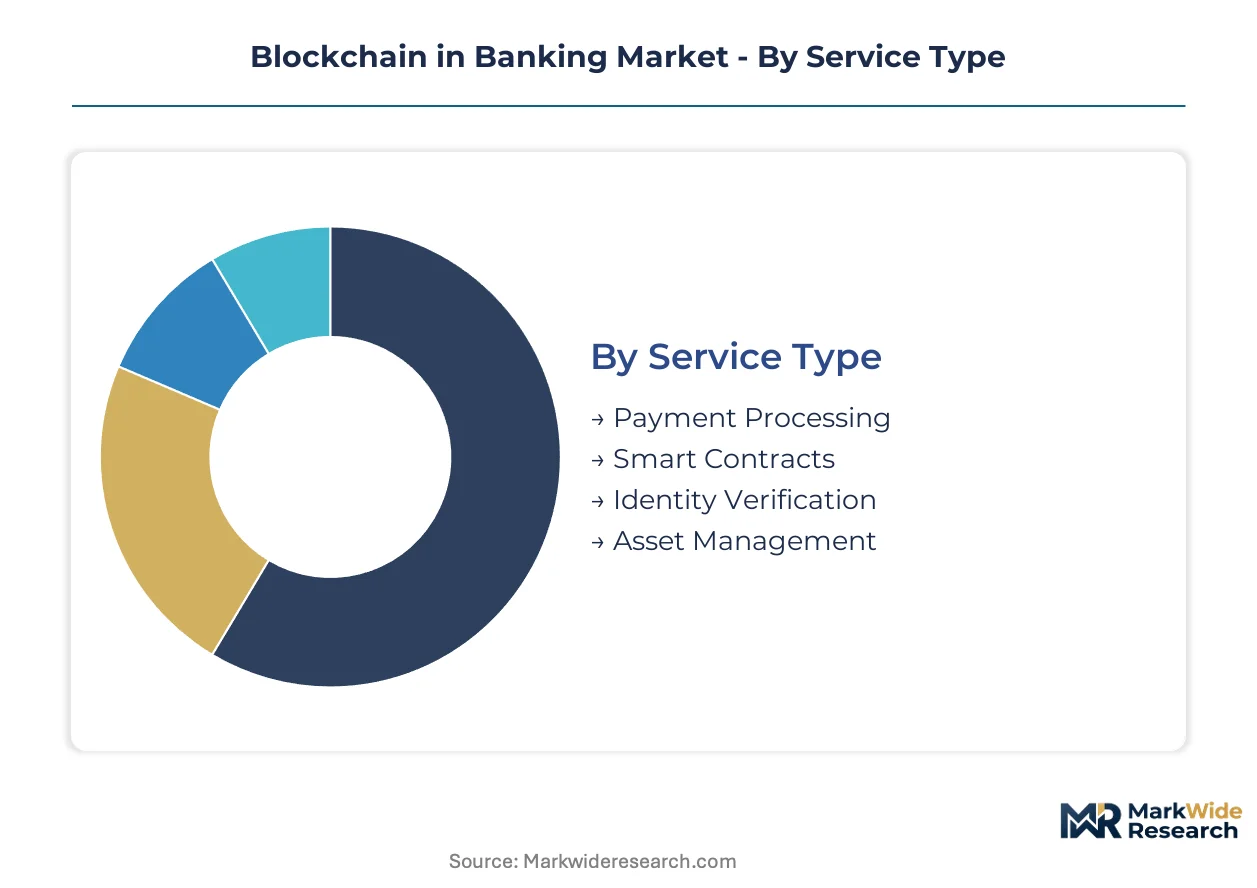
Blockchain banking deployments fragment across service layers, infrastructure models, and institutional archetypes. Procurement patterns diverge sharply between wholesale payment corridors seeking atomic settlement and retail custody operations requiring regulatory-grade audit trails. Channel economics favor integrated platform vendors for multi-service contracts while point solutions capture niche compliance workflows.
Service Type:
Payment processing flows predominantly through correspondent banking upgrade cycles, while smart contract demand concentrates in trade finance digitization channels. Identity verification services route through regulatory compliance procurement, and asset management solutions target treasury modernization programs.
- Payment Processing:Atomic settlement rails eliminate nostro-vostro prefunding across Asia-Pacific correspondent networks. Singapore's MAS-sanctioned live production networks anchor regional demand concentration for cross-border liquidity optimization.
- Smart Contracts:Programmable escrow logic automates conditional payment release in commodity trading workflows. EU MiCA licensing mandates are accelerating procurement of audited compliance-embedded contract infrastructure among European trade finance desks.
- Identity Verification:Zero-knowledge proof implementations enable privacy-preserving KYC attestation for correspondent onboarding.
- Asset Management:Tokenized securities settlement compresses clearing cycles for repo market participants.
By volume, Payment Processing leads. By growth pace, Smart Contracts is ahead.
Technology:
Cost tiers stratify around auditability requirements and data confidentiality mandates. Permissioned architectures command premium pricing for regulatory-grade deployments, while hybrid models balance transparency economics against isolation needs.
- Private Blockchain:Restricted node membership enables granular access control for Tier 1 custody operations. Swiss and Singaporean banks deploy these architectures for collateral management workflows requiring hardware-isolated execution environments.
- Hybrid Blockchain:Partitioned data layers separate transparent settlement records from confidential transaction details. Basel Committee capital charges are filtering procurement toward these architectures for their audit trail completeness.
- Public Blockchain:Open validation networks serve stablecoin treasury operations with real-time attestation requirements.
- Distributed Ledger Technology:Non-blockchain DAG structures optimize for high-throughput payment netting scenarios.
By deployment scale, Private Blockchain dominates. By adoption velocity, Hybrid Blockchain is climbing the fastest.
Customer Type:
Application intensity varies by balance sheet complexity and regulatory scrutiny exposure. Investment banks drive structured product tokenization, while retail institutions prioritize payment cost reduction.
- Investment Banks:Structured finance desks deploy DLT for repo market T+0 settlement and corporate bond issuance automation. India's RBI wholesale CBDC pilots are creating vendor qualification pathways for domestic and foreign infrastructure providers targeting securities clearing modernization.
- Retail Banks:Correspondent relationship managers seek atomic settlement alternatives to SWIFT messaging delays. Singapore's banking hub concentration generates clustered demand for cross-border retail remittance cost compression.
- Credit Unions:Smaller balance sheets favor managed service deployments to avoid capital expenditure concentration.
- Fintech Companies:Unlicensed entities leverage Banking-as-a-Service integrations for stablecoin treasury infrastructure.
By contract value, Investment Banks lead. By activation speed, Fintech Companies is expanding most quickly.
Deployment:
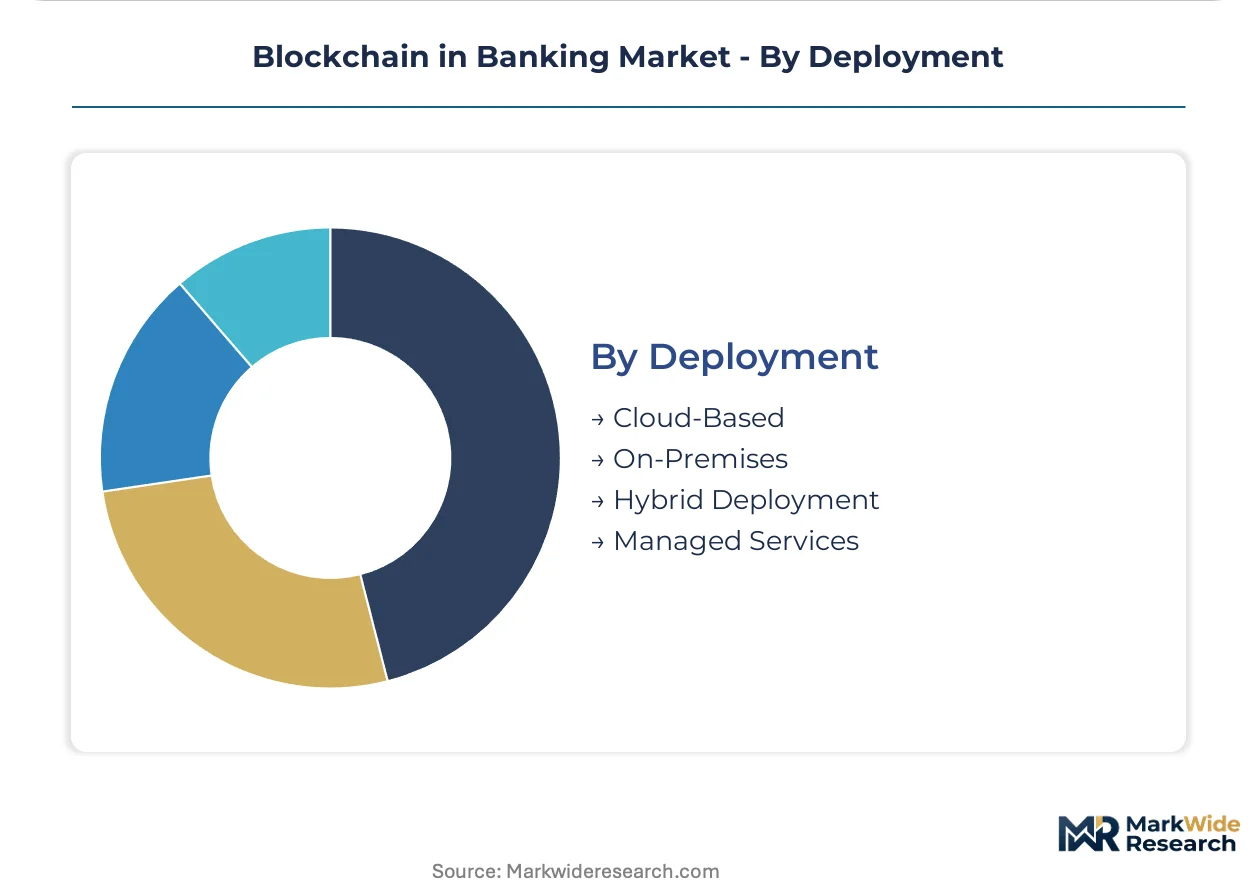
Volume concentration follows data sovereignty requirements and core banking integration complexity. Cloud deployments accelerate for greenfield digital asset subsidiaries, while on-premises persists for mainframe-adjacent legacy systems.
- Cloud-Based:Elastic infrastructure supports volatile transaction volumes in CBDC pilot programs. US-domiciled banks are segregating digital asset operations into separately capitalized cloud-hosted subsidiaries to satisfy SEC disclosure attestation requirements.
- Managed Services:Outsourced node operation and key custody reduce Byzantine fault tolerance engineering talent requirements. Distributed systems engineering scarcity is pushing Tier 2 institutions toward vendor-operated ledger infrastructure.
- On-Premises:Air-gapped validation satisfies national regulators demanding jurisdictional data residency.
- Hybrid Deployment:Sensitive workflows execute on-premises while settlement layers synchronize to cloud nodes.
By installed base, Cloud-Based leads. By contract growth, Managed Services is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ledger infrastructure vendors cluster around three regulatory poles: SEC disclosure regimes in the United States, MiCA licensing deadlines in Europe, and MAS sandbox approvals in Singapore. These jurisdictions anchor cross-border payment corridor deployment and wholesale CBDC pilot programs.
United States
Atomic settlement demand from correspondent banks drives procurement of permissioned ledger infrastructure. SEC quarterly disclosure requirements for material crypto-asset holdings force real-time attestation system upgrades. New York and San Francisco financial centers host segregated digital asset subsidiaries capitalized separately from parent bank balance sheets.
Singapore
Wholesale CBDC networks and tokenized deposit pilots accelerate through MAS regulatory sandbox waivers. The Monetary Authority of Singapore's live production approvals compress deployment timelines for ASEAN correspondent banking corridors. Singapore's banking hub concentrates demand for cross-border liquidity optimization infrastructure.
Germany
EU MiCA licensing mandates compel custody and disclosure architecture upgrades ahead of enforcement deadlines. BaFin supervisory standards filter technology choices toward audited permissioned architectures for institutional deployments. Frankfurt's concentration of universal banks drives structured finance tokenization procurement.
Switzerland
Tokenized securities settlement for repo markets and corporate bond issuance attracts DLT clearing modernization investment. FINMA regulatory frameworks permit hardware-isolated execution environments for collateral management workflows. Zurich and Geneva private banks deploy confidential computing enclaves for smart contract validation.
India
RBI wholesale CBDC pilots create vendor qualification pathways for domestic and foreign ledger infrastructure providers. The central bank's phased e-rupee expansion targets securities clearing modernization and payment cost reduction. Mumbai and Bangalore financial centers anchor demand for core banking middleware integration.
Blockchain in Banking Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the blockchain banking infrastructure segment. Settlement protocol specialists compete against card network incumbents and stablecoin infrastructure providers for correspondent banking upgrade budgets. Three strategic archetypes dominate: native DLT protocol developers, legacy payment rail integrators, and fiat-backed token issuers. Competitive moves center on regulatory sandbox participation and strategic API partnerships with Tier 1 institutions.
Within the native protocol tier, Ripple exemplifies cross-border settlement specialization through its correspondent network anchoring position. Mastercard occupies a position bridging legacy card infrastructure with blockchain API layers, representing the incumbent adaptation archetype. Circle anchors the stablecoin infrastructure segment, exemplifying treasury-focused token issuance for institutional operations.
| Leading Market Players |
|---|
| Ripple |
| PayPal |
| Coinbase Global Inc. |
| Fiat24 |
| Mastercard |
| Galaxy Digital Inc. |
| Block Inc. |
| Nubank |
| Circle |
| Others |
Value Chain & Pricing Dynamics
Network effects in correspondent banking settlement protocols create steep scale economies that compress price floors for Tier 2 institutions while concentrating procurement power among Asia-Pacific hub banks. MAS sandbox approvals in Singapore and EU MiCA licensing mandates collectively reshape vendor pricing power by filtering technology choices toward audited, permissioned architectures that carry compliance premiums.
Pricing Analysis
EU MiCA licensing mandates dictate the pricing tier structure for blockchain banking infrastructure across European deployments. Three-tier pricing structure across premium, standard, and economy levels separates hardware-isolated confidential computing enclaves from cloud-hosted managed services and basic API integration packages. Price differentiation centers on certification grade — Basel Committee audit compliance versus MAS sandbox waiver status — and customization depth for COBOL-era core banking middleware. Cost compression in standard-tier deployments is intensifying because managed service providers are consolidating node operation offerings. Retail banks and credit unions exhibit highest price sensitivity, while investment banks prioritize audit trail completeness over unit economics.
Supply Chain Analysis
Specialized semiconductor fabrication for confidential computing enclaves creates a chokepoint that constrains hardware-isolated execution environment deployment timelines for Swiss and Singaporean collateral management workflows. Geographic supply concentration centers on Taiwan for trusted execution module chipsets, the United States for zero-knowledge proof cryptographic libraries, and Switzerland for private banking compliance software integration. Raw material dependencies include advanced process node silicon, quantum-resistant cryptographic algorithm implementations, and COBOL-interpreter middleware stacks. Single-source vulnerability runs through Taiwan Semiconductor's dominance in secure enclave manufacturing. Distribution runs through Tier 1 systems integrators with Basel Committee audit credentials rather than direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain in banking represents a high-growth disruption anchored by atomic settlement protocols that dismantle decades-old SWIFT correspondent relationships. The convergence of MAS sandbox approvals, EU MiCA enforcement deadlines, and SEC disclosure requirements creates a narrow procurement window for compliant infrastructure vendors.
For Market Incumbents: Shield core correspondent banking revenue streams by accelerating permissioned ledger certification investments ahead of Basel Committee capital charge enforcement. Acquire specialized Byzantine fault tolerance engineering talent through targeted recruitment in Singapore and Zurich financial centers. Vertical integration into hardware-isolated execution environments reduces dependency on Taiwan-based secure enclave suppliers.
For New Entrants and Emerging Players: Differentiate on programmable escrow smart contract specialization for commodity trading workflows, where manual documentation displacement lags payment processing automation. Target India's RBI wholesale CBDC pilot ecosystem as the most penetrable geography, where domestic and foreign infrastructure vendor qualification pathways remain open. Pursue Banking-as-a-Service integration partnerships with fintech treasury operations seeking stablecoin infrastructure without direct licensing overhead.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed service providers operating outsourced node infrastructure for Tier 2 institutions facing distributed systems engineering scarcity. Long-term viability across the analysis window favors vendors with live production network approvals from multiple regulatory sandboxes. Monitor MiCA licensing deadline compliance rates as the critical inflection signal for European market access consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Sandbox Participation | MAS live production waivers compress deployment timelines for ASEAN correspondent banking corridors. |
| Confidential Computing Integration | Hardware-isolated execution environments satisfy FINMA requirements for Swiss collateral management workflows. |
| Core Banking Middleware Development | COBOL-era system interfaces extend deployment timelines for Tier 1 institutions seeking DLT integration. |
| Managed Service Offering Expansion | Outsourced node operation addresses acute Byzantine fault tolerance engineering talent scarcity. |
| Cross-Border Corridor Anchoring | Ripple protocol positioning captures Asia-Pacific atomic settlement demand from correspondent network upgrades. |
Study Parameters
Operator-level perspectives from blockchain infrastructure procurement officers, regulatory compliance leads at Tier 1 banks, distributed systems engineering directors, and MAS sandbox program managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against SEC disclosure filings, MAS regulatory sandbox approval registers, EU MiCA implementation guidance documents, and Basel Committee prudential framework consultations. Bottom-up deployment volume estimates across service types and technologies triangulated against top-down correspondent banking upgrade cycle projections.
Sensitivity analysis around regulatory enforcement timeline scenarios shaped the forecast framework across the analysis window. Modeled segmentation dimensions included service type, technology architecture, customer archetype, and deployment model, with additional granularity for jurisdictional regulatory cluster. CAGRs derived from deployment velocity curves weighted by sandbox approval status and correspondent banking relationship density. Industry-specific inputs incorporated atomic settlement protocol adoption rates and wholesale CBDC pilot expansion trajectories.
Material uncertainties — quantum computing decryption timeline acceleration, interoperability protocol consolidation outcomes, and Basel Committee risk-weighting recalibrations — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory sandbox throughput and correspondent bank infrastructure reinvestment cycle timing. Practitioners should keep alternative scenarios live as MiCA enforcement compliance rates and MAS live production waiver volumes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Payment Bank Solutions Market
Banking
Europe Banking-As-A-Service Market
Banking
Middle East and Africa Neobanking Market
Banking
Corporate Banking Market
Banking
North America Data Analytics in Banking Market
Banking
Singapore Data Analytics in Banking Market
Banking
E-Banking Market
Banking
In Vitro Fertilization Banking Services Market
Banking
Singapore Neobanking Market
Banking
North America Bank Kiosk Market
Banking
Investment Banking Market
Banking
Germany Banking As a Service Market
Banking
China Bank Kiosk Market
Banking
Global Certificate of Deposit Market
Banking
Asia-Pacific Challenger Banks Market
Banking
Intelligent Virtual Assistant (IVA) Based Banking Market