
 Virtual Teller Machine (VTM) Market | 2026-2036
Virtual Teller Machine (VTM) Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Teller Machine (VTM) Market Analytics
Software-defined feature licensing is restructuring how VTMs generate recurring revenue beyond hardware sales. NCR Corporation leverages its installed base of traditional ATMs to extend into video-enabled upgrade paths. Huawei Technologies anchors its position through integrated biometric authentication stacks that reduce third-party dependency. Diebold Nixdorf competes by sustaining dense service technician networks across mature banking markets.
A Virtual Teller Machine combines automated cash handling hardware with real-time video conferencing to connect customers with remote human tellers, typically processing deposits, withdrawals, and account management through touchscreen interfaces with document scanning and biometric verification. The primary commercial purpose is to deliver branch-equivalent service at lower real estate and staffing cost per transaction. Deposit and withdrawal service types dominate current installed value, while account management functionality captures expanding margin pools as banks bundle advisory conversations into self-service sessions. Cloud-based deployment is growing fastest among mid-tier financial institutions seeking to avoid capital-intensive on-premises infrastructure, though hybrid systems retain preference among large retail banks with legacy compliance architectures.
The Federal Reserve's cash access policies and the FFIEC authentication guidance shape product standards for US-deployed VTMs, while China's MIIT cybersecurity certification and GB standards govern biometric data handling in domestic installations. The EU's GDPR and forthcoming AI Act constrain video recording retention and algorithmic identity verification across European credit union networks. Stakeholders must weigh regulatory fragmentation against the cost advantages of unified hardware platforms that can adapt authentication modules to jurisdiction-specific requirements.
Market Dynamics
Cloud migration pressure is compressing deployment timelines for financial institutions seeking to shed on-premises infrastructure burdens while maintaining FFIEC-compliant authentication architectures. This structural shift is redrawing vendor selection criteria away from hardware-centric specifications toward API flexibility and biometric middleware compatibility.
Growth Catalysts
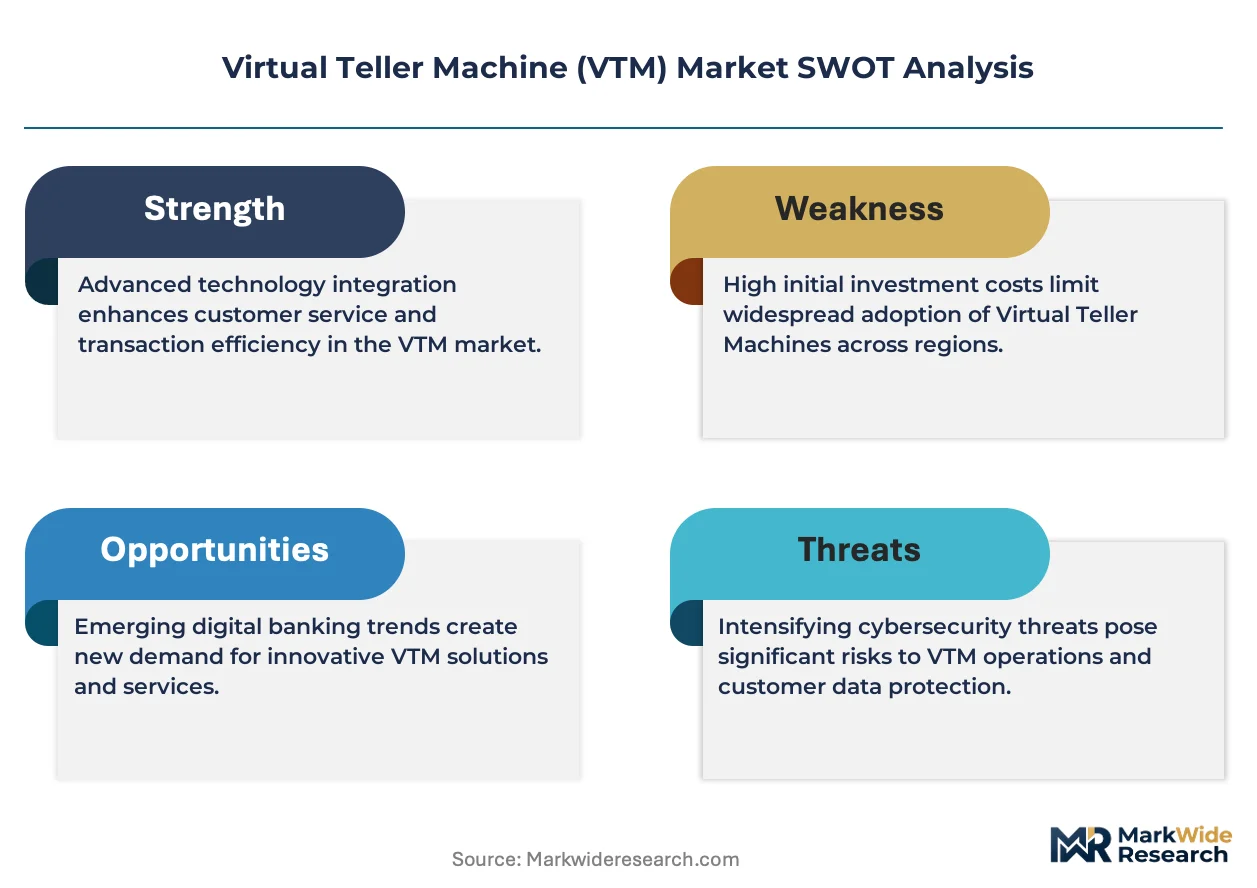
- FFIEC Authentication Guidance:US federal banking regulators mandate multi-factor identity verification for remote teller interactions, compelling credit unions and regional banks to upgrade legacy ATM fleets with video-enabled biometric stacks.
- Branch cost rationalization:Retail banking networks in China and the United States deploy VTMs to preserve face-to-face service relationships while reducing real estate footprints in high-rent urban cores.
- Facial recognition liveness detection:Deep-learning algorithms for spoof-proof biometric verification are integrating into standard hardware configurations, lowering fraud incidence rates for cash-handling transactions.
Market Restraints
- Semiconductor supply concentration:GPU and specialized image processing chip availability remains constrained by Taiwan-based foundry capacity, extending VTM hardware delivery lead times.
- GDPR video retention limits:European Union data protection rules cap recorded teller session storage at 72 hours for most retail banking applications, complicating dispute resolution workflows.
- Mobile banking substitution:Smartphone-native deposit capture and peer-to-peer transfer applications capture routine transactions that VTMs target, narrowing the addressable use case to cash-intensive customer segments.
Strategic Opportunities
- India rural banking mandate:RBI financial inclusion directives require last-mile service points in unbanked districts, creating demand for solar-powered VTMs with satellite connectivity.
- AI-driven predictive routing:Convergence of queue management algorithms with video teller staffing systems enables dynamic specialist allocation during peak demand windows.
- Credit union shared networks:Cooperative deployment models allow smaller institutions to split VTM capital costs while pooling remote teller talent across state lines.
Industry Challenges
- Certification timeline compression:EMVCo and PCI PTS approval cycles for biometric-enabled terminals extend 14-18 months, delaying product launches past budget windows.
- Legacy core banking integration:Proprietary middleware from 1990s-era mainframe systems requires custom API development for real-time balance inquiry and hold functionality.
- Field technician scarcity:Mechatronics expertise combining cash handling mechanics with IP network troubleshooting concentrates in aging workforce cohorts with limited replacement pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Teller Machine (VTM) Market |
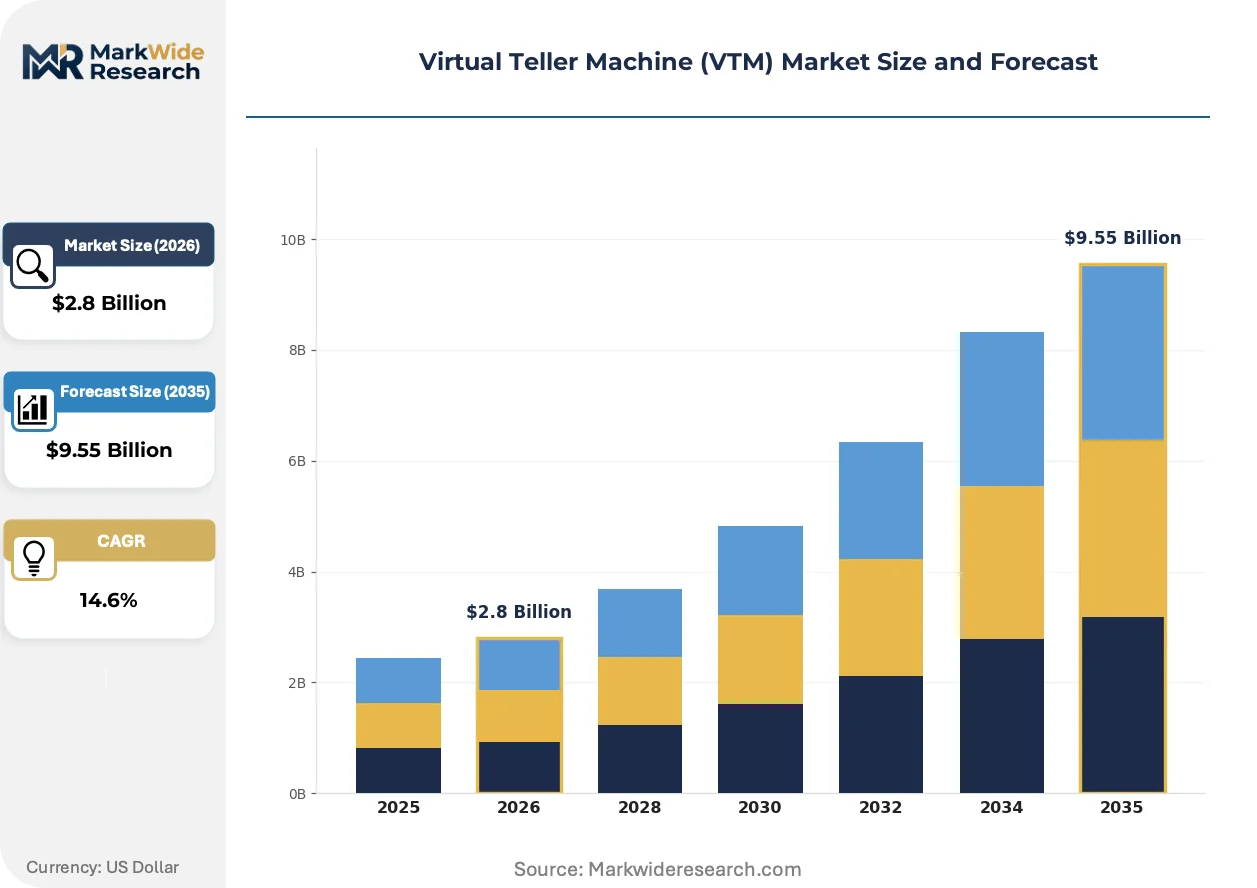
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Deposit, Withdrawal, Account Management, Bill Payment End User: Retail Banks, Credit Unions, Payment Processors, Financial Institutions Deployment: On-Premises, Cloud-Based, Hosted Solutions, Hybrid Systems Technology: Biometric Authentication, Video Conferencing, Touchscreen Interface, Transaction Management |
| Companies Covered | Hitachi-Omron Terminal Solutions Corporation, Huawei Technologies, NCR Corporation, Aurionpro Solutions, Kontron AG, Diebold Nixdorf, Glory Global Solutions, KIOSK Information Systems, GRG Banking Equipment Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Teller Machine (VTM) Market Evolving Landscape
Biometric authentication stacks are displacing signature cards and PIN entry as the primary customer verification layer, while software-defined feature licensing restructures how hardware vendors monetize installed bases beyond initial sale.
Multimodal biometric fusion is integrating iris, facial, and voiceprint recognition into unified authentication workflows that reduce false rejection rates below 0.1 percent. Mid-tier US credit unions adopt these configurations fastest as competitive differentiation against national branch networks. The technology is integrating compliance automation directly into transaction processing, reducing manual audit preparation for FFIEC examinations.
China's MIIT cybersecurity certification for financial terminals now mandates domestic encryption module standards for all biometric data transmission, effective for new installations. This regulatory barrier favors local hardware suppliers with pre-certified component stacks. Foreign vendors respond by establishing joint venture manufacturing within Shanghai and Shenzhen free-trade zones to maintain market access.
Community banks increasingly favor subscription-based VTM-as-a-service arrangements over capital purchase models. Equipment lessors capture margin pools previously held by manufacturers by bundling remote teller staffing, software updates, and hardware refresh cycles into per-transaction fees. This procurement evolution concentrates most visibly in the US Southeast, where rapid branch consolidation creates demand for flexible service delivery without fixed asset commitments.
Virtual Teller Machine (VTM) Market Segmentation
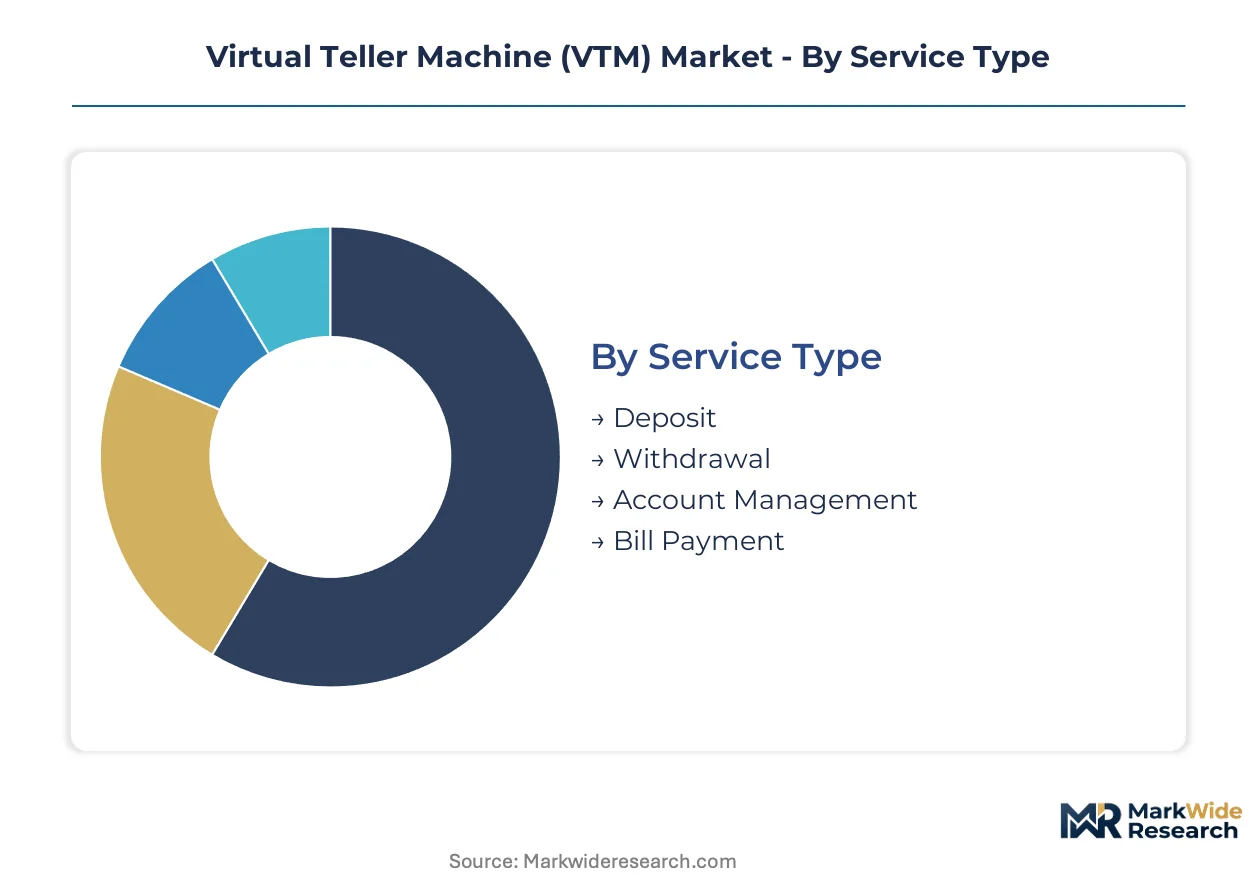
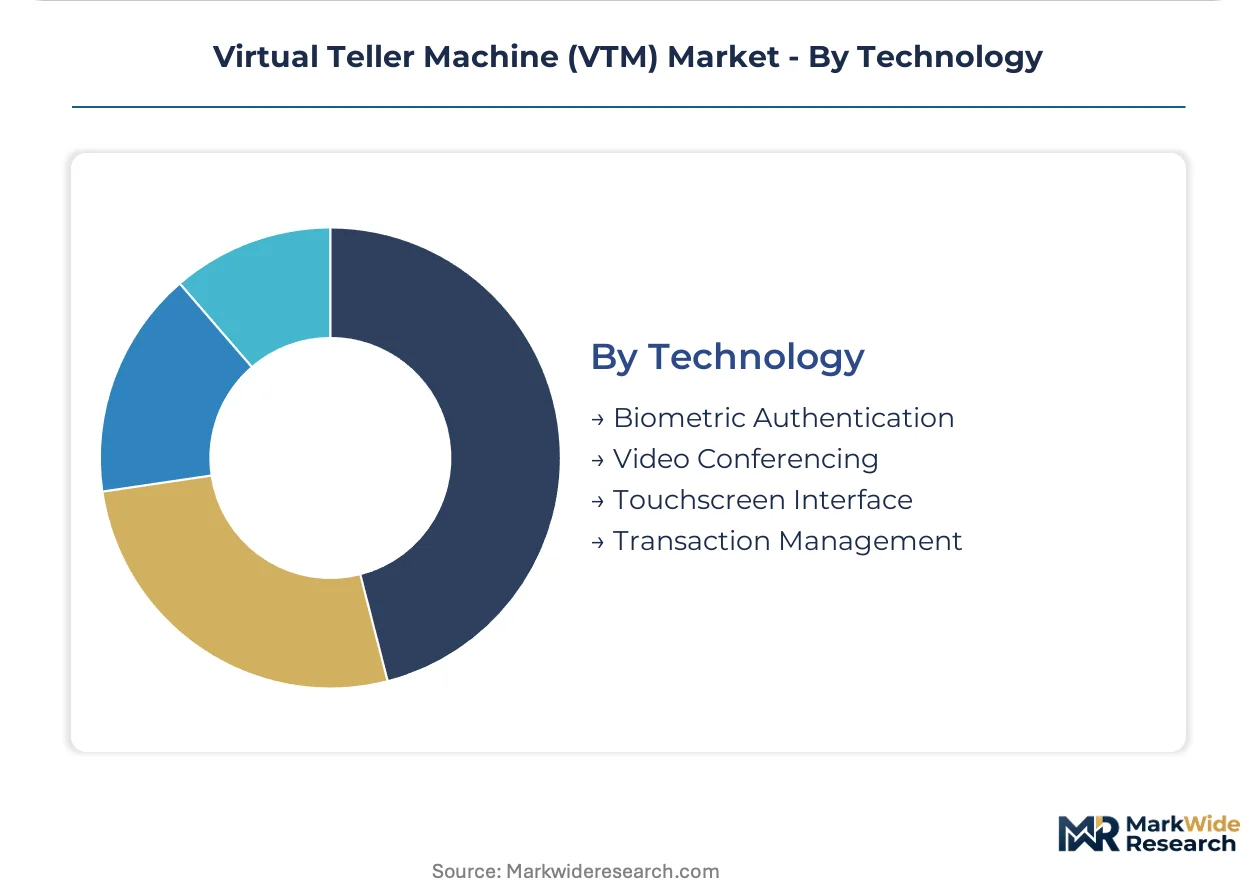
VTM procurement patterns diverge sharply between institutions seeking turnkey standardization and those demanding bespoke authentication stacks. Segmentation reveals how deployment models, service configurations, and technology choices align with distinct risk appetites and regulatory postures across banking networks.
Service Type:
Standardization dominates high-volume cash handling, while account advisory services command premium customization fees from relationship-focused institutions.
- Deposit:Core functionality combining cash acceptance, check imaging, and real-time balance confirmation through integrated cash recyclers. Demand concentrates in US community banks and China's rural commercial banking cooperatives, where FFIEC and MIIT compliance requirements mandate audit-ready transaction logging.
- Withdrawal:Cash dispensing with biometric verification layers replacing card-based authentication. US credit unions deploy these configurations fastest following FFIEC multi-factor guidance updates, prioritizing fraud reduction over speed optimization.
- Account Management:Remote advisory sessions for loan applications, product cross-selling, and dispute resolution. Indian regional banks under RBI inclusion mandates represent expanding demand for video-enabled advisory in underbanked districts.
- Bill Payment:Utility and tax payment processing with receipt generation. Payment processors in Southeast Asian markets integrate this functionality into multi-merchant kiosk networks.
Most installed capacity flows through Deposit. Expansion is steepest in Account Management.
End User:
Cost absorption capacity separates institutions pursuing capital ownership from those favoring operational expenditure models.
- Retail Banks:Tier-one institutions with proprietary branch networks and legacy core banking investments. These buyers prioritize hybrid deployment flexibility and API compatibility with 1990s-era mainframe systems.
- Credit Unions:Member-owned cooperatives with shared branching agreements and constrained IT budgets. US-based credit unions increasingly adopt subscription-based VTM-as-a-service to pool remote teller staffing across state lines.
- Payment Processors:Third-party transaction networks seeking white-label deployment for merchant clients. These operators demand cloud-native architectures with rapid tenant provisioning capabilities.
- Financial Institutions:Catch-all category encompassing neobanks, postal banks, and non-bank lenders. India's India Post Payments Bank exemplifies demand for solar-powered, satellite-connected units under RBI last-mile mandates.
Retail Banks absorb the largest share of capital expenditure. Credit Unions are gaining share fastest through cooperative procurement structures.
Deployment:
Infrastructure control preferences split between compliance-driven on-premises retention and agility-seeking cloud migration.
- On-Premises:Fully owned hardware with local data residency and custom security hardening. Large US retail banks with legacy FFIEC examination histories favor this model despite higher total cost of ownership.
- Cloud-Based:Vendor-managed infrastructure with software-defined feature licensing and automatic compliance updates. Mid-tier US credit unions and European cooperative banks adopt this fastest to shed data center operational burdens.
- Hosted Solutions:Single-tenant managed services with dedicated hardware at vendor facilities. Payment processors in latency-sensitive markets select this for guaranteed throughput without capital deployment.
- Hybrid Systems:Transaction processing at edge with biometric data vaulting on-premises. China's large commercial banks prefer this under MIIT cybersecurity certification requirements for domestic encryption modules.
On-Premises retains the largest installed base. Cloud-Based deployment is climbing the fastest among institutions seeking to avoid infrastructure refresh cycles.
Technology:
Authentication sophistication tiers separate basic video-enabled ATMs from fraud-resistant biometric platforms.
- Biometric Authentication:Multimodal fusion of facial, iris, and voiceprint recognition with liveness detection algorithms. US credit unions deploy these stacks fastest to differentiate against national branch networks while satisfying FFIEC multi-factor mandates.
- Video Conferencing:Real-time teller interaction with session recording and quality monitoring. Indian rural banking mandates under RBI directives drive demand for low-bandwidth-optimized codecs.
- Touchscreen Interface:Document scanning, signature capture, and adaptive accessibility features. Standard configuration across all price tiers with limited differentiation potential.
- Transaction Management:Queue routing, load balancing, and teller allocation algorithms. AI-driven predictive routing represents the fastest-advancing capability layer for peak demand management.
Biometric Authentication commands the highest unit premiums. Transaction Management software is gaining deployment share fastest as banks prioritize operational efficiency over hardware refresh.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys VTMs faster than China, though Chinese manufacturers dominate hardware supply chains. Regulatory divergence between FFIEC guidance and MIIT cybersecurity mandates forces vendors to maintain dual certification tracks. Installation clusters concentrate in financial districts where branch consolidation pressures intersect with cash-intensive customer bases.
United States
Credit unions drive replacement cycles as FFIEC multi-factor authentication guidance compels legacy ATM fleet upgrades. The Federal Reserve's cash access policies shape hardware specifications for cash recyclers and deposit automation. Chicago and Dallas-Fort Worth host dense concentrations of VTM deployments where regional banks rationalize suburban branch networks.
China
Rural commercial banking cooperatives expand VTM networks under financial inclusion mandates targeting unbanked populations. MIIT cybersecurity certification requires domestic encryption modules for all biometric data transmission, favoring local component suppliers. Guangdong Province manufacturing clusters around Shenzhen produce certified hardware for both domestic installation and export markets.
India
India Post Payments Bank and regional rural banks deploy solar-powered VTMs with satellite connectivity under RBI last-mile service mandates. The central bank's financial inclusion directives require service points in districts with limited traditional branch penetration. Maharashtra and Gujarat lead state-level procurement for video-enabled banking kiosks in agricultural credit networks.
Germany
Sparkassen and cooperative banking networks evaluate VTM deployments to preserve face-to-face advisory relationships amid branch closures. GDPR video retention limits complicate dispute resolution workflows, capping recorded teller sessions at 72 hours. Frankfurt and Munich financial centers pilot hybrid deployments balancing cloud agility with on-premises data residency requirements.
Japan
Regional banks facing demographic decline deploy VTMs to maintain service coverage in shrinking rural municipalities. METI industrial policy supports domestic manufacturing of biometric-enabled terminals through technology development subsidies. Nagoya and Osaka industrial corridors host assembly operations for export-oriented hardware production.
Virtual Teller Machine (VTM) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated solution providers capturing premium pricing in regulated markets while component suppliers serve price-sensitive procurement. The vendor base concentrates around three archetypes: full-stack hardware-software integrators, biometric authentication specialists, and cash handling equipment legacy players. Consolidation pressure intensifies as cloud migration demands API compatibility investments that smaller fabricators cannot sustain. Strategic partnerships and geographic licensing agreements represent the dominant competitive moves as vendors navigate certification timeline compression.
Among Asia-Pacific-based hardware specialists, Huawei Technologies and GRG Banking Equipment Co., Ltd. exemplify the integrated stack archetype combining biometric middleware with domestic certification advantages. NCR Corporation represents the installed-base leverage model, converting legacy ATM relationships into video-enabled upgrade pathways. These three anchors illustrate how regulatory alignment and existing customer relationships determine competitive positioning across fragmented procurement environments.
| Leading Market Players |
|---|
| Hitachi-Omron Terminal Solutions Corporation |
| Huawei Technologies |
| NCR Corporation |
| Aurionpro Solutions |
| Kontron AG |
| Diebold Nixdorf |
| Glory Global Solutions |
| KIOSK Information Systems |
| GRG Banking Equipment Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Captive integration into biometric middleware and cash handling mechanics anchors both supply security and pricing power for VTM vendors navigating Taiwan foundry constraints and MIIT certification barriers. This structural choice separates full-stack integrators from component-dependent assemblers.
Pricing Analysis
Capacity additions in China's Guangdong Province are reshaping price floors for biometric-enabled terminals as domestic encryption module certification accelerates local production scale. Pricing stratifies across premium, standard, and economy tiers based on authentication sophistication and FFIEC compliance grade. Cost compression in mid-tier configurations is intensifying because credit unions pool procurement through cooperative networks. Payment processors exhibit highest price sensitivity due to thin transaction margins, while tier-one retail banks absorb premium positioning for hybrid deployment flexibility.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based GPU and image processing chip foundries that feed cash recycler and facial recognition module production. Component sourcing draws from China, South Korea, and Japan for optical sensors, cash handling mechanisms, and video codecs. Tariff exposure on semiconductor imports into the United States threatens margin stability for hardware vendors serving credit union networks. Distribution runs through regional banking equipment distributors with certified technician networks, though cloud-native vendors increasingly bypass physical channels through direct subscription sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Virtual Teller Machine procurement functions as a regulatory compounder where FFIEC multi-factor authentication mandates and China's MIIT cybersecurity certification create sustained replacement demand across installed ATM bases.
For Market Incumbents: Hedge against cloud-native disruption by acquiring API-first biometric middleware specialists before subscription-based competitors capture credit union shared networks. Prioritize certification investment in India's BIS and RBI compliance frameworks as rural banking mandates accelerate. Capacity addition in Shenzhen free-trade zones preserves market access under domestic encryption requirements. For New Entrants and Emerging Players: Capture white-space in India's solar-powered, satellite-connected VTM deployments under RBI last-mile inclusion directives where incumbent service networks remain thin. Target European cooperative banking networks seeking GDPR-compliant cloud alternatives with 72-hour video retention automation. Lead with AI-driven predictive routing as a differentiated software layer above commodity hardware. For Investors and Strategic Acquirers: Consolidation pressure builds where cloud migration demands API compatibility investments beyond smaller fabricator capabilities. Long-term viability centers on vendors with dual certification tracks spanning FFIEC and MIIT frameworks. Acquisition target archetype: biometric authentication specialists with pre-certified component stacks and established technician training programs. Watch cloud-based deployment share in mid-tier credit unions as inflection signal for subscription revenue durability.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Middleware Acquisition | FFIEC compliance mandates accelerate demand for integrated facial-iris-voiceprint fusion stacks. |
| Domestic Encryption Certification | MIIT cybersecurity requirements favor joint venture manufacturing in Shanghai and Shenzhen zones. |
| Credit Union Shared Network Partnership | Cooperative procurement models pool remote teller staffing across state lines for cost absorption. |
| Solar-Powered Rural Deployment | RBI last-mile mandates in unbanked districts create satellite-connected VTM demand clusters. |
| AI-Driven Predictive Routing | Queue management algorithms optimize video teller allocation during peak demand windows. |
Research Methodology
Bottom-up credit union and retail bank procurement modeling reconciled against top-down hardware shipment tracking forms the analytical core of this study. Primary interviews with banking technology officers, branch operations directors, core banking integration specialists, and ATM fleet managers combined with secondary validation from FFIEC examination reports, RBI circulars on financial inclusion, MIIT cybersecurity certification databases, and EMVCo terminal approval records. Triangulation between installed base estimates and vendor revenue disclosures anchors volume assessments.
Input-output matrices map transaction volume forecasts to hardware deployment requirements across the projection horizon. Segmentation dimensions include service type, deployment model, end-user institution tier, and authentication technology sophistication. CAGRs derive from regression analysis of historical ATM replacement cycles adjusted for regulatory mandate acceleration. Industry-specific forecast inputs incorporate semiconductor delivery lead times and certification timeline compression effects.
Semiconductor supply disruptions, regulatory certification delays, and mobile banking substitution acceleration are the dominant revision risks that could compress or extend deployment timelines. Forecasts reflect documented assumptions about FFIEC guidance stability and MIIT encryption module standard continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Banking Tax Management Software Market
Banking
Middle East Data Analytics in Banking Market
Banking
Corporate Digital Banking Market
Banking
Global Retail Core Banking Systems Market
Banking
Merchant Banking Services Market
Banking
Smart Banking Solutions Market
Banking
Singapore Data Analytics in Banking Market
Banking
Canada Intelligent Virtual Assistant (IVA) Based Banking Market
Banking
US Retail Banking Market
Banking
US Banking-As-A-Service Market
Banking
Asia-Pacific Islamic Finance Market
Banking
Cloud-Based Core Banking Market
Banking
Australia Data Analytics in Banking Market
Banking
Core Banking Solutions Market
Banking
Germany Neobanking Market
Banking
Germany Banking As a Service Market