
 Biometrics for Banking and Financial Services Market | 2026-2036
Biometrics for Banking and Financial Services Market Size, Share, and Industry Trends Forecast 2026-2036
Biometrics for Banking and Financial Services Market Insights
GDPR enforcement in Europe is consolidating the cost-of-entry calculus for biometric vendors serving financial institutions. IDEMIA leverages its civil identity infrastructure to anchor high-assurance banking contracts across EU member states. Thales Group sustains competitive positioning through chip-integrated fingerprint modules that dominate payment card personalization. NEC Corporation specializes in multimodal fusion systems that combine facial and iris modalities for tier-one retail banks.
Biometrics for Banking and Financial Services encompasses automated identity verification technologies that measure unique physiological or behavioral characteristics for authentication purposes. Fingerprint recognition systems operate through capacitive or ultrasonic sensors capturing ridge patterns at resolutions exceeding 500 dots per inch, while facial recognition platforms map facial geometry using structured light or time-of-flight cameras for liveness detection against presentation attacks. Fingerprint recognition occupies the largest installed base among biometric types due to decades of sensor cost reduction and embedded deployment in ATMs and mobile banking applications. Multi-factor authentication represents the fastest-expanding authentication mode as regulators mandate layered security beyond single biometric factors for high-value transactions. Cloud-based solutions are capturing disproportionate investment from mid-tier retail banks and credit unions seeking to avoid capital-intensive on-premises infrastructure.
The European Banking Authority, the U.S. Federal Trade Commission, and India's Reserve Bank collectively shape product standards through cybersecurity resilience testing, consumer consent frameworks, and mandatory incident reporting thresholds. BIS certification requirements for biometric devices in India restrict market access to vendors meeting ISO/IEC 19795 performance benchmarks. Stakeholders must monitor evolving liability allocations between biometric algorithm providers and financial institutions as authentication failures trigger fraud losses.
Market Dynamics
The EU AI Act's risk-tiered classification system for biometric systems is forcing algorithm vendors to reengineer authentication pipelines for explainability and auditability, compressing development timelines while elevating compliance costs for financial sector deployments.
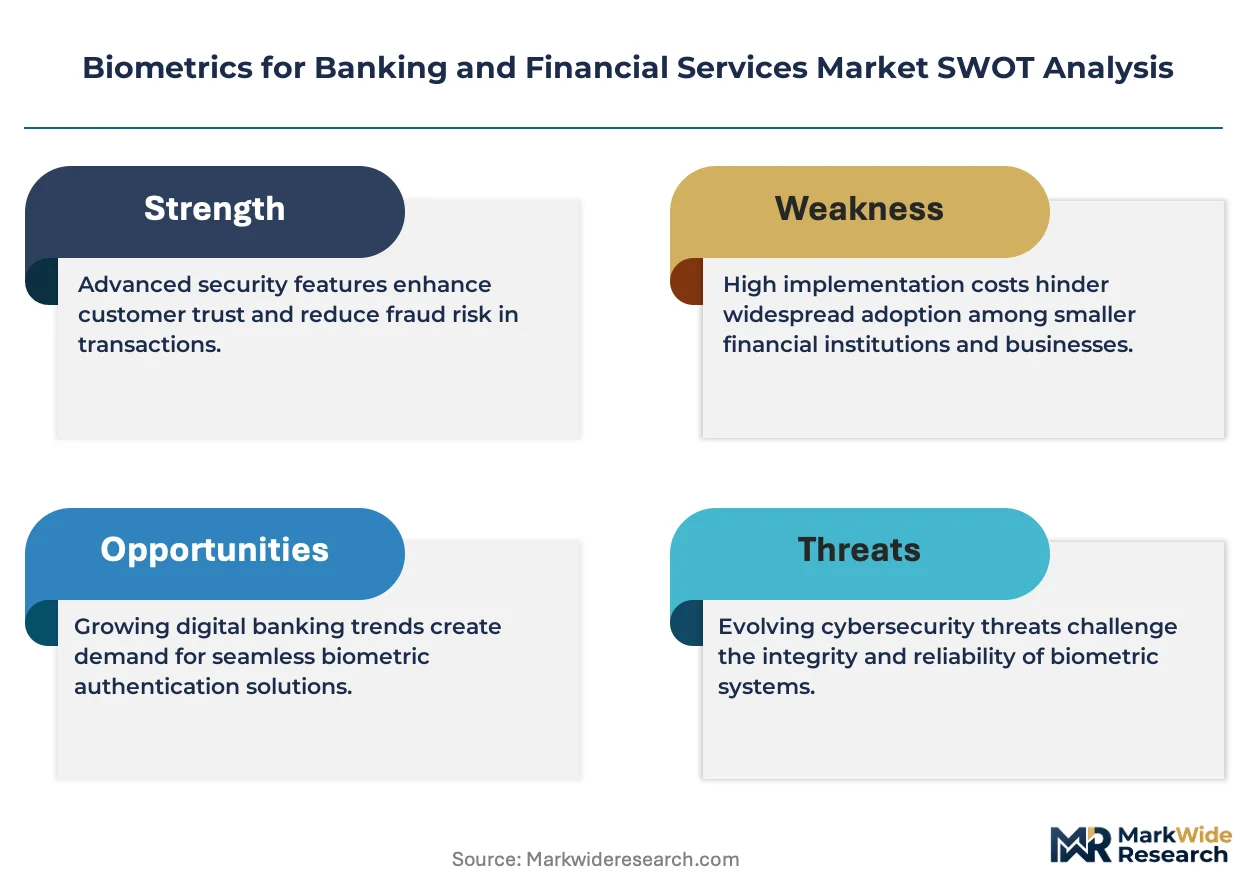
Growth Catalysts
- EU AI Act enforcement:Financial institutions across Germany, France, and Italy must deploy high-assurance biometric systems for remote onboarding, creating mandatory upgrade cycles for legacy authentication infrastructure.
- India's BIS certification mandate:The Reserve Bank of India requires ISO/IEC 19795-compliant biometric devices for all payment terminals, standardizing performance thresholds and accelerating vendor qualification programs.
- Behavioral biometrics integration:Keystroke dynamics and gait analysis layered atop physiological modalities enable continuous authentication without friction, attracting tier-one retail banks seeking transaction monitoring differentiation.
Market Restraints
- Sensor supply concentration:Capacitive fingerprint module production clusters in East Asian contract manufacturers, exposing European and North American integrators to geopolitical supply disruptions and extended lead times.
- GDPR biometric data friction:Explicit consent requirements and purpose limitation rules in European jurisdictions impose legal complexity on cross-border data flows, constraining cloud-based authentication architectures.
- Liveness detection arms race:Deepfake-enabled presentation attacks outpace hardware-based countermeasures, forcing continuous R&D expenditure without durable competitive moats for algorithm providers.
Strategic Opportunities
- Credit union cloud migration:Mid-tier cooperatives in the United States seek subscription-based biometric platforms to bypass capital-intensive on-premises infrastructure, opening vendor-as-a-service revenue streams.
- Voiceprint authentication for call centers:Behavioral voice biometrics layered into IVR systems enable passive caller verification, reducing average handle time for retail banking support operations.
- SEBI's digital KYC mandate:India's securities regulator requires biometric-linked investor verification, extending addressable demand beyond traditional banking into brokerage and wealth management channels.
Industry Challenges
- Multimodal fusion engineering scarcity:Specialists capable of integrating facial, iris, and behavioral signals into unified risk scores command premium compensation, constraining vendor scaling velocity.
- Legacy core banking integration:Mainframe authentication protocols from the 1990s lack API-native interfaces, forcing middleware development that delays biometric deployment timelines by 12-18 months.
- Algorithmic bias remediation:Demographic performance variation in facial recognition systems triggers regulatory scrutiny and litigation exposure, requiring continuous dataset augmentation and fairness auditing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biometrics for Banking and Financial Services Market |
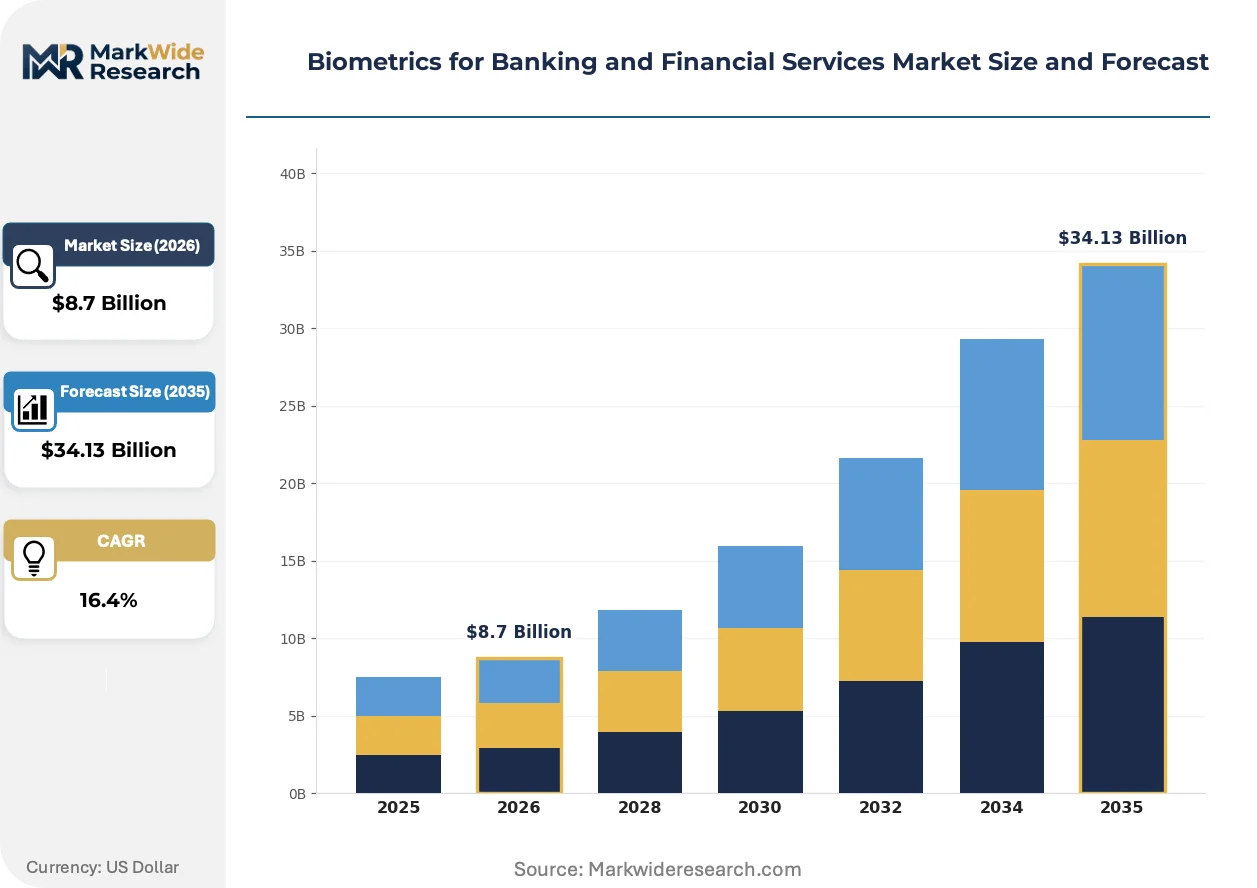
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Biometric Type: Fingerprint Recognition, Facial Recognition, Iris Scanning, Voice Recognition, Palm Vein Recognition Authentication Mode: Two-Factor Authentication, Multi-Factor Authentication, Behavioral Biometrics, Continuous Authentication, Passwordless Access End User: Retail Banks, Investment Firms, Insurance Providers, Payment Processors, Credit Unions Deployment Model: Cloud-Based Solutions, On-Premises Systems, Hybrid Architecture, API Integration, Edge Computing |
| Companies Covered | IDEMIA, Thales Group, NEC Corporation, Fujitsu Limited, Precise Biometrics, Nuance Communications, HID Global, Suprema, Fingerprint Cards, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biometrics for Banking and Financial Services Market Trends and Innovations
Authentication architectures are fragmenting across edge, cloud, and hybrid topologies as financial institutions balance latency requirements against compliance constraints. Three developments are restructuring competitive positioning.
Edge-based facial recognition is decentralizing authentication computation onto smartphones and payment terminals, eliminating round-trip latency for real-time transaction approval. Tier-one retail banks in Singapore and the United Arab Emirates are piloting on-device liveness detection that processes biometric templates locally without cloud transmission. This architecture compresses infrastructure expenditure for mid-tier institutions while satisfying data residency mandates in privacy-sensitive jurisdictions.
The EU AI Act's prohibited-practices list for biometric categorization and emotion recognition is reshaping product roadmaps for vendors serving European financial institutions. Algorithm providers must now document training data provenance and maintain human oversight interfaces for high-risk authentication decisions. German and Dutch retail banks are prioritizing vendors with established conformity assessment procedures, consolidating procurement around pre-certified solution stacks.
Subscription pricing for biometric-as-a-service platforms is displacing perpetual license models among North American credit unions and community banks. These institutions lack capital reserves for upfront hardware deployment but require parity with larger competitors on authentication assurance. Channel partners and core banking vendors are embedding biometric APIs into bundled service offerings, capturing recurring revenue while reducing customer acquisition friction.
Biometrics for Banking and Financial Services Market Segmentation
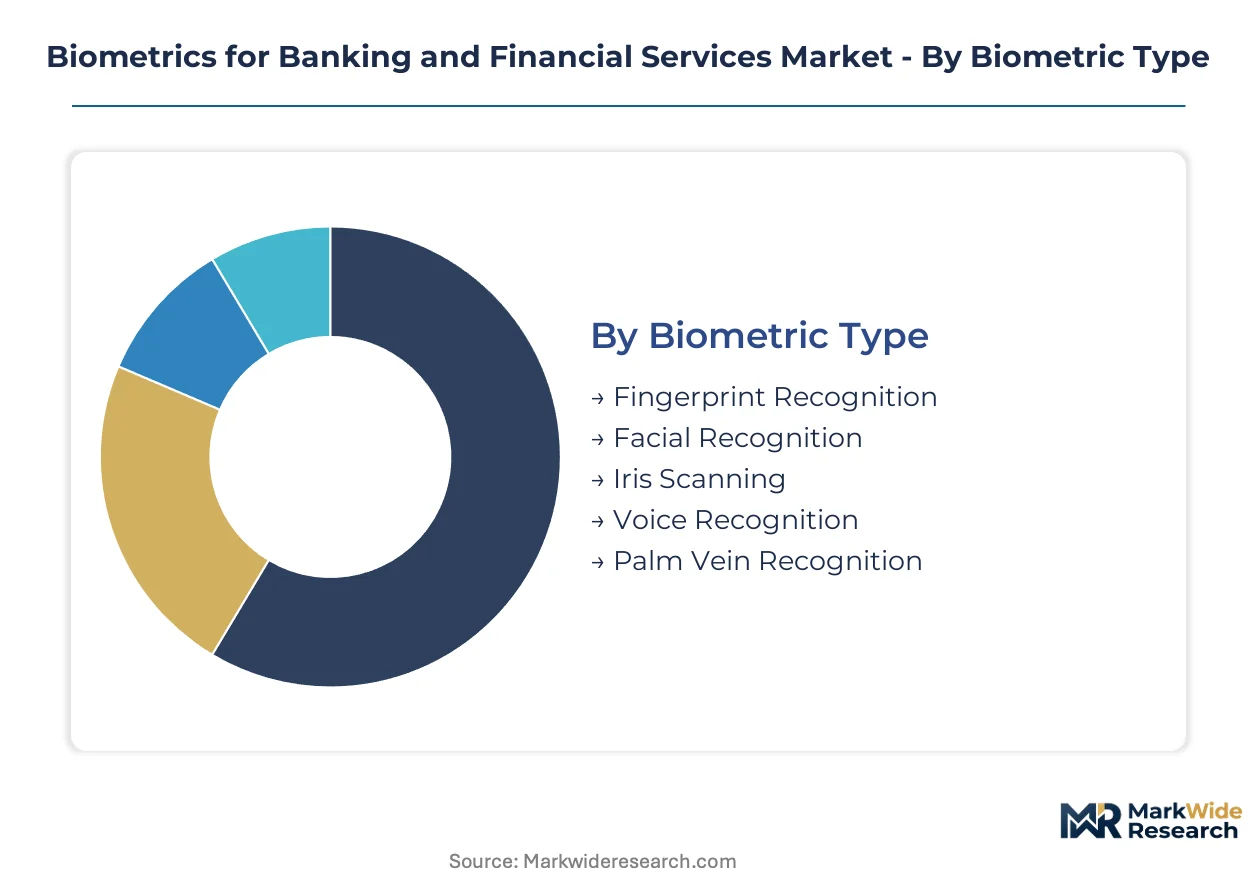
Financial institutions select biometric architectures based on transaction velocity, regulatory jurisdiction, and legacy infrastructure constraints. Segmentation reveals divergent investment patterns between tier-one retail banks prioritizing multimodal fusion and mid-tier cooperatives seeking cloud-native deployment without capital-intensive hardware procurement.
Biometric Type:
Cost tier differentiation separates mass-market fingerprint sensors from premium iris and palm vein systems requiring specialized hardware procurement.
- Fingerprint Recognition:Capacitive and ultrasonic sensors capture ridge patterns exceeding 500 dots per inch resolution. Retail banks in the United States and Germany deploy these modules across ATM networks and mobile banking applications due to decades of sensor cost reduction and established supply chains.
- Facial Recognition:Structured light and time-of-flight cameras map facial geometry with liveness detection against presentation attacks. Demand concentrates in Singapore and the United Arab Emirates where tier-one institutions pilot on-device authentication eliminating cloud transmission latency.
- Iris Scanning:Near-infrared imaging of unique trabecular mesh patterns enables contactless high-assurance verification at physical branch locations.
- Voice Recognition:Spectral analysis of vocal tract characteristics supports passive caller authentication in high-volume retail banking call centers.
- Palm Vein Recognition:Subcutaneous hemoglobin pattern detection offers spoof-resistant biometric capture for premium wealth management client onboarding.
Fingerprint recognition leads volumes today; facial recognition is gaining share fastest.
Authentication Mode:
Application criticality determines whether institutions deploy single-factor convenience or layered assurance for high-value wire transfers.
- Multi-Factor Authentication:Layered biometric and possession-based verification satisfies regulatory mandates for transactions exceeding specified thresholds. India's Reserve Bank requires this architecture for remote payment authorizations, compressing deployment timelines for domestic and foreign vendors seeking BIS certification.
- Two-Factor Authentication:Paired biometric and knowledge-based credentials balance security with user friction for routine account access.
- Behavioral Biometrics:Keystroke dynamics and gait analysis enable continuous risk scoring without explicit user action. Tier-one retail banks in France and Italy integrate these signals into real-time transaction monitoring systems to satisfy EU AI Act explainability requirements.
- Continuous Authentication:Persistent identity verification throughout session duration reduces session hijacking exposure for digital banking platforms.
- Passwordless Access:Biometric-only credentialing eliminates password reset costs and credential stuffing vulnerabilities for mobile-first banking applications.
Multi-factor authentication dominates transaction value protected; behavioral biometrics is expanding most quickly.
End User:
Customer type dictates procurement scale, with investment firms requiring sporadic high-assurance verification versus retail banks demanding millisecond-latency authentication at transaction volume.
- Retail Banks:Branch networks and digital channels require multimodal biometric infrastructure supporting millions of daily authentications. German and Dutch institutions prioritize vendors with established EU AI Act conformity assessment procedures.
- Credit Unions:Subscription-based biometric-as-a-service platforms bypass capital constraints for mid-tier cooperatives in the United States seeking authentication parity with larger competitors.
- Investment Firms:SEBI's digital KYC mandate in India extends biometric-linked verification requirements into brokerage and wealth management channels.
- Insurance Providers:Policyholder identity verification at claim submission reduces synthetic identity fraud in property and casualty lines.
- Payment Processors:ISO/IEC 19795-compliant biometric terminals standardize merchant acceptance infrastructure under India's Reserve Bank directives.
Retail banks anchor procurement volumes today; credit unions are climbing the fastest.
Deployment Model:
Maturity stage separates legacy on-premises installations from cloud-native architectures favored by institutions without mainframe-era technical debt.
- Cloud-Based Solutions:Subscription pricing eliminates upfront hardware expenditure while enabling elastic capacity for seasonal transaction peaks. Mid-tier retail banks and credit unions in North America disproportionately invest here to avoid capital-intensive infrastructure ownership.
- Hybrid Architecture:Sensitive template storage on-premises with compute-intensive matching in cloud environments balances data residency with scalability.
- On-Premises Systems:Air-gapped biometric infrastructure satisfies strict data sovereignty requirements in privacy-sensitive European jurisdictions.
- API Integration:Embedded biometric modules within core banking platforms reduce middleware development delays that otherwise extend deployment timelines.
- Edge Computing:On-device template processing eliminates round-trip latency and satisfies GDPR purpose limitation rules by preventing biometric data transmission.
On-premises systems retain installed base leadership; cloud-based solutions are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biometric engineering talent clusters in Germany, the United States, India, Singapore, and the United Arab Emirates anchor regional deployment patterns for financial authentication infrastructure.
United States
Credit unions and community banks drive cloud-native biometric procurement to match tier-one authentication standards without capital expenditure. The Federal Trade Commission enforces cybersecurity resilience testing through updated Safeguards Rule provisions. Austin and Charlotte host concentrated vendor development centers serving mid-tier cooperative banking networks.
Germany
Retail banking networks demand pre-certified biometric stacks satisfying EU AI Act conformity assessments for high-risk authentication decisions. The Bundesbank coordinates with BaFin to mandate explainable algorithm documentation for remote onboarding systems. Frankfurt's fintech corridor attracts algorithm vendors establishing European conformity assessment capabilities.
India
Payment terminal manufacturers and retail banks scale ISO/IEC 19795-compliant device deployment under Reserve Bank directives for biometric-linked transaction authorization. SEBI extends biometric KYC requirements into securities brokerage channels. Mumbai and Bengaluru concentrate vendor engineering operations serving domestic certification programs.
Singapore
Tier-one retail banks pilot on-device facial recognition eliminating cloud transmission latency for real-time transaction approval. The Monetary Authority of Singapore mandates operational resilience standards for critical digital infrastructure. The city-state's technology corridor hosts edge-computing biometric laboratories serving Southeast Asian expansion.
United Arab Emirates
Wealth management institutions deploy palm vein and iris systems for premium client onboarding in physical branch locations. The central bank's consumer protection framework shapes biometric consent and data retention protocols. Dubai International Financial Centre concentrates vendor regional headquarters serving Gulf Cooperation Council expansion.
Biometrics for Banking and Financial Services Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across authentication hardware and algorithm development. The vendor base separates into three strategic tiers: civil identity infrastructure operators, semiconductor-integrated module fabricators, and multimodal fusion software architects. Consolidation pressures intensify as EU AI Act compliance costs favor vendors with established conformity assessment procedures and cross-border data governance capabilities. Capacity expansion concentrates in cloud-native biometric-as-a-service platforms, while strategic partnerships between core banking vendors and authentication specialists compress deployment timelines for mid-tier institutions.
Within the civil identity infrastructure tier, IDEMIA anchors high-assurance banking contracts leveraging established government credentialing relationships. Thales Group exemplifies semiconductor-integrated positioning through chip-embedded fingerprint module supply chains. NEC Corporation occupies the multimodal fusion software tier, combining physiological and behavioral signal processing for tier-one retail banking deployments. These three entities represent divergent competitive archetypes: credentialing-led, hardware-integrated, and algorithm-specialized respectively.
| Leading Market Players |
|---|
| IDEMIA |
| Thales Group |
| NEC Corporation |
| Fujitsu Limited |
| Precise Biometrics |
| Nuance Communications |
| HID Global |
| Suprema |
| Fingerprint Cards |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between BIS-compliant hardware and uncertified commodity sensors splits both procurement economics and supplier qualification pathways across Indian payment terminals and European banking infrastructure. Premium-grade biometric modules command sustained margin premiums through ISO/IEC 19795 validation, while mid-tier credit unions in North America gravitate toward subscription SaaS models that externalize compliance burden.
Pricing Analysis
Bundled authentication-as-a-service offerings diverge sharply from unbundled perpetual-license procurement across buyer archetypes. Three-tier pricing structure across premium certified, standard integrated, and economy white-label tiers reflects ISO/IEC 19795 validation status and after-sales algorithm update commitments. Cost compression in economy fingerprint sensor tiers intensifies because East Asian contract manufacturers expand capacitive module capacity. Credit unions exhibit highest price sensitivity, while tier-one retail banks in Germany and Singapore prioritize certified stacks regardless of premium.
Supply Chain Analysis
Regional distribution centers in Singapore, Dubai, and Frankfurt anchor hub-and-spoke fulfillment patterns for biometric hardware across respective banking corridors. Sensor fabrication concentrates in Taiwan, South Korea, and China, while algorithm development clusters in Germany, the United States, and India. Supply chain risk centers on single-source vulnerability for ultrasonic fingerprint MEMS foundry capacity. Distribution runs through core banking vendor channel partnerships that bundle biometric APIs into broader digital transformation contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biometric vendors face a geographic-arbitrage imperative: EU AI Act compliance costs in Germany and France run substantially higher than India's BIS certification pathway, creating divergent capital efficiency profiles for equivalent authentication assurance.
For Market Incumbents: Hedge algorithmic obsolescence risk by deepening multimodal fusion R&D capabilities beyond facial-iris combinations into behavioral signal integration. Secure backward integration into edge-computing silicon design to reduce dependency on Taiwanese foundry allocation. Prioritize conformity assessment pre-certification in EU member states before competitor lock-in solidifies.
For New Entrants and Emerging Players: Capture credit union SaaS whitespace in the United States through API-native platforms that bypass legacy core banking middleware delays. Target India's SEBI-mandated securities KYC extension as the most penetrable adjacent vertical beyond traditional banking. Lead with voiceprint authentication for call center IVR systems where incumbent presence remains fragmented.
For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native biometric-as-a-service platforms serving mid-tier cooperatives, given subscription recurrence and lower customer acquisition friction versus hardware-heavy incumbents. Acquisition targets should demonstrate established BIS or EU AI Act conformity assessment procedures. Monitor Reserve Bank of India certification queue depth as inflection signal for vendor market share shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Pre-Certification | Accelerates procurement eligibility for German and Dutch retail banking networks. |
| Cloud-Native Biometric-as-a-Service Launch | Enables credit union market entry without capital-intensive hardware deployment. |
| Behavioral Biometrics Layer Integration | Satisfies tier-one bank demand for continuous authentication under FTC scrutiny. |
| Edge Computing Silicon Partnership | Reduces round-trip latency for Singapore and UAE on-device facial recognition pilots. |
| SEBI KYC Channel Extension | Captures biometric-linked investor verification mandate across Indian brokerage networks. |
Research Methodology
Direct dialogue with biometric algorithm engineers, retail bank CTOs, core banking platform product managers, and BIS certification auditors grounded qualitative findings in operational reality. Secondary validation drew from RBI circulars, EU AI Act implementation guidance, SEBI KYC directives, and SEC 10-K disclosures from listed authentication vendors. Bottom-up device shipment modeling and top-down banking IT spend analysis were cross-referenced for triangulation.
Segment-level value outputs across biometric type, authentication mode, and deployment model dimensions were generated through the projection horizon. CAGRs were derived from fitted growth curves incorporating regulatory mandate timelines, certification queue dynamics, and cloud adoption elasticity. Forecast inputs included tier-one bank R&D budget trajectories and credit union technology spend surveys.
Regulatory enforcement delays, sensor supply disruptions, and liveness detection technology leapfrogs are the dominant revision risks that could compress or extend modeled adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Mobile Banking Market
Banking
Singapore Neobanking Market
Banking
Third-Party Banking Software Market
Banking
US Retail Banking Market
Banking
Letter of Credit Confirmation Market
Banking
Global IoT in Banking and Financial Services Market
Banking
Canada Data Analytics in Banking Market
Banking
Global Neobanking Market
Banking
Performance Bank Guarantee Market
Banking
Blockchain in Banking Market
Banking
Onsite and Offsite Atms Market
Banking
Europe Banking-As-A-Service Market
Banking
Banking Tax Management Software Market
Banking
ATM Market
Banking
Germany Neobanking Market
Banking
Europe Data Analytics in Banking Market