
 ATM Market | 2026-2036
ATM Market Size, Share, and Industry Trends Forecast 2026-2036
ATM Market Intelligence
Chinese ATM manufacturing capacity is shifting toward intelligent terminals with integrated biometric modules. GRG Banking Equipment leverages its domestic supply chain to dominate intelligent cash recycler production. Diebold Nixdorf sustains its North American service infrastructure through dense technician networks. NCR Atleos anchors its position in managed services for retail bank branches across the United States.
An automated teller machine is a self-service banking terminal that authenticates users through card readers, PIN pads, or biometric sensors to execute cash withdrawal, deposit, balance inquiry, and fund transfer transactions. Multi-function ATMs lead product type value pools by consolidating deposit automation, check imaging, and cardless transaction capabilities. Off-site deployment in public places and hotel lobbies represents the fastest-growing installation category as banks reduce full-service branch footprints. Internet-based connectivity now dominates new installations, displacing legacy dial-up infrastructure.
PCI Security Standards Council frameworks govern terminal encryption and data protection requirements across deployed networks. The EU's GDPR and the US FFIEC authentication guidelines shape biometric data handling and multi-factor verification mandates. India's RBI financial inclusion directives and BIS certification standards for cash handling equipment accelerate rural deployment timelines. Stakeholders must monitor central bank digital currency pilots and their potential to redefine ATM transaction architectures.
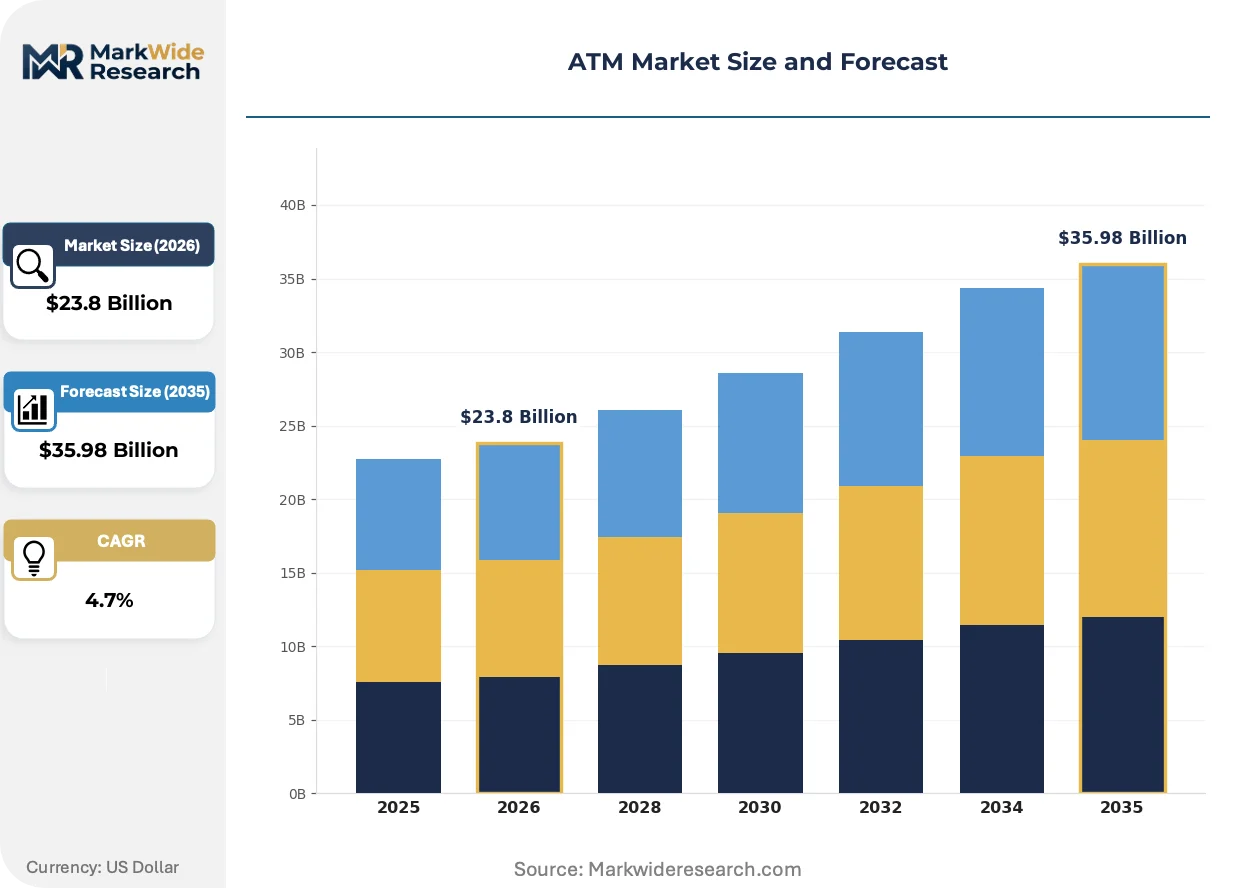
Market Dynamics
Biometric authentication mandates and contactless card standards are restructuring hardware procurement cycles, forcing manufacturers to redesign terminal architectures around fingerprint sensors and NFC modules while decommissioning legacy mag-stripe infrastructure.
Growth Catalysts
- RBI Financial Inclusion Directives:India's central bank mandates drive sustained deployment of off-site and mobile ATM units into unbanked rural districts, expanding addressable terminal base.
- Contactless Card Standards:EMVCo contactless specifications accelerate hardware refresh cycles across retail banking networks, requiring NFC-enabled reader modules in new installations.
- Southeast Asia Rural Networks:Banking consortiums in Indonesia, Vietnam, and the Philippines extend ATM access to agricultural communities previously excluded from formal financial services.
Market Restraints
- Semiconductor Component Volatility:Supply constraints for secure microcontrollers and biometric sensor chips inflate terminal manufacturing costs and extend lead times.
- GDPR Biometric Data Friction:The European Union's data protection framework imposes strict consent and storage protocols for fingerprint and facial recognition templates, complicating cross-border deployment.
- Mobile Payment Substitution:Smartphone-based digital wallets and QR-code transaction platforms reduce cash withdrawal frequency among urban consumer segments.
Strategic Opportunities
- Central Bank Digital Currency Integration:Pilot programs for CBDC cash-in/cash-out functionality at ATM terminals create new transaction architecture requirements in China, India, and Brazil.
- Managed Services Transition:Hardware-as-a-service contracts shift capital expenditure burdens from retail banks to equipment vendors, expanding recurring revenue pools.
- Intelligent Cash Recycler Convergence:Deposit automation technology merges with traditional dispensing functions, enabling branch staff reduction and 24-hour self-service operations.
Industry Challenges
- PCI-DSS Compliance Timeline:Terminal encryption upgrades to meet Payment Card Industry data security standards require coordinated fleet-wide software deployments and certification audits.
- Legacy System Integration:Core banking software from the 1990s lacks API compatibility with modern IoT-connected ATM networks, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ATM Market |
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $35.98 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cash Dispensers, Multi-function ATMs, Kiosk ATMs, Mobile ATMs End User: Retail Banks, Credit Unions, Independent Operators, Financial Institutions Deployment: On-premise, Off-site, Public Places, Hotel Lobbies Connectivity: Internet-based, Private Network, Dial-up, Satellite |
| Companies Covered | GRG Banking Equipment Co. Ltd., Nautilus Hyosung, Diebold Nixdorf, Inc., Fujitsu Ltd., OKI Electric Industry Co. Ltd., NCR Atleos, Triton Systems of Delaware LLC, HESS Cash Systems GmbH & Co KG, Hitachi-Omron Terminal Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ATM Market Strategic Shifts & Innovations
Edge computing architectures and cloud-native transaction processing are dismantling centralized host-dependent models, enabling real-time analytics and predictive maintenance capabilities at the terminal level.
Biometric authentication technology is decentralizing identity verification from bank-controlled databases to locally processed fingerprint and iris templates stored within tamper-resistant hardware security modules. Regional banks in Latin America and Southeast Asia deploy these terminals fastest, bypassing card issuance infrastructure entirely. This shift compresses fraud liability pools while expanding financial inclusion reach into populations lacking formal identification documents.
The EU's GDPR and the US FFIEC authentication guidelines impose divergent compliance burdens on multinational equipment suppliers. European mandates restrict biometric template storage duration and mandate explicit user consent mechanisms. American regulators emphasize multi-factor verification thresholds without prescribing specific data localization requirements. Vendors respond by developing modular firmware architectures that activate jurisdiction-specific privacy protocols based on terminal GPS coordinates.
After-sales service unbundling accelerates as retail banks separate hardware procurement from maintenance contracts, awarding multi-year managed service agreements to specialized third-party providers. This fragmentation disrupts traditional vendor-captive service models dominant in North American markets. Indian public sector banks lead this transition, tendering nationwide maintenance contracts independent of original equipment manufacturer relationships.
ATM Market Segmentation
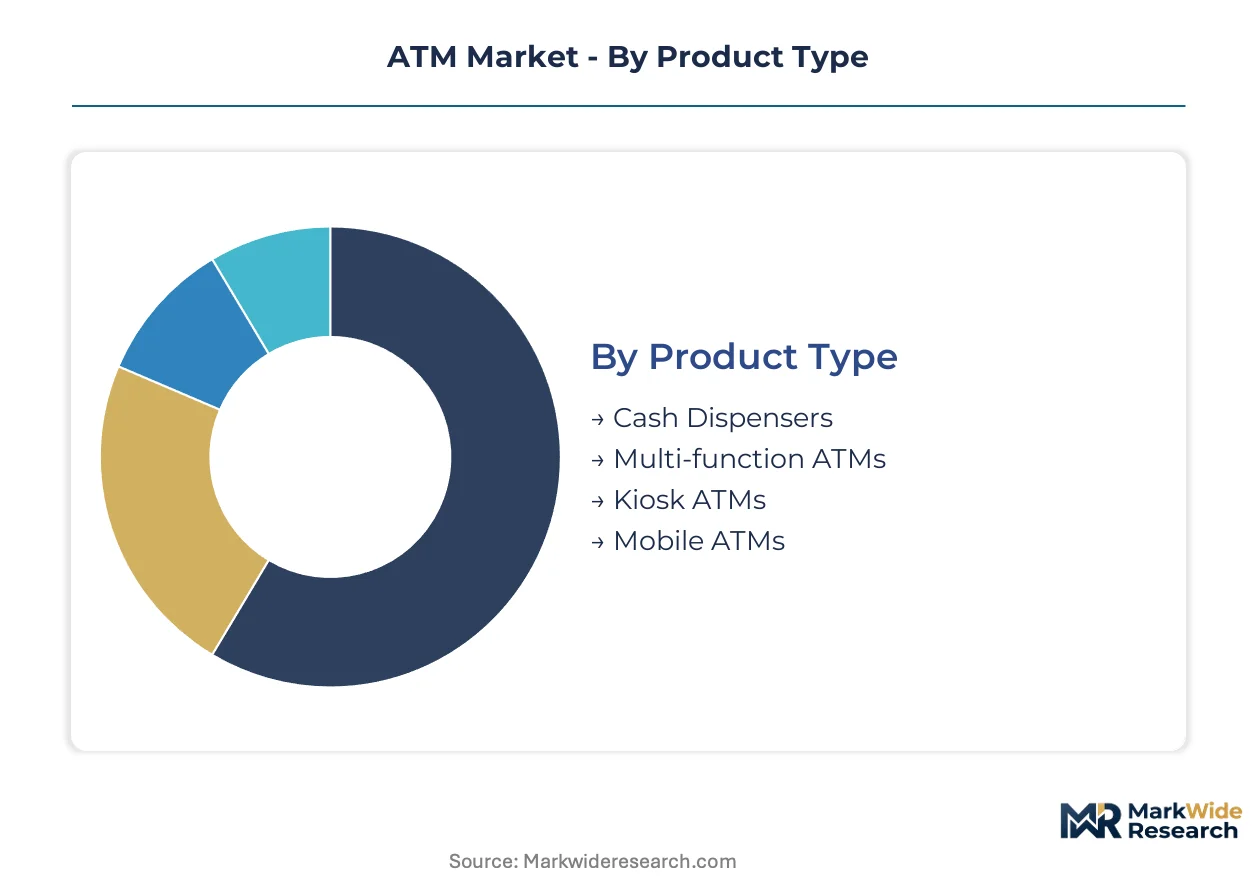
ATM procurement decisions pivot on transaction complexity, security mandates, and deployment economics. Terminal specifications vary sharply across rural inclusion programs and premium urban retail networks.
Product Type:
Bank procurement teams prioritize transaction throughput and cash handling automation when selecting terminal architectures.
- Multi-function ATMs:These terminals consolidate deposit automation, check imaging, and cardless transaction capabilities within a single hardware footprint. Indian public sector banks concentrate orders here under RBI financial inclusion mandates requiring deposit-taking functionality in rural deployments.
- Cash Dispensers:Single-purpose withdrawal terminals with simplified hardware stacks and lower per-unit procurement costs. Southeast Asian banking consortiums favor these for high-traffic urban corridors where deposit demand remains thin.
- Kiosk ATMs:Compact footprint terminals designed for space-constrained retail environments with reduced cash capacity.
- Mobile ATMs:Vehicle-mounted units serving temporary events, agricultural markets, and disaster relief zones.
Volume sits with Multi-function ATMs; growth tilts toward Mobile ATMs.
End User:
Capital allocation discipline and regulatory compliance burdens shape buyer profiles across institutional categories.
- Retail Banks:Full-service commercial banks deploy the largest terminal fleets with integrated biometric authentication and managed service contracts. These institutions drive NFC-enabled reader upgrades across Indonesian and Vietnamese networks.
- Independent Operators:Third-party deployers purchase white-label terminals for revenue-sharing placement in convenience stores and transit hubs. Their procurement concentrates on internet-based connectivity modules to minimize leased line costs.
- Credit Unions:Member-owned cooperatives with smaller fleet scales and longer replacement cycles.
- Financial Institutions:Catch-all category encompassing microfinance lenders and postal banking networks.
Terminal density peaks with Retail Banks; expansion rates favor Independent Operators.
Deployment:
Real estate economics and foot traffic patterns determine site selection strategies.
- Off-site:Terminals installed in non-bank locations including shopping centers, fuel stations, and transit terminals. These deployments are expanding most quickly as Indian and Brazilian banks reduce full-service branch footprints.
- Hotel Lobbies:Premium placement targeting business travelers with currency exchange and concierge-integrated services. Southeast Asian tourism corridors concentrate demand here.
- On-premise:Traditional branch-adjacent installations with dedicated security infrastructure.
- Public Places:Government building and hospital placements with accessibility mandates.
Installed base clusters in On-premise; the steepest expansion trajectory belongs to Off-site.
Connectivity:
Network architecture choices determine transaction latency, security exposure, and recurring telecommunications expenditure.
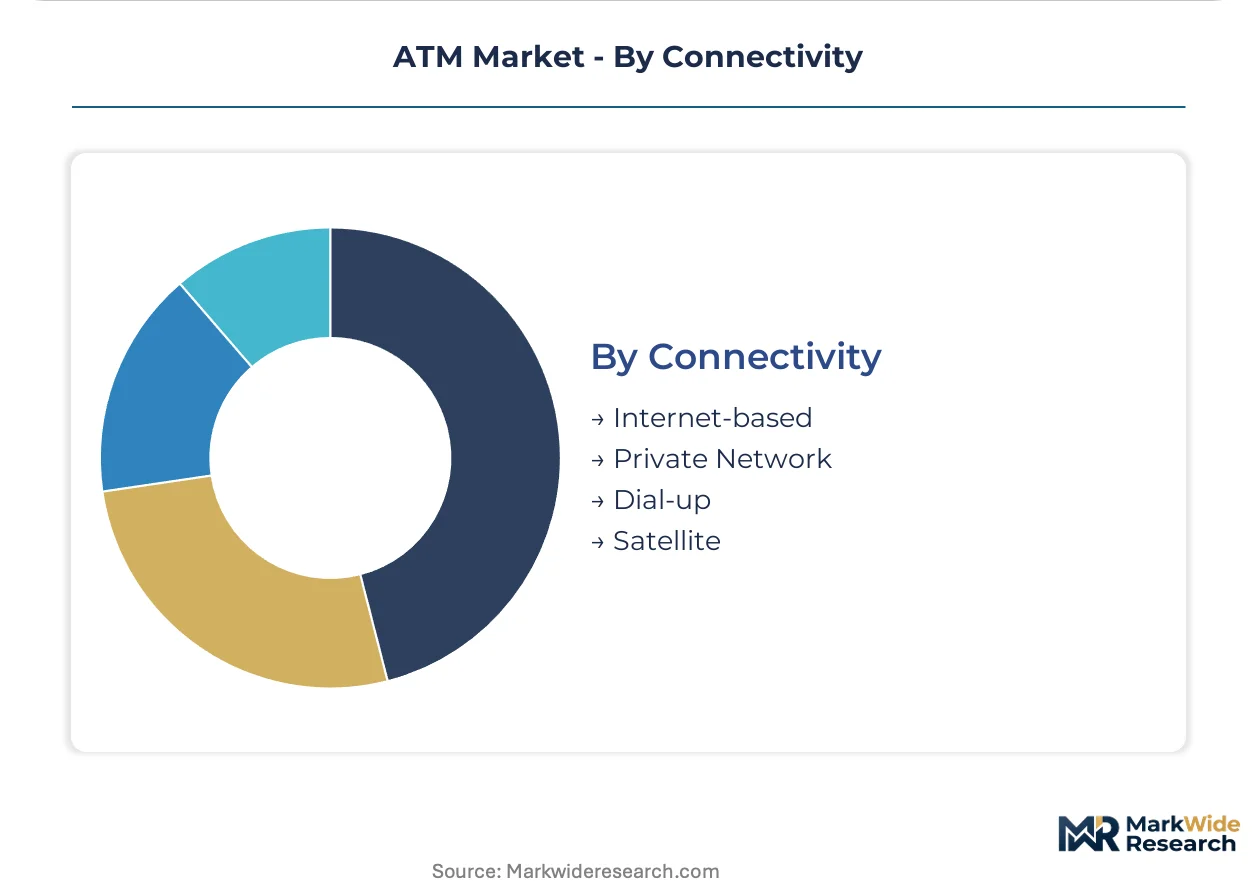
- Internet-based:IP-connected terminals now dominate new installations, enabling real-time fraud monitoring and cloud-native software updates. This architecture displaces legacy infrastructure across Latin American banking networks.
- Private Network:Leased-line connectivity for high-security deployments in government and defense contexts.
- Dial-up:Analog modem connections persisting in remote rural zones with limited broadband penetration.
- Satellite:Backup connectivity for mobile units and disaster recovery scenarios.
Deployment share concentrates in Internet-based; Satellite gains traction for contingency coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Secure microcontroller fabrication clusters in Taiwan and South Korea anchor ATM hardware supply chains for terminal manufacturers worldwide.
United States
Retail banks drive fleet modernization through managed service contracts and biometric authentication upgrades. The FFIEC multi-factor verification guidelines shape procurement specifications for NFC-enabled terminals. Dallas-Fort Worth concentrates service infrastructure where Diebold Nixdorf maintains dense technician networks for rapid-response maintenance coverage.
India
RBI financial inclusion mandates accelerate off-site and mobile ATM deployment into unbanked rural districts. BIS certification standards for cash handling equipment compress deployment timelines for domestic manufacturers. Mumbai and Bangalore cluster fintech partnerships where banking consortiums pilot CBDC cash-in/cash-out terminal architectures.
China
Intelligent cash recycler demand concentrates in state-owned banking networks replacing legacy dispensing infrastructure. The MIIT industrial standards for IoT-connected terminals accelerate edge computing adoption. Shenzhen and Guangzhou anchor manufacturing where GRG Banking Equipment leverages domestic supply chain integration for cost-competitive production.
Germany
GDPR biometric data restrictions complicate fingerprint-enabled terminal deployment across retail banking networks. The EU AI Act classification requirements for automated authentication systems impose additional compliance verification. Frankfurt and Munich concentrate banking headquarters where procurement teams evaluate hardware-as-a-service contract structures.
Brazil
Central bank digital currency pilot programs create new transaction architecture requirements for ATM terminal networks. The central bank's Pix instant payment integration mandates reshape connectivity module specifications. São Paulo anchors independent operator networks where third-party deployers expand convenience store and transit hub placements.
ATM Market Key Industry Players
Global majors compete with regional champions across service infrastructure density and supply chain integration depth. The vendor base separates into consolidated equipment manufacturers with captive service arms, specialized regional fabricators with government procurement relationships, and independent service organizations unbundling maintenance from hardware sales. Three archetypes dominate: integrated hardware-service providers, intelligent terminal specialists, and white-label OEM suppliers. Competitive moves concentrate on managed services transitions and biometric module integration partnerships.
Within the integrated hardware-service tier, Diebold Nixdorf and NCR Atleos exemplify North American-centric service infrastructure models. GRG Banking Equipment represents Chinese supply chain-anchored manufacturing scale. These three occupy distinct competitive positions without overlapping geographic dominance.
| Leading Market Players |
|---|
| GRG Banking Equipment Co. Ltd. |
| Nautilus Hyosung |
| Diebold Nixdorf, Inc. |
| Fujitsu Ltd. |
| OKI Electric Industry Co. Ltd. |
| NCR Atleos |
| Triton Systems of Delaware LLC |
| HESS Cash Systems GmbH & Co KG |
| Hitachi-Omron Terminal Solutions |
| Others |
Cost & Logistics Intelligence
Indian public sector banks concentrate procurement volumes under RBI financial inclusion mandates, anchoring contract-based pricing with multi-year managed service bundles that shift capital expenditure to operational expenditure models.
Pricing Analysis
Warranty and maintenance bundling separates captive service contracts from unbundled third-party maintenance agreements. Three-tier pricing structure across premium intelligent recyclers, standard multi-function terminals, and economy cash dispensers reflects biometric module integration depth and deposit automation capability. Cost compression in economy tiers intensifies because semiconductor component volatility inflates secure microcontroller procurement. Independent operators exhibit highest price sensitivity due to thin revenue-sharing margins, while state-owned banks absorb premium pricing for compliance-certified hardware.
Supply Chain Analysis
Workforce availability constraints in Shenzhen and Guangzhou manufacturing clusters tighten production scheduling for edge computing modules and biometric sensor integration. Taiwan and South Korea anchor secure microcontroller fabrication, while China dominates intelligent terminal assembly and cash handling mechanism production. The supply chain draws from specialized optical sensor suppliers, precision metal fabricators, and tamper-resistant hardware security module foundries. Single-source vulnerability concentrates in biometric chip supply where qualified vendors remain limited. Distribution runs through OEM-direct channels for retail banks and specialized ATM deployers for independent operator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as managed services transitions force smaller regional fabricators to exit or sell to integrated hardware-service providers with captive maintenance infrastructure.
For Market Incumbents: Extend service infrastructure density through technician network expansion in North American and Indian markets where rapid-response maintenance contracts determine procurement outcomes. Deepen backward integration into biometric sensor supply chains to mitigate semiconductor volatility exposure. Prioritize firmware modularity investments that activate jurisdiction-specific privacy protocols for GDPR and RBI compliance without hardware redesign. For New Entrants and Emerging Players: Independent service organizations represent the most penetrable channel partner type for unbundling maintenance from legacy OEM relationships. Target white-label manufacturing contracts for Southeast Asian banking consortiums extending rural ATM access. Pursue hardware-as-a-service contract structures that shift capital burden to vendor balance sheets and differentiate against traditional equipment sales models. For Investors and Strategic Acquirers: The window for entry favors intelligent terminal specialists with biometric module integration capabilities and established BIS or PCI-DSS certification pathways. Long-term viability hinges on positioning for central bank digital currency pilot participation across India, Brazil, and China. Monitor CBDC cash-in/cash-out terminal architecture mandates as the primary inflection signal for hardware refresh cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Module Integration Partnership | PCI-DSS certification for fingerprint-enabled terminals unlocks Indian and Southeast Asian rural banking procurement. |
| Managed Services Contract Expansion | Hardware-as-a-service structures capture recurring revenue from retail banks reducing branch footprints. |
| Edge Computing Architecture Deployment | Cloud-native transaction processing enables real-time fraud monitoring and predictive maintenance capabilities. |
| CBDC Terminal Architecture Development | Pilot program participation in India and Brazil positions vendors for central bank digital currency integration mandates. |
| Third-Party Maintenance Network Buildout | Unbundled service contracts disrupt OEM-captive models and capture Indian public sector bank tender volumes. |
Research Approach
Independent corroboration across primary interviews with ATM procurement managers, managed services contract directors, biometric technology suppliers, and central bank payment system officials underwrites the qualitative findings. Secondary validation draws from RBI circulars on financial inclusion directives, PCI Security Standards Council framework documentation, EMVCo contactless specifications, and BIS certification standards for cash handling equipment. Bottom-up terminal deployment estimates triangulate against top-down banking network expansion projections.
Comparable-period anchoring to historical ATM installation data across rural inclusion programs and urban branch reduction initiatives structures the projection horizon. The analytical framework segments by product type, deployment category, connectivity architecture, and end-user institutional category. CAGRs derive from fitted growth curves calibrated to central bank payment infrastructure reports and banking consortium expansion disclosures. Forecast inputs incorporate semiconductor lead time fluctuations and regulatory mandate implementation timelines.
Several conditions sit outside the modeled scope, including central bank digital currency pilot abandonment, biometric data regulation reversal in the European Union, and sustained mobile payment substitution exceeding current trajectory assumptions. Forecasts reflect documented assumptions about RBI mandate continuity and contactless card standard adoption rates. Material deviation in semiconductor supply normalization or GDPR enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Cybersecurity in Banking Market
Banking
Singapore Neobanking Market
Banking
Video Banking Service Market
Banking
Cloud Computing Banking Market
Banking
Global Banking BPS Market
Banking
US Investment Banking Market
Banking
Middle East Data Analytics in Banking Market
Banking
US Data Analytics in Banking Market
Banking
Corporate Digital Banking Market
Banking
Germany Neobanking Market
Banking
India Data Analytics in Banking Market
Banking
Retail Banking IT Spending Market
Banking
Latin America Neo Banking Services Market
Banking
Data Analytics in Banking Market
Banking
Bank Management Software Market
Banking
South Korea Data Analytics in Banking Market