
 Disaster Recovery in Banking Market | 2026-2036
Disaster Recovery in Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Disaster Recovery in Banking Market Analysis
Cloud architecture expertise is bifurcating the competitive landscape, with institutions struggling to staff hybrid infrastructure roles even as spending accelerates. Microsoft Corporation leverages its Azure Stack portfolio to anchor on-premises-to-cloud failover pathways for tier-one banks. IBM Corporation sustains mainframe-centric recovery franchises through deeply embedded Z-series replication protocols. Amazon Web Services competes aggressively on price-performance for cloud-native backup, extending its GovCloud enclaves to satisfy financial services compliance.
Disaster recovery in banking encompasses the policies, tools, and infrastructure that financial institutions deploy to restore critical systems, data integrity, and transactional continuity following cyber incidents, natural catastrophes, or operational failures. Core specifications include recovery time objectives under four hours for payment systems and recovery point objectives near zero for real-time ledger databases, with primary purpose centered on maintaining depositor confidence and systemic stability. Cloud recovery services now lead value creation as banks migrate from tape-based archives to immutable object storage with automated orchestration, while hybrid deployment architectures capture the fastest expansion by reconciling regulator-mandated data locality with elasticity needs. Business continuity planning retains mature, high-margin characteristics due to bespoke consulting engagements and regulatory audit dependencies.
The US Federal Reserve, the European Banking Authority through its Digital Operational Resilience Act framework, and the UK's Prudential Regulation Authority collectively shape demand by mandating stress-tested recovery playbooks and third-party risk governance. Institutions in multi-jurisdictional footprints must navigate overlapping compliance regimes that specify divergent data residency, testing frequency, and vendor concentration limits. Stakeholders should monitor how artificial intelligence-driven anomaly detection integrates with legacy failover workflows, as this convergence will determine which technology suppliers retain strategic relevance in bank procurement cycles.
Market Dynamics
Cloud recovery adoption is fragmenting vendor hierarchies as tier-one banks abandon tape-based archives for immutable object storage with automated orchestration, forcing infrastructure providers to re-architect failover pathways around hybrid latency requirements and data-sovereignty mandates.
Growth Catalysts
- US Federal Reserve operational resilience guidance:Commercial banks across the United States are expanding cloud recovery investments to satisfy intensified stress-testing mandates for payment system continuity.
- Hybrid deployment architectures:Institutions in Germany and the United Kingdom balance regulatory data-locality requirements with elasticity needs through bifurcated on-premises-to-cloud failover configurations.
- Real-time ledger databases:Near-zero recovery point objectives for transactional systems are driving demand for automated orchestration layers that compress restoration windows.
Market Restraints
- Cloud architecture expertise scarcity:Staffing gaps for hybrid infrastructure roles are widening even as institutional spending accelerates, creating execution bottlenecks for failover pathway deployment.
- Multi-jurisdictional compliance friction:Overlapping regimes from the US Federal Reserve, European Banking Authority, and UK Prudential Regulation Authority impose divergent data residency and testing frequency requirements.
- Vendor concentration limits:Regulatory caps on third-party risk exposure restrict single-supplier dependencies for critical recovery functions.
Strategic Opportunities
- Artificial intelligence-driven anomaly detection:Convergence of machine learning with legacy failover workflows creates white space for suppliers that integrate predictive failure signaling into orchestration platforms.
- GovCloud enclave expansion:Financial services compliance requirements are opening specialized cloud partitions with hardened security boundaries for classified transactional data.
- Bespoke consulting engagements:Regulatory audit dependencies sustain high-margin business continuity planning services tied to stress-tested recovery playbook certification.
Industry Challenges
- Mainframe-centric recovery integration:Deeply embedded Z-series replication protocols resist cloud-native displacement, forcing hybrid architectures to accommodate legacy replication semantics.
- Cross-border data synchronization:Jurisdictional fragmentation in data-sovereignty mandates complicates real-time ledger consistency across national failover sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disaster Recovery in Banking Market |
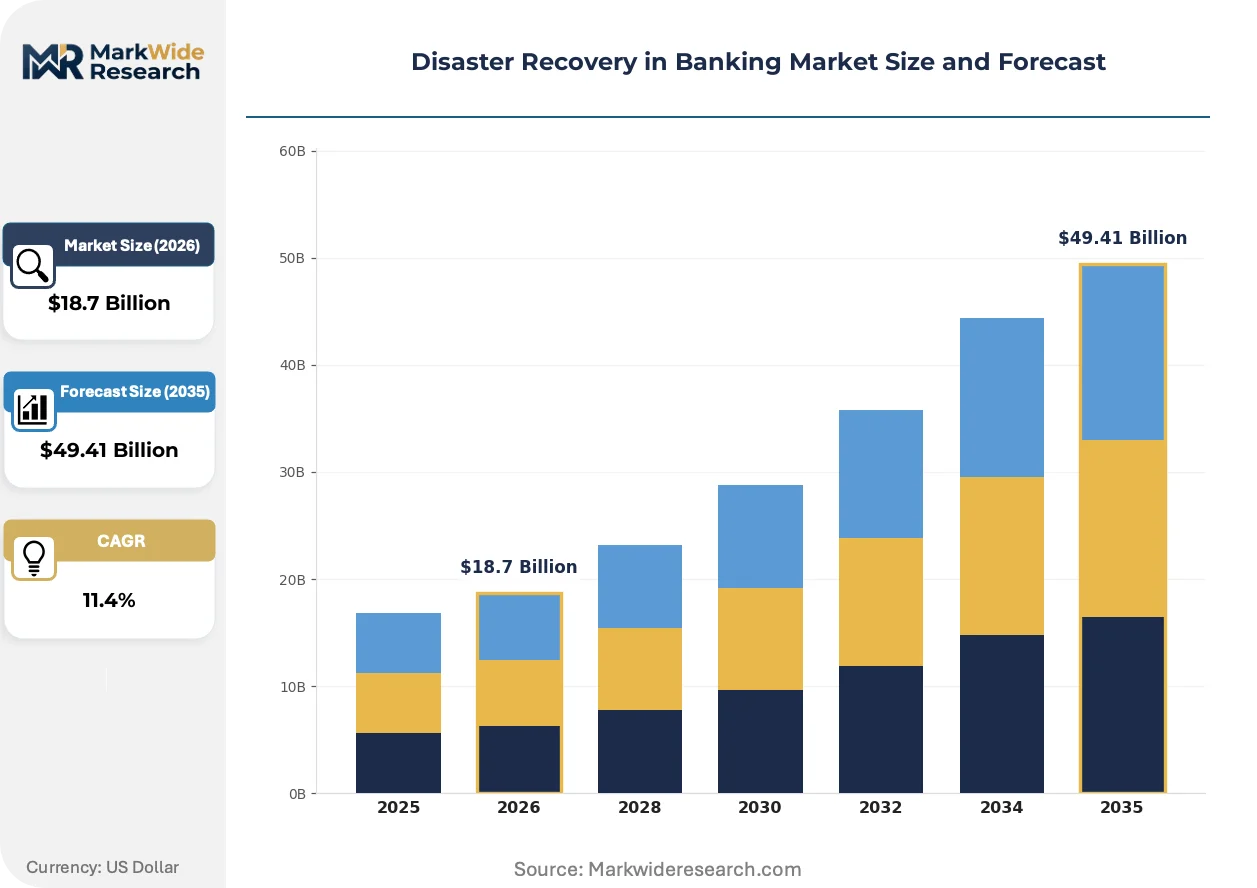
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Backup Solutions, Data Recovery Services, Cloud Recovery, Business Continuity Planning Deployment: On-Premises, Hybrid, Cloud-Based, Managed Services End User: Commercial Banks, Investment Banks, Credit Unions, Asset Management Firms Technology: Virtualization, Software as a Service, Disaster Recovery as a Service, Data Replication |
| Companies Covered | Microsoft Corporation, International Business Machines (IBM) Corporation, VMware Inc., Amazon Web Services (AWS), Veeam, Commvault, Acronis, Cisco, Zerto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disaster Recovery in Banking Market Emerging Trajectories
Immutable object storage with automated orchestration is actively displacing decades-old tape-based recovery paradigms, compressing restoration timelines while introducing new complexity around hybrid latency optimization and sovereignty-compliant routing.
Immutable object storage systems replicate transactional data across geographically distributed nodes with cryptographic integrity verification. Tier-one banks in the United States and United Kingdom are deploying these systems for sub-hour recovery time objectives. This architecture is displacing magnetic tape archives and manual restoration procedures that previously dominated bank disaster recovery programs.
The European Banking Authority's Digital Operational Resilience Act framework mandates stress-tested recovery playbooks with defined third-party risk governance protocols. Financial institutions must document failover pathways for critical business functions and demonstrate quarterly testing frequency. Banks in Germany and France are responding by consolidating vendor relationships and demanding contractual uptime guarantees with penalty clauses.
Outcome-based contracting for recovery services is compressing traditional procurement cycles as institutions shift from capital-intensive infrastructure ownership to operational expenditure models. Managed service providers are displacing in-house disaster recovery teams through guaranteed restoration service level agreements. This behavioral shift is most visible among mid-tier commercial banks in the United States seeking to reduce fixed infrastructure costs while maintaining regulatory compliance.
Disaster Recovery in Banking Market Segmentation
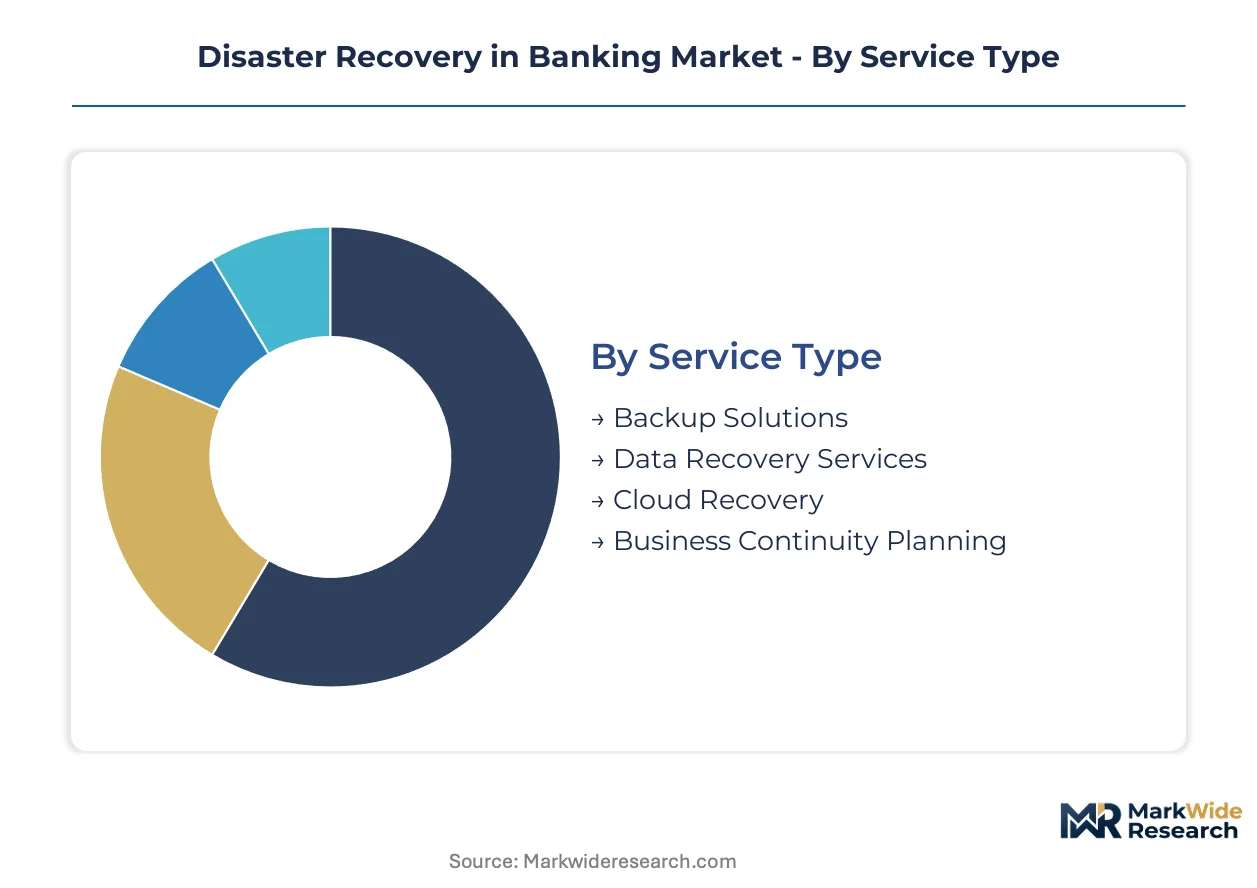
Bank procurement cycles for disaster recovery diverge sharply across service modalities and infrastructure footprints, with regulatory mandates forcing institutions to maintain parallel capabilities rather than consolidate on single-vendor stacks. Channel dynamics vary by segment complexity, from self-service cloud portals to multi-year consulting engagements requiring audit-certified delivery partners.
Service Type:
Channel mix bifurcates between automated platform delivery for standardized backup workloads and partner-mediated consulting for compliance-intensive planning services.
- Backup Solutions:Immutable object storage architectures with cryptographic integrity verification compress restoration windows for transactional databases. Commercial banks in the United States deploy these for sub-four-hour recovery time objectives mandated by Federal Reserve guidance.
- Cloud Recovery:Automated orchestration layers spanning on-premises-to-cloud failover pathways reconcile latency requirements with data-sovereignty constraints. Demand concentrates among tier-one institutions navigating multi-jurisdictional compliance regimes.
- Data Recovery Services:Specialized forensic restoration for corrupted ledger databases following ransomware incidents.
- Business Continuity Planning:Bespoke consulting engagements tied to regulatory audit dependencies and stress-tested playbook certification.
Backup solutions dominate installed base. Cloud recovery is where expansion concentrates.
Deployment:
Cost tier stratification separates capital-intensive owned infrastructure from operational expenditure models favored by mid-tier institutions seeking fixed-cost predictability.
- Hybrid:Bifurcated architectures partition real-time transactional workloads on-premises while archiving to cloud object storage for geographic redundancy. German and United Kingdom institutions favor this configuration to satisfy regulatory data-locality mandates without sacrificing elasticity.
- Managed Services:Outcome-based contracting with guaranteed restoration service level agreements displaces in-house disaster recovery teams. Mid-tier commercial banks adopt these arrangements to reduce fixed infrastructure overhead while maintaining compliance.
- On-Premises:Legacy mainframe-centric replication protocols for Z-series environments resisting cloud-native displacement.
- Cloud-Based:Native immutable storage with automated failover for greenfield digital banking platforms.
On-premises retains mature, high-margin characteristics in mainframe-dependent institutions. Managed services are climbing the fastest among commercial banks seeking procurement flexibility.
End User:
Application complexity scales with transactional velocity and regulatory scrutiny, driving divergent recovery point objective specifications across institutional categories.
- Commercial Banks:Payment system continuity mandates under Federal Reserve operational resilience guidance demand sub-four-hour recovery time objectives with near-zero recovery point objectives for real-time ledgers. These institutions represent the primary demand concentration for hybrid deployment architectures.
- Investment Banks:Cross-border trading infrastructure requires synchronized failover across multiple sovereign jurisdictions with divergent data residency requirements.
- Credit Unions:Member-owned institutions with constrained capital budgets favor managed service consumption models over owned infrastructure.
- Asset Management Firms:Portfolio accounting systems with end-of-day batch processing tolerate longer restoration windows than transactional banking.
Commercial banks command the largest absolute spending. Investment banks are gaining share fastest as trading infrastructure modernization accelerates.
Technology:
Supply concentration among hyperscale cloud providers is forcing traditional infrastructure vendors to re-architect around API-compatible orchestration layers.
- Disaster Recovery as a Service:Subscription-based failover automation with pre-configured runbook orchestration and penalty-backed uptime guarantees. Financial services compliance requirements are opening specialized GovCloud enclaves with hardened security boundaries.
- Data Replication:Synchronous and asynchronous replication protocols for transactional database consistency across geographically distributed nodes. Deeply embedded Z-series replication semantics resist displacement in legacy mainframe environments.
- Virtualization:Abstracted compute recovery for x86 workload portability between on-premises and cloud substrates.
- Software as a Service:Cloud-native backup management platforms with consumption-based pricing for mid-market institutions.
Data replication anchors legacy infrastructure continuity. Disaster Recovery as a Service represents the steepest expansion trajectory as institutions abandon capital-intensive ownership models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Federal Reserve anchors regulatory momentum through intensified operational resilience guidance, while commercial banks across Germany and the United Kingdom navigate overlapping data-sovereignty mandates. Procurement cycles diverge sharply as institutions reconcile latency requirements with jurisdictional compliance.
United States
Commercial banks dominate absolute spending on hybrid failover architectures. The Federal Reserve mandates sub-four-hour recovery time objectives for payment system continuity. New York and Chicago financial clusters anchor demand concentration for automated orchestration layers.
Germany
Tier-one institutions bifurcate transactional workloads between on-premises infrastructure and cloud archives. The European Banking Authority's Digital Operational Resilience Act imposes quarterly testing frequency with documented third-party risk governance. Frankfurt's banking hub drives consolidation of vendor relationships with contractual uptime guarantees.
United Kingdom
The Prudential Regulation Authority shapes procurement through stress-tested recovery playbook requirements. London-based investment banks synchronize failover across multiple sovereign jurisdictions with divergent data residency rules. Hybrid deployment architectures capture fastest expansion as institutions balance regulatory data-locality with elasticity needs.
Japan
Financial institutions maintain deeply embedded mainframe-centric recovery protocols resisting cloud-native displacement. METI guidance emphasizes operational continuity for systemic banking functions. Tokyo's financial district sustains demand for Z-series replication semantics alongside emerging hybrid configurations.
India
Mid-tier commercial banks favor managed service consumption models over capital-intensive infrastructure ownership. RBI operational resilience frameworks mandate documented failover pathways for critical business functions. Mumbai and Bengaluru clusters anchor adoption of subscription-based disaster recovery services with penalty-backed uptime guarantees.
Disaster Recovery in Banking Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with hyperscale cloud providers and legacy infrastructure vendors competing for failover pathway dominance. The competitive terrain bifurcates between subscription-based orchestration platforms and embedded mainframe replication franchises. Two strategic archetypes define positioning: cloud-native automation specialists and mainframe-anchored continuity incumbents. Dominant competitive moves include GovCloud enclave expansion to satisfy financial services compliance and bespoke consulting engagements tied to regulatory audit dependencies.
Within the integrated leader tier, Microsoft Corporation and International Business Machines Corporation occupy positions spanning cloud-native and legacy infrastructure domains. Microsoft Corporation exemplifies the cloud automation archetype through Azure Stack portfolio deployment for tier-one bank failover pathways. International Business Machines Corporation anchors mainframe-centric recovery franchises through deeply embedded replication protocols. Amazon Web Services sits within the price-performance competitive vector, extending specialized cloud partitions for classified transactional data. VMware Inc. represents hybrid infrastructure positioning, bridging on-premises and cloud substrates for latency-sensitive workloads.
| Leading Market Players |
|---|
| Microsoft Corporation |
| International Business Machines (IBM) Corporation |
| VMware Inc. |
| Amazon Web Services (AWS) |
| Veeam |
| Commvault |
| Acronis |
| Cisco |
| Zerto |
| Others |
Supply Flow & Price Mechanics
Outcome-based contracting with penalty-backed uptime guarantees locks in multi-year supply relationships for tier-one banks while compressing price visibility into fixed operational expenditure commitments. This structure concentrates procurement leverage among institutions with sufficient balance-sheet depth to negotiate contractual service level agreements across hybrid cloud and on-premises failover pathways.
Pricing Analysis
Long-term offtake arrangements dominate tier-one bank procurement, with subscription-based disaster recovery as a service compressing legacy capital-intensive licensing models. Price differentiation hinges on certification tier—FedRAMP-authorized GovCloud enclaves command substantial premiums over standard commercial partitions—and geographic redundancy scope, with multi-jurisdictional failover configurations carrying material uplifts. Pricing pressure stems from hyperscale cloud providers competing aggressively on compute-storage bundles, eroding margins for pure-play orchestration vendors. Mid-tier commercial banks exhibit acute price sensitivity, prioritizing fixed-cost predictability over performance optimization, while investment banks tolerate premium positioning for sub-hour recovery time objective guarantees.
Supply Chain Analysis
Strategic stockpiling of cryptographic key management infrastructure and dedicated network capacity characterizes bank supply chain posture, diverging from just-in-time norms prevalent in less regulated sectors. Geographic supply concentration centers on the United States, Germany, and the United Kingdom, where hyperscale cloud regions and financial services regulatory frameworks co-locate. The supply chain draws from specialized semiconductor components for hardware security modules, submarine cable capacity for cross-border replication, and certified personnel pools for audit-compliant deployment. Single-source vulnerability in mainframe Z-series replication protocols creates structural dependency on legacy infrastructure vendors. Distribution runs through direct enterprise sales teams and certified systems integrators with regulatory audit credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent disaster recovery vendors face substitution pressure from cloud-native automation platforms that displace embedded mainframe replication franchises through API-compatible orchestration layers.
For Market Incumbents: Fortify hybrid infrastructure positioning by deepening Z-series protocol integration with Azure Stack and AWS Outposts deployments, neutralizing cloud-native displacement. Invest in FedRAMP and European Banking Authority certification pipelines to defend GovCloud enclave access against emerging competitors. Prioritize outcome-based contracting capabilities to match hyperscaler pricing transparency. For New Entrants and Emerging Players: Lead with artificial intelligence-driven anomaly detection convergence, targeting mid-tier commercial banks in India and the United States where managed service consumption models outpace owned infrastructure adoption. Emphasize subscription-based orchestration with penalty-backed uptime guarantees to bypass capital-intensive procurement cycles. Position through certified systems integrators with existing regulatory audit relationships. For Investors and Strategic Acquirers: Capital is best deployed toward hybrid infrastructure specialists bridging mainframe replication semantics with cloud-native failover automation, capturing the longest-dated substitution window across the analysis window. Monitor artificial intelligence integration velocity as the primary inflection signal—vendors demonstrating predictive failure signaling capabilities will consolidate procurement preference.| Strategic Initiative | Industry Significance |
|---|---|
| GovCloud Enclave Expansion | FedRAMP-authorized partitions satisfy US Federal Reserve compliance for classified transactional data. |
| Outcome-Based Contracting | Penalty-backed uptime guarantees displace capital-intensive infrastructure ownership among mid-tier banks. |
| Artificial Intelligence Integration | Predictive anomaly detection converges with legacy failover workflows to compress restoration windows. |
| Hybrid Architecture Certification | European Banking Authority audit credentials unlock German and United Kingdom procurement cycles. |
| Mainframe Protocol Modernization | API-compatible Z-series replication layers defend against cloud-native displacement in Japan and US East Coast clusters. |
Methodological Framework
Operator-level perspectives from chief technology officers, infrastructure resilience officers, regulatory compliance leads at tier-one commercial banks, and procurement managers at managed service providers anchored the qualitative base. These primary insights combined with secondary validation from US Federal Reserve guidance documents, European Banking Authority Digital Operational Resilience Act frameworks, UK Prudential Regulation Authority consultation papers, and hyperscaler financial services compliance disclosures. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across service type, deployment architecture, end-user category, and technology modality dimensions.
Sensitivity analysis tested forecast robustness across alternative regulatory implementation timelines and cloud adoption velocity scenarios over the projection horizon. The analytical framework modeled service type segmentation—backup solutions, cloud recovery, data recovery services, business continuity planning—against deployment configurations spanning hybrid, managed services, on-premises, and cloud-based alternatives. CAGR derivation incorporated bank IT spending elasticity coefficients, regulatory compliance cost pass-through rates, and substitution dynamics between tape-based archives and immutable object storage.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement intensity or accelerated hyperscaler price competition would require recalibration. Forecasts reflect assumptions regarding European Banking Authority implementation consistency and US Federal Reserve operational resilience guidance continuity. Revision becomes warranted when artificial intelligence integration timelines for failover orchestration cross adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Global Chatbot for Banking Market
Banking
Middle East Data Analytics in Banking Market
Banking
United Kingdom Data Analytics in Banking Market
Banking
Banking As a Service (BAAS) Market
Banking
Banking Credit Analytics Market
Banking
US Data Analytics in Banking Market
Banking
Global IoT in Banking and Financial Services Market
Banking
Core Banking Solutions Market
Banking
Blockchain in Retail Banking Market
Banking
Banking Software Market
Banking
Brazil Retail Banking Market
Banking
Germany Neobanking Market
Banking
Banking Tax Management Software Market
Banking
Middle East and Africa Neobanking Market
Banking
Corporate Banking Market
Banking
Internet of Things (IoT) in Banking Market