
 Medical Products Market | 2026-2036
Medical Products Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Products Market Analysis
Biomedical engineering talent is rotating toward robotics and digital health specializations, constraining traditional device manufacturing pipelines. Medtronic leverages its integrated surgical robotics platform to anchor premium positioning in minimally invasive procedures. Johnson & Johnson sustains broad portfolio depth across orthopedics and electrophysiology, while Siemens Healthineers dominates diagnostic imaging through AI-enhanced modality development.
Medical products encompass instruments, apparatus, implants, and consumables engineered to diagnose, monitor, treat, or prevent disease, typically manufactured under ISO 13485 quality management systems with biocompatibility validation per ISO 10993. These products serve acute care, chronic disease management, and preventive medicine across institutional and ambulatory settings. Diagnostics and surgical instruments command the largest revenue pools, reflecting recurring consumable demand and capital replacement cycles. Robotics and telemedicine represent the fastest-expanding technology segments, driven by labor cost pressures and post-acute care decentralization.
FDA premarket approval and EU MDR notified body conformity assessments shape product development timelines and market access costs for manufacturers. Japan's PMDA and China's NMPA impose additional localization requirements that favor regional production footprints. Stakeholders must monitor regulatory divergence between FDA's quality management system harmonization efforts and EU MDR's heightened clinical evidence demands when allocating R&D and commercial resources.
Market Dynamics
Hospital procurement of connected surgical systems is accelerating as health systems modernize operating suites under capital replacement cycles and reimbursement stability pressures.
Growth Catalysts
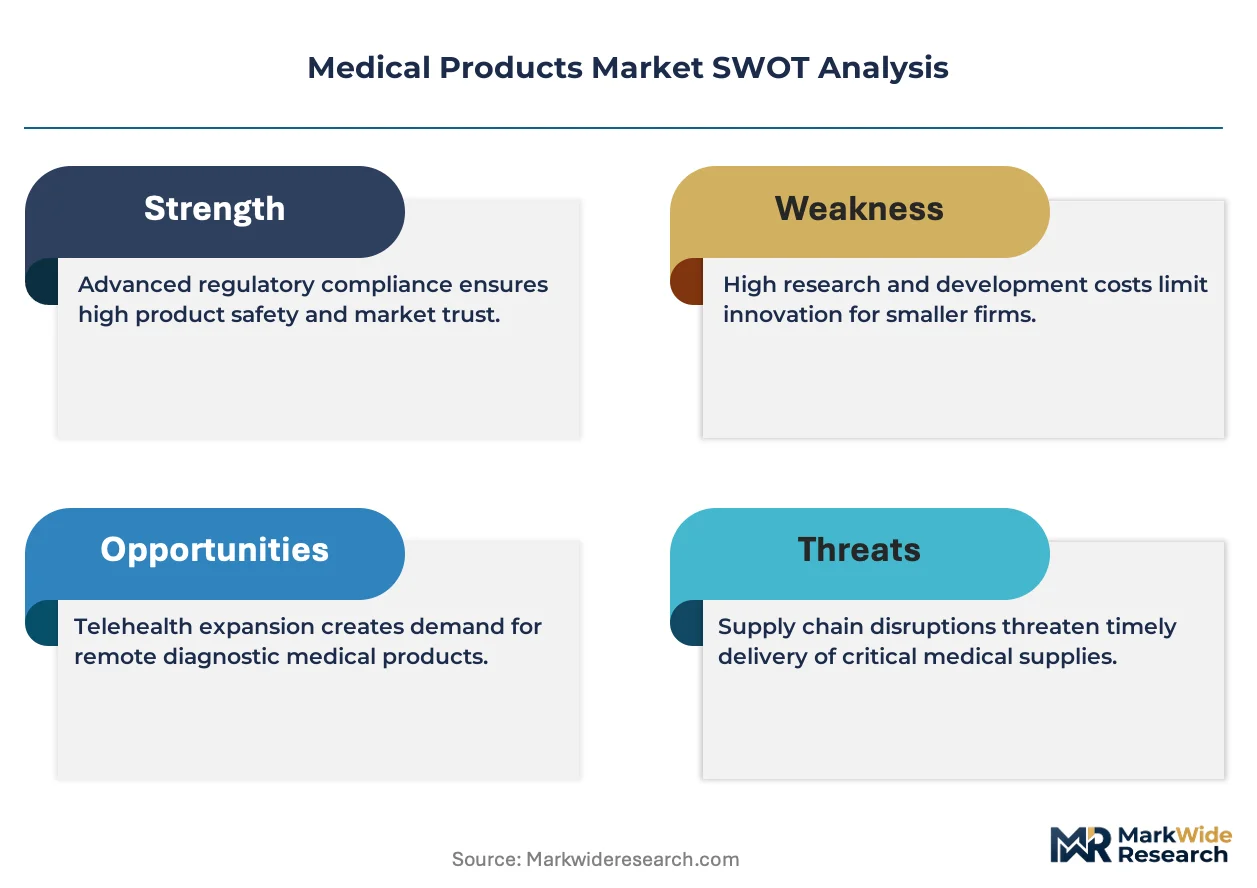
- FDA premarket notification pathways:Tightening quality benchmarks for device manufacturers elevate barriers that reward established quality systems and drive consolidation toward compliant producers.
- Japan's aging demographics:Sustained capital investment in diagnostic and surgical infrastructure supports demand concentration for advanced medical products.
- Robotics integration:Labor cost pressures and post-acute care decentralization accelerate adoption of automated surgical platforms across institutional settings.
Market Restraints
- EU MDR clinical evidence demands:Heightened conformity requirements extend product development timelines and inflate market access costs for manufacturers without established notified body relationships.
- Biomedical engineering talent rotation:Workforce migration toward robotics and digital health specializations constrains traditional device manufacturing pipelines.
- China NMPA localization mandates:Regional production footprint requirements fragment supply chain economics for multinational manufacturers.
Strategic Opportunities
- Telemedicine platform expansion:Post-acute care decentralization creates white space for remote monitoring and diagnostic delivery systems in ambulatory settings.
- AI-enhanced diagnostic modalities:Siemens Healthineers' imaging dominance demonstrates pathway for algorithm-integrated device categories to capture premium positioning.
- Germany's reimbursement stability:Predictable capital allocation frameworks support sustained investment in connected surgical infrastructure replacement cycles.
Industry Challenges
- ISO 13485 quality system maintenance:Talent scarcity in traditional manufacturing compliance functions strains audit readiness and certification continuity.
- Biocompatibility validation per ISO 10993:Extended testing protocols compress product launch windows and elevate pre-market capital intensity.
- Regulatory divergence monitoring:Stakeholders must track FDA quality management harmonization efforts against EU MDR clinical evidence demands when allocating R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Products Market |
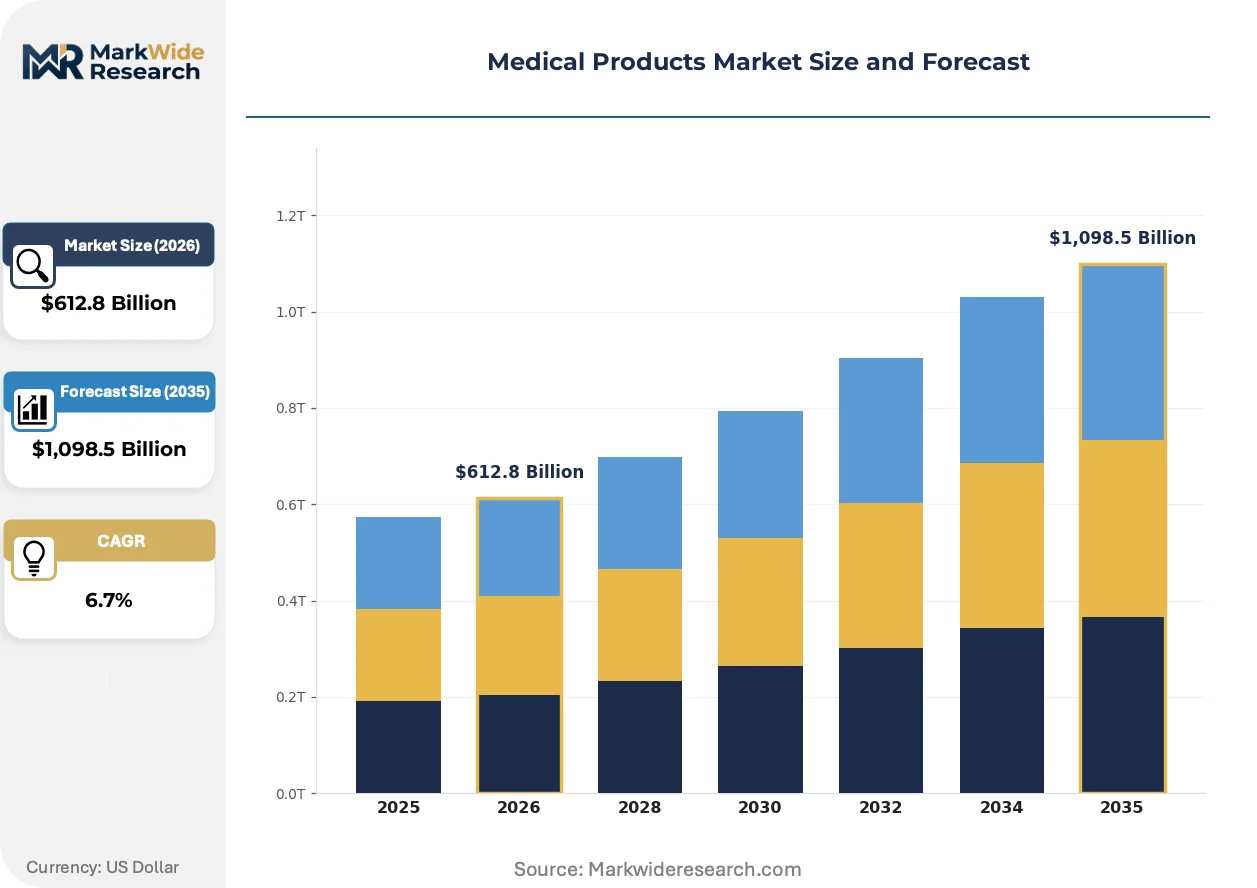
| Market Size in 2026 | $612.8 Billion |
| Market Size in 2035 | $1,098.5 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostics, Surgical Instruments, Infusion Pumps, Stents End User: Hospitals, Clinics, Outpatient Facilities, Home Care Application: Cardiology, Orthopedics, Neurology, Urology Technology: Biotechnology, Nanotechnology, Robotics, Telemedicine |
| Companies Covered | Medtronic, Johnson & Johnson, Abbott Laboratories, Stryker Corporation, Boston Scientific Corporation, Siemens Healthineers, Philips, GE Healthcare, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Products Market Emerging Trajectories
Digital health integration and regulatory harmonization pressures are actively restructuring how medical products are developed, validated, and commercialized across institutional and ambulatory channels.
Surgical robotics is bifurcating competitive positioning between integrated platform vendors and modular component suppliers. Health systems with capital replacement budgets favor turnkey robotic ecosystems that bundle instrumentation, software, and service contracts. This technology is bifurcating procurement patterns into premium integrated suites versus lower-tier conventional laparoscopic equipment.
EU MDR notified body conformity assessments are compressing product development timelines and elevating clinical evidence requirements for Class III devices. Manufacturers face extended review queues as notified body capacity constrains against submission volumes. High-risk implantable categories bear disproportionate compliance burden, driving portfolio rationalization toward lower-classification products.
Health system procurement committees are consolidating vendor relationships around outcome guarantees and total cost-of-ownership frameworks. Group purchasing organizations and integrated delivery networks disintermediate traditional distributor relationships. This concentration is most visible in United States health systems pursuing operating suite standardization across multi-hospital networks.
Medical Products Market Segmentation
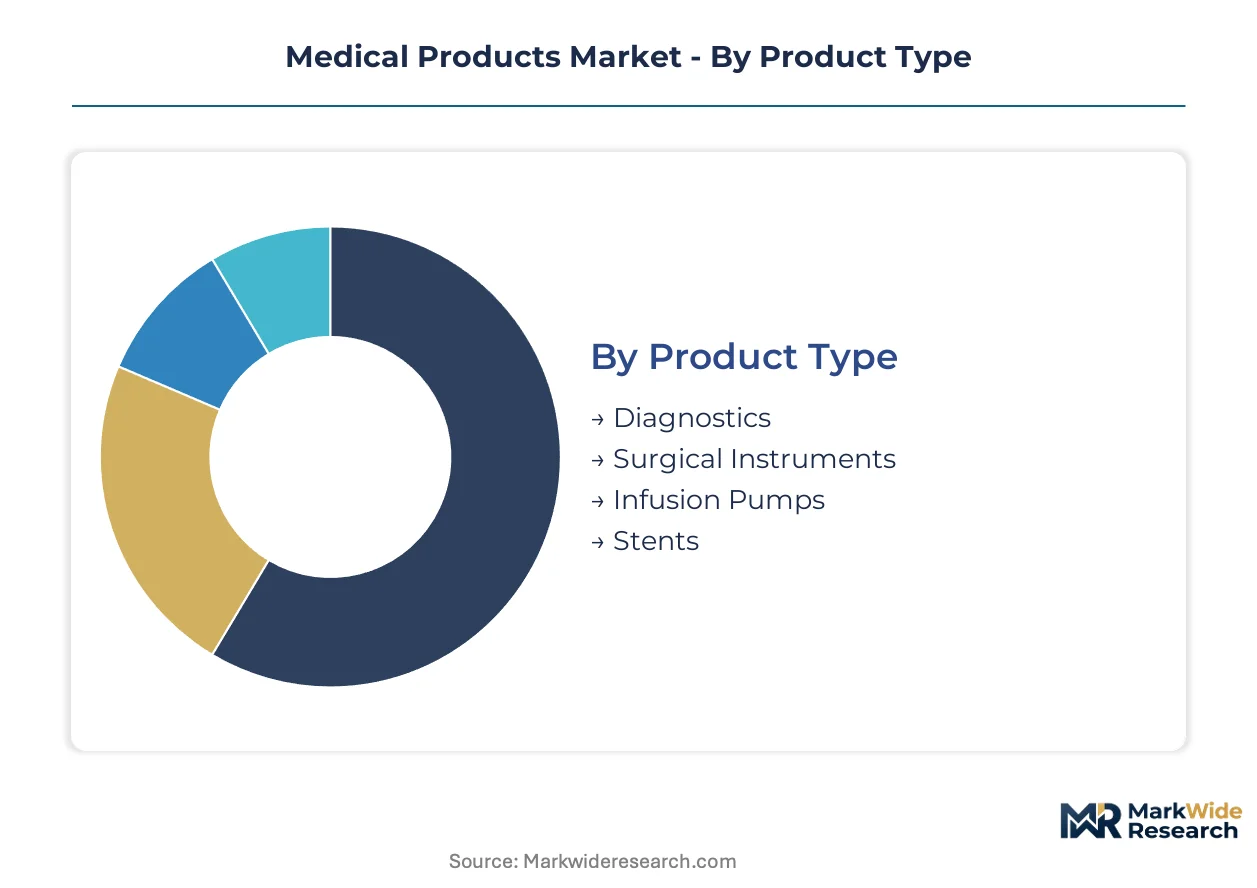
Medical products traverse highly differentiated channel pathways where capital equipment flows through institutional procurement committees while consumables route through distributor networks and direct contracts. Understanding these segment-channel alignments reveals where pricing power concentrates and where volume scale dominates revenue capture.
Product Type:
Channel economics vary sharply across product categories, with capital-intensive systems commanding multi-year service contracts while consumables generate recurring revenue through high-velocity reorder cycles.
- Diagnostics:Imaging modalities and in-vitro testing platforms integrate software analytics and consumable reagents. Demand clusters in United States health systems pursuing laboratory consolidation and Germany's statutory health insurance networks modernizing pathology infrastructure.
- Surgical Instruments:Electromechanical devices and precision cutting tools manufactured under ISO 13485 with biocompatibility validation per ISO 10993. Japan's PMDA regulatory framework shapes premium positioning for advanced laparoscopic and robotic-compatible instrumentation.
- Infusion Pumps:Programmable drug delivery systems with wireless connectivity features.
- Stents:Coronary and peripheral vascular implants subject to FDA premarket notification and EU MDR clinical evidence requirements.
Diagnostics dominates installed base. Surgical instruments is where expansion concentrates.
End User:
Procurement authority and reimbursement pathways diverge across care settings, with hospitals retaining capital budget control while home care channels expand through remote monitoring reimbursement codes.
- Hospitals:Integrated delivery networks and academic medical centers with centralized capital allocation committees. United States health systems concentrate demand for connected surgical suites under replacement cycles tied to Medicare reimbursement stability.
- Clinics:Physician-owned and hospital-affiliated ambulatory surgery centers with constrained equipment budgets favoring leased or refurbished systems.
- Outpatient Facilities:Specialized diagnostic and same-day surgical centers with high patient throughput requirements.
- Home Care:Post-acute monitoring and chronic disease management devices reimbursed through remote patient monitoring billing codes.
Hospitals anchor capital procurement volume. Home care is gaining share fastest.
Application:
Clinical specialization determines regulatory pathway intensity and outcome-based contracting feasibility, with cardiovascular and orthopedic categories leading value-based reimbursement pilots.
- Cardiology:Interventional devices and electrophysiology systems for arrhythmia management and structural heart repair. Germany's diagnosis-related group reimbursement supports sustained investment in catheterization laboratory infrastructure.
- Orthopedics:Joint replacement implants and arthroscopic instruments with long clinical follow-up requirements. Japan's aging demographics drive demand concentration for hip and knee arthroplasty systems.
- Neurology:Deep brain stimulation and cerebrospinal fluid management devices with specialized surgical training requirements.
- Urology:Endoscopic and lithotripsy systems for minimally invasive stone and prostate procedures.
Orthopedics holds the largest implantable device installed base. Cardiology is where technology substitution accelerates.
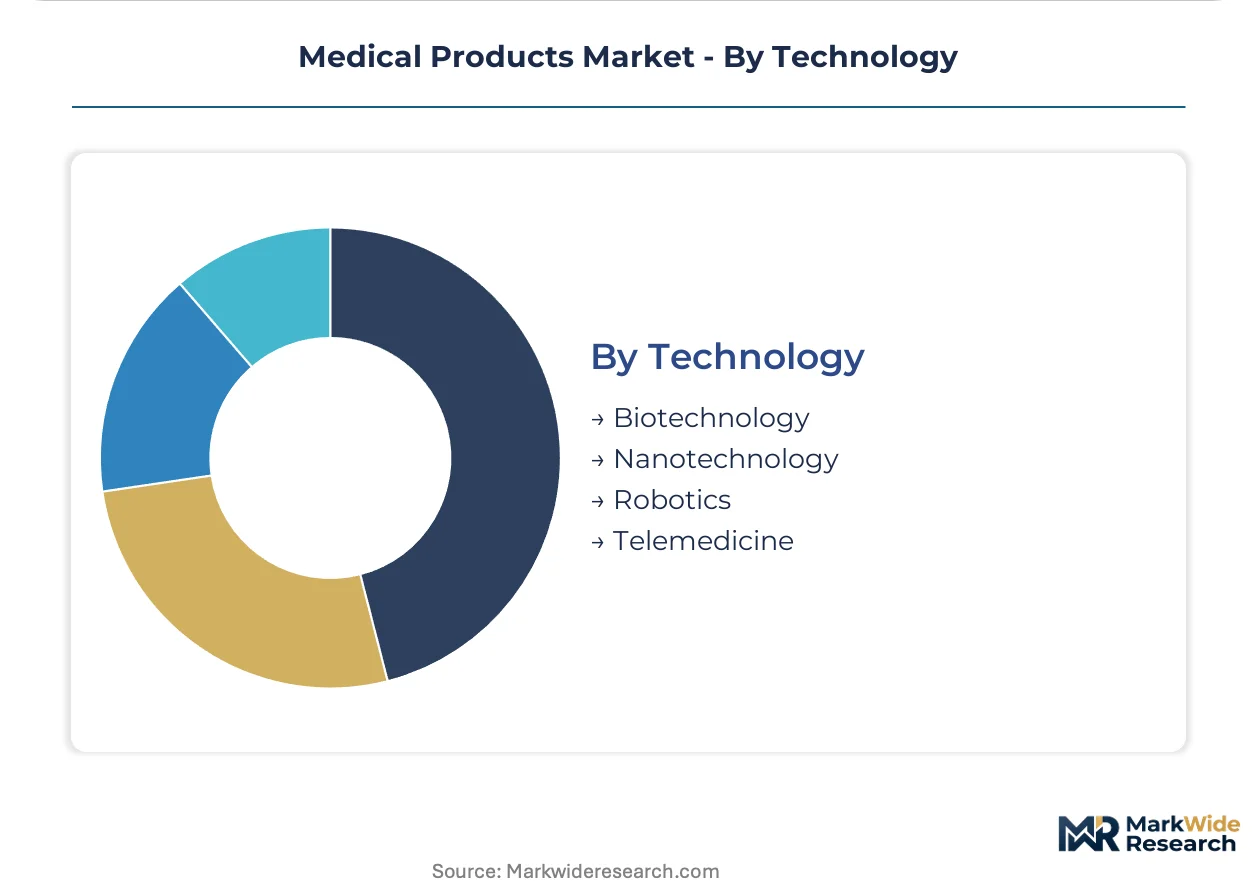
Technology:
R&D allocation and patent intensity separate mature manufacturing platforms from emerging modalities requiring novel regulatory frameworks and clinical evidence generation.
- Biotechnology:Tissue-engineered implants and bioresorbable materials with extended biocompatibility validation protocols. EU MDR notified body assessments impose disproportionate burden on novel biological device categories.
- Nanotechnology:Surface-modified implants and targeted drug delivery systems with emerging ISO standardization gaps.
- Robotics:Automated surgical platforms with integrated imaging and instrumentation undergoing rapid FDA 510(k) pathway evolution.
- Telemedicine:Remote diagnostic and monitoring systems with reimbursement codes expanding across United States Medicare and Japan's public health insurance.
Biotechnology anchors established therapeutic categories. Robotics is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical products consumption varies sharply across geographies. The United States prioritizes capital-intensive robotic surgical suites, while Germany emphasizes diagnostic imaging infrastructure and Japan concentrates implantable devices for aging populations.
United States
Medicare reimbursement stability and integrated delivery network consolidation drive hospital procurement of connected surgical systems. FDA premarket notification pathways tighten quality benchmarks, elevating compliance costs for market entrants. The Minneapolis medical device corridor anchors robotic platform development, with health systems in the Upper Midwest standardizing operating suite configurations.
Germany
Statutory health insurance networks modernize pathology infrastructure, sustaining diagnostic imaging demand. EU MDR notified body conformity assessments compress product development timelines for implantable manufacturers. The Baden-Württemberg industrial cluster concentrates precision surgical instrument production, with Stuttgart-area fabricators supplying European hospital networks.
Japan
Aging demographics concentrate demand for hip and knee arthroplasty systems and cardiac implantables. PMDA regulatory frameworks shape premium positioning requirements for advanced laparoscopic instrumentation. The Kansai region around Osaka hosts specialized manufacturers of biocompatible materials, serving domestic and Asia-Pacific distribution channels.
China
Hospital tier-grading systems accelerate procurement of domestic-brand diagnostic equipment in secondary and tertiary facilities. NMPA localization mandates require regional production footprints for multinational market access. The Yangtze River Delta medical device manufacturing belt expands capacity for consumable production, with Shanghai-based distributors penetrating provincial procurement networks.
Switzerland
Private hospital networks and cantonal health systems sustain premium-priced orthopedic and cardiovascular implant demand. Swissmedic regulatory frameworks align with EU MDR standards while maintaining distinct quality system requirements. The Lake Geneva biotech corridor concentrates high-value implantable device R&D, with Basel-area firms leveraging proximity to pharmaceutical precision manufacturing ecosystems.
Medical Products Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a bifurcated competitive structure. Tier-one participants bundle capital equipment with long-term service contracts and consumable supply agreements, while mid-scale specialists compete on segment-specific clinical outcomes. Three archetypes dominate: integrated surgical platform vendors, diagnostic imaging modality developers, and diversified implantable device manufacturers. Competitive moves concentrate on portfolio rationalization toward higher-margin categories and backward integration into critical component supply.
Among diversified implantable device manufacturers, Medtronic and Boston Scientific occupy positions exemplifying the integrated platform approach, while Siemens Healthineers anchors the diagnostic imaging modality tier. These entities represent contrasting strategic postures: device-centric vertical integration versus software-enhanced hardware ecosystems. Specialists in electrophysiology and structural heart repair sit within narrower competitive bandwidths, competing on clinical evidence depth rather than portfolio breadth. The competitive terrain rewards established quality management systems and notified body relationships over pure scale metrics.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Abbott Laboratories |
| Stryker Corporation |
| Boston Scientific Corporation |
| Siemens Healthineers |
| Philips |
| GE Healthcare |
| Danaher Corporation |
| Others |
Supply Flow & Price Mechanics
Polymer substitution for metal in biocompatible implant housings simultaneously shifts procurement geography toward Germany's polymer compounding clusters and compresses per-unit material costs for mid-tier manufacturers.
Pricing Analysis
Long-term service contracts with bundled consumable supply dominate capital equipment transactions, while spot purchasing governs high-velocity disposables. Three-tier pricing structure across premium, standard, and economy levels separates integrated robotic platforms from conventional laparoscopic sets and generic reprocessed instruments. Cost compression in economy tiers intensifies because Group Purchasing Organizations consolidate vendor panels around total cost-of-ownership metrics. Ambulatory surgery centers exhibit highest price sensitivity; academic medical centers prioritize outcome guarantees over per-unit cost.
Supply Chain Analysis
Germany, Switzerland, and the United States anchor precision component fabrication for surgical instruments and implantable devices. Supply chains draw from titanium alloy feedstock, medical-grade polymers, and biocompatible coatings. Single-source vulnerability concentrates in EU MDR-notified body capacity for sterilization validation. Distribution runs through integrated delivery network central warehouses and specialized medical device distributors with cold-chain capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement of connected surgical systems sits in early-cycle expansion, with Medicare reimbursement stability for remote patient monitoring codes accelerating post-acute care decentralization.
For Market Incumbents: Compound platform ecosystem advantages by anchoring hospital system partnerships around multi-year service contracts with guaranteed uptime clauses. Deepen backward integration into biocompatible polymer compounding to offset raw material cost volatility. Prioritize notified body relationship expansion to compress EU MDR conformity assessment timelines against submission backlogs. For New Entrants and Emerging Players: Differentiate on modular robotic instrumentation compatible with incumbent platforms rather than competing for turnkey system procurement. Target ambulatory surgery centers in United States metropolitan corridors with leased equipment models and per-procedure consumable pricing. Pursue FDA 510(k) clearance for single-specialty applications with abbreviated clinical evidence requirements. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors diversified implantable device manufacturers with established quality management systems. Five-to-ten year viability hinges on regulatory pathway execution speed and hospital system contract renewal rates. Monitor notified body capacity expansion announcements as inflection indicator for Class III device launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market access for moderate-risk devices against PMA pathway timelines. |
| CE Marking Pathway | Unlocks EU MDR conformity for implantable categories under notified body review. |
| Hospital System Partnership | Secures multi-year procurement commitments from integrated delivery networks. |
| Software Companion Development | Enables AI-enhanced diagnostic claims for imaging modality premium positioning. |
| Reimbursement Strategy | Aligns product coding with Medicare remote patient monitoring billing expansion. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and regulatory affairs leads; and secondary validation against FDA 510(k) and PMA filing databases, EU MDR notified body submission records, CMS Medicare reimbursement code updates, and hospital procurement system contract disclosures. Bottom-up demand modeling triangulated against top-down market sizing across product type, end user, application, and technology dimensions.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmented demand aggregation and replacement cycle timing. Segmentation dimensions included capital equipment versus consumable product economics, institutional versus ambulatory channel pathways, and regulatory classification intensity. CAGRs derived from historical capital expenditure patterns and reimbursement code expansion trajectories, with robotics adoption curves and telemedicine reimbursement eligibility as specific forecast inputs.
Material uncertainties — regulatory pathway delays, notified body capacity constraints, and reimbursement code revision timing — sit outside the modeled envelope. Forecasts reflect documented assumptions about capital replacement cycle continuity and demographic demand concentration. Recalibration cycles align with material shifts in FDA quality management harmonization efforts and EU MDR clinical evidence requirement evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Global Life Science Products Market
Healthcare Products
Smoking Cessation Aids Market
Healthcare Products
Italy Hand Sanitizer Market
Healthcare Products
Global Clinical Trial Consumables Market
Healthcare Products
Antimicrobial Furniture Market
Healthcare Products
Medical Scrubs Market
Healthcare Products
Automatic Hand Sanitizer Dispenser Market
Healthcare Products
Australia Hair Transplant Market
Healthcare Products
United States Infrared Sauna Market
Healthcare Products
Europe Hand Sanitizer Market
Healthcare Products
Hand Sanitizer Market
Healthcare Products
Dementia Care Products Market
Healthcare Products
North America Adult Incontinence Products Market
Healthcare Products
Blood and Organ Bank Market
Healthcare Products
Patient Cleansing Products Market
Healthcare Products
Incontinence Products Market