
 Menopause Supplement Market | 2026-2036
Menopause Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Menopause Supplement Market Insights
Plant-derived compounds are broadening the raw-material base for menopause supplements as manufacturers reduce reliance on synthetic hormone analogs. Bayer AG leverages its pharmaceutical heritage to sustain clinical credibility in phytoestrogen formulations. Pharmavite anchors its position through mass-market channel control and third-party certification programs.
Menopause supplements comprise botanical extracts, minerals, and vitamins formulated to modulate thermoregulatory, skeletal, and neurocognitive functions during ovarian hormone decline; standard products typically standardize active marker compounds such as triterpene glycosides in black cohosh to defined percentages. The phytoestrogen category leads volume due to established consumer familiarity with soy isoflavones and red clover extracts, while gummy formats capture the fastest expansion as palatability drives compliance among perimenopausal cohorts. Bone health applications command premium positioning given the chronicity of osteoporosis risk and physician endorsement patterns.
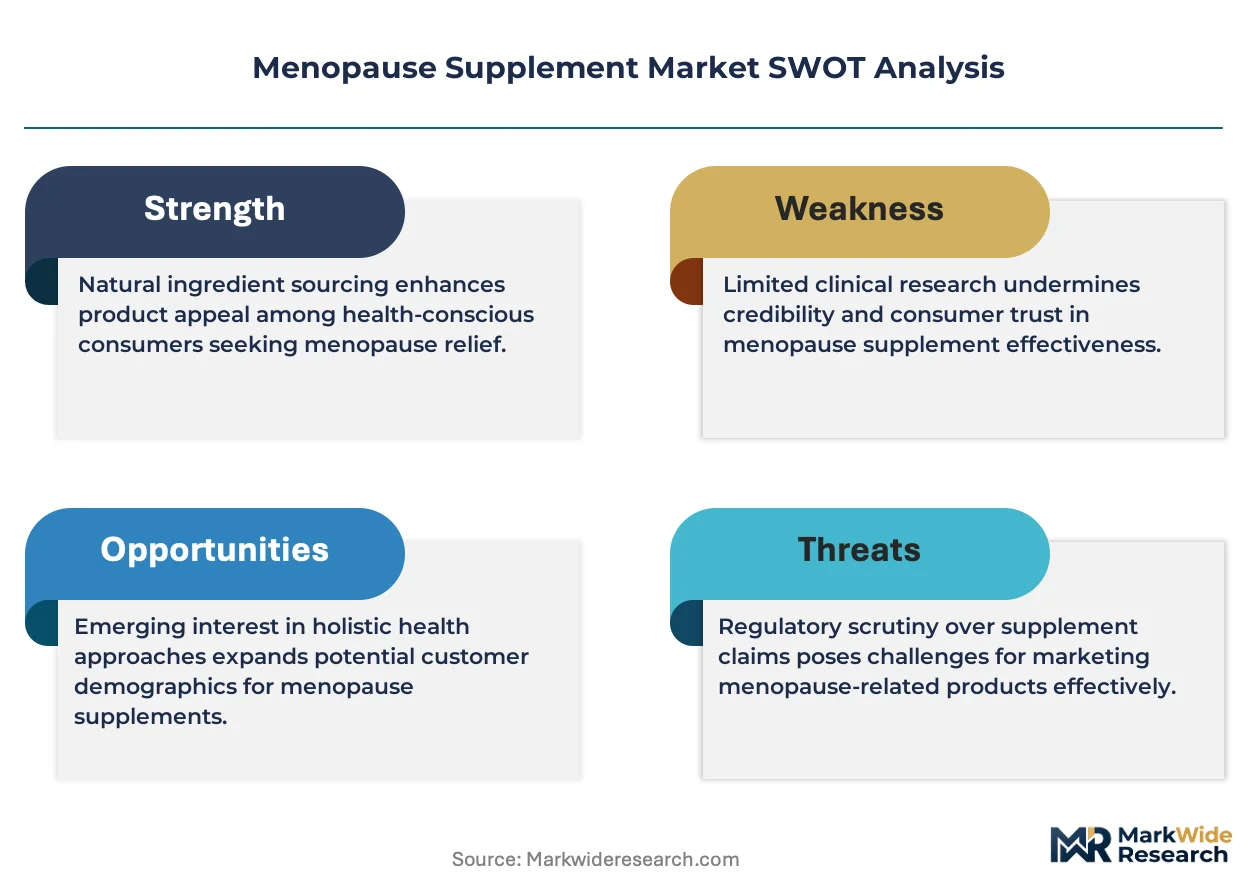
FDA Current Good Manufacturing Practices and EFSA health claim authorization processes determine which efficacy statements survive on product labels, directly filtering market access for new entrants. Japan's Ministry of Health, Labour and Welfare Foods with Function Claims system offers a parallel regulatory pathway that rewards clinical substantiation with differentiated positioning. Stakeholders must monitor evolving substantiation requirements across jurisdictions to allocate R&D investment toward claim categories with the highest probability of regulatory clearance.
Market Dynamics
The menopause supplement sector faces intensifying pressure from regulatory substantiation requirements, as FDA and EFSA tighten evidentiary standards for botanical health claims and force reformulation of legacy products lacking clinical trial backing.
Growth Catalysts
- EFSA Article 13.1 health claim pathways:Manufacturers investing in randomized controlled trials secure differentiated positioning on European shelves, creating competitive moats against commodity botanical suppliers.
- Japan's Foods with Function Claims system:This parallel regulatory framework rewards clinical substantiation with premium pricing authority, attracting R&D investment from multinational supplement houses.
- Perimenopausal cohort expansion:Women aged 45-55 in developed health systems now initiate supplementation earlier, extending consumption duration and lifetime value per user.
Market Restraints
- Black cohosh supply concentration:Wild-harvested North American rootstock faces sustainability constraints and price volatility, forcing dependence on cultivated alternatives with variable marker compound profiles.
- FDA 21 CFR Part 111 compliance costs:Current Good Manufacturing Practices mandates impose capital-intensive testing protocols that disproportionately burden mid-tier contract manufacturers.
- Synthetic hormone substitution threat:Prescription menopausal hormone therapy retains physician endorsement for severe vasomotor symptoms, limiting supplement penetration in high-acuity patient segments.
Strategic Opportunities
- Gummy format white space:Palatability-driven compliance gains in perimenopausal demographics remain underexploited outside North American mass-market channels.
- Personalized nutrition convergence:Integration of microbiome profiling with phytoestrogen metabolism genetics enables bespoke formulation services with recurring revenue models.
- German pharmacy channel rehabilitation:Professional endorsement through Apotheken counters restores clinical credibility eroded by e-commerce commoditization.
Industry Challenges
- Phytochemistry standardization expertise gap:Analytical chemists capable of validating triterpene glycoside content across heterogeneous botanical lots command premium compensation and scarce availability.
- Legacy ERP integration friction:Supplement manufacturers modernizing quality management systems face data migration complexity with existing batch record infrastructure.
- Cross-jurisdiction claim harmonization:Divergent permissible language between FDA structure-function rules and EFSA authorized health claims forces territory-specific labeling runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Menopause Supplement Market |
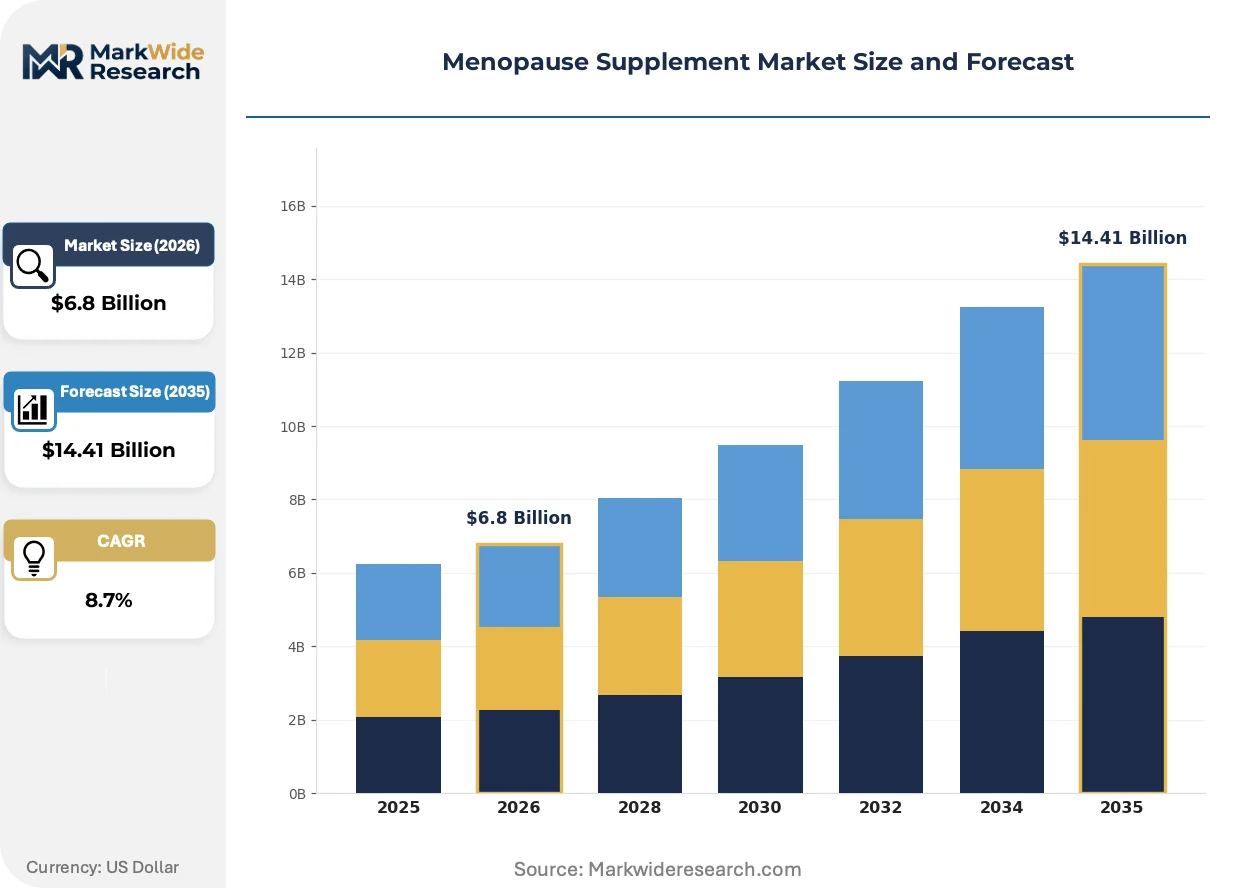
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phytoestrogens, Black Cohosh, Dong Quai, Evening Primrose Oil, Calcium, Magnesium Form: Capsules, Tablets, Powders, Liquids, Gummies Application: Hot Flashes Relief, Bone Health, Mood Stabilization, Sleep Improvement, Cardiovascular Support End User: Pharmacies, Wellness Clinics, Nutritional Centers, Online Retailers |
| Companies Covered | Amway, Bayer AG, Blackmores, Herbalife Nutrition, Nature’s Way Products, Pharmavite, Pfizer, Pure Encapsulations, Theramex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Menopause Supplement Market Trends and Innovations
Direct-to-consumer diagnostic platforms are collapsing the information asymmetry between supplement marketers and menopausal women, enabling evidence-based self-selection that rewards clinically substantiated formulations over marketing-heavy alternatives.
Microencapsulation technology is decentralizing bioactive delivery by protecting heat-sensitive isoflavones through gastric transit, enabling novel food-matrix applications beyond traditional capsules. Functional beverage manufacturers in Japan and the United States adopt these encapsulated extracts for ready-to-drink menopause-positioned products. This decentralization compresses the dominance of pill-centric supplement incumbents and opens shelf-space competition from adjacent nutrition categories.
EFSA's 2024 tightened botanical claim evaluation criteria are forcing European manufacturers to retire legacy "traditional use" arguments and commission new human intervention studies. The industrial consequence is a bifurcation between substantiated premium lines and delisted commodity products. Bone health applications face the steepest evidentiary climb, as osteoporosis risk reduction claims now require fracture endpoint data rather than bone mineral density proxies.
Subscription-based replenishment models are displacing retail replenishment cycles among digitally native perimenopausal consumers, locking in twelve-month commitments through personalized protocol adjustments. Telehealth platforms integrating symptom tracking with automated supplement dosing recommendations capture this behavioral shift most visibly in United States metropolitan markets, where employer wellness benefits subsidize program enrollment.
Menopause Supplement Market Segmentation
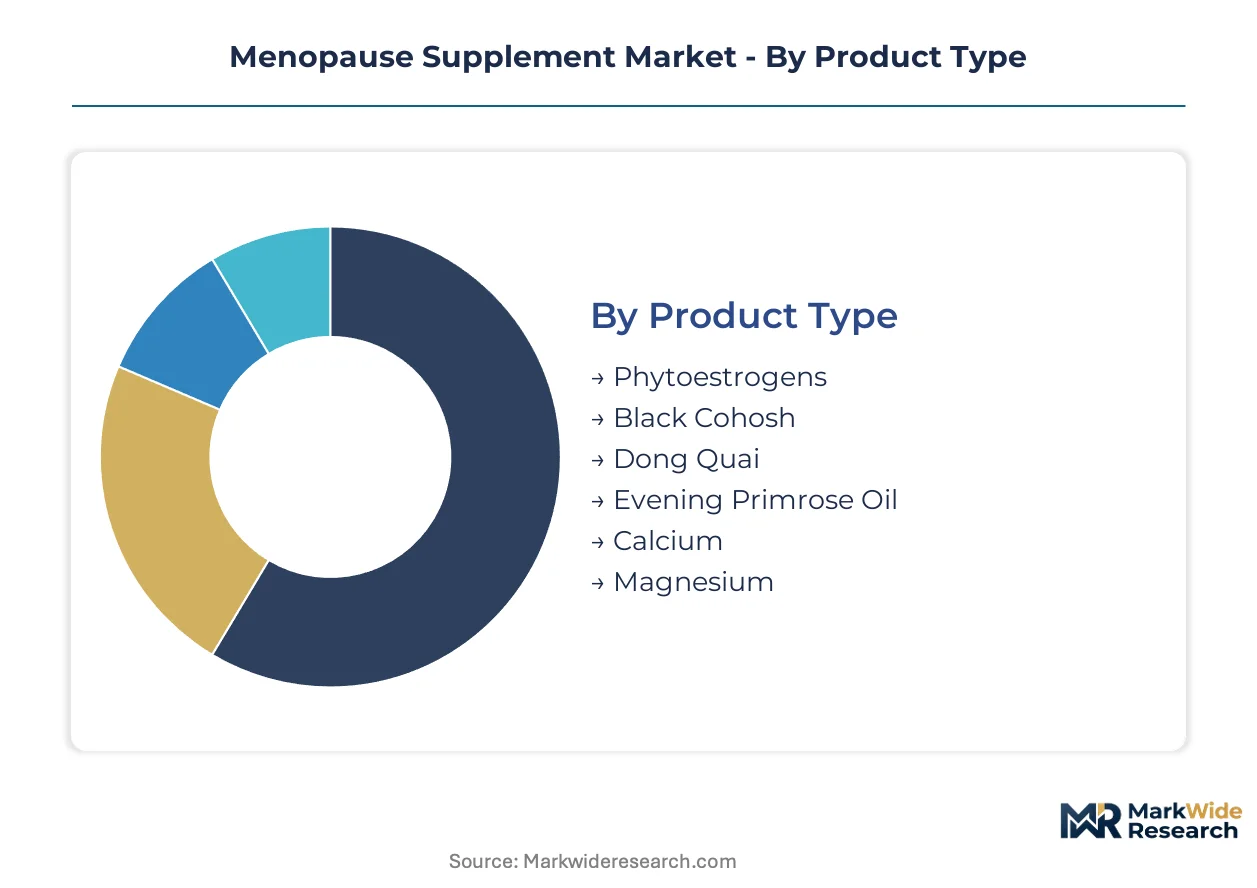
Segmentation in the menopause supplement market reveals how formulation science, delivery mechanisms, and distribution channels intersect to serve distinct consumer needs. Understanding these divisions exposes where R&D investment concentrates and which product architectures command pricing power.
Product Type:
Standalone botanical extracts dominate prescription-adjacent positioning, while mineral complexes embed into broader women's health protocols.
- Phytoestrogens:Soy isoflavones and red clover extracts deliver standardized genistein and daidzein content for estrogen receptor modulation. Demand clusters in Germany and Japan where EFSA and MHLW substantiation pathways reward clinical dossiers. Japanese functional food manufacturers embed these into fermented soy matrices for daily consumption.
- Black Cohosh:Triterpene glycoside standardization defines pharmaceutical-grade extracts for vasomotor symptom management. North American wild-harvesting constraints push formulation houses toward cultivated Actaea racemosa with verified marker profiles. Supply volatility limits expansion into price-sensitive Asian markets.
- Dong Quai:Angelica sinensis polysaccharide extracts serve traditional Chinese medicine practitioners in Pacific Rim diaspora communities.
- Evening Primrose Oil:Gamma-linolenic acid content targets atopic dermatitis co-occurring with hormonal transition.
- Calcium:Carbonate and citrate salts anchor osteoporosis prevention protocols with physician endorsement.
- Magnesium:Bisglycinate and oxide forms address sleep architecture disruption and muscle cramping.
Phytoestrogens lead volumes today; gummy-format mineral complexes are gaining share fastest.
Form:
Cost tier stratification separates premium bioavailability-enhanced delivery from commodity bulk powders.
- Capsules:Hard-shell gelatin and HPMC vehicles protect acid-sensitive actives through gastric transit. German Apotheken channels favor enteric-coated variants for professional dispensing credibility.
- Tablets:Direct compression and wet granulation methods enable high-volume production economics for mass-market SKUs. US drugstore chains drive tablet format dominance through shelf-stable inventory efficiency.
- Powders:Bulk isoflavone concentrates serve compounding pharmacies and functional beverage manufacturers.
- Liquids:Liposomal emulsions target consumers with dysphagia or pediatric dosing requirements.
- Gummies:Pectin-based matrices with masked bitterness technology capture perimenopausal compliance advantages in direct-to-consumer channels.
Tablets dominate current volume; gummies exhibit the steepest expansion trajectory.
Application:
Application segmentation tracks symptom severity gradients from lifestyle discomfort to chronic disease risk.
- Hot Flashes Relief:Thermoregulatory modulation formulations combine black cohosh with sage extract for immediate symptom interruption. US telehealth platforms bundle these with wearable temperature monitoring for protocol optimization.
- Bone Health:Calcium-vitamin D-K2 matrices target trabecular bone preservation with fracture endpoint claims requiring regulatory investment. EFSA's tightened substantiation standards force European manufacturers toward pharmaceutical-grade clinical trials.
- Mood Stabilization:Saffron and rhodiola adjuncts address anxiety-depression symptom clusters.
- Sleep Improvement:Magnesium-threonate and L-theanine combinations target sleep onset latency reduction.
- Cardiovascular Support:Red yeast rice and omega-3 adjuncts address lipid profile shifts post-menopause.
Bone health commands premium positioning; mood stabilization applications expand most quickly through mental health platform integration.
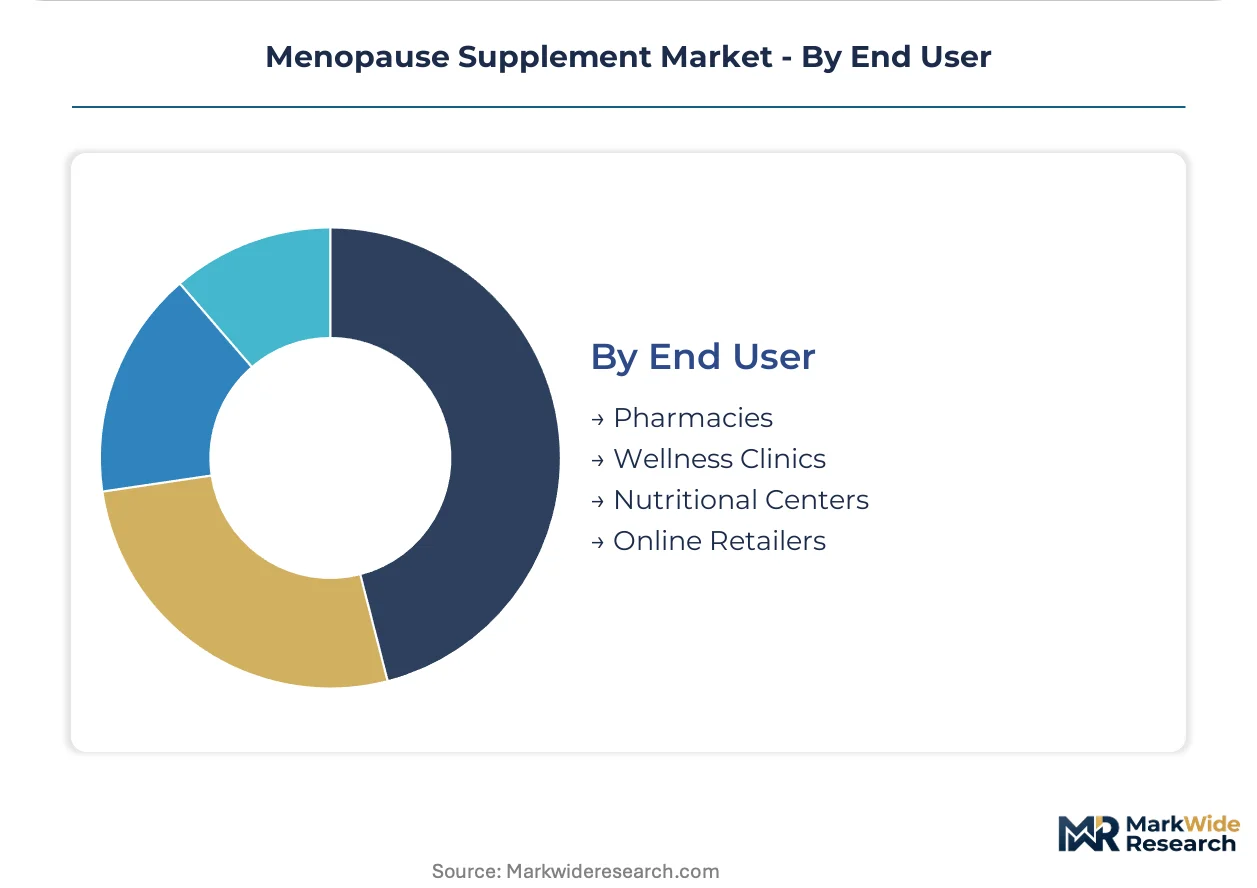
End User:
Channel type determines clinical credibility requirements versus convenience prioritization.
- Pharmacies:Brick-and-mortar dispensaries in Germany and Japan enforce pharmacist consultation protocols that validate premium pricing. German Apotheken rehabilitation efforts restore trust eroded by e-commerce commoditization.
- Wellness Clinics:Integrative medicine practices bundle supplements with bioidentical hormone protocols for comprehensive menopause management. US functional medicine networks drive protocol-based subscription models.
- Nutritional Centers:Independent health food retailers serve educated early adopters seeking non-GMO and organic certifications.
- Online Retailers:Amazon and specialized DTC platforms capture price-sensitive replenishment through subscription mechanics.
Pharmacies retain volume leadership; online retailers are climbing the fastest through algorithmic personalization engines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmacy networks anchor European menopause supplement distribution through Apotheken channels that enforce pharmacist consultation protocols. Japanese functional food manufacturers embed phytoestrogens into fermented soy matrices for daily consumption. United States direct-to-consumer platforms capture algorithmic personalization advantages through subscription mechanics.
United States
Perimenopausal women aged 45-55 initiate supplementation earlier than prior cohorts, extending consumption duration. FDA 21 CFR Part 111 Current Good Manufacturing Practices mandates impose capital-intensive testing protocols. Telehealth platforms in metropolitan markets bundle symptom tracking with automated dosing recommendations.
Germany
EFSA Article 13.1 health claim pathways reward randomized controlled trial investment with differentiated shelf positioning. German Apotheken rehabilitation efforts restore clinical credibility eroded by e-commerce commoditization. Bavaria-based formulation houses specialize in enteric-coated capsule variants for professional dispensing.
Japan
Ministry of Health, Labour and Welfare Foods with Function Claims system rewards clinical substantiation with premium pricing authority. Aging demographics intersect with proactive wellness cultures in Kanto region consumption clusters. Tokyo functional beverage manufacturers adopt microencapsulated isoflavones for ready-to-drink applications.
United Kingdom
Boots and Holland & Barrett high-street networks serve educated early adopters seeking non-GMO certifications. MHRA borderline regulations determine whether products classify as medicines or food supplements. London-based wellness clinics bundle botanical formulations with bioidentical hormone protocols.
Menopause Supplement Market Competitive Landscape
Global majors compete with regional champions across regulatory substantiation capabilities and channel control. The vendor base stratifies into three tiers: pharmaceutical heritage companies with clinical trial infrastructure, mass-market houses with retail scale, and specialized botanical extractors with cultivation relationships. Strategic moves concentrate on EFSA dossier preparation for European premium positioning and gummy format capacity expansion for perimenopausal compliance gains.
Within the pharmaceutical heritage tier, Bayer AG leverages its clinical credibility infrastructure to sustain phytoestrogen formulation authority. Pharmavite anchors mass-market positioning through third-party certification programs and channel control. Among Asia-Pacific specialists, Blackmores occupies a position exemplifying pharmacy-endorsed premium botanical positioning.
| Leading Market Players |
|---|
| Amway |
| Bayer AG |
| Blackmores |
| Herbalife Nutrition |
| Nature's Way Products |
| Pharmavite |
| Pfizer |
| Pure Encapsulations |
| Theramex |
| Others |
Pricing and Supply Chain Analysis
EFSA's 2024 tightened botanical claim substantiation mandates are forcing European manufacturers toward pharmaceutical-grade clinical trials, compressing margins on legacy formulations and redirecting procurement toward verified-cultivar suppliers with documented marker compound profiles.
Pricing Analysis
Input-cost pass-through from wild-harvested black cohosh supply constraints is intensifying price volatility across North American-sourced formulations. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-substantiated extracts from traditional-use botanicals and commodity-grade mineral complexes. Pricing pressure stems from FDA 21 CFR Part 111 compliance cost absorption among mid-tier contract manufacturers. Mass-market drugstore chains exhibit highest price sensitivity; German Apotheken channels tolerate premium positioning through pharmacist consultation value-add.
Supply Chain Analysis
Japan's Foods with Function Claims domestic-content preferences are reshaping sourcing toward Kanto-region cultivation partnerships for soy isoflavone matrices. Supply concentrates in the United States for black cohosh extraction, Germany for enteric-coated formulation finishing, and Japan for functional beverage integration. Raw material dependencies encompass North American Actaea racemosa rootstock, Brazilian soy concentrate, and Chinese Angelica sinensis polysaccharides. Single-source vulnerability runs through wild-harvested cohosh populations facing sustainability constraints. Distribution runs through pharmacy networks in Germany and Japan, direct-to-consumer platforms in the United States, and wellness clinic protocols in metropolitan UK markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Perimenopausal cohorts aged 45-55 in developed health systems are shifting procurement toward clinically substantiated, third-party-certified formulations over commodity botanical alternatives.
For Market Incumbents: Hedge against synthetic hormone therapy recapture in severe vasomotor segments by deepening EFSA dossier investment for bone health fracture-endpoint claims. Secure cultivated black cohosh supply contracts with verified triterpene glycoside profiles to insulate against wild-harvest price spikes. Prioritize gummy format capacity expansion for perimenopausal compliance retention. For New Entrants and Emerging Players: Telehealth platforms integrating symptom tracking with automated dosing recommendations represent the most penetrable white space for algorithmic personalization plays. Target subscription-based replenishment mechanics in United States metropolitan markets where employer wellness benefits subsidize enrollment. Pursue white-label partnerships with Japanese functional beverage manufacturers for microencapsulated isoflavone supply. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized botanical extractors possessing validated cultivation relationships and analytical chemistry capabilities for phytochemistry standardization. Five-to-ten year viability hinges on regulatory substantiation moats rather than marketing scale. Watch for EFSA Article 13.1 authorization announcements as inflection indicators for premium pricing authority validation.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Health Claim Dossier Investment | Randomized controlled trial expenditure secures differentiated European shelf positioning against commodity suppliers. |
| Gummy Format Manufacturing Scale-Up | Pectin-based palatability technology captures perimenopausal compliance advantages in direct-to-consumer channels. |
| Cultivated Black Cohosh Supply Agreements | Verified Actaea racemosa cultivation insulates formulation houses from wild-harvest sustainability constraints. |
| Telehealth Platform Integration | Symptom-tracking algorithm bundling locks in twelve-month subscription commitments through protocol personalization. |
| Japanese FFC System Registration | Ministry of Health, Labour and Welfare substantiation rewards clinical investment with premium pricing authority. |
Research Methodology
Multiple input streams — regulatory filing analysis, supply chain participant interviews, and retail audit reconciliation — were synthesized to construct market estimates. Primary discussions with formulation scientists, pharmacy procurement managers, contract manufacturing executives, and regulatory affairs specialists were cross-validated against FDA 21 CFR Part 111 inspection records, EFSA health claim authorization databases, and Japanese MHLW Foods with Function Claims registrations. Bottom-up SKU-level demand modeling and top-down demographic penetration analysis were reconciled to establish volume baselines.
Data-stream reconciliation across product type, form, application, and distribution channel dimensions enabled segmentation-level growth trajectory projection. CAGRs were derived from cohort consumption duration extension patterns and format substitution elasticity modeling. Forecast inputs incorporated perimenopausal population demographics, EFSA substantiation timeline assumptions, and pharmacy channel rehabilitation velocity indicators throughout the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory claim authorization delays, wild-harvest supply disruptions, and synthetic hormone therapy prescribing pattern shifts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Global Vitamin D Therapy Market
Dietary Supplements
Mens Health Supplements Market
Dietary Supplements
Veterinary Dietary Supplements Market
Dietary Supplements
Global Melatonin Market
Dietary Supplements
Cold Remedies Market
Dietary Supplements
Soft Gel Capsule Market
Dietary Supplements
Vitamin D Deficiency Treatment Market
Dietary Supplements
Glucosamine Salt Market
Dietary Supplements
Hair Loss Supplement Market
Dietary Supplements
Bone and Teeth Supplements Market
Dietary Supplements
Pet Skin and Coat Health Supplement Market
Dietary Supplements
Herbal Medicinal Products Market
Dietary Supplements
Concentrated Angelica Pills Market
Dietary Supplements
Pet Allergy Immune Supplements Market
Dietary Supplements
Womens Health and Beauty Supplements Market
Dietary Supplements
Postpartum Health Supplements Market