
 Cold Remedies Market | 2026-2036
Cold Remedies Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Remedies Market Analysis
Self-directed healthcare purchasing is shifting how consumers select cold remedies, with pharmacy chains and online platforms capturing larger transaction volumes. Reckitt Benckiser Group plc dominates the decongestant segment through sustained brand equity and shelf-space control. Johnson & Johnson Services, Inc. anchors its position via extensive pediatric formulations and retail pharmacy partnerships. GlaxoSmithKline plc differentiates through science-backed positioning and healthcare professional recommendations.
Cold remedies comprise pharmacological preparations formulated with active ingredients such as pseudoephedrine, dextromethorphan, guaifenesin, and chlorpheniramine, manufactured through tablet compression, liquid suspension, and metered-dose spray processes to alleviate rhinorrhea, nasal congestion, cough, and associated upper respiratory symptoms. Decongestants and cough suppressants command the largest revenue pools due to immediate symptom relief and repeat purchase frequency, while nasal sprays represent the fastest-growing delivery mode as consumers prioritize rapid onset and portable administration. Tablets retain maturity in developed markets where convenience and dosing precision matter, though syrups maintain strength in pediatric and senior segments where swallowing difficulties persist.
The FDA's OTC monograph reform program governs active ingredient safety and efficacy determinations, while the EPA regulates volatile organic compounds in certain propellant-based nasal spray formulations. The FTC monitors advertising claims for homeopathic and natural-positioned products, constraining unsubstantiated efficacy messaging. Stakeholders must monitor evolving monograph finalization timelines and ingredient reclassification risks that could force portfolio reformulation or channel restrictions.
Market Dynamics
The FDA's OTC monograph reform is compressing formulation timelines and forcing manufacturers to revalidate active ingredient dossiers ahead of final determinations on pseudoephedrine and dextromethorphan safety profiles.
Growth Catalysts
- Self-Medication Surge:Pharmacy retail chains in the United States are expanding private-label portfolios as consumers bypass physician consultations for routine upper respiratory symptoms.
- REACH Compliance Alignment:European manufacturers accelerating propellant reformulation to meet volatile organic compound restrictions are capturing shelf space from non-compliant imports.
- Nasal Spray Technology:Metered-dose spray processes enabling rapid onset delivery are driving repeat purchase frequency among working-age demographics seeking workplace-compatible administration.
Market Restraints
- API Supply Concentration:Pseudoephedrine precursor sourcing depends on concentrated chemical manufacturing clusters in China, exposing formulators to export license volatility.
- Monograph Uncertainty:The FDA's unresolved final determinations on cough suppressant efficacy are freezing R&D allocation decisions across tablet and liquid suspension portfolios.
- Natural Substitute Threat:Homeopathic and botanical-positioned remedies are capturing preference share among parents seeking pediatric alternatives to synthetic actives.
Strategic Opportunities
- Senior Formulation Gap:Dysphagia-friendly delivery formats remain underdeveloped for aging populations in Japan, where METI guidelines favor geriatric-accessible packaging innovations.
- Digital Pharmacy Integration:Telehealth platforms in the United States are creating direct-to-patient subscription channels for seasonal cold remedy pre-positioning.
- Propellant Innovation:Hydrofluoroalkane transitions compliant with EPA regulations are opening technical differentiation paths for domestic nasal spray manufacturers.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Shortages of specialists versed in both OTC stability testing and rapid dissolution engineering are extending product development cycles.
- Legacy System Integration:Batch record digitization required for FDA electronic submission mandates is forcing mid-tier manufacturers into costly MES platform overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Remedies Market |
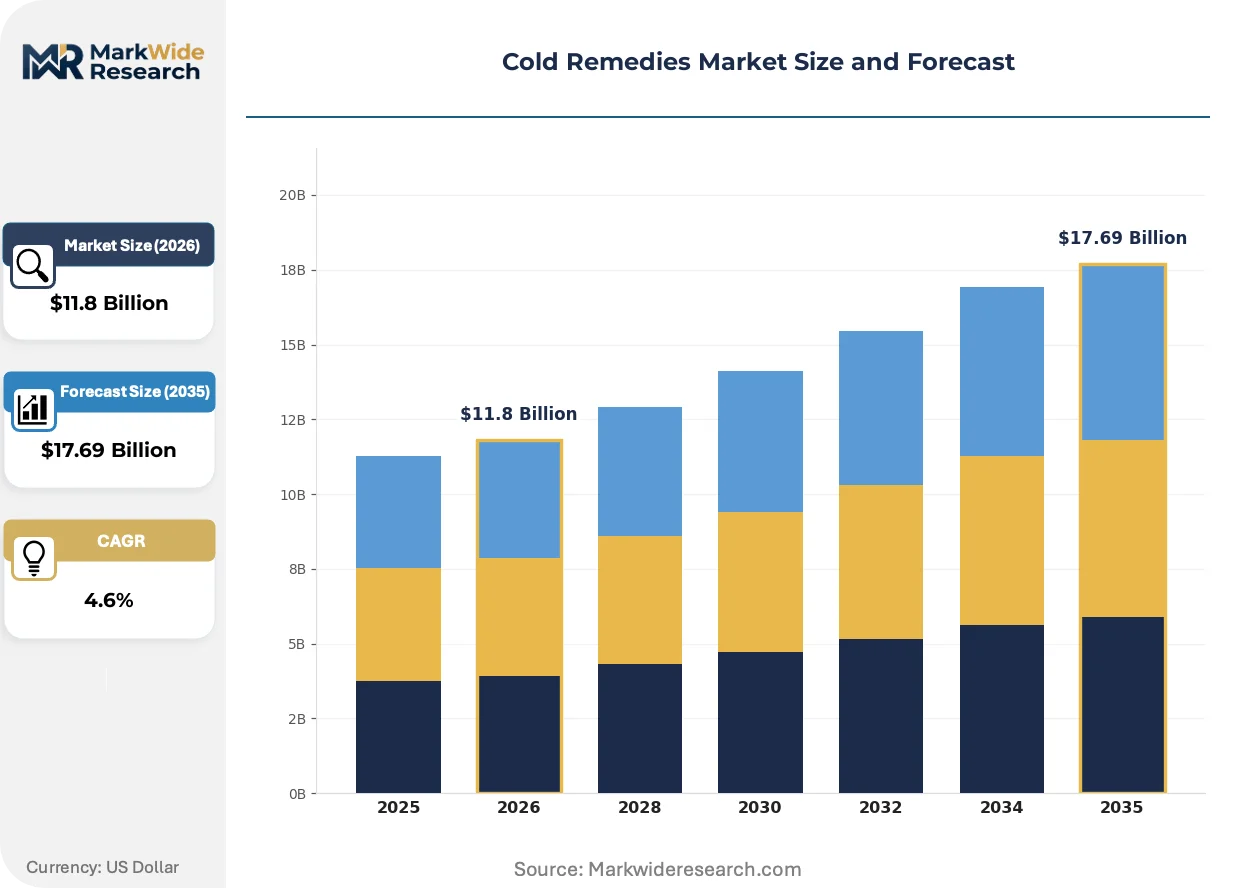
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Decongestants, Antihistamines, Cough Suppressants, Expectorants Delivery Mode: Tablets, Syrups, Nasal Sprays, Lozenges End User: Adults, Children, Seniors, Caregivers Packaging Type: Blister Packs, Bottles, Sachets, Jars |
| Companies Covered | Reckitt Benckiser Group plc, Johnson & Johnson Services, Inc., GlaxoSmithKline plc, Novartis AG, Bayer AG, AstraZeneca plc, Sun Pharmaceutical Industries Ltd., Pfizer Inc., Prestige Brands Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Remedies Market Emerging Trajectories
Formulation science and delivery mechanism engineering are converging to reshape how active ingredients reach systemic circulation, with speed-to-symptom-relief becoming the primary competitive battleground.
Continuous manufacturing platforms are rewriting production economics for liquid suspensions. Mid-tier United States contract manufacturers are adopting modular processing skids to compress batch cycle times from days to hours. This technology is rewriting capacity utilization metrics and enabling just-in-time inventory models for pharmacy chain private-label programs.
The EPA's phasedown of hydrofluorocarbon propellants under the AIM Act is forcing nasal spray manufacturers toward compressed gas and aqueous pump alternatives. Domestic formulators investing in aqueous system stability science are securing provisional shelf-space commitments ahead of 2025 compliance deadlines. Pediatric and geriatric segments show strongest preference migration toward propellant-free delivery.
Subscription-based replenishment models are displacing episodic pharmacy purchasing among urban United States households with predictable seasonal illness patterns. Amazon Pharmacy and CVS CarePass are capturing recurring revenue streams through algorithmic reminder systems tied to regional influenza surveillance data. This shift concentrates demand forecasting accuracy advantages with platforms possessing integrated health data ecosystems.
Cold Remedies Market Segmentation
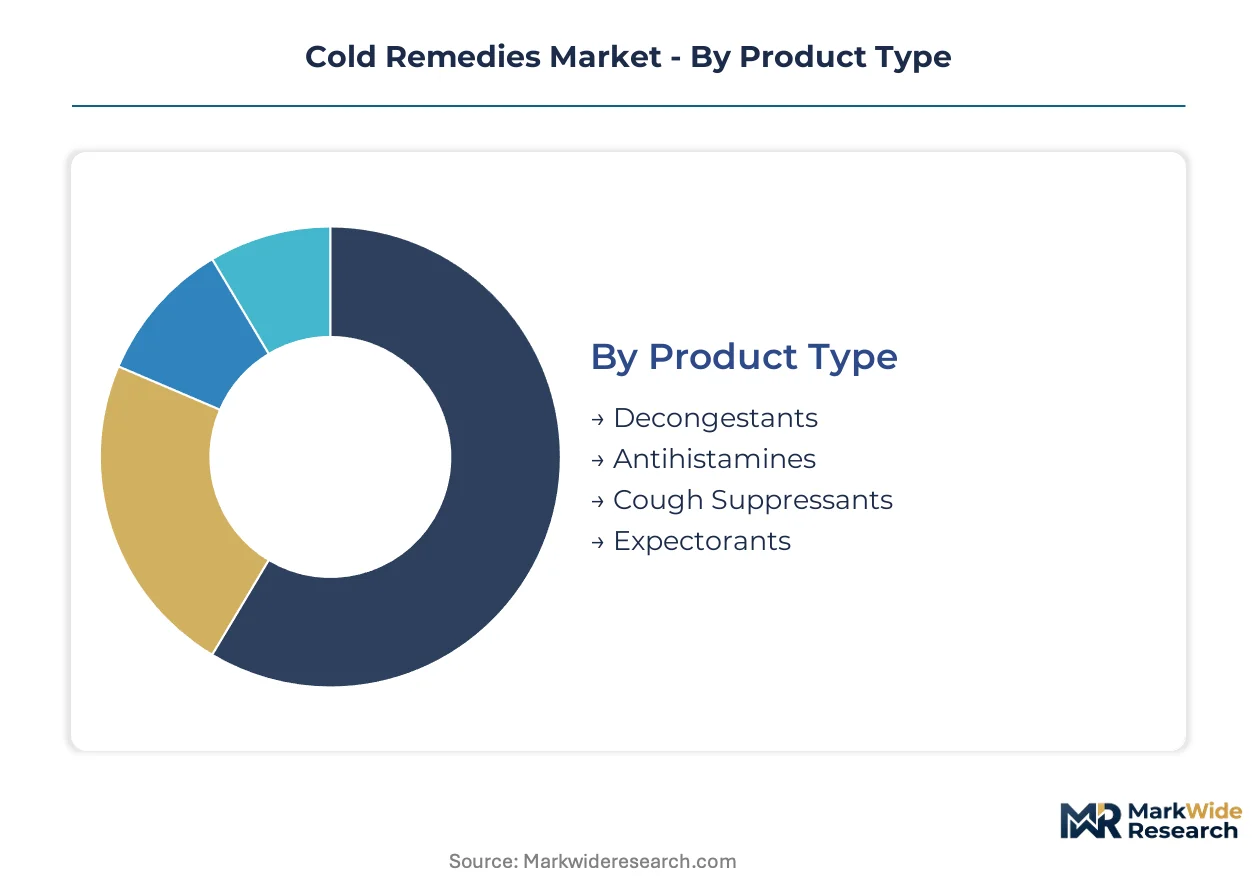
Cold remedy manufacturers calibrate formulation, dosage, and packaging specifications to distinct buyer profiles across therapeutic need, administration preference, and purchasing context. Segmentation discipline separates volume-heavy pharmacy chains from premium-positioned direct-to-consumer channels.
Product Type:
Buyer differentiation in this category hinges on symptom severity and speed-of-relief expectations rather than price sensitivity alone.
- Decongestants:Formulations containing pseudoephedrine or phenylephrine target nasal mucosal vasoconstriction for rapid sinus pressure relief. Demand concentrates in the United States during October-March influenza season, with pharmacy retail chains capturing repeat purchases through private-label substitution.
- Cough Suppressants:Dextromethorphan-based preparations interrupt the medullary cough reflex for nighttime symptom management. Working-age demographics in urban United States markets drive preference for workplace-compatible dosing that avoids sedation.
- Antihistamines:Chlorpheniramine and diphenhydramine formulations block H1 receptors for rhinorrhea control.
- Expectorants:Guaifenesin-based products thin bronchial secretions for productive cough management.
Volume sits with Decongestants; growth tilts toward Cough Suppressants.
Delivery Mode:
Route of administration selection reflects age-related swallowing capability, onset speed requirements, and workplace discretion needs.
- Nasal Sprays:Metered-dose aqueous and propellant-based systems deliver topical decongestion with sub-minute onset. United States professionals favor portable, discreet administration during commuting hours, though EPA hydrofluorocarbon phasedown is forcing propellant reformulation investments.
- Tablets:Compressed solid dosage forms enable precise milligram dosing and extended-release engineering. Developed-market pharmacy chains favor blister-pack tablets for inventory efficiency and theft reduction.
- Syrups:Liquid suspensions accommodate pediatric and geriatric populations with dysphagia, particularly in Japan where METI guidelines emphasize geriatric-accessible packaging.
- Lozenges:Slow-dissolving oral matrices provide throat-soothing actives with localized anesthetic effect.
Tablets dominate transaction counts; Nasal Sprays are climbing the fastest.
End User:
Purchasing authority and safety tolerance thresholds create distinct formulation requirements across age and care relationships.
- Adults:Self-medicating consumers aged 18-64 select multi-symptom combination products for convenience. United States telehealth platforms now enable direct-to-patient subscription channels for seasonal pre-positioning.
- Caregivers:Parents and professional care providers demand pediatric-specific dosing clarity and tamper-evident packaging. Homeopathic substitute preference is strongest among this segment, constraining synthetic active growth.
- Children:Weight-based dosing requirements and palatability engineering drive syrup and chewable dominance.
- Seniors:Polypharmacy interaction risks and swallowing difficulties favor single-ingredient, dysphagia-friendly formats.
Adults generate the highest absolute volume; Caregivers show the steepest expansion trajectory.
Packaging Type:
Supply chain efficiency and retail theft exposure determine format selection more than consumer preference alone.
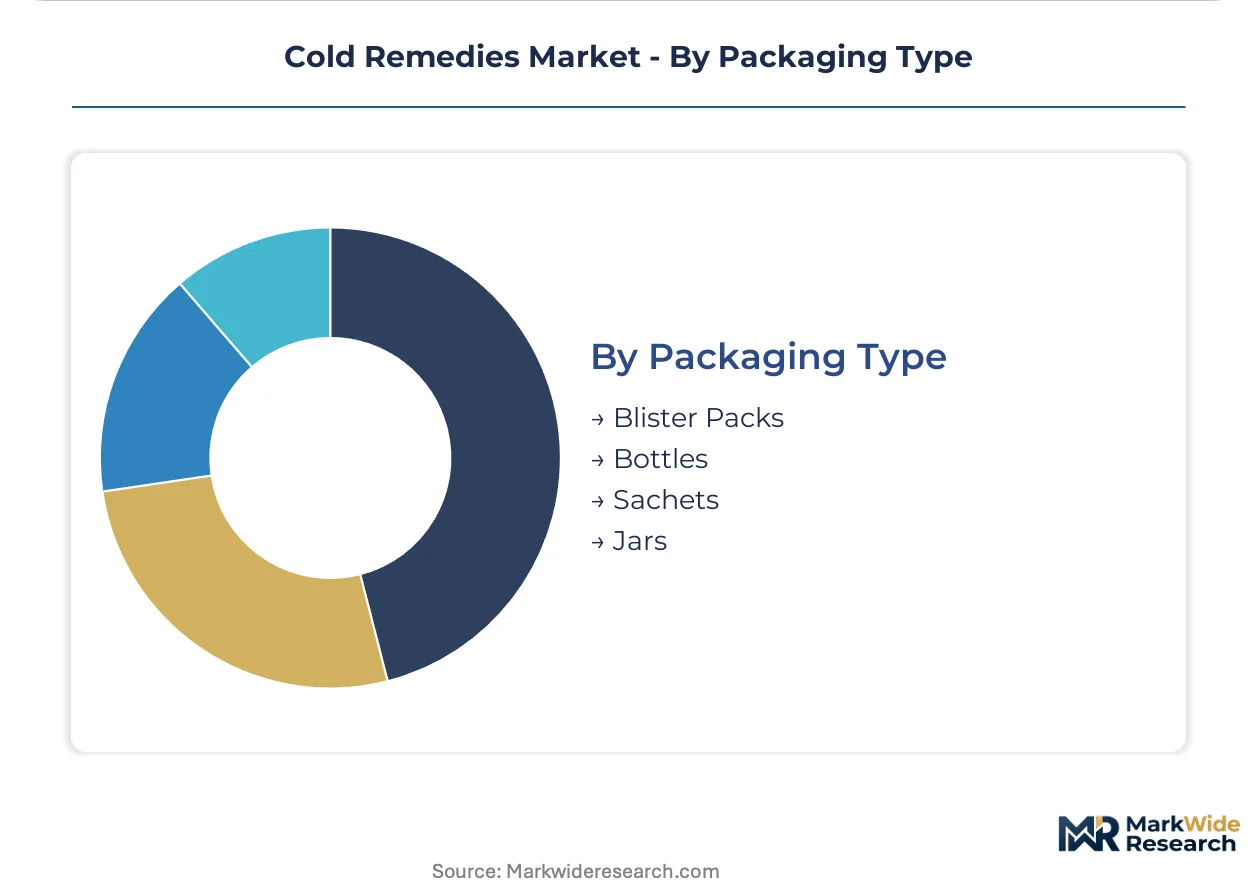
- Blister Packs:Individual cavity sealing with aluminum-laminate backing enables unit-dose dispensing and extended shelf stability. United States pharmacy chains mandate blister formats for high-shrink SKUs.
- Bottles:HDPE and PET containers accommodate liquid suspensions with child-resistant closure requirements.
- Sachets:Single-use foil pouches serve travel and sample distribution channels.
- Jars:Wide-mouth containers support lozenge and medicated cream categories.
Blister Packs command the largest unit volume; Bottles retain the widest format applicability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India and China's coastal provinces concentrate API manufacturing for cold remedy actives, while FDA-regulated formulation plants cluster in Puerto Rico and New Jersey corridors serving North American demand.
United States
Pharmacy retail chains drive volume through private-label substitution and telehealth-integrated subscription models. The FDA's OTC monograph reform compels manufacturers to revalidate pseudoephedrine and dextromethorphan dossiers ahead of final determinations. New Jersey and Puerto Rico host concentrated formulation facilities supplying national distribution networks.
China
Precursor chemical manufacturing for pseudoephedrine concentrates in Jiangsu and Shandong province clusters, exposing formulators to export license volatility. NMPA alignment with international API quality standards is accelerating facility upgrades. Zhejiang province contract manufacturers are expanding tablet compression capacity for Western private-label programs.
Germany
REACH compliance investments in propellant reformulation are capturing shelf space from non-compliant imports across European pharmacy chains. ECHA volatile organic compound restrictions are forcing hydrofluoroalkane transitions in nasal spray manufacturing. Bavaria-based formulators lead aqueous pump system stability science development.
India
CDSCO-approved facilities in Gujarat and Maharashtra produce generic dextromethorphan and guaifenesin for export markets. PLI scheme incentives are expanding domestic tablet and liquid suspension capacity. Hyderabad's pharmaceutical cluster specializes in pediatric syrup formulations for Middle East and African markets.
Japan
METI geriatric-accessible packaging guidelines favor dysphagia-friendly delivery formats for aging populations. PMDA post-market surveillance requirements constrain rapid formulation changes. Osaka-Kobe industrial corridor manufacturers dominate lozenge and medicated throat drop production for domestic and Asian export markets.
Cold Remedies Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with decongestant and cough suppressant categories consolidating around heritage consumer health portfolios while private-label penetration rises in pharmacy retail channels. Three archetypes dominate: science-backed pharmaceutical majors with healthcare professional recommendation networks, diversified consumer health conglomerates controlling shelf space through retail partnerships, and emerging regional formulators capturing share via cost-competitive API integration. Competitive moves concentrate on portfolio reformulation ahead of regulatory deadlines and vertical integration into precursor chemical supply.
Among UK-heritage consumer health specialists, Reckitt Benckiser Group plc and GlaxoSmithKline plc exemplify brand-equity-driven positioning in decongestant and multi-symptom categories. Johnson & Johnson Services, Inc. represents the diversified healthcare conglomerate archetype, anchoring pediatric formulation strength through retail pharmacy network density. These three entities occupy positions reflecting distinct strategic bets on healthcare professional influence versus direct-to-consumer marketing intensity.
| Leading Market Players |
|---|
| Reckitt Benckiser Group plc |
| Johnson & Johnson Services, Inc. |
| GlaxoSmithKline plc |
| Novartis AG |
| Bayer AG |
| AstraZeneca plc |
| Sun Pharmaceutical Industries Ltd. |
| Pfizer Inc. |
| Prestige Brands Holdings, Inc. |
| Others |
Supply Flow & Price Mechanics
Pseudoephedrine precursor costs originating in Jiangsu and Shandong province chemical clusters cascade through three pricing tiers before reaching United States pharmacy shelves, with API concentration in China amplifying volatility exposure for formulators negotiating annual supply contracts.
Pricing Analysis
Short lead-time premiums command pricing power for domestic manufacturers holding FDA-validated pseudoephedrine dossiers ahead of monograph finalization, while spot inventory discounts attract private-label pharmacy chains with flexible formulation timelines. Three-tier pricing structure across premium branded, standard retail, and economy private-label levels separates heritage equity players from contract manufacturers and store brands. Pricing pressure stems from REACH compliance investments in propellant reformulation that compress margins for European nasal spray specialists. Private-label pharmacy chains exhibit highest price sensitivity, while pediatric caregivers accepting synthetic actives show lowest elasticity due to safety premium tolerance.
Supply Chain Analysis
Direct-to-pharmacy channels handle hyperscale private-label demand from CVS and Walgreens, while distributor intermediaries serve independent drugstores with smaller lot sizes. API manufacturing concentrates in China, India, and Germany, with precursor chemicals drawing from concentrated chemical clusters in Jiangsu and Shandong provinces. Formulation dependencies rest on pseudoephedrine, dextromethorphan, and hydrofluoroalkane propellants. Single-source vulnerability in Chinese precursor export licensing exposes formulators to supply interruption. Distribution runs through wholesale distributors McKesson and AmerisourceBergen before pharmacy shelf placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cold remedies sector sits in a technology-transition phase as aqueous pump systems displace hydrofluorocarbon propellants under EPA phasedown mandates, forcing capital reallocation toward stability science and manufacturing retooling.
For Market Incumbents: Lock in propellant-free formulation expertise ahead of EPA compliance deadlines to defend shelf space against compliant European imports. Secure backward integration into precursor chemical supply to reduce Jiangsu cluster dependency. Prioritize pediatric and geriatric dysphagia-friendly delivery formats where synthetic active tolerance remains highest.
For New Entrants and Emerging Players: Continuous manufacturing platforms for liquid suspensions offer technology-first entry into private-label contract manufacturing serving pharmacy chain just-in-time inventory models. Target mid-tier United States contract manufacturing capacity constrained by MES platform overhaul costs. Pursue direct-to-patient subscription channel partnerships with telehealth platforms as the primary go-to-market angle.
For Investors and Strategic Acquirers: FDA monograph finalization on dextromethorphan efficacy is the leading indicator that portfolio reformulation requirements will trigger consolidation among mid-tier manufacturers lacking R&D bandwidth. Five-to-ten year viability favors formulators with validated aqueous stability science and established pharmacy chain relationships. Monitor CDSCO facility upgrade timelines in Gujarat and Maharashtra as signals of Indian export capacity expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Propellant Reformulation Investment | EPA AIM Act compliance secures nasal spray shelf space ahead of hydrofluorocarbon phasedown deadlines. |
| Continuous Manufacturing Adoption | Modular processing skids compress batch cycle times for pharmacy chain private-label programs. |
| Pediatric Formulation Development | METI geriatric-accessible packaging guidelines open Japan market entry for dysphagia-friendly formats. |
| Telehealth Platform Partnership | Amazon Pharmacy and CVS CarePass integration enables recurring revenue through algorithmic replenishment. |
| API Supply Diversification | CDSCO-approved Gujarat and Maharashtra facilities reduce concentration risk in Chinese precursor clusters. |
Methodological Framework
Document review covered FDA OTC monograph proceedings, EPA AIM Act implementation guidance, and ECHA REACH compliance databases, complemented by interviews with formulation chemistry directors, pharmacy chain category managers, and regulatory affairs leads at OTC manufacturers. Secondary sources included customs trade data for API movements, SEC 10-K filings from consumer health conglomerates, and Nielsen retail audit data for pharmacy channel volume. Bottom-up demand modeling from end-user segments was cross-referenced against top-down market sizing from manufacturer revenue disclosures.
Historical volume trajectories were cross-referenced against panel input from procurement officers at wholesale distributors to calibrate projection assumptions across the analysis window. Segmentation dimensions modeled included product type, delivery mode, end user age cohort, and packaging format. CAGRs were derived from regression analysis of historical transaction data adjusted for regulatory inflection points. Industry-specific forecast inputs incorporated FDA monograph timeline scenarios and seasonal influenza surveillance patterns from CDC data.
Several conditions sit outside the modeled scope, including potential FDA ingredient reclassification decisions, abrupt export license suspensions in Chinese chemical clusters, and pandemic-scale respiratory illness disruptions beyond historical variance. Forecasts reflect assumptions about regulatory timeline adherence and consumer self-medication trend continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Melatonin Sleep Supplements Market
Dietary Supplements
Pet Allergy Immune Supplements Market
Dietary Supplements
Pet Skin and Coat Health Supplement Market
Dietary Supplements
Herbal Medicine Market
Dietary Supplements
Immune Health Supplements Market
Dietary Supplements
Concentrated Angelica Pills Market
Dietary Supplements
Menopause Supplement Market
Dietary Supplements
Global Vitamin D Therapy Market
Dietary Supplements
Ipriflavone Market
Dietary Supplements
Testosterone Injectable Market
Dietary Supplements
Oral Clinical Nutrition Supplements Market
Dietary Supplements
Australia Nicotine Replacement Therapy Market
Dietary Supplements
Eye Care Supplements Market
Dietary Supplements
Androgens and Anabolic Steroids Market
Dietary Supplements
Global Beauty Supplements Market
Dietary Supplements
Canine Weight Loss Drugs Market