
 Concentrated Angelica Pills Market | 2026-2036
Concentrated Angelica Pills Market Size, Share, and Industry Trends Forecast 2026-2036
Concentrated Angelica Pills Market Insights
Women's health and wellness clinics is expanding as a primary demand channel for concentrated angelica pills, shifting the end-use vertical mix away from general retail toward specialized healthcare settings. Bio-Botanica Inc. leverages its botanical extraction expertise to serve pharmaceutical-grade supply chains. Changsha Luyuan Bio-Tech Co. Ltd. anchors production capacity in China's angelica cultivation heartland. Tropical Herb Products Co. Ltd. competes through specialized traditional remedy formulations targeting Southeast Asian markets.
Concentrated angelica pills are standardized botanical preparations derived from Angelica sinensis root, typically containing measured levels of ferulic acid and polysaccharides achieved through ethanol extraction and vacuum concentration processes, formulated for hematopoietic and gynecological therapeutic applications. Capsule formats dominate volume due to dosing precision and patient compliance advantages in clinical settings. Tablet formulations sustain margin pools through extended-release coating technologies that differentiate premium positioning. Powder segments occupy niche positions in compounding pharmacy and traditional remedy applications where customization drives value.
China's NMPA herbal registration pathways and South Korea's MFDS botanical drug standards shape product development requirements and cross-border market access protocols for manufacturers. The FDA's dietary supplement GMP enforcement and EFSA novel food evaluations create additional compliance thresholds for export-oriented producers. Stakeholders must monitor evolving pharmacovigilance requirements for botanical concentrates as regulatory frameworks tighten traceability and adulteration controls across major demand markets.
Market Dynamics
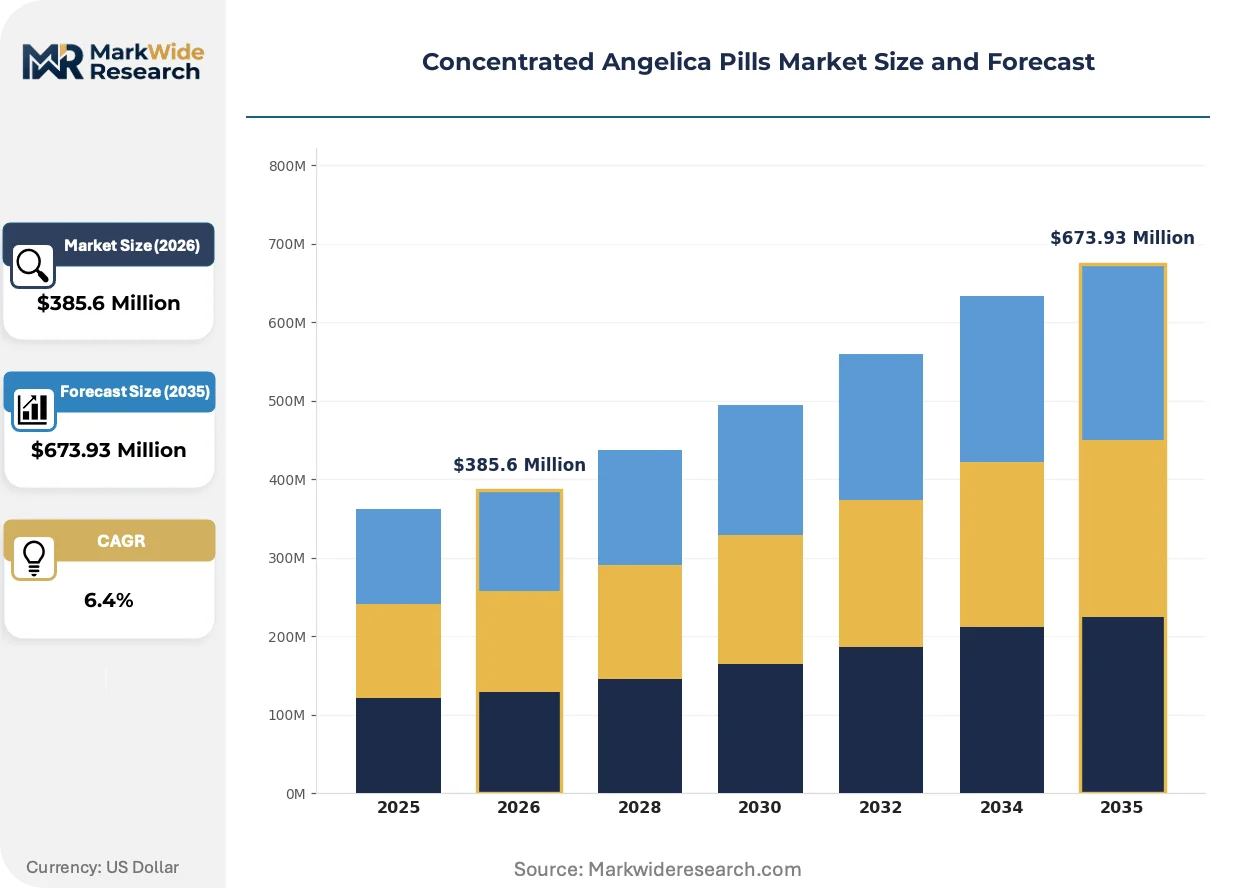
China's NMPA herbal registration reforms are compressing time-to-market for concentrated botanical preparations while simultaneously tightening pharmacovigilance traceability requirements, forcing manufacturers to rebuild quality systems around serialization and batch-level documentation.
Growth Catalysts
- Women's health clinic integration:Specialized healthcare settings in South Korea and Japan are replacing general retail as primary demand channels, driving volume through prescriber networks rather than consumer self-selection.
- MFDS botanical drug standards:South Korea's regulatory framework is creating harmonization pathways that reduce duplicate testing burdens for cross-border suppliers serving East Asian markets.
- Ethanol extraction standardization:Vacuum concentration process improvements are yielding more consistent ferulic acid and polysaccharide levels, enabling clinical-grade claims that differentiate premium formulations.
Market Restraints
- Angelica sinensis supply concentration:Raw material sourcing clusters in specific cultivation zones of Gansu and Yunnan provinces, creating weather and crop-yield vulnerability for downstream processors.
- EFSA novel food evaluation timelines:European market access requires extensive safety dossiers that extend commercialization timelines by 24-36 months compared to traditional medicine jurisdictions.
- Synthetic hematopoietic substitutes:Pharmaceutical alternatives for anemia management compete directly with angelica-based formulations in reimbursement-sensitive healthcare systems.
Strategic Opportunities
- Compounding pharmacy channels:Powder format producers can capture value in North American and European markets where customization drives premium pricing outside standardized product regulations.
- Extended-release coating technologies:Tablet format innovators can differentiate through modified-release profiles that improve patient compliance in chronic gynecological applications.
- Thailand and Vietnam distribution:Southeast Asian markets with deepening traditional medicine infrastructure present underpenetrated expansion targets for established East Asian suppliers.
Industry Challenges
- Phytochemical standardization expertise:Ferulic acid quantification and polysaccharide profiling require specialized analytical chemistry capabilities that outpace current workforce development in botanical processing regions.
- Dual registration requirements:Manufacturers targeting both pharmaceutical and dietary supplement positioning must maintain parallel compliance systems under FDA GMP and NMPA drug standards simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concentrated Angelica Pills Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extract, Capsule, Tablet, Powder End User: Distributors, Retailers, Pharmacies, Online Customers Application: Dietary Supplement, Herbal Medicine, Traditional Remedies, Health Optimization Packaging Type: Bottles, Blister Packs, Pouches, Jars |
| Companies Covered | Thiptipa Co. Ltd., Bio-Botanica Inc., Zingo Enterprise Co. Ltd., Tropical Herb Products Co. Ltd., Mighty International Co. Ltd., DENK Ingredients GmbH, Changsha Luyuan Bio-Tech Co. Ltd., Changsha Huir Biological-Tech Co. Ltd., Dingxi Fengyuan Import and Export Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concentrated Angelica Pills Market Trends and Innovations
Technological convergence in extraction and formulation is compressing the gap between traditional remedy positioning and clinical-grade therapeutic claims, while regulatory divergence between jurisdictions is fragmenting product development roadmaps.
Supercritical CO2 extraction is unifying quality and yield objectives previously treated as trade-offs in ethanol-based processing. Women's health and wellness clinics in Japan are adopting these extracts at accelerated pace for prescriber-dispensed formulations. This technology is unifying premium and standard tier supply chains by reducing batch-to-batch variation that previously separated clinical-grade from commodity products.
China's NMPA herbal product registration reforms are mandating full supply chain traceability from cultivation to finished dose. Manufacturers must now implement serialization systems that document each processing stage for regulatory audit. Concentrated pill producers serving domestic and export markets simultaneously face the steepest compliance reconstruction costs.
Specialized healthcare settings are displacing retail pharmacy as the dominant channel for patient acquisition. South Korean women's health clinics now account for the majority of new patient starts for hematopoietic and gynecological applications. This channel rotation is most visible in Seoul and Tokyo metropolitan areas where integrated traditional-modern medicine networks have achieved deepest penetration.
Concentrated Angelica Pills Market Segmentation
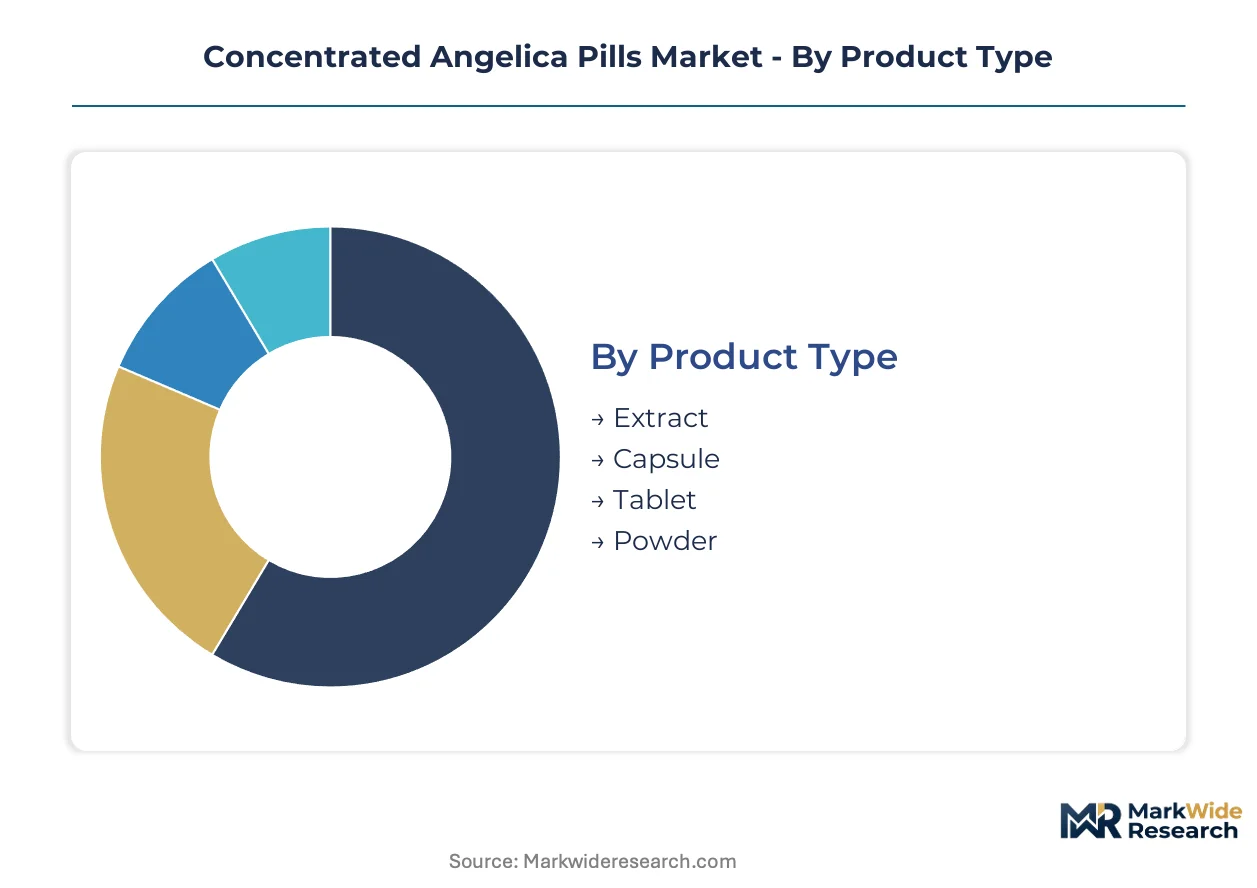
Segmentation in concentrated angelica pills reflects divergent supply chain requirements across clinical-grade and commodity channels. Manufacturers configure extraction and formulation assets differently depending on whether target customers demand standardized potency or customized compounding flexibility.
Product Type:
Supply concentration in ethanol extraction and vacuum concentration infrastructure favors formats that amortize capital investment across high-throughput production runs.
- Capsule:Hard gelatin and vegetable-based shells deliver precise ferulic acid dosing for women's health clinics in Seoul and Tokyo. South Korean MFDS botanical drug standards favor this format for prescriber-dispensed hematopoietic applications. Extended-release coating technologies differentiate premium positioning in chronic gynecological therapy.
- Tablet:Compressed formulations with modified-release profiles improve patient compliance through reduced dosing frequency. Japan's METI-registered traditional medicine manufacturers dominate tablet production for domestic reimbursement pathways. Manufacturing requires dedicated compression and coating lines that raise capital barriers for new entrants.
- Extract:Liquid concentrates serve compounding pharmacies requiring customizable potency adjustment.
- Powder:Bulk material supports traditional remedy customization in Southeast Asian markets.
Capsule formats absorb the bulk of installed capacity; Tablet production is expanding most quickly through extended-release innovation.
End User:
Customer type determines regulatory compliance burden and margin structure, with institutional channels demanding documentation that retail bypasses.
- Pharmacies:Hospital and community dispensaries in Japan and South Korea require NMPA-equivalent serialization for traceability. China's herbal registration reforms mandate batch-level documentation that raises procurement standards. These channels capture premium pricing through prescriber endorsement and insurance reimbursement integration.
- Online Customers:Direct-to-consumer platforms in China and Southeast Asia bypass traditional distribution markups. E-commerce operators face intensifying FDA GMP scrutiny for cross-border sales into North American markets. Customer acquisition concentrates on mobile-first wellness platforms targeting urban female demographics.
- Distributors:Wholesale networks aggregate fragmented demand across regional traditional medicine practitioners.
- Retailers:Health food stores and specialty outlets serve self-directed consumers seeking general wellness applications.
Pharmacy channels command the steepest compliance investment; Online customer acquisition is climbing the fastest through platform consolidation.
Application:
Application segmentation tracks the boundary between regulated therapeutic claims and wellness positioning that determines market access pathways.
- Herbal Medicine:Clinically positioned formulations for gynecological and hematopoietic therapy require NMPA drug registration or MFDS botanical drug approval. China's registration reforms compress approval timelines while tightening pharmacovigilance requirements. Manufacturing must maintain dual compliance systems for domestic and export markets simultaneously.
- Dietary Supplement:Wellness-positioned products face FDA enforcement of 21 CFR 111 GMP standards and EFSA novel food evaluations for European access. Ferulic acid standardization levels determine whether products qualify for structure-function claims or require drug registration. EFSA safety dossiers extend European commercialization timelines substantially.
- Traditional Remedies:Cultural practice exemptions in Thailand and Vietnam permit marketing outside pharmaceutical regulations.
- Health Optimization:General wellness applications compete with synthetic alternatives in reimbursement-sensitive systems.
Herbal medicine applications dominate revenue concentration; Dietary supplement positioning is gaining share fastest through channel expansion.
Packaging Type:
Packaging configuration aligns with distribution channel requirements for shelf stability, tamper evidence, and patient compliance features.
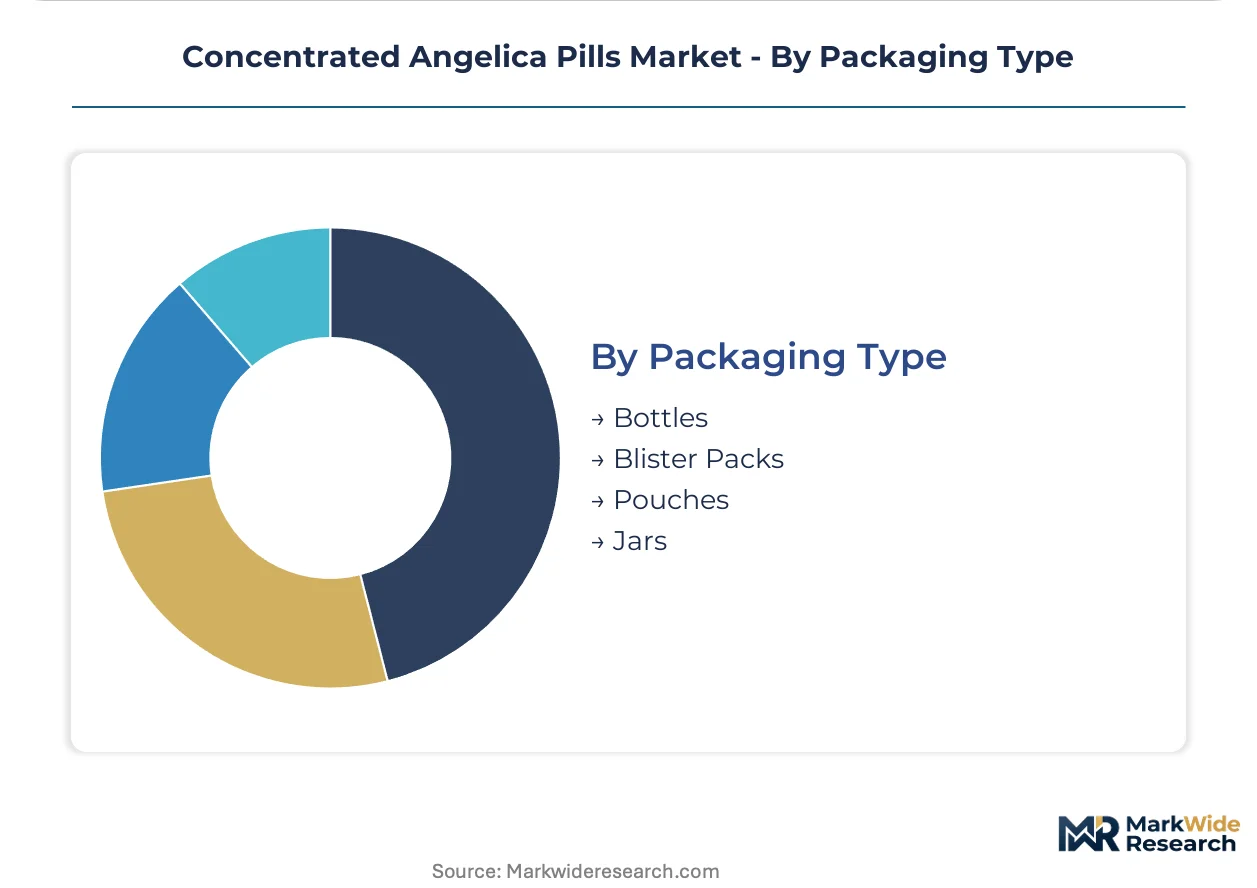
- Blister Packs:Unit-dose aluminum-plastic configurations support compliance programs in Japanese women's health clinics. PMDA packaging guidelines favor blister formats for prescription traditional medicines. Child-resistant and senior-friendly opening mechanisms differentiate premium tier positioning.
- Bottles:Amber glass and high-density polyethylene containers dominate retail pharmacy distribution for capsule and tablet counts. China's NMPA serialization mandates require integrated tamper-evident seals that increase per-unit packaging cost. Bulk bottle formats serve maintenance therapy prescriptions with 90-day supply standards.
- Pouches:Flexible film formats reduce shipping cube for powder segments and extract sachets.
- Jars:Wide-mouth containers accommodate powder scoop dispensing for compounding applications.
Bottle formats carry the majority of unit volume; Blister pack adoption is expanding most quickly through clinical channel preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates cultivation and extraction infrastructure for angelica root, while consumption spreads across East Asian clinical networks. Japan and South Korea absorb premium formulations through prescriber channels. Southeast Asian markets present expansion frontiers with lighter regulatory burdens.
China
NMPA herbal registration reforms compress approval timelines for concentrated botanical preparations while mandating serialization from field to finished dose. Gansu and Yunnan provinces anchor raw material supply, with Dingxi and Kunming processing clusters upgrading vacuum concentration capacity. Domestic manufacturers face parallel compliance burdens for pharmaceutical-grade domestic sales and dietary supplement exports.
Japan
Women's health clinics in Tokyo and Osaka metropolitan areas drive prescriber-dispensed volume for hematopoietic applications. METI-registered traditional medicine manufacturers dominate tablet production under PMDA packaging guidelines favoring blister formats. Supercritical CO2 extraction adoption accelerates in Kanto region facilities seeking batch-to-batch consistency.
South Korea
MFDS botanical drug standards create harmonization pathways reducing duplicate testing for cross-border suppliers. Seoul Capital Area clinics account for majority of new patient starts through integrated traditional-modern medicine networks. Busan-Ulsan corridor hosts formulation specialists serving domestic prescriber channels.
Thailand
Cultural practice exemptions permit traditional remedy marketing outside pharmaceutical regulations. Bangkok and Chiang Mai distribution networks aggregate demand from regional practitioners. Local compounding pharmacies source powder formats for customized gynecological preparations.
Vietnam
Deepening traditional medicine infrastructure in Hanoi and Ho Chi Minh City creates underpenetrated demand for established East Asian suppliers. Domestic distributors seek ethanol-extracted concentrates for clinic dispensing. Regulatory alignment with ASEAN harmonization protocols simplifies import documentation.
Concentrated Angelica Pills Market Competitive Landscape
Top-tier vendors anchor clinical-grade supply chains, while mid-tier specialists serve compounding and traditional remedy channels. The vendor base stratifies across extraction-scale tiers, with vacuum concentration assets determining cost position. Three archetypes dominate: botanical extraction specialists, regional formulation houses, and integrated cultivator-processors. Competitive moves concentrate on backward integration into Gansu cultivation zones and technology licensing for supercritical CO2 extraction.
Within the extraction-specialist tier, Bio-Botanica Inc. and Changsha Luyuan Bio-Tech Co. Ltd. exemplify divergent geographic anchoring strategies. Tropical Herb Products Co. Ltd. occupies a position bridging traditional remedy formulation and Southeast Asian distribution. DENK Ingredients GmbH represents European-market access capability through compliance with EFSA novel food evaluation frameworks. Changsha Huir Biological-Tech Co. Ltd. and Dingxi Fengyuan Import and Export Co. Ltd. sit within the cultivator-processor archetype, leveraging proximity to Gansu raw material zones.
| Leading Market Players |
|---|
| Thiptipa Co. Ltd. |
| Bio-Botanica Inc. |
| Zingo Enterprise Co. Ltd. |
| Tropical Herb Products Co. Ltd. |
| Mighty International Co. Ltd. |
| DENK Ingredients GmbH |
| Changsha Luyuan Bio-Tech Co. Ltd. |
| Changsha Huir Biological-Tech Co. Ltd. |
| Dingxi Fengyuan Import and Export Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Clinical-grade versus commodity-grade ferulic acid standardization creates divergent margin structures that propagate through extraction infrastructure choices and buyer procurement patterns. Premium capsule formats commanding prescriber-channel pricing in Seoul and Tokyo draw from dedicated vacuum concentration lines with batch-level serialization, while powder segments serving Southeast Asian compounding pharmacies absorb spot-market angelica root with minimal documentation overhead.
Pricing Analysis
Short lead-time premiums dominate contract structures for Japanese women's health clinics requiring serialized blister packs under PMDA packaging guidelines, while spot inventory discounts penetrate Southeast Asian distributor channels. Three-tier pricing structure across premium, standard, and economy levels reflects ferulic acid quantification precision and extended-release coating technology. Pricing pressure stems from synthetic hematopoietic substitutes competing for reimbursement coverage in South Korean hospital systems. Retail pharmacy buyers exhibit highest price sensitivity; prescriber-dispensed clinic channels accept premium positioning.
Supply Chain Analysis
Direct-to-clinic channels handle hyperscale demand from Seoul Capital Area integrated medicine networks, while distributor aggregation serves fragmented traditional practitioner demand across Thailand and Vietnam. Raw material supply draws from Gansu and Yunnan cultivation zones with Dingxi processing clusters anchoring extraction capacity. Angelica sinensis crop-yield vulnerability from weather exposure in concentrated growing regions presents structural supply risk. Distribution runs through prescriber networks in Japan and South Korea, with e-commerce platforms capturing self-directed demand in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction is displacing legacy ethanol-based vacuum concentration as the dominant processing technology, compressing batch-to-batch variation gaps between clinical-grade and commodity supply tiers.
For Market Incumbents: Deepen backward integration into Gansu cultivation zones to secure raw material supply against weather-driven crop volatility. Invest in serialization infrastructure to meet NMPA traceability mandates before compliance deadlines tighten. Lock prescriber-channel relationships in Tokyo and Seoul through extended-release formulation partnerships that synthetic substitutes cannot replicate.
For New Entrants and Emerging Players: Compounding pharmacies in North America represent an underserved buyer archetype with customization-driven demand outside standardized product regulations. Target powder format supply to Bangkok and Ho Chi Minh City distribution networks where cultural practice exemptions permit traditional remedy positioning. Pursue white-label manufacturing partnerships with established East Asian extractors to bypass capital-intensive vacuum concentration infrastructure.
For Investors and Strategic Acquirers: Re-rating potential sits with cultivator-processor hybrids given NMPA registration reform catalysts compressing time-to-market for compliant suppliers. Five-to-ten year viability favors integrated Gansu-based operations with captive angelica supply and dual domestic-export compliance systems. Watch MFDS botanical drug standard harmonization progress as the signal for cross-border supply chain consolidation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Adoption | Kanto region facilities achieve PMDA-grade batch consistency previously requiring premium tier separation. |
| Backward Integration into Gansu Cultivation | Dingxi processors secure captive angelica supply against Yunnan weather exposure and crop yield volatility. |
| Extended-Release Coating Technology | Tablet innovators capture chronic gynecological therapy compliance premiums in Japanese reimbursement pathways. |
| Serialization Infrastructure Deployment | NMPA-compliant batch documentation enables simultaneous domestic pharmaceutical and export dietary supplement positioning. |
| Southeast Asian Distribution Expansion | Bangkok and Chiang Mai networks aggregate Thailand's traditional practitioner demand with lighter regulatory burdens. |
Research Methodology
Document review covered NMPA herbal registration filings, MFDS botanical drug standards, and PMDA packaging guidelines, complemented by interviews with extraction facility managers, women's health clinic prescribing physicians, traditional medicine distributors, and pharmaceutical procurement officers. Secondary sources included customs trade data for angelica root imports, SEC filings for publicly traded botanical extractors, and hospital procurement databases tracking prescriber-dispensed traditional medicine volumes. Bottom-up volume modeling triangulated against top-down market sizing across product format segments.
Cross-referencing historical adoption curves for supercritical extraction technology against expert panel input on clinic integration timelines anchored growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled included product format, application positioning, end-user channel, and regional regulatory cluster. CAGRs derived from supply-side capacity expansion plans and demand-side prescriber network penetration curves, with ferulic acid standardization thresholds and extended-release coating adoption rates as industry-specific forecast inputs.
Revisions become necessary when NMPA traceability mandate enforcement timelines accelerate, MFDS-KFDA harmonization protocols expand, or synthetic hematopoietic substitute reimbursement coverage shifts in South Korean national health insurance. Forecasts reflect assumptions about continued traditional-modern medicine network integration in East Asian metropolitan areas and sustained angelica cultivation stability in Gansu core growing regions. Periodic stress-testing of base assumptions against crop yield reports and regulatory amendment notices is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Alpha Lipoic Acid Market
Dietary Supplements
Bone and Teeth Supplements Market
Dietary Supplements
Global Vitamin D Therapy Market
Dietary Supplements
Global Lipid Regulators Market
Dietary Supplements
Pediatric Supplements Market
Dietary Supplements
Hair Loss Supplement Market
Dietary Supplements
Fertility Supplements Market
Dietary Supplements
Australia Nicotine Replacement Therapy Market
Dietary Supplements
Veterinary Dietary Supplements Market
Dietary Supplements
Lifestyle-Related Disease Supplements Market
Dietary Supplements
Mens Health Supplements Market
Dietary Supplements
Immune Health Supplements Market
Dietary Supplements
Vitamin D Deficiency Treatment Market
Dietary Supplements
Bone and Joint Health Supplements Market
Dietary Supplements
Womens Health and Beauty Supplements Market
Dietary Supplements
Pet Skin and Coat Health Supplement Market