
 AI in Medical Coding Market | 2026-2036
AI in Medical Coding Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Medical Coding Market Analytics
The buyer base for AI coding platforms is broadening beyond large health systems to encompass mid-size physician groups and ambulatory surgery centers. Oracle leverages its Cerner EHR integration to anchor cloud-based coding workflows across integrated delivery networks. Nym Health specializes in autonomous clinical language understanding, differentiating its engine for emergency department encounters. IBM sustains enterprise credibility through Watson Health infrastructure, competing for multi-hospital contracts that demand on-premises data sovereignty.
AI in medical coding denotes software systems that apply natural language processing and machine learning algorithms to extract billable diagnostic and procedural codes from unstructured clinical documentation, operating with specificity thresholds that match or exceed certified human coders. Natural language processing dominates current deployments because physician notes remain predominantly free-text, while deep learning represents the fastest-expanding technology layer as transformer architectures improve entity recognition across specialties. Cloud-based delivery captures the largest deployment share due to lower capital barriers, though hybrid configurations are gaining traction among billing companies managing multiple client security protocols.
The US Department of Health and Human Services and CMS enforce documentation integrity standards that directly determine AI coding system validation requirements, while HIPAA mandates constrain how cloud-based platforms handle protected health information across subcontractor chains. The FDA exercises oversight when coding AI functions as software-as-a-medical-device components within broader clinical decision support systems. Stakeholders must monitor evolving state-level scope-of-practice rulings that could reclassify automated coding output as practicing medicine, triggering licensure barriers that reshape vendor go-to-market economics.
Market Dynamics
The transition from fee-for-service to value-based reimbursement under CMS rules is compressing documentation timelines and forcing health systems to automate code extraction at the point of care.
Growth Catalysts
- ICD-10-CM/PCS complexity:The expanded code set creates bottlenecks in human-only workflows, driving demand for autonomous clinical language processing in emergency departments and surgical suites.
- HIPAA-compliant cloud infrastructure:Hardened data architectures now permit protected health information to flow across subcontractor chains without on-premises captivity, lowering deployment barriers for mid-size physician groups.
- Staffing shortages in health information management:Certified coder attrition in United States acute care settings accelerates platform substitution for routine inpatient and outpatient encounters.
Market Restraints
- State-level scope-of-practice uncertainty:Pending rulings in multiple United States jurisdictions threaten to reclassify automated coding output as practicing medicine, triggering licensure barriers that reshape vendor economics.
- Hybrid deployment costs:Billing companies managing multiple client security protocols face elevated capital requirements for on-premise nodes alongside cloud instances.
- Transformer architecture limitations:Current deep learning models struggle with low-frequency specialty terminology in pathology and radiology reports, requiring sustained human oversight.
Strategic Opportunities
- Ambulatory surgery center penetration:United States outpatient surgical networks remain underautomated relative to integrated delivery networks, presenting whitespace for specialized emergency department coding engines.
- European outpatient network expansion:Continental health systems are consolidating diagnostic documentation across borders, creating demand for multilingual natural language processing that handles procedural coding variations.
- Real-time quality metric integration:Value-based care contracts now tie reimbursement to HEDIS and Star Ratings performance, enabling AI platforms that surface documentation gaps during the encounter rather than retrospectively.
Industry Challenges
- Certified coder retraining requirements:Health information management departments must reskill staff from production coding to exception handling and clinical validation, a transition that consumes 12-18 months in large hospital systems.
- EHR integration complexity:Legacy Cerner and Epic deployments require custom API development to feed unstructured notes into cloud-based coding engines, extending implementation timelines and consuming IT resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Medical Coding Market |
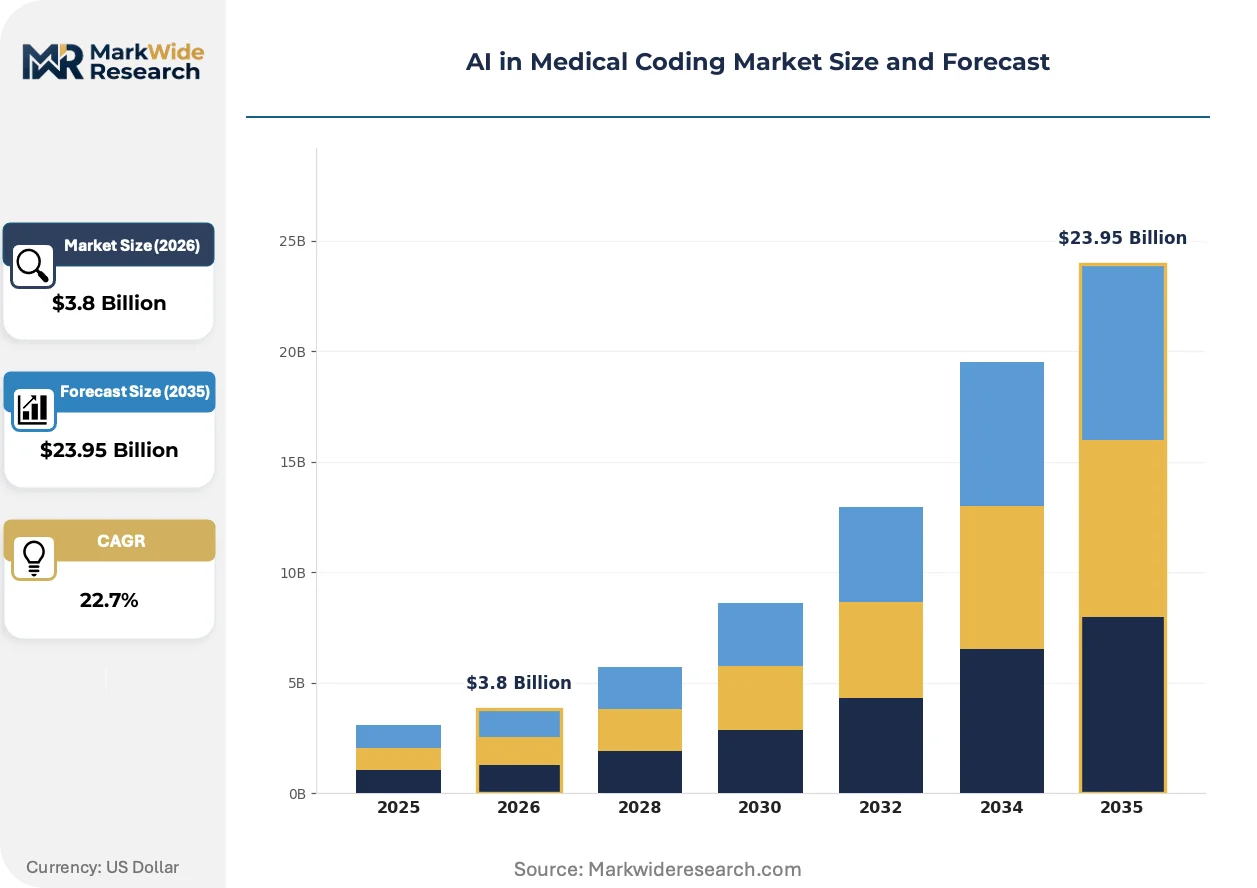
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $23.95 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Natural Language Processing, Machine Learning, Deep Learning, Computer Vision Deployment: Cloud-Based, On-Premises, Hybrid, Software as a Service End User: Hospitals, Clinics, Insurance Providers, Billing Companies Application: Revenue Cycle Management, Fraud Detection, Compliance, Claims Processing |
| Companies Covered | CodaMetrix, Fathom, Nym Health, Oracle, IBM, AKASA, Aideo Technologies, BUDDI.AI, Diagnoss, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Medical Coding Market Evolving Landscape
Natural language processing architectures are fragmenting into specialty-tuned modules that handle distinct clinical domains, while regulatory pressure on algorithmic accountability intensifies documentation standards for training data provenance.
Transformer-based entity recognition is modularizing across emergency medicine, cardiology, and orthopedic subspecialties. Large health systems in the United States are deploying specialty-specific models rather than monolithic platforms. This decomposition enables faster retraining cycles when CMS issues annual ICD-10-CM updates, compressing vendor release schedules from quarterly to monthly.
The FDA's evolving software-as-a-medical-device guidance now captures autonomous coding functions embedded within clinical decision support systems. Manufacturers must document training data demographics and performance disparities across patient populations. Emergency department platforms face the strictest scrutiny due to high-acuity decision timelines and downstream billing velocity.
Mid-size physician groups are consolidating purchasing through group purchasing organizations and regional health information exchanges, displacing direct vendor relationships. United States ambulatory networks now negotiate enterprise licenses collectively rather than practice-by-practice. This concentration shifts pricing power toward buyers and forces vendors to standardize implementation playbooks for faster deployment at scale.
AI in Medical Coding Market Segmentation
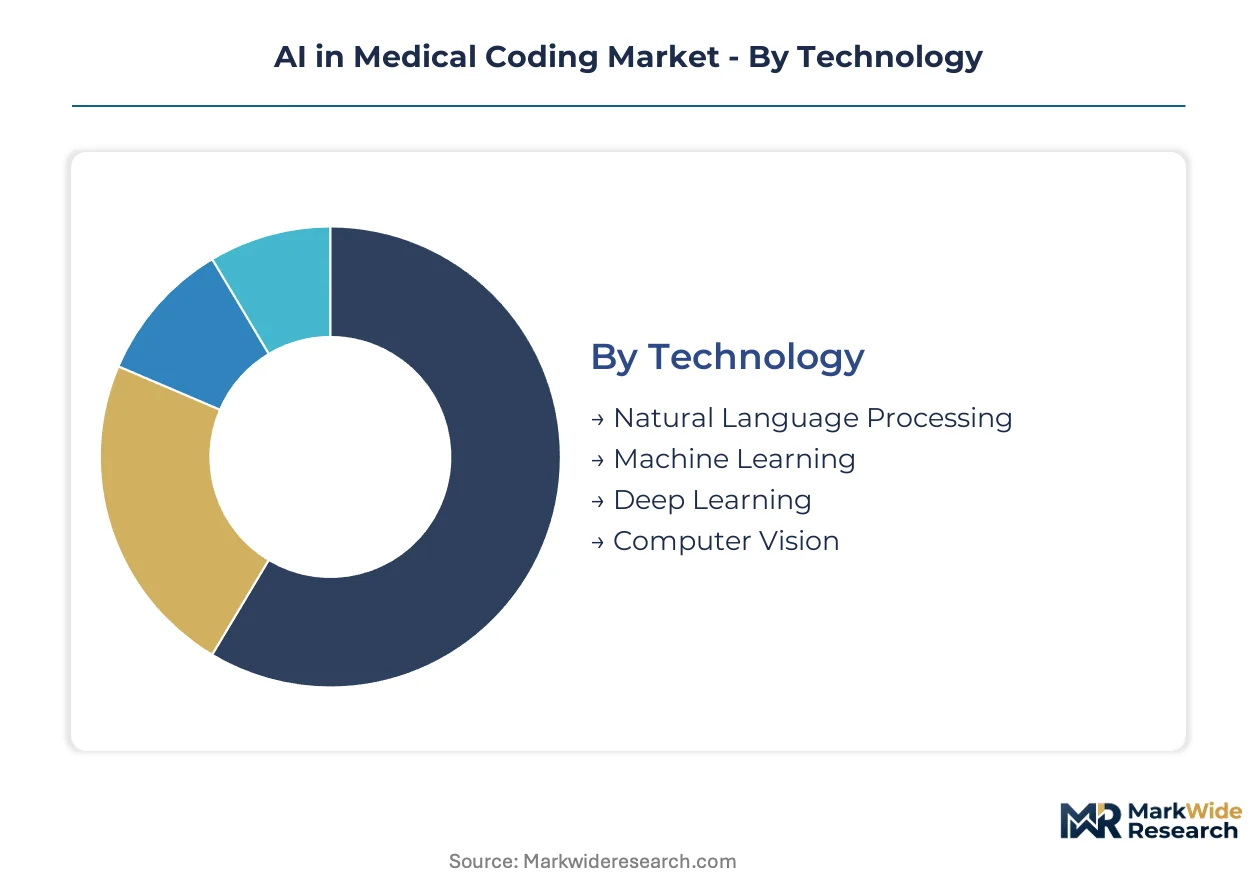
Segmentation in AI medical coding reveals how technology architecture, infrastructure choices, and buyer economics intersect. Each dimension exposes distinct integration patterns, cost structures, and regulatory exposure that shape vendor product roadmaps and customer procurement criteria.
Technology:
Natural language processing engines embed directly into EHR workflows, while deep learning modules operate as standalone pre-processing layers before human coder review.
- Natural Language Processing:Rule-based and statistical language models parse unstructured physician notes into structured code candidates. United States emergency departments deploy these engines at point-of-care to compress documentation-to-bill cycles under value-based contracting timelines.
- Deep Learning:Transformer architectures extract entities from complex clinical narratives with specialty-specific tuning. Large health systems in the United States favor these models for cardiology and orthopedic subspecialties where code complexity exceeds human throughput during high-acuity surges.
- Machine Learning:Supervised classification systems trained on historical coding decisions flag probable errors before claim submission. Mid-size physician groups adopt these for lower-cost automation of routine outpatient encounters.
- Computer Vision:Image-to-text pipelines extract codes from scanned paper records and handwritten clinical documentation. Billing companies managing legacy client archives deploy these to digitize retrospective encounters without manual transcription.
Natural language processing leads volumes today; deep learning is gaining share fastest.
Deployment:
Cloud configurations dominate mid-market physician groups lacking capital for server infrastructure, while hybrid architectures spread risk across client security protocols.
- Cloud-Based:Multi-tenant SaaS architectures with HIPAA-compliant subcontractor chains eliminate on-premises hardware requirements. United States ambulatory surgery centers prefer these for rapid deployment without IT staff expansion.
- Hybrid:Sensitive data remains on local nodes while compute-intensive model training leverages cloud elasticity. Billing companies managing multiple hospital clients adopt this to satisfy divergent security postures without duplicating entire technology stacks.
- On-Premises:Air-gapped installations serve health systems with strict data sovereignty mandates or state-level restrictions on cross-border PHI transfer. These deployments require 12-18 month implementation timelines and dedicated infrastructure teams.
- Software as a Service:Subscription pricing with standardized implementation playbooks enables group purchasing organizations to negotiate enterprise licenses across regional physician networks. United States outpatient consolidations favor this for predictable operating expenditure profiles.
Cloud-based deployment leads volumes today; hybrid configurations are climbing the fastest.
End User:
Hospital procurement cycles stretch 18-24 months with extensive EHR integration requirements, while billing companies prioritize multi-tenant scalability across heterogeneous client environments.
- Hospitals:Acute care systems in the United States deploy comprehensive platforms spanning emergency, surgical, and inpatient documentation. These buyers demand specialty-tuned modules and real-time quality metric integration for CMS value-based programs.
- Billing Companies:Revenue cycle management vendors process encounters across dozens of health system clients with incompatible EHR instances. Their procurement prioritizes API flexibility and rapid onboarding protocols over deep clinical workflow integration.
- Clinics:Outpatient physician groups with 10-50 providers seek point solutions for specific documentation bottlenecks. These buyers favor cloud-based natural language processing with minimal IT configuration.
- Insurance Providers:Payers deploy autonomous coding engines for pre-authorization validation and retrospective claims review. Their implementations emphasize fraud detection algorithms and compliance auditing rather than provider workflow acceleration.
Hospitals lead volumes today; billing companies are expanding most quickly.
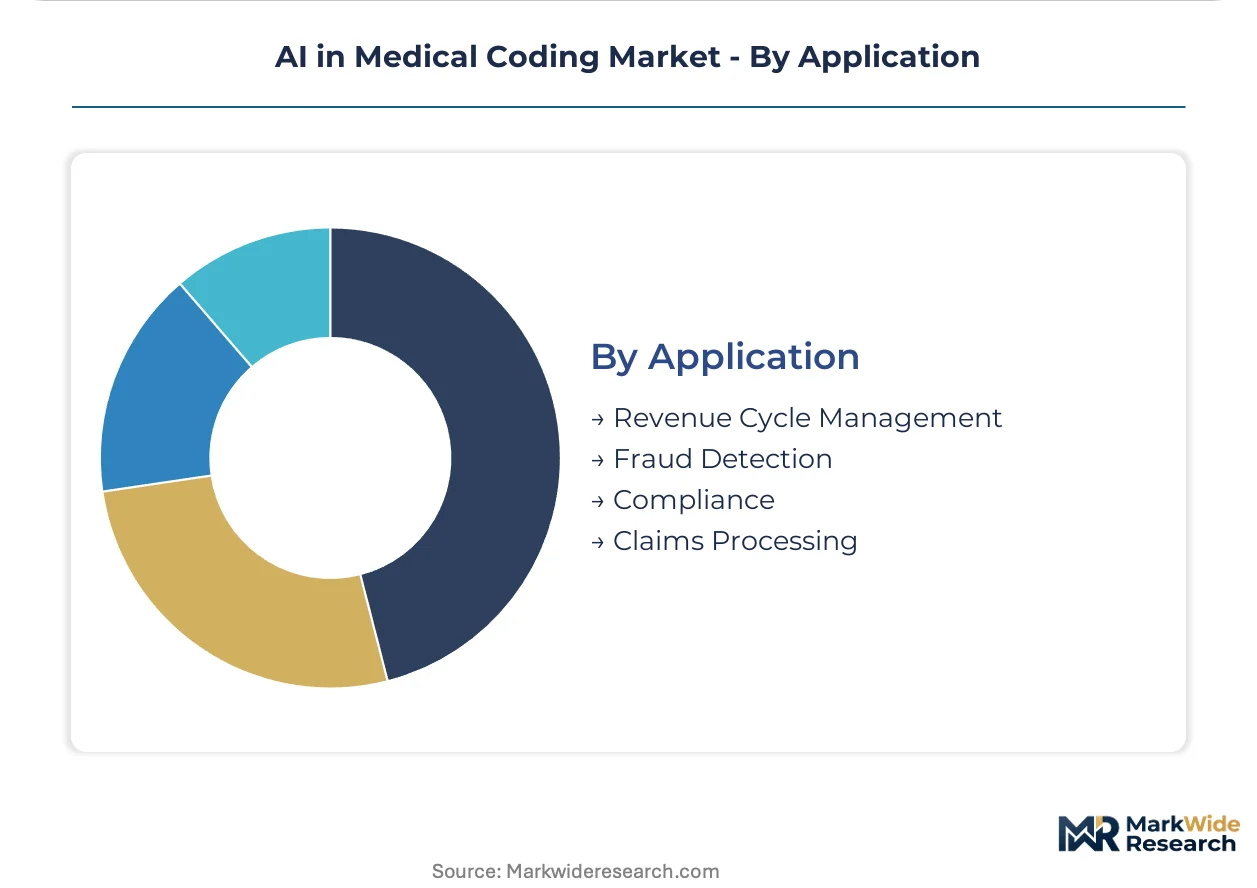
Application:
Revenue cycle management absorbs the majority of platform investment, while compliance applications face intensifying FDA scrutiny under software-as-a-medical-device guidance.
- Revenue Cycle Management:End-to-end automation from documentation capture through claim submission and denial management. United States health systems under CMS value-based contracts prioritize these platforms to compress days-to-bill metrics.
- Compliance:Automated auditing against documentation integrity standards enforced by the US Department of Health and Human Services. These applications face the strictest regulatory validation requirements when embedded in clinical decision support workflows.
- Fraud Detection:Pattern recognition across historical claims to identify aberrant coding sequences before payer submission. Insurance providers and billing companies deploy these to mitigate recovery audit contractor exposure.
- Claims Processing:Real-time code validation and bundling logic acceleration for high-volume transaction environments. Large billing operations use these to maintain throughput during seasonal patient volume surges.
Revenue cycle management leads volumes today; compliance applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified medical coders concentrate in the United States, where health systems face acute staffing shortages and ICD-10-CM complexity drives automation demand. This talent scarcity shapes platform deployment patterns across major healthcare markets.
United States
Hospital systems in Texas and Florida deploy autonomous coding engines to address emergency department throughput pressures under CMS value-based contracts. The Department of Health and Human Services enforces documentation integrity standards that determine AI validation requirements. The Dallas-Fort Worth metroplex anchors a cluster of revenue cycle management vendors serving multi-hospital networks with hybrid cloud deployments.
Germany
Outpatient networks in Bavaria and North Rhine-Westphalia consolidate diagnostic documentation across regional health information exchanges. The EU AI Act imposes algorithmic accountability requirements on clinical decision support systems with embedded coding functions. Berlin hosts a concentration of health IT consultancies bridging EHR integration gaps for mid-size physician groups adopting NLP-based platforms.
United Kingdom
NHS trusts in London and the Midlands pilot autonomous coding for secondary care encounters to reduce administrative burden on clinical staff. NHS England's digitization mandates accelerate procurement of cloud-based documentation tools. The Cambridge-Oxford corridor attracts health AI startups specializing in specialty-tuned language models for surgical coding.
Canada
Provincial health authorities in Ontario and British Columbia evaluate AI coding to address chronic health information management workforce gaps. Health Canada exercises oversight when coding software functions as software-as-a-medical-device components. Toronto's hospital network serves as a testbed for multilingual NLP handling procedural variations across English and French documentation.
Australia
Public hospital systems in New South Wales and Victoria deploy automated coding to compress documentation-to-bill cycles under activity-based funding models. The Therapeutic Goods Administration regulates AI-enabled clinical software under medical device frameworks. Melbourne's digital health precinct concentrates vendors adapting international platforms to local clinical terminology standards.
AI in Medical Coding Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment modalities and buyer segments. The market exhibits tiered concentration, with enterprise technology vendors anchoring integrated delivery network contracts while nimble startups penetrate ambulatory surgery centers and mid-size physician groups. Two strategic archetypes dominate: EHR-integrated platform providers leveraging existing data infrastructure, and autonomous language understanding specialists optimizing for specific clinical domains. Competitive intensity centers on EHR integration speed and specialty-specific model accuracy, with vendors racing to compress implementation timelines from 18 months to under 90 days.
Within the autonomous language understanding tier, Nym Health and Fathom exemplify focused specialists competing against diversified technology conglomerates. Oracle and IBM occupy positions as enterprise infrastructure anchors, leveraging cloud and Watson Health platforms respectively to secure multi-hospital contracts demanding data sovereignty compliance. AKASA represents the revenue cycle automation archetype, bridging coding functionality with broader financial operations. These three groupings—specialist language engines, enterprise cloud infrastructure, and integrated revenue cycle suites—capture distinct procurement budgets across hospital systems, billing companies, and ambulatory networks.
| Leading Market Players |
|---|
| CodaMetrix |
| Fathom |
| Nym Health |
| Oracle |
| IBM |
| AKASA |
| Aideo Technologies |
| BUDDI.AI |
| Diagnoss |
| Others |
Value Network & Pricing Analysis
HIPAA-compliant cloud infrastructure mandates gate both qualified supply and premium-tier pricing access, as vendors must demonstrate hardened data architectures before health systems commit to enterprise contracts. This regulatory threshold stratifies the vendor base into certified premium providers and uncertified economy alternatives, with pricing power accumulating to firms that preemptively invested in compliant subcontractor chains.
Pricing Analysis
The bundled-vs-unbundled service split dominates procurement decisions across hospital systems and ambulatory networks. SaaS-tiered subscription models with standardized implementation playbooks capture mid-size physician groups through group purchasing organizations, while unbundled per-encounter transactional pricing serves billing companies managing heterogeneous client portfolios. Price differentiation hinges on EHR integration depth and specialty-specific model accuracy, with premium tiers commanding advantage for real-time quality metric integration. Pricing pressure stems from buyer consolidation through regional health information exchanges, compressing margins for direct vendor relationships. Ambulatory surgery centers exhibit highest price sensitivity due to capital constraints, whereas integrated delivery networks prioritize accuracy guarantees over cost minimization.
Supply Chain Analysis
Freight cost insignificance characterizes this digital services market, as cloud-based delivery eliminates physical distribution entirely. Compute infrastructure concentrates in United States hyperscaler regions, with secondary nodes in Germany and United Kingdom serving data sovereignty requirements. Model training draws from proprietary clinical documentation datasets, open-source transformer architectures, and specialty-specific annotated corpora. Single-source vulnerability emerges from concentrated cloud provider dependency for GPU-intensive deep learning workloads. Distribution runs through direct enterprise sales for hospital systems, while billing companies access platforms via API-first integration partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, where CMS value-based care mandates continuously expand documentation automation requirements and deepen platform stickiness across health system workflows.
For Market Incumbents: Anticipate state-level scope-of-practice rulings that could reclassify automated coding as practicing medicine, triggering licensure barriers. Oracle and IBM should anchor multi-hospital contracts with on-premises data sovereignty options, while Nym Health and Fathom deepen specialty-tuned model accuracy for emergency department and surgical encounters. Vertical integration into EHR-native workflows—particularly Cerner and Epic API development—defends against pure-play displacement.
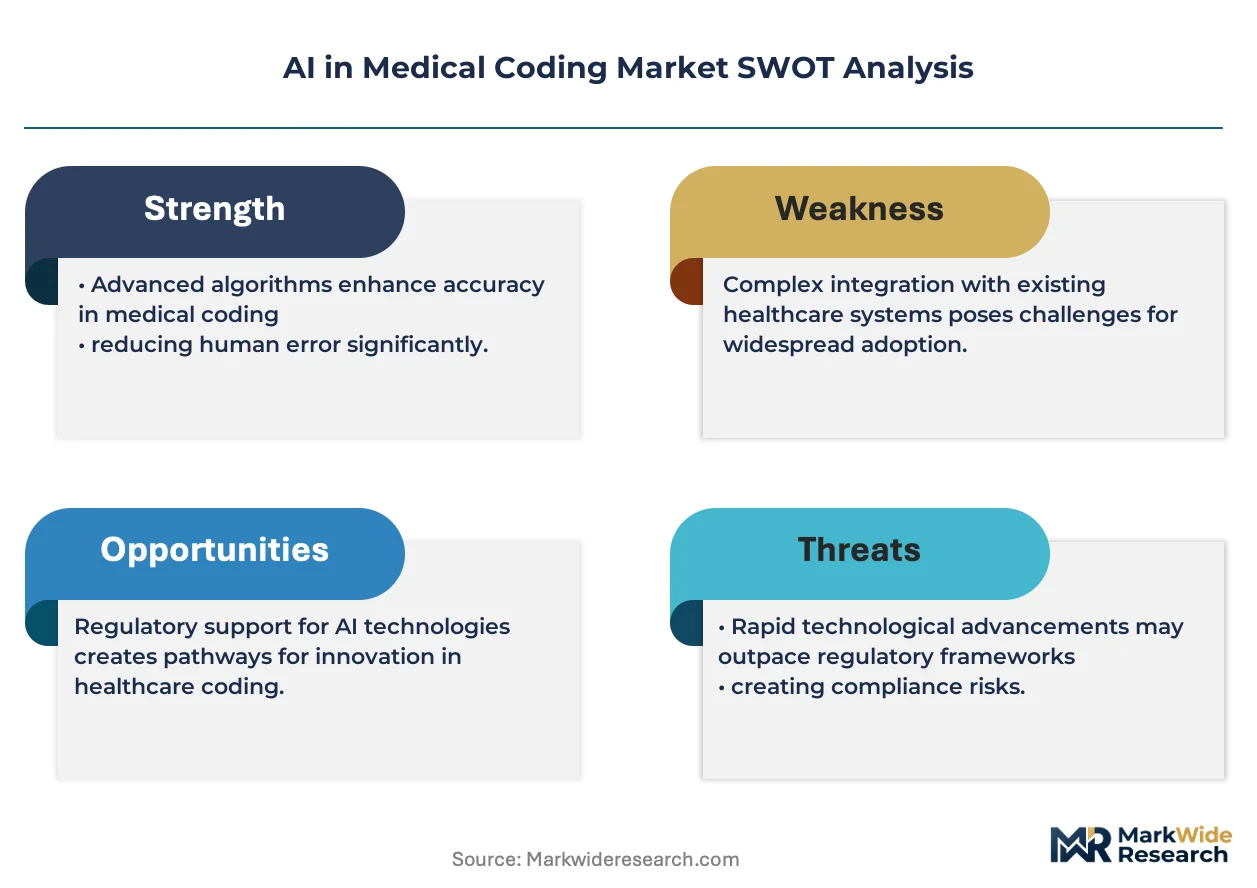
For New Entrants and Emerging Players: Group purchasing organizations represent the most penetrable channel for mid-size physician group access, as these buyers now negotiate enterprise licenses collectively rather than practice-by-practice. European outpatient networks present whitespace for multilingual natural language processing engines handling procedural coding variations across borders. A compliance-first go-to-market emphasizing FDA software-as-a-medical-device documentation accelerates hospital procurement cycles.
For Investors and Strategic Acquirers: Roll-up economics work for autonomous language understanding specialists because health system procurement increasingly demands modular, specialty-tuned models rather than monolithic platforms. The five-to-ten year viability window favors firms with demonstrated EHR integration speed and annual ICD-10-CM update retraining capabilities. The signal to watch is FDA enforcement patterns on algorithmic accountability documentation for training data demographics.
| Strategic Initiative | Industry Significance |
|---|---|
| Specialty-Tuned Model Development | Decomposes monolithic platforms into emergency medicine, cardiology, and orthopedic modules for faster CMS update cycles. |
| EHR Native Integration | Compresses implementation timelines from 18 months to under 90 days through Cerner and Epic API partnerships. |
| Hybrid Cloud Deployment | Balances billing company multi-client security protocols with cloud elasticity for compute-intensive training. |
| Real-Time Quality Metric Integration | Surfaces documentation gaps during encounters rather than retrospectively for HEDIS and Star Ratings performance. |
| Regulatory Pre-Certification Pathway | Documents training data provenance and performance disparities ahead of FDA software-as-a-medical-device scrutiny. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with health information management directors, hospital procurement committees, revenue cycle executives, and EHR integration specialists with secondary validation against CMS Medicare data, hospital procurement databases, GPO contracts, and FDA software-as-a-medical-device guidance documents. Bottom-up encounter volume modeling and top-down health system IT spending analysis triangulated market sizing across the analysis window.
Segment-weighting approaches distributed value and volume across technology layers, deployment configurations, end-user archetypes, and application functions. Natural language processing, deep learning, machine learning, and computer vision modules were modeled separately with specialty-specific adoption curves. CAGRs derived from health system automation penetration rates, certified coder attrition patterns, and value-based care contract expansion. Forecast inputs incorporated EHR vendor market share dynamics and state-level regulatory timeline uncertainties.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA enforcement evolution on algorithmic accountability and state-level scope-of-practice reclassifications. Forecasts reflect documented assumptions regarding CMS rule stability and cloud infrastructure cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Global Medical Transcription Software Market
Medical Information Systems
Global Clinical Documentation Improvement Market
Medical Information Systems
Donor Management Software Market
Medical Information Systems
Middle East Secure Messaging in Healthcare Market
Medical Information Systems
US Healthcare ERP Market
Medical Information Systems
Medical Simulation Software Market
Medical Information Systems
Global Medical Decision Support Systems for Sepsis Market
Medical Information Systems
Mobile Medical Apps Market
Medical Information Systems
Global Cardiovascular Information System Market
Medical Information Systems
Critical Care Information Systems Market
Medical Information Systems
Healthcare Information Software Market
Medical Information Systems
US Medical Coding Market
Medical Information Systems
Medical 3D Software Market
Medical Information Systems
Global Medical Scheduling Software Market
Medical Information Systems
OBGYN EHR Market
Medical Information Systems
Urology EMR Software Market