
 Tool Tethering Market | 2026-2036
Tool Tethering Market Size, Share, and Industry Trends Forecast 2026-2036
Tool Tethering Market Intelligence
Modular tethered tool kits is repositioning buyer choice away from standalone lanyard purchases toward integrated fall-protection bundles. Ergodyne leverages its channel control across industrial distributors to anchor kit penetration in construction and utilities. Stanley Black & Decker competes through manufacturing scale that sustains cost positioning across premium and standard tiers. 3M differentiates via technology leadership in retractable reel mechanisms that extend product lifecycle in aerospace maintenance environments.
Tool tethering comprises engineered lanyards, retractors, and attachment points designed to arrest free-falling hand tools above two pounds, typically rated to withstand impact forces exceeding 80 pounds with energy-absorbing webbing or coiled cord construction. Its primary industrial purpose is eliminating dropped-object hazards that cause fatalities, equipment damage, and operational shutdowns in elevated work zones. Tethered tool kits command the largest margin pool as bundled configurations reduce procurement friction for safety managers, while retractable reels represent the fastest-growing technology segment due to ergonomic advantages in repetitive-access tasks. Construction sites dominate application volume, though aerospace maintenance generates premium pricing through certification-grade material requirements.
OSHA dropped-object standards and FAA maintenance safety directives shape product specifications by mandating tool arrestment in elevated work environments, driving replacement cycles and compliance audits. ISO 1983 and ANSI/ISEA 121-2018 establish test protocols for tether strength and gate-closure integrity that determine market access for imported equipment. Stakeholders must monitor regulatory harmonization between North American and European certification regimes as export-dependent manufacturers face diverging conformity assessment requirements.
Market Dynamics
OSHA dropped-object enforcement is compressing replacement cycles as construction crews face crew-level procurement mandates tied to federal inspection protocols, forcing distributors to stock modular tethered kits rather than standalone lanyards.
Growth Catalysts
- ANSI/ISEA 121-2018 adoption:The standard's gate-closure integrity requirements are accelerating equipment turnover at US construction sites as safety managers conduct compliance audits ahead of OSHA inspections.
- Wind turbine maintenance expansion:Technicians working at 80-meter hub heights in Texas and Iowa are driving tethered tool kit volume as independent service providers standardize fall-protection protocols.
- Coiled cord retractor technology:Energy-absorbing webbing rated above 80 pounds is displacing basic lanyards in aerospace maintenance hangars where repetitive tool access demands ergonomic solutions.
Market Restraints
- Petrochemical input volatility:Nylon and polyester webbing costs fluctuate with crude oil derivatives, compressing margin pools for standard-tier manufacturers without backward integration into synthetic fiber production.
- Import certification friction:Diverging conformity assessment between US ANSI protocols and European CE marking regimes creates inventory segmentation costs for Asia-Pacific manufacturers serving dual markets.
- Mechanical substitution risk:Magnetic tool holders and vacuum-assisted retrieval systems are capturing share in controlled-environment manufacturing where dropped-object hazards remain minimal.
Strategic Opportunities
- India infrastructure buildout:The country's national construction safety regulator is drafting elevated-work mandates modeled on OSHA frameworks, opening first-mover positioning for kit suppliers before local manufacturing scales.
- Drone-assisted tether deployment:Convergence of retractable reel mechanisms with unmanned aerial systems is enabling pre-positioned tool stations at remote transmission tower sites.
- Utility cooperative procurement platforms:Rural electric cooperatives in the Midwest are consolidating safety equipment purchasing through shared-service organizations, creating direct-to-crew distribution channels outside industrial distributors.
Industry Challenges
- FAA maintenance directive compliance timelines:Aerospace MRO facilities face 90-day certification windows for new tether equipment, compressing vendor qualification cycles and straining quality assurance bandwidth.
- Legacy tool inventory retrofit complexity:Attachment point drilling and welding on existing wrenches and drivers requires specialized technician training that general safety managers lack, slowing kit penetration at mid-sized contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tool Tethering Market |
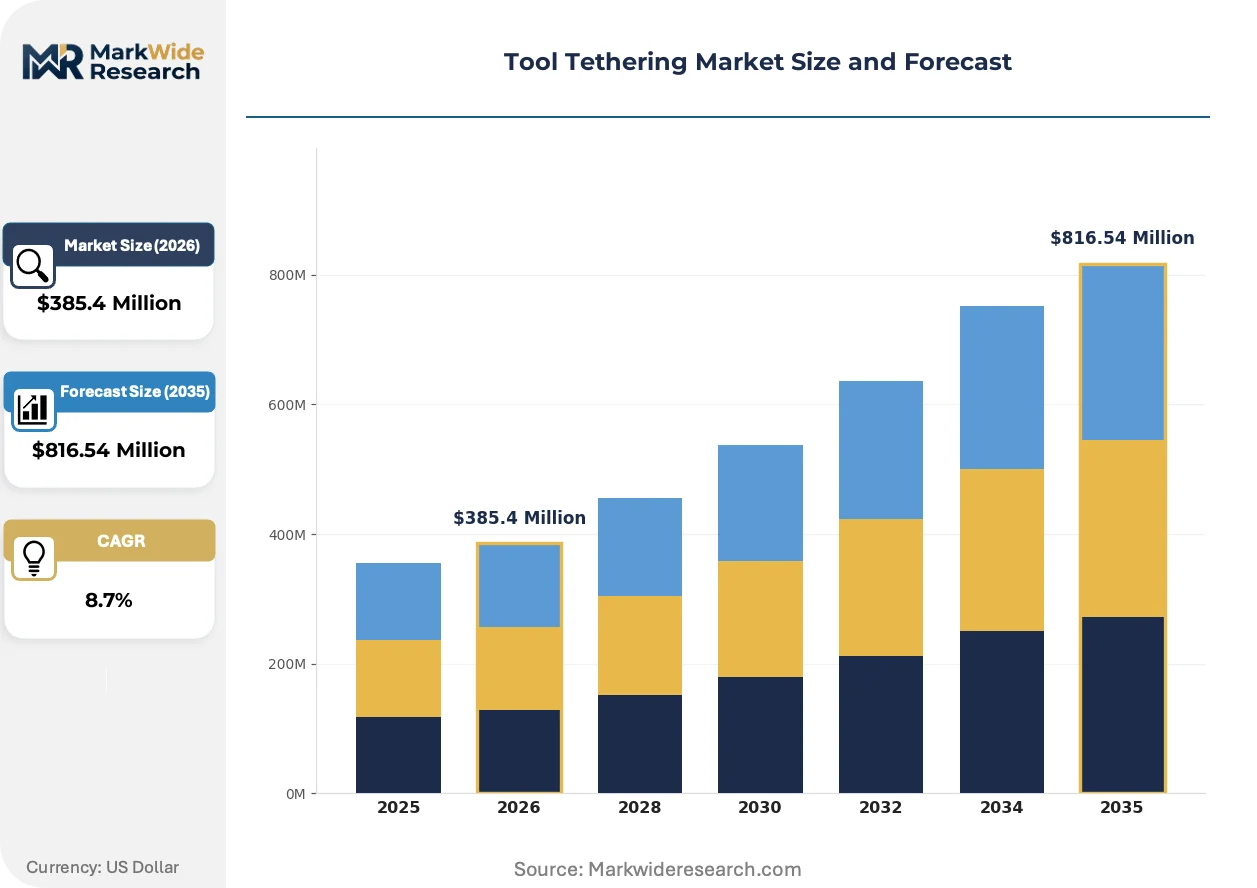
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retraction Lanyards, Tool Retractors, Tethered Tool Kits, Safety Tethering Straps, Magnetic Holders Technology: Retractable Reels, Elastic Tethers, Coiled Cords, Magnetic Attachments, Snap Hooks Application: Construction Sites, Aerospace Maintenance, Telecommunications, Oilfield Services, Shipbuilding End User: Industrial Technicians, Field Engineers, Maintenance Crews, Safety Managers, Inspection Specialists |
| Companies Covered | Ergodyne, Stanley Black & Decker, 3M, Buckingham Manufacturing, FallTech, Honeywell International, Milwaukee Tool, NLG GmbH, MSA Safety, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tool Tethering Market Strategic Shifts & Innovations
Retractable reel mechanisms are compressing the ergonomic gap between fall protection and productivity, reshaping how maintenance crews balance safety compliance with task speed in elevated environments.
Self-retracting lanyard systems with integrated energy absorption are expanding into wind turbine service operations where technicians cycle tools hundreds of times per shift. OEM service divisions at Vestas and Siemens Gamesa are specifying these mechanisms in blade inspection contracts. The technology is expanding into rental fleet configurations as equipment lessors recognize lifecycle advantages over traditional coil tethers.
OSHA's National Emphasis Program on dropped objects is triggering inspection waves across Texas and Florida construction zones. General contractors are responding by mandating third-party tether audits before crane lifts commence. Specialty trade subcontractors in commercial high-rise development face the steepest compliance penalties, driving emergency kit procurement through industrial distributors with same-day fulfillment capabilities.
Integrated procurement platforms are consolidating safety manager workflows as construction firms migrate from purchase-order-based buying to subscription replenishment models. Industrial distributors including Grainger and Fastenal are deploying vendor-managed inventory systems that auto-replenish consumable tethers based on crew headcount. The shift is most visible among top-50 ENR contractors with multi-state project portfolios where standardization reduces site-level procurement friction.
Tool Tethering Market Segmentation
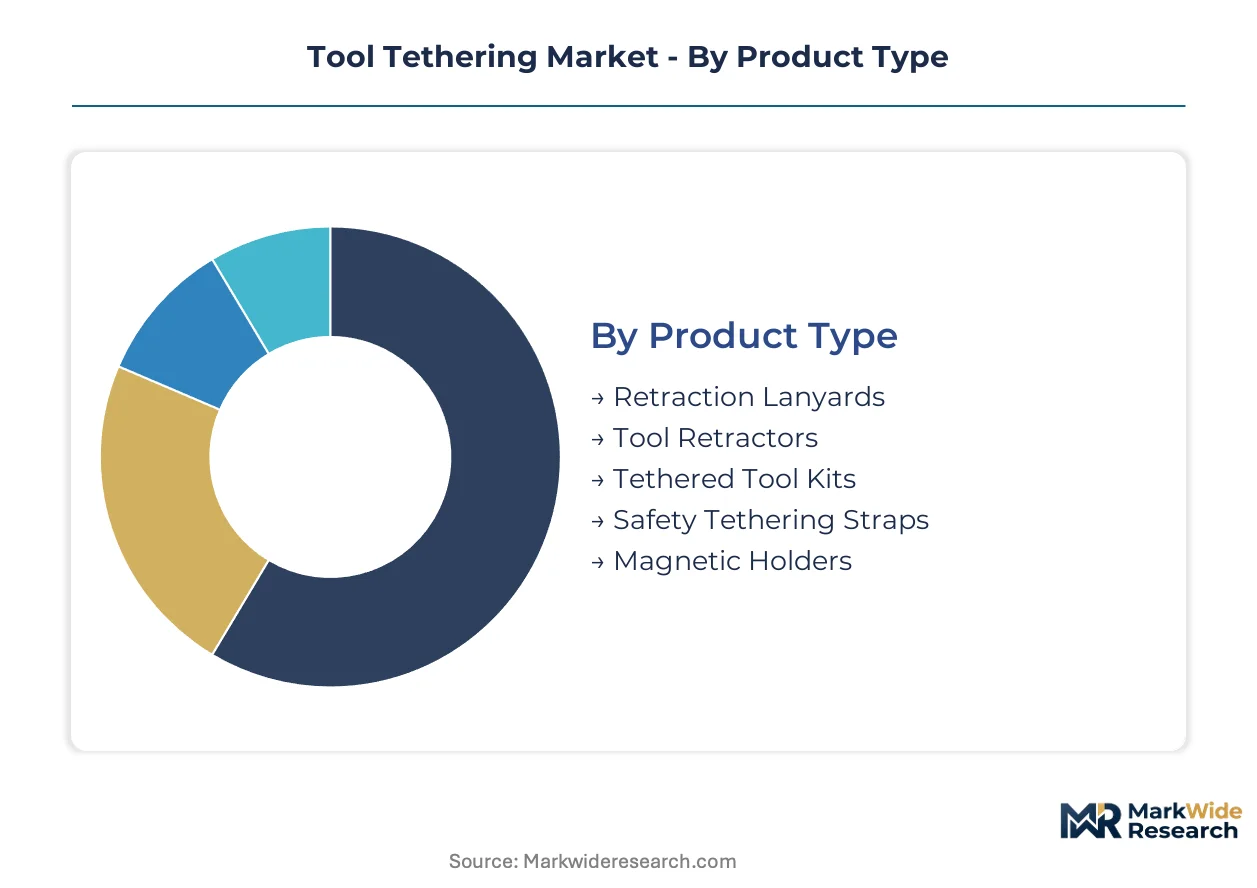
Tool tethering equipment fragments across four structural axes that determine procurement patterns and margin capture. Product architecture and attachment mechanisms shape compliance viability, while end-user workflow requirements dictate bundling logic and channel access.
Product Type:
Retraction mechanisms and kit configurations anchor the commercial landscape, with standalone components serving retrofit demand.
- Retraction Lanyards:Self-coiling webbing systems rated above 80 pounds impact force dominate wind turbine blade inspection contracts. Technicians at Vestas and Siemens Gamesa service divisions specify these for 80-meter hub height operations where repetitive tool cycling demands ergonomic compliance.
- Tethered Tool Kits:Bundled configurations integrating attachment points, lanyards, and carrying cases command the largest margin pool. Grainger and Fastenal auto-replenishment programs concentrate procurement among top-50 ENR contractors with multi-state portfolios.
- Tool Retractors:Spring-loaded mechanisms with 6-10 foot reach enable single-handed tool access in aerospace maintenance hangars.
- Safety Tethering Straps:Basic webbing solutions serve price-sensitive retrofit demand at mid-sized construction contractors.
- Magnetic Holders:Rare-earth attachment systems capture controlled-environment manufacturing where ferrous tool inventories predominate.
Tethered tool kits lead on scale; retraction lanyards lead on momentum.
Technology:
Energy absorption and deployment speed separate premium mechanisms from commodity tethering.
- Retractable Reels:Integrated braking systems with 48-inch-per-second maximum descent velocity meet ANSI/ISEA 121-2018 energy absorption protocols. These mechanisms expand most quickly into rental fleet configurations as equipment lessors recognize lifecycle advantages over coil tethers.
- Coiled Cords:Polyurethane-sheathed steel cables rated for 100,000 extension cycles displace basic lanyards in FAA-regulated aerospace MRO facilities. The 90-day certification windows for new tether equipment compress vendor qualification cycles.
- Elastic Tethers:Bungee-construction webbing serves temporary elevated work platforms with lower duty-cycle requirements.
- Magnetic Attachments:Neodymium-based systems with 50-pound breakaway ratings address non-ferrous tool limitations in petrochemical maintenance.
- Snap Hooks:Gate-closure mechanisms with double-action release prevent inadvertent disconnection in construction crane lift zones.
Coiled cords lead on scale; retractable reels lead on momentum.
Application:
Height exposure and regulatory intensity concentrate demand in infrastructure maintenance and vertical construction.
- Construction Sites:OSHA National Emphasis Program inspection waves across Texas and Florida drive crew-level procurement mandates. General contractors now require third-party tether audits before crane lifts commence.
- Aerospace Maintenance:FAA maintenance safety directives mandate tool arrestment in elevated hangar environments. Certification-grade material requirements generate premium pricing through specialized distributors.
- Wind Turbine Maintenance:Independent service providers in Iowa and Texas standardize fall-protection protocols for 80-meter hub height operations.
- Oilfield Services:Platform rigging crews face dropped-object hazards in North Sea and Gulf of Mexico offshore installations.
- Shipbuilding:Confined-space elevated work in Korean and Japanese yards drives retractable reel adoption for hull assembly operations.
Construction sites lead on scale; wind turbine maintenance leads on momentum.
End User:
Safety manager authority versus technician autonomy determines kit specification versus component purchasing.
- Safety Managers:Corporate-level procurement authority at ENR top-50 contractors drives standardized kit deployment across multi-state project portfolios. Subscription replenishment models reduce site-level friction.
- Industrial Technicians:Direct specification influence in wind turbine and aerospace maintenance operations shapes retractable reel preferences based on repetitive-access ergonomics.
- Field Engineers:Utility cooperative procurement platforms in the Midwest consolidate purchasing through shared-service organizations.
- Maintenance Crews:Rural electric cooperative members access direct-to-crew distribution channels outside industrial distributor networks.
- Inspection Specialists:Third-party compliance auditors specify equipment for pre-lift certification in OSHA-inspected construction zones.
Safety managers lead on scale; industrial technicians lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tool tethering originated in North American construction safety protocols during the 1990s, with OSHA enforcement frameworks establishing the first systematic dropped-object prevention standards. The industry's geographic footprint now extends across industrialized economies with elevated-work regulatory regimes.
United States
Infrastructure investment and commercial high-rise development drive crew-level procurement across Texas and Florida construction zones. OSHA's National Emphasis Program on dropped objects triggers inspection waves that force emergency kit purchases through industrial distributors. Houston and Miami metropolitan areas concentrate demand among specialty trade subcontractors facing steep compliance penalties.
Germany
Wind turbine manufacturing and offshore platform rigging create dual demand channels for certified tether systems. CE marking requirements under EU machinery directives shape product specifications for export-oriented fabricators. The North Sea port cluster around Hamburg and Bremerhaven anchors procurement for platform maintenance crews.
China
Shipbuilding yards in the Yangtze River Delta and Pearl River Delta drive retractable reel adoption for hull assembly operations. GB standards for fall protection equipment establish domestic certification protocols that diverge from ANSI frameworks. Shanghai and Guangzhou municipal construction regulators are drafting elevated-work mandates for commercial tower projects.
India
National infrastructure buildout and metro rail expansion generate first-mover positioning opportunities before local manufacturing scales. The national construction safety regulator is drafting elevated-work mandates modeled on OSHA frameworks. Mumbai and Delhi-NCR construction corridors concentrate demand among mid-sized contractors retrofitting legacy tool inventories.
United Arab Emirates
Mega-project construction and port logistics operations create premium-tier demand for certified tether systems. Dubai's building safety code mandates tool arrestment for work above six meters on commercial tower sites. The Jebel Ali industrial zone concentrates procurement among oilfield services contractors serving offshore Arabian Gulf installations.
Tool Tethering Market Key Industry Players
The competitive structure tilts toward diversified safety equipment conglomerates with channel control across industrial distributors. Mid-sized specialists occupy niche positions in retractable reel technology and aerospace-certified materials. Three archetypes dominate: integrated fall-protection conglomerates with construction-sector scale, component specialists with manufacturing backward integration into synthetic fiber production, and regional fabricators serving localized certification regimes. M&A activity concentrates on retractable reel technology acquisitions, while capacity expansion focuses on coiled cord manufacturing for wind turbine service contracts.
Among North American-based safety equipment suppliers, Ergodyne and FallTech exemplify channel-anchored positioning through industrial distributor relationships. NLG GmbH represents European specialist archetypes with certification-grade manufacturing for offshore and aerospace applications. Stanley Black & Decker occupies the diversified conglomerate tier, leveraging manufacturing scale across premium and standard equipment tiers. These three anchors illustrate how competitive positioning fragments across channel control, specialization depth, and manufacturing breadth.
| Leading Market Players |
|---|
| Ergodyne |
| Stanley Black & Decker |
| 3M |
| Buckingham Manufacturing |
| FallTech |
| Honeywell International |
| Milwaukee Tool |
| NLG GmbH |
| MSA Safety |
| Others |
Cost & Logistics Intelligence
Certification-grade aerospace tethering diverges sharply from construction-site commodity kits, with ANSI/ISEA 121-2018 compliance and FAA maintenance directives creating a pricing ladder that maps directly onto synthetic fiber sourcing depth and distributor channel control. Premium retractable reels command position through neodymium attachment engineering and energy-absorbing webbing rated above 80 pounds, while standard-tier manufacturers absorb petrochemical input volatility through nylon and polyester spot-market exposure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels anchors the market, with certification grade and volume scale as the primary price differentiation drivers. Cost compression in standard-tier webbing is intensifying because crude oil derivative volatility feeds directly into nylon and polyester input costs without backward integration buffers. Safety managers at ENR top-50 contractors show least price sensitivity due to subscription replenishment models, while mid-sized retrofit contractors exhibit highest sensitivity to per-unit lanyard costs.
Supply Chain Analysis
Direct-to-crew distribution through utility cooperative procurement platforms and industrial distributor networks handles multi-state contractor demand, while specialized aerospace channels serve FAA-regulated MRO facilities. Manufacturing concentrates in the United States for ANSI-certified construction equipment, Germany for CE-marked offshore systems, and China for shipbuilding retractable reels. Supply chains rest on synthetic fiber webbing, rare-earth magnetic components, and spring-loaded retraction mechanisms. Single-source vulnerability in neodymium sourcing from China creates structural risk for magnetic attachment suppliers. Distribution runs through Grainger and Fastenal auto-replenishment programs for construction, with specialized distributors capturing aerospace premium tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA's National Emphasis Program on dropped objects functions as a regulatory compounder, with inspection waves across Texas and Florida construction zones converting compliance mandates into sustained replacement-cycle demand.
For Market Incumbents: Cement channel control through vendor-managed inventory systems that auto-replenish consumable tethers based on crew headcount, defending against industrial distributor disintermediation. Deepen backward integration into synthetic fiber production to absorb petrochemical input volatility that compresses margin pools for standard-tier competitors lacking captive supply.
For New Entrants and Emerging Players: Begin with India's national infrastructure buildout before local manufacturing scales, targeting Mumbai and Delhi-NCR construction corridors where mid-sized contractors retrofit legacy tool inventories. Pursue drone-assisted tether deployment convergence as a go-to-market angle for remote transmission tower sites in Texas and Iowa wind corridors.
For Investors and Strategic Acquirers: Consolidation pressure builds where retractable reel technology acquisitions concentrate M&A activity and coiled cord manufacturing capacity expansion targets wind turbine service contracts. Long-term viability favors component specialists with certification-grade manufacturing depth over undifferentiated webbing fabricators. Watch FAA maintenance directive compliance timelines as the inflection signal, with 90-day certification windows compressing vendor qualification cycles and straining quality assurance bandwidth at aerospace MRO facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Retractable Reel Technology Acquisition | Captures ergonomic advantages in Vestas and Siemens Gamesa blade inspection contracts. |
| Coiled Cord Manufacturing Scale-Up | Addresses 100,000-cycle durability requirements in FAA-regulated aerospace MRO hangars. |
| Vendor-Managed Inventory Deployment | Locks ENR top-50 contractors into subscription replenishment models through Grainger and Fastenal. |
| India First-Mover Positioning | Establishes kit supplier presence before national construction safety regulator mandates elevate local manufacturing. |
| Drone-Assisted Tether Integration | Enables pre-positioned tool stations at 80-meter hub height wind turbine sites in Texas and Iowa. |
Research Approach
Coverage spans the United States, Germany, China, India, and the United Arab Emirates, with primary inputs from each market combining interviews with safety managers at ENR top-50 contractors, wind turbine service technicians at Vestas and Siemens Gamesa, aerospace MRO procurement leads, industrial distributor category managers, and construction site foremen. Secondary validation draws from OSHA enforcement records, FAA maintenance safety directives, ANSI/ISEA 121-2018 test protocols, EU machinery directive CE marking requirements, and customs trade data on synthetic fiber imports. Bottom-up crew-level procurement estimates triangulate against top-down infrastructure investment flows.
Rate-of-change decomposition separates volume expansion from price-mix effects across the analysis window, with segmentation dimensions including retraction mechanism type, certification grade tier, end-use application, and buyer archetype. CAGRs derive from regression against OSHA inspection frequency, wind turbine installed base growth, and commercial high-rise construction permits. Industry-specific forecast inputs incorporate petrochemical price indices for nylon and polyester webbing, and FAA maintenance directive compliance timeline compression.
Several conditions sit outside the modeled scope, including magnetic tool holder substitution rates in controlled-environment manufacturing and vacuum-assisted retrieval system adoption curves. Forecasts reflect assumptions about regulatory harmonization between North American and European certification regimes. Periodic stress-testing of base assumptions is recommended given diverging conformity assessment requirements for Asia-Pacific manufacturers serving dual markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Hospital Logistics Robots Market
Robotics and Automation
Surgical Robots Market
Robotics and Automation
Robot Controller, Integrator and Software Market
Robotics and Automation
Drone-Based NDT Inspection Systems for Energy and Infrastructure Assets Market
Robotics and Automation
Metal Fabrication Robots Market
Robotics and Automation
Bionic Glove's Market
Robotics and Automation
Global Automotive Gesture Recognition System Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Technology Market
Robotics and Automation
Delta Robotics Market
Robotics and Automation
Cybersecurity in Robotics Market
Robotics and Automation
Global Molecular Robotics Market
Robotics and Automation
Healthcare Assistive Robot Market
Robotics and Automation
Long-Range Drone Package Delivery Market
Robotics and Automation
Mobile Stabilizer Market
Robotics and Automation
Global Mobile Robots Market
Robotics and Automation
Smart Exoskeleton Market