
 Robot Pedestal Market | 2026-2036
Robot Pedestal Market Size, Share, and Industry Trends Forecast 2026-2036
Robot Pedestal Market Analytics
Modular pedestal configurations that bundle adjustable height platforms with quick-change tooling interfaces are repositioning how manufacturing buyers evaluate total system cost. FANUC leverages its captive servo motor production to control pedestal-drive integration costs across its installed base. ABB anchors its pedestal offerings to its OmniCore controller architecture, sustaining software-defined motion profiles as a differentiation layer. KUKA competes through its AGILUS series integration, where compact pedestals occupy high-density automotive body shop layouts.
A robot pedestal is a rigid structural base, typically fabricated from welded steel or extruded aluminum with precision-machined mounting surfaces, that provides stable elevation, vibration damping, and positional accuracy for industrial robotic arms in repetitive manufacturing environments. The platform typically incorporates electromechanical lift mechanisms or fixed-height columns rated for dynamic payload capacities exceeding the robot's maximum reach torque. Fixed pedestals dominate current installed value due to their lower capital outlay and established maintenance protocols in legacy automotive lines. Mobile pedestals represent the fastest-expanding category, as logistics centers and contract manufacturers prioritize fleet reconfigurability over permanent infrastructure. Composite material adoption remains nascent but carries margin concentration in cleanroom and food-handling applications where aluminum corrosion resistance falls short.
ISO 10218 safety standards for industrial robots, the EU Machinery Directive's stability requirements for fixed installations, and OSHA's general duty clauses for workplace robotics are collectively elevating pedestal design verification burdens. These frameworks compel manufacturers to document fatigue-load testing and tip-over resistance calculations before market access, particularly for collaborative robot deployments in shared human-machine workspaces. Stakeholders must monitor how emerging national building codes classify permanently anchored robot pedestals versus mobile platforms, as this distinction triggers divergent permitting, inspection, and insurance cost structures.
Market Dynamics
The EU Machinery Directive's stability requirements for fixed installations are forcing pedestal manufacturers to re-engineer structural designs around fatigue-load documentation and tip-over resistance calculations, particularly for collaborative robot deployments in shared human-machine workspaces.
Growth Catalysts
- ISO 10218 safety standards:The updated industrial robot safety framework mandates enhanced pedestal anchoring and vibration damping for collaborative applications, creating specification pull from automotive OEMs in Germany.
- Automotive assembly line expansion:Welding and material handling operations are driving specification of robot-mounted pedestal systems with quick-change tooling interfaces in flexible manufacturing cells.
- Mobile platform adoption:Logistics centers and contract manufacturers are prioritizing fleet reconfigurability over permanent infrastructure, accelerating demand for electromechanically actuated height-adjustable pedestals.
Market Restraints
- Steel and aluminum input volatility:Welded steel fabrication and precision-machined aluminum extrusions face commodity price swings that compress margin on fixed-height column production.
- Supply concentration in precision-machined mounting surfaces:German and Japanese machine tool suppliers control high-tolerance finishing capacity for dynamic payload-rated platforms.
- Regulatory fragmentation:Divergent national building code classifications for permanently anchored versus mobile platforms trigger inconsistent permitting and insurance cost structures across jurisdictions.
Strategic Opportunities
- Cleanroom and food-handling verticals:Composite material adoption carries margin concentration where aluminum corrosion resistance falls short, opening specification channels in pharmaceutical and packaged goods processing.
- OSHA general duty clause enforcement:Workplace robotics safety inspections are elevating documented design verification requirements, favoring suppliers with pre-certified fatigue-load testing protocols.
- Convergence of AGV fleet management with pedestal-mounted robotics:Integration of mobile pedestals with automated guided vehicle navigation systems enables dynamic workcell repositioning in high-mix contract manufacturing.
Industry Challenges
- Controls integration expertise scarcity:Software-defined motion profile implementation requires rare cross-functional competence spanning mechanical engineering and real-time controller architecture.
- Legacy line retrofit complexity:Established automotive body shops face downtime penalties when replacing fixed pedestals with height-adjustable alternatives in running production environments.
- Collaborative robot certification timelines:ISO/TS 15066 compliance documentation for human-robot collaborative pedestals extends product development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robot Pedestal Market |
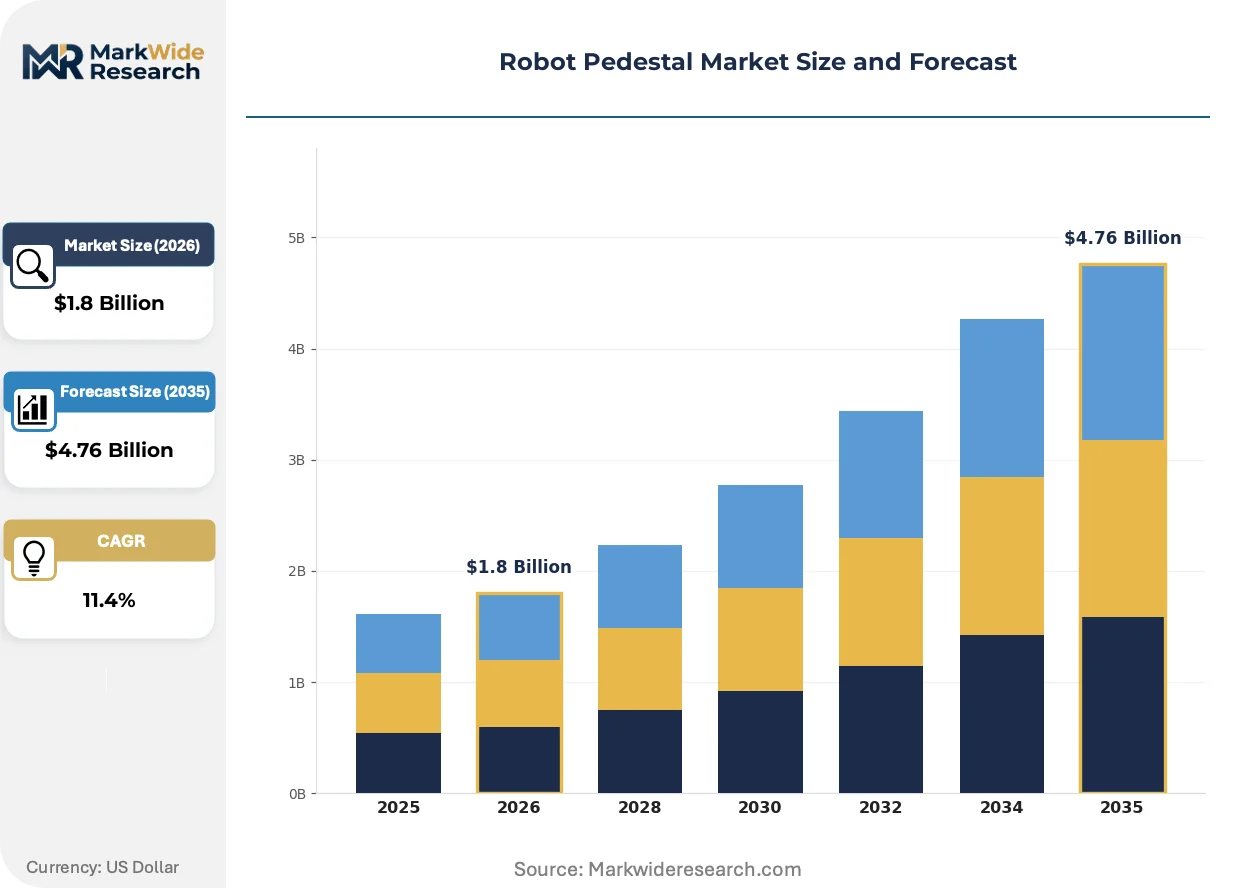
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Pedestals, Mobile Pedestals, Adjustable Pedestals, Collapsible Pedestals End User: Manufacturing Plants, Logistics Centers, Retail Stores, Educational Institutions Material: Steel, Aluminum, Plastic, Composite Technology: Electromechanical, Hydraulic, Pneumatic, Others |
| Companies Covered | FANUC, ABB, KUKA, Yaskawa, Universal Robots, Robotiq, Doosan Robotics, Staubli Robotics, Schunk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robot Pedestal Market Evolving Landscape
Electromechanical lift mechanisms and composite material formulations are actively displacing legacy fixed-height steel columns, while regulatory documentation requirements are reshaping supplier competitive positioning around pre-certified design packages.
Carbon-fiber-reinforced polymer pedestal construction is absorbing vibration damping requirements previously addressed through massive steel castings. Medical device manufacturers and semiconductor fabs are specifying these platforms for cleanroom installations where electromagnetic interference and particulate shedding must be minimized. The material transition is absorbing margin from traditional metal fabrication while enabling premium positioning in contamination-sensitive end-uses.
The EU Machinery Directive's 2023 update to stability requirements for fixed installations mandates documented tip-over resistance calculations before market access. German notified bodies are enforcing this through enhanced conformity assessment procedures, compelling non-EU suppliers to establish EU-based technical file repositories. Collaborative robot deployments in shared workspaces face the steepest compliance burden, with integrators now requiring pedestal suppliers to provide finite element analysis packages as standard deliverables.
Specification authority is migrating from plant engineering departments to central procurement functions with enterprise-level fleet standardization mandates. Automotive OEMs are consolidating supplier relationships around full-system integrators who bundle pedestal, robot, and controller procurement, displacing the historical pattern of component-level sourcing. This concentration is most visible in Germany, where BMW, Mercedes-Benz, and Volkswagen Group have implemented preferred supplier programs for flexible manufacturing cell infrastructure.
Robot Pedestal Market Segmentation
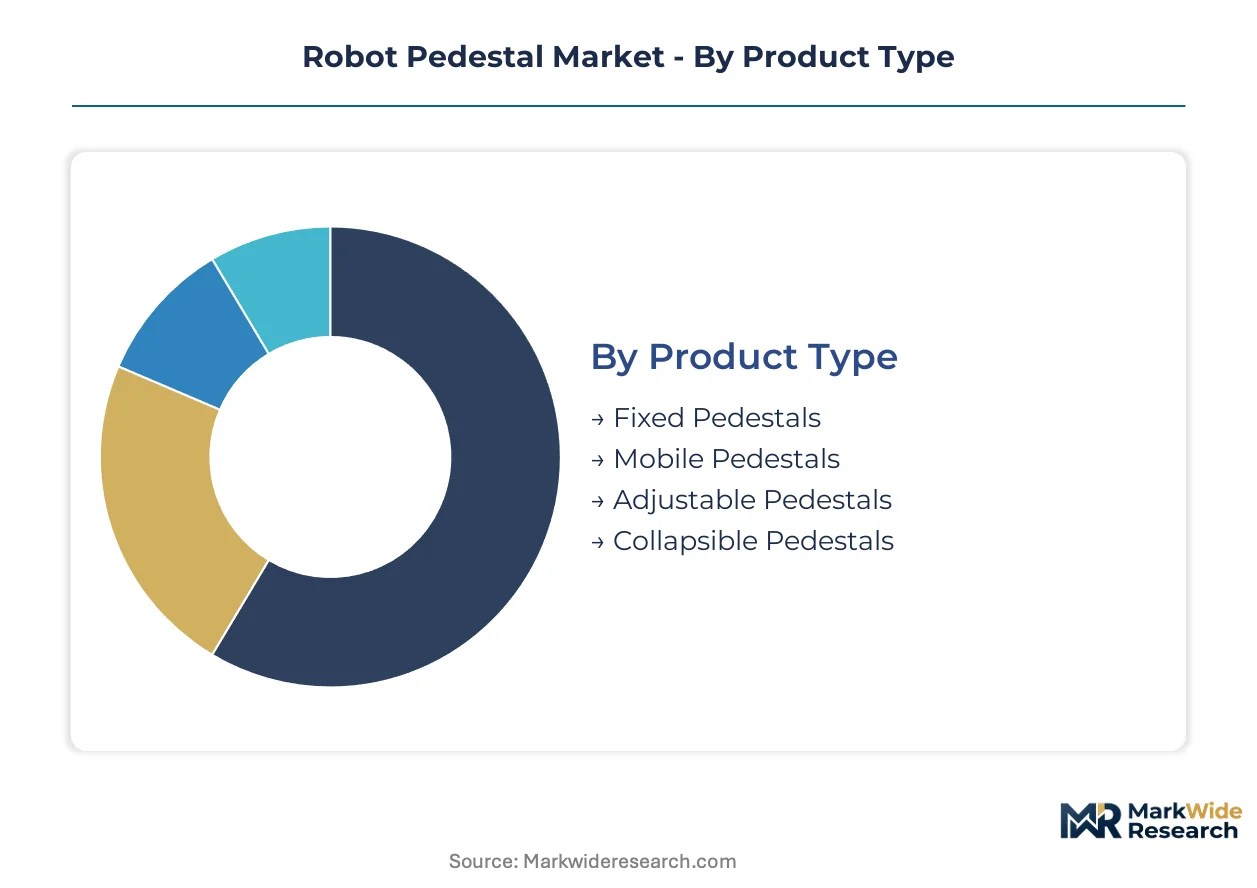
Pedestal configuration choices directly determine compliance pathways under ISO 10218 and the EU Machinery Directive. Buyers segment procurement decisions across mobility, material, and actuation technology to match specific welding, material handling, or collaborative robot deployments.
Product Type:
Certification burden varies sharply: fixed installations trigger EU Machinery Directive stability documentation and tip-over resistance calculations, while mobile platforms face divergent national building code classifications and fleet insurance protocols.
- Fixed Pedestals:Rigid welded steel or aluminum columns with precision-machined mounting surfaces rated for dynamic payload capacities exceeding robot reach torque. Automotive assembly lines in Germany specify these for legacy body shop welding operations where permanent anchoring satisfies ISO 10218 vibration damping mandates.
- Mobile Pedestals:Electromechanically actuated height-adjustable platforms with quick-change tooling interfaces enabling fleet reconfigurability. Logistics centers and contract manufacturers prioritize these for high-mix manufacturing cells where workcell repositioning outweighs infrastructure permanence.
- Adjustable Pedestals:Electromechanical lift mechanisms accommodating variable robot reach requirements across multiple product generations.
- Collapsible Pedestals:Compact transport configurations for temporary installations and educational demonstration environments.
Fixed Pedestals sits at the top of the volume ranking, with Mobile Pedestals climbing the fastest.
End User:
Procurement authority concentrates differently across customer types: automotive OEMs centralize through full-system integrators, while logistics operators emphasize fleet standardization mandates.
- Manufacturing Plants:Automotive body shops and flexible manufacturing cells demanding fatigue-load documentation and finite element analysis packages as standard deliverables under EU notified body enforcement.
- Logistics Centers:E-commerce fulfillment and warehouse automation operators specifying mobile pedestal fleets with AGV navigation integration for dynamic workcell repositioning.
- Retail Stores:Inventory management and customer service robot deployments with lower payload requirements and reduced stability documentation burdens.
- Educational Institutions:Vocational training and research laboratories prioritizing collapsible configurations and reduced capital outlay over industrial-grade certification.
Manufacturing Plants command the highest specification density, with Logistics Centers expanding most quickly.
Material:
Material selection governs corrosion resistance, electromagnetic interference, and cleanroom compatibility — critical for pharmaceutical and semiconductor end-uses where aluminum falls short.
- Steel:Welded fabrication with massive castings for vibration damping in heavy-duty automotive welding operations. Commodity price volatility compresses margin on fixed-height column production.
- Aluminum:Extruded profiles with precision-machined mounting surfaces for moderate payload applications where weight reduction enables faster robot acceleration profiles.
- Plastic:Lower-cost alternatives for light-payload collaborative robot deployments in retail and educational settings with minimal regulatory documentation requirements.
- Composite:Carbon-fiber-reinforced polymer construction absorbing vibration damping requirements while minimizing electromagnetic interference and particulate shedding in medical device and semiconductor cleanroom installations.
Steel retains dominant volume position, with Composite gaining share fastest in contamination-sensitive verticals.
Technology:
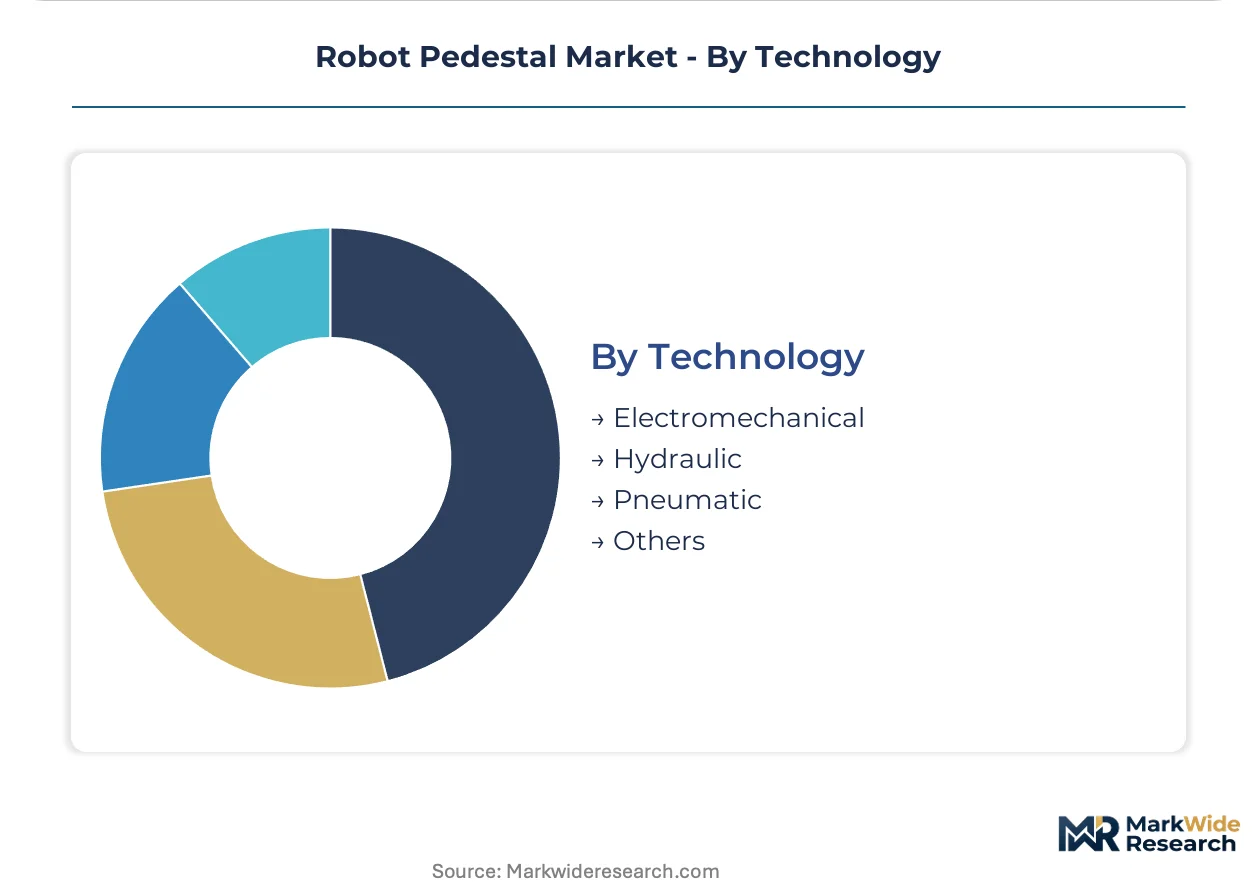
Actuation technology determines height adjustment precision, maintenance protocols, and integration complexity with software-defined motion profiles.
- Electromechanical:Servo motor-driven lift mechanisms with captive production integration controlling pedestal-drive costs. FANUC leverages in-house servo manufacturing for this configuration.
- Hydraulic:High-force actuation for extreme payload ratings in heavy industrial welding and material handling operations.
- Pneumatic:Cost-effective positioning for lighter collaborative robot deployments with reduced precision requirements.
- Others:Emerging magnetic and linear motor configurations for specialized cleanroom and high-speed positioning applications.
Electromechanical holds the volume lead, with integrated servo-drive variants expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial robot integration in automotive manufacturing during the 1970s, establishing the technical foundations for pedestal-mounted systems now deployed worldwide. Japanese and US manufacturers subsequently developed competing standards, creating today's tri-polar supply geography.
United States
OSHA enforcement of general duty clauses for workplace robotics is elevating documented design verification requirements for pedestal installations. The Department of Labor's regional offices in Michigan and Ohio coordinate inspection protocols specifically targeting automotive body shop robot stability. Detroit-Warren-Dearborn metro anchors North American demand, where Ford and General Motors consolidate flexible manufacturing cell procurement around full-system integrators.
Germany
EU Machinery Directive stability requirements and ISO 10218 safety standards mandate fatigue-load documentation and tip-over resistance calculations before market access. KBA enforcement through German notified bodies compels non-EU suppliers to establish EU-based technical file repositories. Stuttgart and Munich industrial corridors concentrate specification authority, with BMW, Mercedes-Benz, and Volkswagen Group implementing preferred supplier programs for pedestal infrastructure.
Japan
METI industrial automation incentives and JIS standards for robot safety equipment shape procurement criteria for export-oriented manufacturers. The Ministry of Economy, Trade and Industry coordinates conformity assessment alignment with ISO frameworks to preserve access to European automotive OEM supply chains. Nagoya and Osaka manufacturing belts host dense clusters of precision-machined mounting surface suppliers controlling high-tolerance finishing capacity.
China
GB standards for industrial robot safety and MIIT smart manufacturing initiatives accelerate domestic pedestal production capacity expansion. SAMR market access procedures require stability documentation mirroring EU Machinery Directive structures for collaborative robot deployments. Yangtze River Delta automotive hubs in Shanghai and Jiangsu province absorb the fastest-expanding mobile pedestal volumes for logistics center fleet reconfigurability.
South Korea
MFDS alignment with ISO/TS 15066 for collaborative robot safety extends certification timelines for pedestal-mounted human-robot workspace installations. METI-equivalent industrial policy through the Ministry of Trade, Industry and Energy subsidizes electromechanical lift mechanism development for height-adjustable platforms. Busan-Ulsan manufacturing corridor concentrates shipbuilding and automotive welding applications demanding dynamic payload-rated pedestal systems.
Robot Pedestal Market Competitive Landscape
The competitive structure tilts toward diversified industrial automation conglomerates with captive controller architecture and servo motor production. Market positions stratify across three tiers: full-system integrators bundling robot-pedestal-controller procurement, component specialists supplying precision-machined mounting surfaces, and regional fabricators competing on fixed-height column capital outlay. Consolidation pressure intensifies as automotive OEM procurement centralization favors suppliers with pre-certified fatigue-load testing protocols and EU technical file repositories. Geographic expansion and strategic partnerships constitute the dominant competitive moves, with European and Asian players establishing regional conformity assessment capabilities.
Among diversified automation conglomerates, FANUC and ABB exemplify archetypes anchored to proprietary controller ecosystems, while KUKA occupies a position within the European automotive body shop integration tier. FANUC leverages in-house servo manufacturing to control pedestal-drive integration costs, representing the backward-integrated production model. ABB sustains software-defined motion profile differentiation through its OmniCore architecture, anchoring the software-centric competitive vector. KUKA competes through compact pedestal configurations optimized for high-density automotive layouts, exemplifying the application-specialized fabrication approach. These three entities collectively illustrate how captive technology control and regional conformity assessment capabilities determine specification access in consolidated procurement environments.
| Leading Market Players |
|---|
| FANUC |
| ABB |
| KUKA |
| Yaskawa |
| Universal Robots |
| Robotiq |
| Doosan Robotics |
| Staubli Robotics |
| Schunk |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap German fabricators anchor welded steel pedestal production, transmitting commodity cost volatility directly into contract pricing while resisting margin compression through captive machining capabilities. Their ownership structure limits external financing for capacity expansion, tightening supply responsiveness during demand spikes from automotive OEM procurement cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Premium tiers carry ISO 10218 pre-certified fatigue-load documentation and finite element analysis packages, while economy tiers target educational and retail deployments with minimal regulatory documentation. Cost compression in steel-intensive fixed-height columns is intensifying because commodity input volatility outpaces contract repricing cycles. Logistics centers exhibit highest price sensitivity due to fleet-scale procurement and mobile platform standardization mandates, whereas pharmaceutical cleanroom buyers prioritize electromagnetic compatibility over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and China coordinate hub-and-spoke fulfillment patterns for precision-machined mounting surfaces and electromechanical lift mechanisms. Welded steel fabrication draws from Chinese and Turkish mill supply, while carbon-fiber-reinforced polymer formulations source from Japanese specialty chemical producers. Single-source vulnerability concentrates in high-tolerance finishing capacity controlled by German and Japanese machine tool suppliers. Distribution runs through full-system integrators who bundle pedestal-robot-controller procurement, displacing component-level channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Machinery Directive's 2023 stability update operates as a regulatory compounder, mandating tip-over resistance documentation that extends product development timelines and elevates pre-certified supplier premiums.
For Market Incumbents: Anticipate procurement consolidation toward full-system integrators by deepening backward integration into servo motor production and establishing EU-based technical file repositories. Certification investment in ISO/TS 15066 compliance documentation represents the critical defensive lever against emerging composite-material specialists targeting cleanroom verticals.
For New Entrants and Emerging Players: Enter via carbon-fiber-reinforced polymer formulations for semiconductor and medical device cleanroom installations, where aluminum corrosion resistance failures create specification white space. Target South Korean and Chinese logistics center fleets through AGV navigation integration partnerships as the most penetrable mobile pedestal channel.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional steel fabricators lacking EU conformity assessment capabilities but possessing precision-machining infrastructure. Long-term viability over the coming decade hinges on regulatory compliance scalability rather than production volume. Watch ISO 10218 amendment announcements as the primary inflection signal for certification-premium expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| EU Technical File Repository Establishment | Non-EU suppliers gain market access under KBA-enforced Machinery Directive compliance pathways. |
| Composite Material Formulation Partnership | Carbon-fiber-reinforced polymer sourcing secures cleanroom specification channels beyond steel capabilities. |
| AGV Navigation System Integration | Mobile pedestal fleets enable dynamic workcell repositioning for high-mix contract manufacturers. |
| Captive Servo Motor Production Expansion | FANUC-style backward integration controls pedestal-drive cost structures across installed base. |
| ISO/TS 15066 Pre-Certification Investment | Documented collaborative robot compliance compresses 8-14 month development cycle penalties. |
Research Methodology
Coverage spans Germany, Japan, the United States, China, and South Korea, with primary inputs from each territory's manufacturing belt. Plant engineers, OEM procurement teams at automotive body shops, aftermarket service heads, and robotics integration specialists contributed structured interviews. Secondary validation drew from EU Machinery Directive filings, KBA conformity assessment records, OSHA regional enforcement protocols, and SEC disclosures from listed automation conglomerates. Bottom-up volume estimates triangulated against top-down industrial robot installation data across the analysis window.
Rate-of-change decomposition segmented growth across product mobility type, material formulation, actuation technology, and end-use vertical. CAGRs were derived from installed base evolution modeling and replacement cycle analysis. Forecast inputs incorporated EU regulatory amendment timelines, automotive OEM flexible manufacturing cell investment patterns, and logistics center fleet standardization mandates without year-specific event assumptions.
Inputs from notified body filing databases and industrial robot trade associations were available through the study window; gaps in private contract pricing introduce uncertainty bands around margin structure estimates. Forecasts reflect documented assumption sets regarding regulatory enforcement intensity and commodity price stabilization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Programmable Robots Market
Robotics and Automation
Middle East and Africa Medical Robots Market
Robotics and Automation
Grafting Robot Market
Robotics and Automation
Mobile Robot Charging Station Market
Robotics and Automation
Africa Agricultural Robots and Mechatronics Market
Robotics and Automation
Global Robot Software Market
Robotics and Automation
Telepresence Robotics Market
Robotics and Automation
Industrial Robotics Market
Robotics and Automation
AGV Dispatch Management Platforms Market
Robotics and Automation
Cybersecurity in Robotics Market
Robotics and Automation
Italy Cloud Robotics Market
Robotics and Automation
Delta Robotics Market
Robotics and Automation
Robotics for NDT Market
Robotics and Automation
Robotics in Shipbuilding Market
Robotics and Automation
North America Automated Guided Vehicle (AGV) Market
Robotics and Automation
Robotic Process Automation in Legal Services Market