
 Playout Solutions Market | 2026-2036
Playout Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Playout Solutions Market Outlook
Buyer concentration among national broadcasters and sports leagues is expanding as these entities consolidate channel operations onto unified playout platforms. Harmonic leverages its software-defined video portfolio to capture multi-year infrastructure contracts from tier-one broadcasters. Evertz anchors its position through deep manufacturing scale in hardware-based routing and signal processing. Grass Valley competes by sustaining R&D intensity in IP-based production workflows that integrate directly with playout automation layers.
Playout solutions comprise integrated hardware and software systems that ingest, schedule, render, and transmit video and audio content to distribution networks, operating at latencies below two frames for live broadcast synchronization and supporting codecs from MPEG-2 through HEVC and AV1. The primary commercial purpose is to ensure continuous, frame-accurate channel output with automated failover and dynamic ad insertion. Cloud-based deployments now represent the fastest-expanding product category as broadcasters shed capital-intensive on-premise infrastructure. Channel-in-a-Box solutions dominate margin pools by collapsing graphics, branding, and automation into single-server deployments that reduce rack space and operator headcount. Hardware-based segments retain structural importance in markets with constrained connectivity or strict local-content custody requirements.
The FCC enforces closed-captioning accuracy and emergency alert integration standards that shape product certification requirements for U.S. playout vendors. EMA's medical device regulation does not apply here; instead, the EU's AVMSD and GDPR frameworks govern cross-border content distribution and viewer data handling in European deployments. India's TRAI mandates specific local-content quotas and ad-time caps that force playout systems to embed real-time compliance logic. Stakeholders must monitor how AI-generated content detection requirements and emerging deepfake labeling mandates across multiple jurisdictions will reshape metadata handling and provenance verification in next-generation playout architectures.
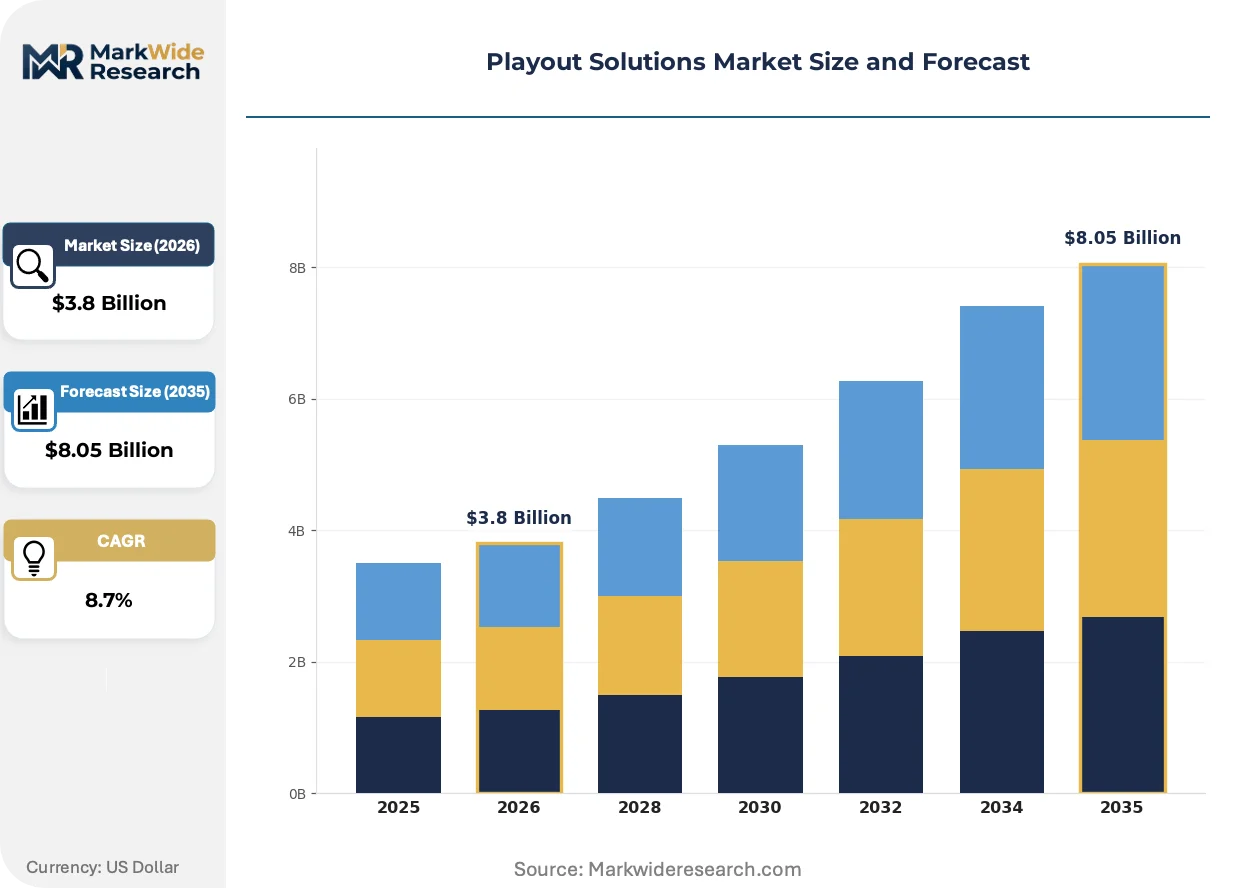
Market Dynamics
Broadcaster migration from capital-intensive on-premise hardware to cloud-native software stacks is compressing traditional infrastructure refresh cycles and redistributing value capture toward recurring-revenue service models.
Growth Catalysts
- ATSC 3.0 mandate:The FCC's next-generation broadcast standard in the United States forces infrastructure upgrades that embed advanced playout capabilities including 4K transmission and interactive content layers.
- Cloud workflow adoption:National broadcasters and sports leagues consolidate channel operations onto unified platforms, expanding procurement of automated playout systems with dynamic ad insertion.
- India:TRAI-mandated local-content quotas and ad-time caps require real-time compliance logic embedded in playout architectures, driving replacement of legacy systems.
Market Restraints
- Connectivity dependency:Cloud-based deployments face structural barriers in markets with constrained broadband infrastructure or strict local-content custody requirements that mandate on-premise hardware retention.
- Codec fragmentation:Simultaneous support requirements for MPEG-2 through HEVC and AV1 inflate engineering complexity and certification timelines for unified playout platforms.
- GDPR data handling:The EU's cross-border content distribution and viewer data frameworks impose operational friction on cloud deployments spanning multiple European jurisdictions.
Strategic Opportunities
- Channel-in-a-Box expansion:Single-server deployments that collapse graphics, branding, and automation present white space in mid-market broadcasters seeking rack-space reduction and operator headcount compression.
- AI-generated content detection:Emerging deepfake labeling mandates across multiple jurisdictions will reshape metadata handling and provenance verification requirements in next-generation playout architectures.
- Germany:The EU's AVMSD framework implementation creates regulatory tailwind for infrastructure refresh cycles among public broadcasters modernizing distribution networks.
Industry Challenges
- IP-based production integration:Broadcasters face execution complexity stitching playout automation layers with existing SDI-to-IP transition workflows without service interruption.
- Frame-accurate synchronization:Maintaining sub-two-frame latency for live broadcast synchronization across hybrid cloud-edge deployments strains engineering resources and requires specialized talent pools.
- Emergency alert certification:FCC closed-captioning accuracy and emergency alert integration standards create compliance timeline pressure for vendor product certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Playout Solutions Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IP-Based, Cloud-Based, Hardware-Based, Software-Based Product Type: Automated Playout, Live Playout, Channel-in-a-Box, Virtual Playout End User: Broadcasters, OTT Platforms, Media Companies, Sports Organizations Service Type: Managed Services, Professional Services, Support & Maintenance, Consulting Services |
| Companies Covered | Harmonic, Evertz, Grass Valley, Imagine Communications, Pebble Beach Systems, PlayBox Technology, Pixel Power, Florical Systems, BroadStream Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
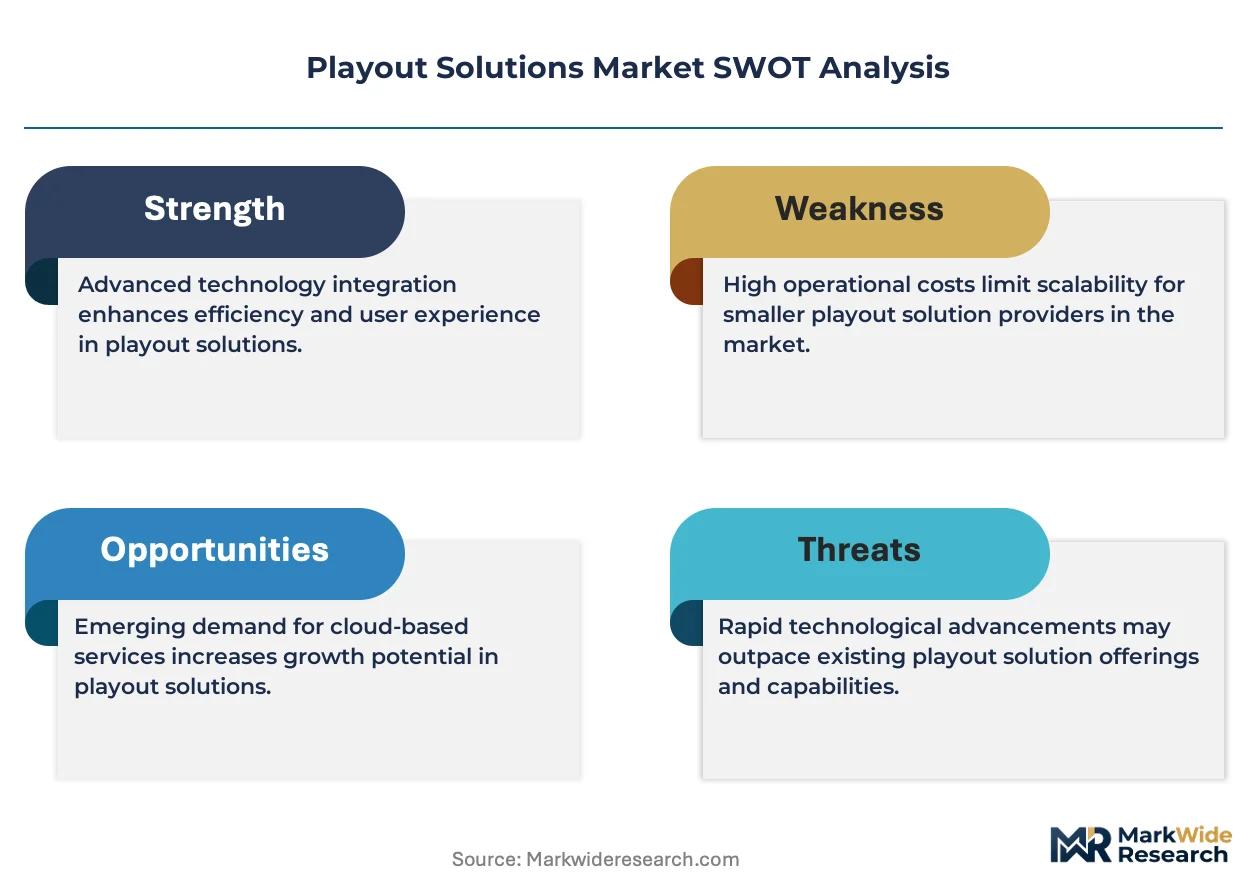
Playout Solutions Market Strategic Shifts
Software-defined architectures are actively redistributing competitive advantage from hardware manufacturing scale toward cloud orchestration capabilities and API-first integration ecosystems.
Edge computing nodes deployed at CDN points of presence are decentralizing playout processing from centralized broadcast facilities. Regional sports networks and national broadcasters with distributed operations are adopting these architectures fastest. This topology is decentralizing latency-sensitive workloads while retaining cloud-based management planes, compressing the traditional broadcast facility footprint.
The EU's AVMSD framework and GDPR requirements are tightening cross-border content distribution compliance. European deployments now embed viewer data handling logic directly into playout metadata pipelines. Public broadcasters in Germany and France are most affected, reconfiguring cloud provider selection to ensure data residency.
Buyer concentration among consolidated media groups is compressing sales cycles and elevating technical integration requirements. Large broadcasters now demand unified platforms spanning playout, graphics, and distribution rather than point solutions. This pattern is most visible in the United States where national broadcasters and sports leagues negotiate multi-year infrastructure contracts with embedded professional services.
Playout Solutions Market Segmentation
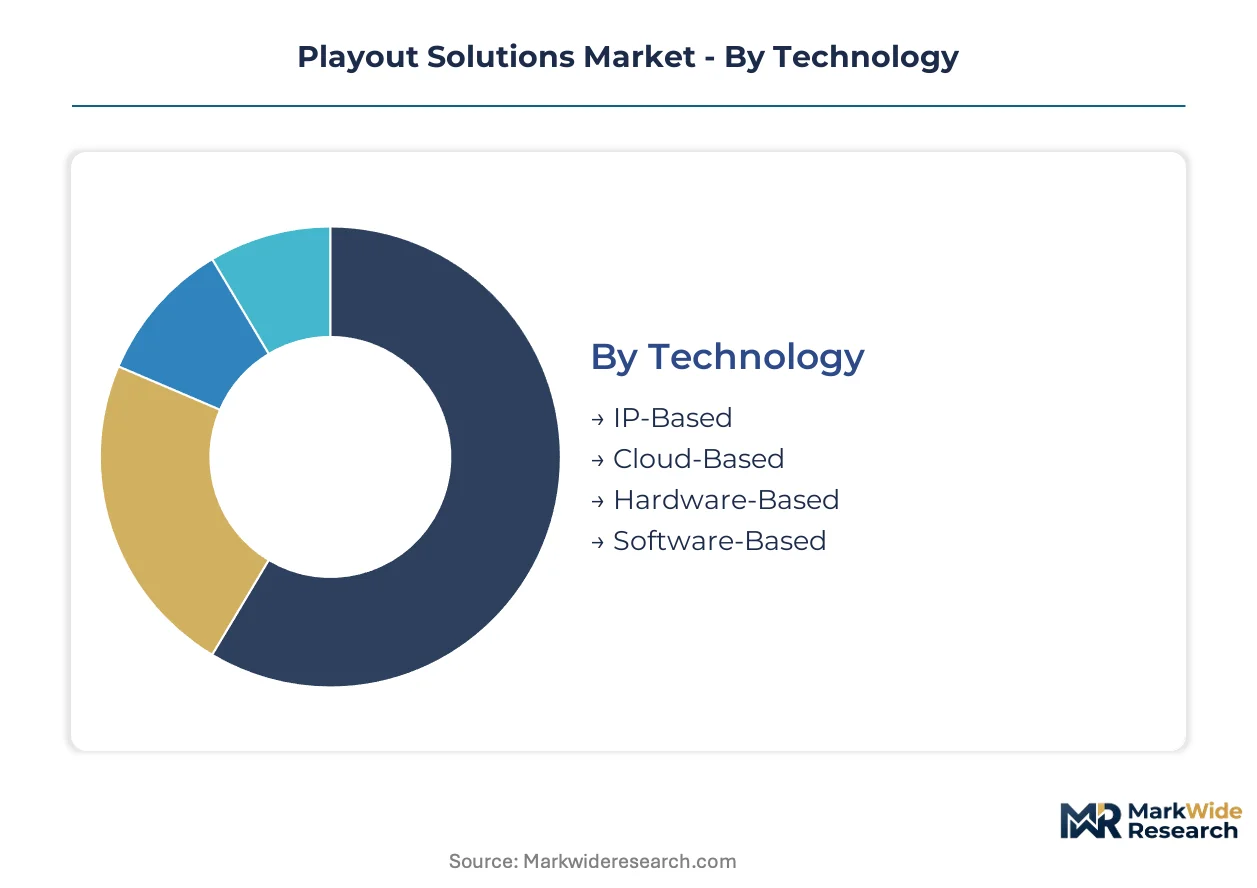
Playout solutions segment across technology architectures, deployment models, and service relationships that determine capital intensity and operational flexibility for broadcast operators. Each segmentation axis reveals distinct margin profiles and customer concentration patterns that reshape competitive positioning.
Technology:
Volume concentrates in hardware-dominated legacy installations while premium capture shifts toward software-defined and cloud-native stacks.
- Cloud-Based:Software stacks running on public or private cloud infrastructure eliminate on-premise server footprints and convert capital expenditure to recurring operational models. National broadcasters in the United States and sports leagues consolidating multi-channel operations are expanding procurement fastest, though constrained broadband markets in India retain hybrid requirements.
- IP-Based:Network-based signal transport replacing traditional SDI routing enables scalable channel expansion without dedicated copper infrastructure. German public broadcasters modernizing distribution networks under AVMSD compliance timelines are deploying these architectures most aggressively, integrating directly with automated playout layers.
- Hardware-Based:Dedicated appliance deployments persist where local-content custody mandates or connectivity gaps prohibit cloud migration.
- Software-Based:On-premise software licenses without cloud dependency serve mid-market broadcasters seeking automation without subscription economics.
Today's leader: Hardware-Based. Tomorrow's challenger: Cloud-Based.
Product Type:
Application context separates live event workflows from file-based automation, with integration depth determining customer stickiness.
- Channel-in-a-Box:Single-server systems collapsing graphics, branding, and automation into unified deployments dominate margin pools by reducing rack space and operator headcount. Mid-market broadcasters in Germany and India seeking operational compression represent the fastest-expanding demand concentration.
- Automated Playout:Rules-based scheduling and transmission systems with dynamic ad insertion capabilities anchor infrastructure contracts from tier-one broadcasters. United States national networks migrating to ATSC 3.0 workflows are refreshing these systems to embed 4K transmission and interactive content layers.
- Live Playout:Sub-two-frame latency systems for real-time broadcast synchronization serve sports organizations and news operations.
- Virtual Playout:Fully software-rendered channel origination without dedicated broadcast hardware enables rapid channel launches.
Channel-in-a-Box commands current margins; Automated Playout captures renewal cycles.
End User:
Customer scale and procurement sophistication create tiered pricing structures across consolidated media groups and fragmented operators.
- Broadcasters:National and regional television networks with multi-channel operations requiring frame-accurate synchronization and automated failover. FCC closed-captioning accuracy mandates and emergency alert integration standards shape certification requirements for United States deployments.
- OTT Platforms:Streaming-native operators building cloud-first distribution infrastructure without legacy hardware baggage. India's platform buildouts under TRAI-mandated local-content quotas are driving replacement of legacy systems with real-time compliance logic.
- Media Companies:Content owners with multi-platform distribution needs spanning traditional broadcast and digital endpoints.
- Sports Organizations:Leagues and regional networks with distributed operations and peak-load event requirements.
Broadcasters anchor current revenue; OTT Platforms are climbing the fastest.
Service Type:
Margin capture redistributes from perpetual licenses toward recurring service relationships as cloud adoption accelerates.
- Managed Services:Outsourced playout operations where vendors assume operational responsibility for channel output, including compliance monitoring and dynamic ad insertion. United States sports leagues and national broadcasters are consolidating onto these arrangements to shed specialized talent requirements.
- Professional Services:Integration, customization, and workflow engineering for complex multi-vendor environments. GDPR data handling requirements across European jurisdictions are elevating demand for compliance-focused deployment architecture.
- Support & Maintenance:Technical assistance and software update subscriptions for on-premise deployments.
- Consulting Services:Strategic advisory for cloud migration planning and SDI-to-IP transition roadmapping.
Managed Services lead present bookings; Professional Services gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized broadcast engineering talent pools in Los Angeles, London, and Mumbai anchor geographic demand concentration for playout infrastructure modernization.
United States
National broadcasters and regional sports networks are consolidating multi-channel operations onto unified cloud-native platforms. FCC ATSC 3.0 mandates force infrastructure upgrades embedding 4K transmission and interactive content layers. Los Angeles hosts the densest cluster of broadcast facility engineering teams modernizing legacy SDI workflows.
Germany
Public broadcasters under AVMSD compliance timelines are aggressively deploying IP-based signal transport architectures. GDPR cross-border data handling requirements reshape cloud provider selection for viewer metadata pipelines. Munich and Cologne anchor the largest broadcast technology integration clusters in continental Europe.
India
OTT platform buildouts and TRAI-mandated local-content quotas drive replacement of legacy automation systems. Real-time compliance logic for ad-time caps forces embedded processing in playout architectures. Mumbai and Bengaluru concentrate streaming-native engineering teams building cloud-first distribution infrastructure.
United Kingdom
Consolidated media groups demand unified platforms spanning playout, graphics, and distribution rather than point solutions. Ofcom broadcasting codes and emerging AI-generated content detection requirements reshape metadata handling specifications. London's Soho district retains specialized post-production and channel-origination engineering density.
Japan
Broadcasters transitioning 8K experimental channels toward commercial deployment require next-generation compression and synchronization capabilities. METI technology roadmaps prioritize software-defined video processing for terrestrial network efficiency. Tokyo's broadcast engineering corridor hosts concentrated vendor integration and certification activity.
Playout Solutions Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base separates into three strategic archetypes: software-defined video portfolio vendors, hardware-centric signal processing manufacturers, and IP-native production workflow developers. Dominant competitive moves include multi-year infrastructure contract capture from tier-one broadcasters and embedded professional services for complex SDI-to-IP transitions.
Within the software-defined tier, Harmonic leverages cloud orchestration capabilities to anchor recurring-revenue service relationships. Evertz occupies a position exemplifying hardware manufacturing scale in routing and signal processing. Grass Valley represents the IP-native archetype through sustained engineering intensity in production workflow integration.
| Leading Market Players |
|---|
| Harmonic |
| Evertz |
| Grass Valley |
| Imagine Communications |
| Pebble Beach Systems |
| PlayBox Technology |
| Pixel Power |
| Florical Systems |
| BroadStream Solutions |
| Others |
Value Chain & Pricing Dynamics
Captive cloud infrastructure development by hyperscalers anchors supply positioning while compressing subscription pricing power for independent software vendors. This vertical integration pattern concentrates value capture among broadcasters with direct cloud partnerships, forcing mid-tier vendors toward professional services bundling to defend margin.
Pricing Analysis
Capacity additions in Germany and India are reshaping price floors for Channel-in-a-Box deployments as regional manufacturing scales. Three-tier pricing structure across premium, standard, and economy levels separates broadcast-grade certification tiers, with FCC ATSC 3.0 compliance commanding substantial premiums. Cost compression in mid-market SaaS tiers is intensifying because hyperscaler direct-selling bypasses traditional vendor channels. National broadcasters in the United States show least price sensitivity due to multi-year infrastructure lock-ins, while regional Indian broadcasters exhibit highest sensitivity to recurring operational costs.
Supply Chain Analysis
Regional distribution centers in Los Angeles, London, and Mumbai anchor hub-and-spoke fulfillment patterns for specialized broadcast hardware. Manufacturing concentrates in Taiwan for GPU acceleration modules, Germany for precision timing equipment, and the United States for software-defined video processing chipsets. Component sourcing draws from South Korean memory suppliers, Japanese precision oscillators, and Chinese PCB fabrication. Single-source vulnerability around FPGA supply from Xilinx-AMD creates procurement risk for latency-critical live playout systems. Distribution runs through systems integrators with broadcast engineering certifications rather than direct vendor-to-broadcaster models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in playout solutions rests on cloud orchestration premiumization and the displacement of hardware-heavy cost structures by software-defined stacks.
For Market Incumbents: Extend recurring-revenue service relationships through embedded professional services for SDI-to-IP transitions, capturing multi-year infrastructure contracts before hyperscalers consolidate direct broadcaster relationships. Invest in real-time compliance logic certification for India's TRAI mandates to preempt regional specialist capture. Backward integration into edge computing node deployment at CDN points of presence secures latency-critical live sports workflows against cloud-native challengers. For New Entrants and Emerging Players: Cloud marketplace distribution routes offer lowest-friction customer acquisition for virtual playout solutions targeting mid-market broadcasters in Germany and India. White space concentrates in AI-generated content detection modules for metadata pipelines, where emerging deepfake labeling mandates create first-mover certification advantages. Partner with regional systems integrators in Mumbai and Bengaluru for TRAI-compliant deployment architecture rather than direct enterprise sales. For Investors and Strategic Acquirers: Roll-up economics work for IP-native production workflow specialists because broadcaster consolidation demands unified platform procurement spanning playout, graphics, and distribution. Target acquisition archetypes include Channel-in-a-Box vendors with embedded graphics engines and managed services operators with sports league contracts. Signal to watch: FCC emergency alert certification timeline acceleration indicating infrastructure refresh cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Hyperscaler partnerships with national broadcasters displace on-premise hardware capital expenditure models. |
| ATSC 3.0 Compliance Certification | FCC mandates force 4K transmission and interactive layer embedding in United States infrastructure contracts. |
| Channel-in-a-Box Product Line Expansion | Single-server deployments reduce rack space and operator headcount for mid-market German and Indian broadcasters. |
| Managed Services Outsourcing | United States sports leagues shed specialized talent requirements through vendor-operational responsibility transfers. |
| Edge Computing Node Deployment | CDN point-of-presence processing decentralizes latency-sensitive workloads for regional sports networks. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with broadcast technology executives, channel operations directors, systems integration specialists, and regulatory compliance officers with secondary validation. Sources included FCC filing databases, TRAI consultation papers, EU AVMSD implementation reports, SEC 10-K disclosures from listed broadcast technology vendors, and hyperscaler capex announcements. Bottom-up channel count modeling and top-down infrastructure spend estimates were triangulated against vendor booking disclosures.
Historical reference periods anchored the projection horizon through year-over-year infrastructure refresh cycle analysis and cloud adoption trajectory mapping. Segmentation dimensions modeled include technology architecture, deployment model, product type, end-user scale, and service relationship type, with additional weighting for regulatory compliance tier complexity. CAGRs were derived from installed base turnover rates and new platform procurement velocity. Forecast inputs incorporated ATSC 3.0 mandate implementation timelines and TRAI local-content quota enforcement intensity.
Regulatory delay, hyperscaler pricing aggression, and broadcast rights consolidation are the dominant revision risks that could compress vendor margin assumptions or accelerate cloud displacement timelines. Forecasts reflect operating assumptions about infrastructure refresh cadence and compliance technology embedding. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Blockchain in Media and Entertainment Market
Digital Media
Global Stock Video Market
Digital Media
Media Coding Service Market
Digital Media
In Flight Entertainment Market
Digital Media
Music Rights Management Market
Digital Media
Anime Market
Digital Media
Global Music Video Production Market
Digital Media
Digital Media Switchers Market
Digital Media
Multichannel Network Market
Digital Media
Digital Rights Management in Media and Entertainment Market
Digital Media
VFX Market
Digital Media
Sports Graphics Market
Digital Media
US Animation, Vfx and Post Production Market
Digital Media
Asia-Pacific and Germany Digital Out of Home (DOOH) Advertising Market
Digital Media
Europe Location-Based Entertainment Market
Digital Media
Online Gambling Market