
 Middle East and Africa Animation Market | 2026-2036
Middle East and Africa Animation Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Animation Market Foresight
High-definition 4K rendering pipelines is rotating through the Middle East and Africa animation landscape as broadcasters and streaming platforms upgrade technical specifications. DreamWorks Animation leverages its established IP licensing infrastructure to sustain premium content revenue across Gulf markets. Triggerfish Animation Studios anchors African original production capacity from Cape Town, while Animation DXB Design Studios dominates commissioned commercial work for UAE government and tourism clients.
Animation in the Middle East and Africa encompasses the design, production, and post-processing of moving visual content through digital 2D vector manipulation, 3D polygonal modeling, stop-motion frame capture, and motion graphics compositing, typically delivered at 24–60 frames per second for broadcast, theatrical, or interactive display. The primary commercial purpose spans entertainment distribution, educational curriculum delivery, brand advertising campaigns, and healthcare visualization tools. 3D animation commands the largest production investment pool across Gulf entertainment budgets, while motion graphics captures the fastest expansion as corporate and government sectors digitize public communications. Online streaming distribution now outpaces theatrical releases as the dominant revenue channel for original series, though television retains structural importance in North African households where linear broadcast infrastructure remains entrenched.
The National Media Council of the UAE enforces content classification and licensing standards that shape which animation projects receive production permits and distribution clearance across Emirates markets. South Africa's Film and Publication Board and Nigeria's National Film and Video Censors Board impose age-appropriate ratings and local content quotas that directly determine market access for both imported and domestically produced animation. Saudi Arabia's General Commission for Audiovisual Media has introduced licensing frameworks for streaming platforms that alter how animation content enters the Kingdom. Stakeholders must monitor how divergent censorship regimes across these jurisdictions fragment content versioning requirements and force localization investments that alter project economics.
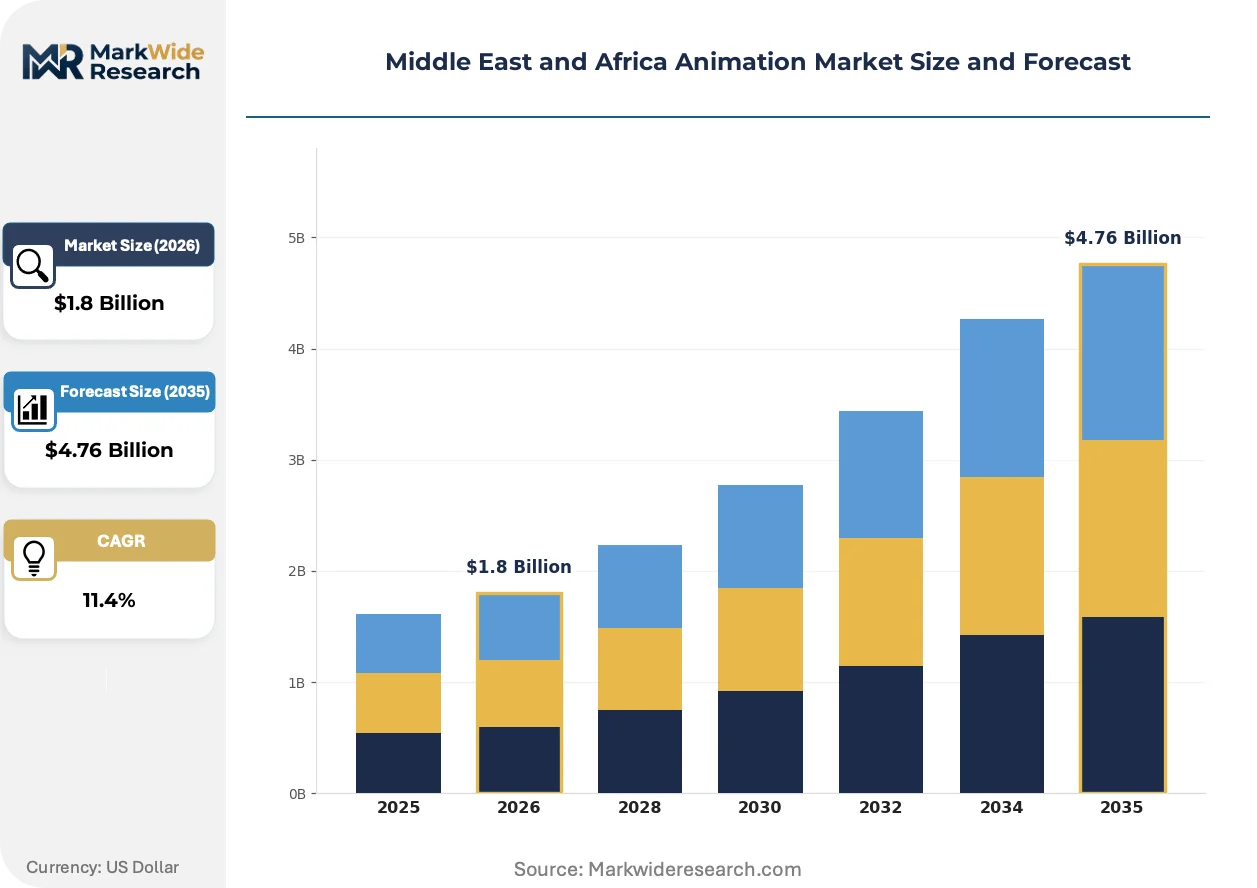
Market Dynamics
Streaming platform technical specifications are compressing production timelines across Middle East and Africa animation studios, forcing infrastructure upgrades that reshape project economics and competitive positioning.
Growth Catalysts
- 4K rendering pipelines:Broadcasters in the United Arab Emirates now mandate high-definition delivery standards, compelling studios to modernize post-production workflows and capture premium licensing fees.
- NFVCB content codes:Nigeria's National Film and Video Censors Board local content quotas create protected market access for domestic animation producers serving Nollywood distribution channels.
- Dubai Media City incubation:The free zone's production facility subsidies and talent visa programs concentrate regional animation capacity in the Emirates.
Market Restraints
- Render farm electricity costs:Grid instability and diesel generator dependence in Lagos and Johannesburg inflate per-frame processing expenses above Gulf benchmarks.
- South African FPB classification delays:The Film and Publication Board's backlog in age-rating certifications stretches theatrical release windows and strains working capital.
- Imported software licensing:Subscription costs for Autodesk Maya and Adobe After Effects dominate studio operating budgets, with limited open-source alternatives penetrating professional pipelines.
Strategic Opportunities
- Saudi GCAM streaming licenses:The General Commission for Audiovisual Media's platform authorization framework opens Kingdom distribution for animation series previously blocked by theatrical-only pathways.
- Healthcare visualization:Medical training institutions in Egypt and Morocco commission anatomical animation for surgical simulation, creating non-entertainment revenue streams.
- Motion graphics digitization:Government communication departments across Gulf Cooperation Council states replace print campaigns with animated public service announcements.
Industry Challenges
- Character rigging specialization:Studios in Cape Town and Nairobi compete for the limited pool of technical artists capable of building production-ready 3D puppet systems.
- Multi-jurisdiction versioning:Divergent censorship requirements between the UAE's National Media Council, Saudi GCAM, and Nigerian NFVCB force redundant localization passes on single properties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Animation Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: 2D Animation, 3D Animation, Stop Motion, Motion Graphics Industry Vertical: Entertainment, Education, Advertising, Healthcare Distribution Channel: Online Streaming, Television, Theatrical Releases, Mobile Apps Target Audience: Children, Adults, Businesses, Educational Institutions |
| Companies Covered | Studio Ghibli, Production I.G, DreamWorks Animation, Animation DXB Design Studios, Karbonat, Triggerfish Animation Studios, MAPPA, Vinno Media, Toei Animation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Animation Market Shifts & Advancements
Real-time rendering engines are compressing the gap between concept and final output, altering how Middle East and Africa studios bid on projects and staff production teams.
Unreal Engine 5's Nanite virtualized geometry system is miniaturizing asset preparation timelines for architectural visualization and pre-rendered series. Nigerian commercial studios adopt the platform for government project pitches, collapsing what required weeks of polygon optimization into days. The technology is miniaturizing the traditional modeling-texturing-rigging pipeline, allowing smaller teams to bid on scopes previously reserved for Triggerfish-scale operations.
South Africa's Film and Publication Board amended its online content classification regulations to cover streaming-native releases, eliminating the theatrical-first pathway that delayed digital premieres. The change forces distributors to submit interactive platform materials alongside traditional broadcast cuts. Subscription services operating in Johannesburg and Cape Town now maintain parallel compliance teams to manage simultaneous multi-platform launches.
Commissioning patterns among Emirates government clients now prioritize rapid-turnaround motion graphics over fully animated narrative content. Dubai tourism authorities contract three-week social media campaigns rather than six-month broadcast series, compressing vendor selection and payment cycles. Procurement through twofour54's pre-approved supplier rosters accelerates this shift, locking out non-incumbent studios from public-sector work.
Middle East and Africa Animation Market Segmentation
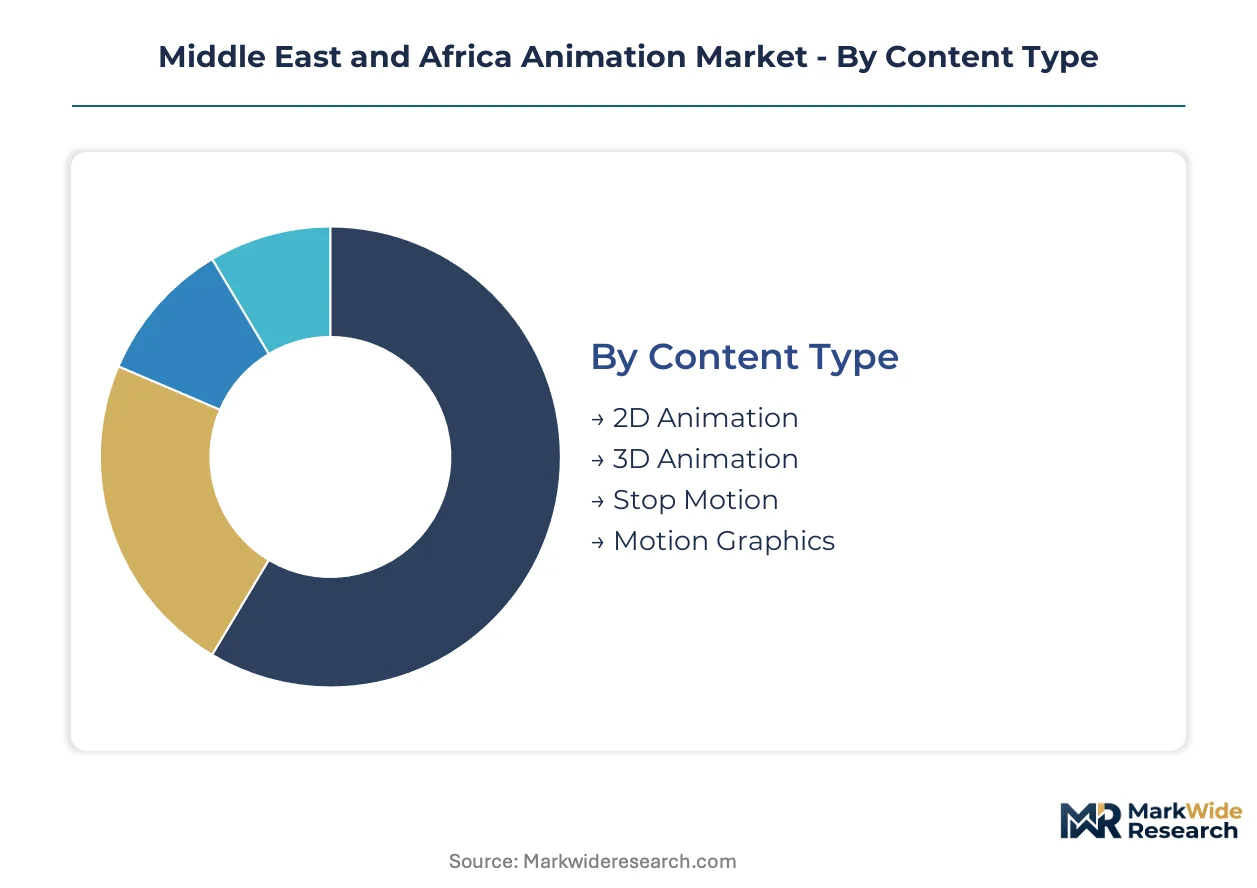
Segmentation in the Middle East and Africa animation market reveals how technical specifications, regulatory environments, and distribution infrastructure fragment revenue opportunities across distinct buyer profiles. Studios must align production pipelines with channel-specific delivery requirements to capture premium licensing fees.
Content Type:
Channel mix varies sharply by technical format, with 3D animation dominating theatrical and streaming premium tiers while motion graphics flows through government procurement and social media campaigns.
- 3D Animation:Polygonal modeling and rigging pipelines require specialized render farm infrastructure. Demand concentrates in the United Arab Emirates, where Dubai Media City facilities and twofour54 subsidies support high-budget series production for streaming platforms. The format commands the largest production investment pool across Gulf entertainment budgets.
- Motion Graphics:Vector-based compositing and kinetic typography enable rapid-turnaround deliverables. Saudi Arabia's General Commission for Audiovisual Media licensing framework and UAE government communication departments drive replacement of print campaigns with animated public service announcements.
- 2D Animation:Vector manipulation and traditional frame-by-frame techniques serve educational content and lower-budget streaming series across North African markets.
- Stop Motion:Physical puppet and set fabrication remains niche, with limited commercial application outside specialty advertising and artistic projects in South Africa.
By volume, 3D Animation leads. By growth pace, Motion Graphics is expanding most quickly.
Industry Vertical:
Cost tiers stratify sharply across verticals, with entertainment absorbing capital-intensive pipelines while healthcare and education operate on constrained procurement cycles.
- Entertainment:Feature films and episodic series require 24–60 frames per second delivery for theatrical and streaming platforms. Nigeria's National Film and Video Censors Board local content quotas create protected market access for domestic producers serving Nollywood distribution channels.
- Advertising:Brand campaigns and commercial spots prioritize compressed timelines over technical sophistication. Emirates government clients now contract three-week social media campaigns rather than six-month broadcast series.
- Education:Curriculum delivery and instructional content serve schools and training institutions across Egypt and Morocco with lower per-minute budgets.
- Healthcare:Anatomical visualization and surgical simulation represent emerging non-entertainment revenue streams for medical training institutions.
Entertainment captures the highest absolute spend. Healthcare demonstrates the steepest expansion trajectory as medical simulation adoption accelerates.
Distribution Channel:
Geographic penetration determines channel viability, with streaming infrastructure concentrated in Gulf Cooperation Council states while linear broadcast retains structural importance in North African households.
- Online Streaming:Subscription platforms now mandate 4K rendering specifications and compressed delivery timelines. South Africa's Film and Publication Board amended online content classification regulations to cover streaming-native releases, eliminating theatrical-first pathways.
- Television:Linear broadcast infrastructure remains entrenched in North African households, sustaining demand for episodic content that meets traditional scheduling constraints.
- Theatrical Releases:Cinema distribution faces compressed windows as streaming platforms capture premiere rights, though family-oriented animation retains venue viability in Saudi Arabia.
- Mobile Apps:Short-form content for smartphone consumption targets commuter audiences and youth demographics with lower production values and vertical formatting requirements.
Streaming platforms lead by revenue contribution. Mobile Apps are gaining share fastest as data costs decline and smartphone penetration deepens.
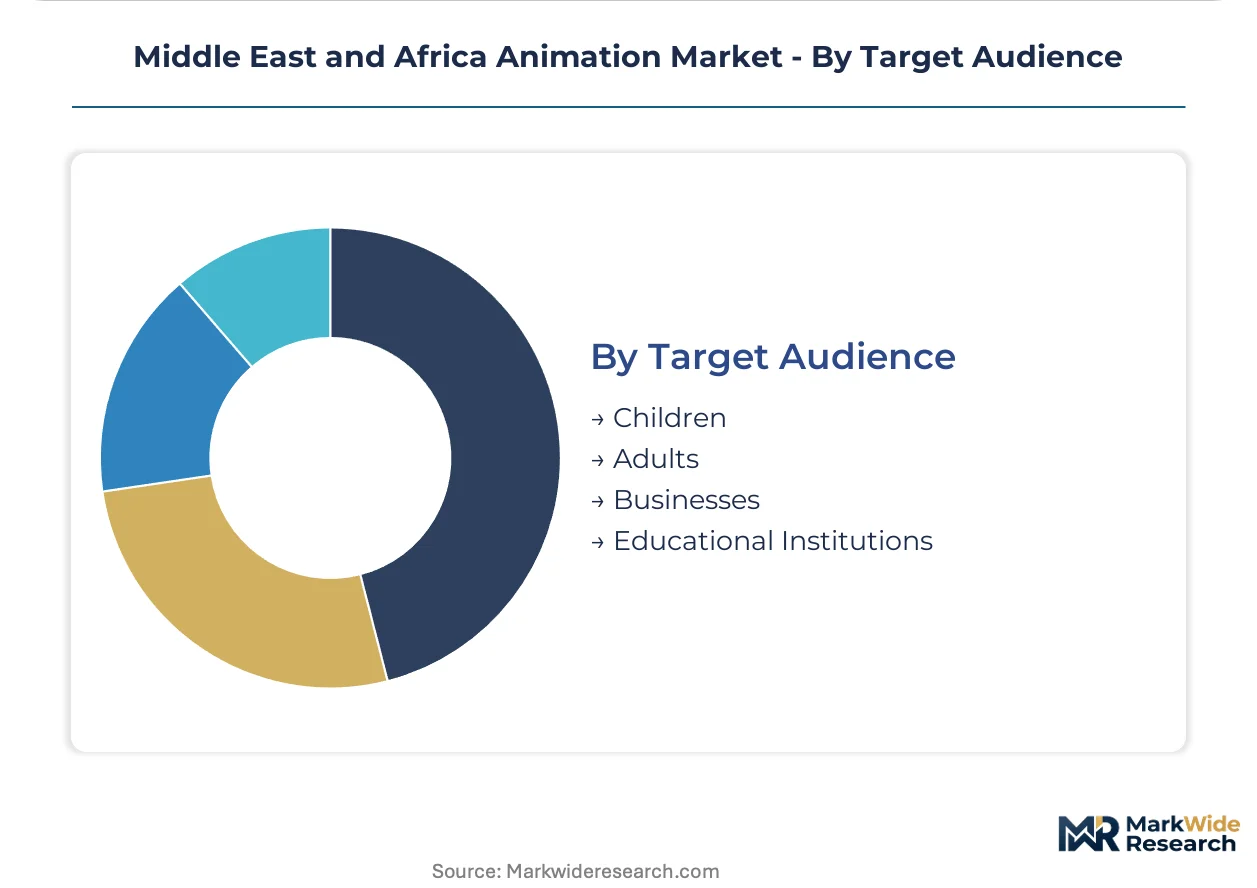
Target Audience:
Customer type dictates content standards and regulatory scrutiny, with children's programming facing the most stringent classification requirements across jurisdictions.
- Children:Age-appropriate content faces dual oversight from South Africa's Film and Publication Board and Nigeria's National Film and Video Censors Board, with classification delays stretching release windows.
- Adults:Mature-themed animation for streaming platforms operates under divergent censorship regimes that force redundant localization passes between UAE, Saudi, and Nigerian markets.
- Businesses:Corporate training and internal communications represent stable procurement for commercial studios in Lagos and Johannesburg.
- Educational Institutions:Schools and universities commission curriculum-aligned content with specific learning outcome requirements and extended review cycles.
Children's content dominates by production volume. Adult-oriented streaming series climb the fastest as platform competition intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Animation services flow predominantly into the Middle East and Africa region rather than outward, with Gulf entertainment budgets importing technical expertise while Nigerian and South African studios develop exportable original IP for streaming distribution.
United Arab Emirates
Dubai Media City and Abu Dhabi twofour54 incubate regional animation capacity through production facility subsidies and talent visa programs. The National Media Council enforces content classification standards that determine which projects receive production permits across Emirates markets. Dubai tourism authorities now contract rapid-turnaround motion graphics campaigns through pre-approved supplier rosters, concentrating government procurement among incumbent studios.
Saudi Arabia
The General Commission for Audiovisual Media introduced licensing frameworks for streaming platforms that alter how animation content enters the Kingdom. Family-oriented theatrical releases retain venue viability as cinema infrastructure expands, though streaming platforms increasingly capture premiere rights. Riyadh-based production facilities are scaling to meet GCAM technical specifications for platform authorization.
South Africa
Triggerfish Animation Studios anchors African original production capacity from Cape Town, serving international streaming commissions. The Film and Publication Board's amended online content classification regulations now cover streaming-native releases, eliminating theatrical-first pathways that previously delayed digital premieres. Classification backlogs nonetheless stretch release windows and strain distributor working capital.
Nigeria
Nollywood distribution channels create protected market access for domestic animation producers under National Film and Video Censors Board local content quotas. Lagos studios face render farm electricity costs inflated by grid instability and diesel generator dependence. The NFVCB content codes directly determine theatrical and streaming market access for both imported and domestically produced animation.
Egypt
Medical training institutions in Cairo and Alexandria commission anatomical animation for surgical simulation, creating non-entertainment revenue streams distinct from Gulf entertainment budgets. Educational content procurement operates on constrained cycles compared to streaming platform specifications. Linear broadcast infrastructure retains structural importance in Egyptian households where traditional scheduling constraints persist.
Middle East and Africa Animation Market Competitive Landscape
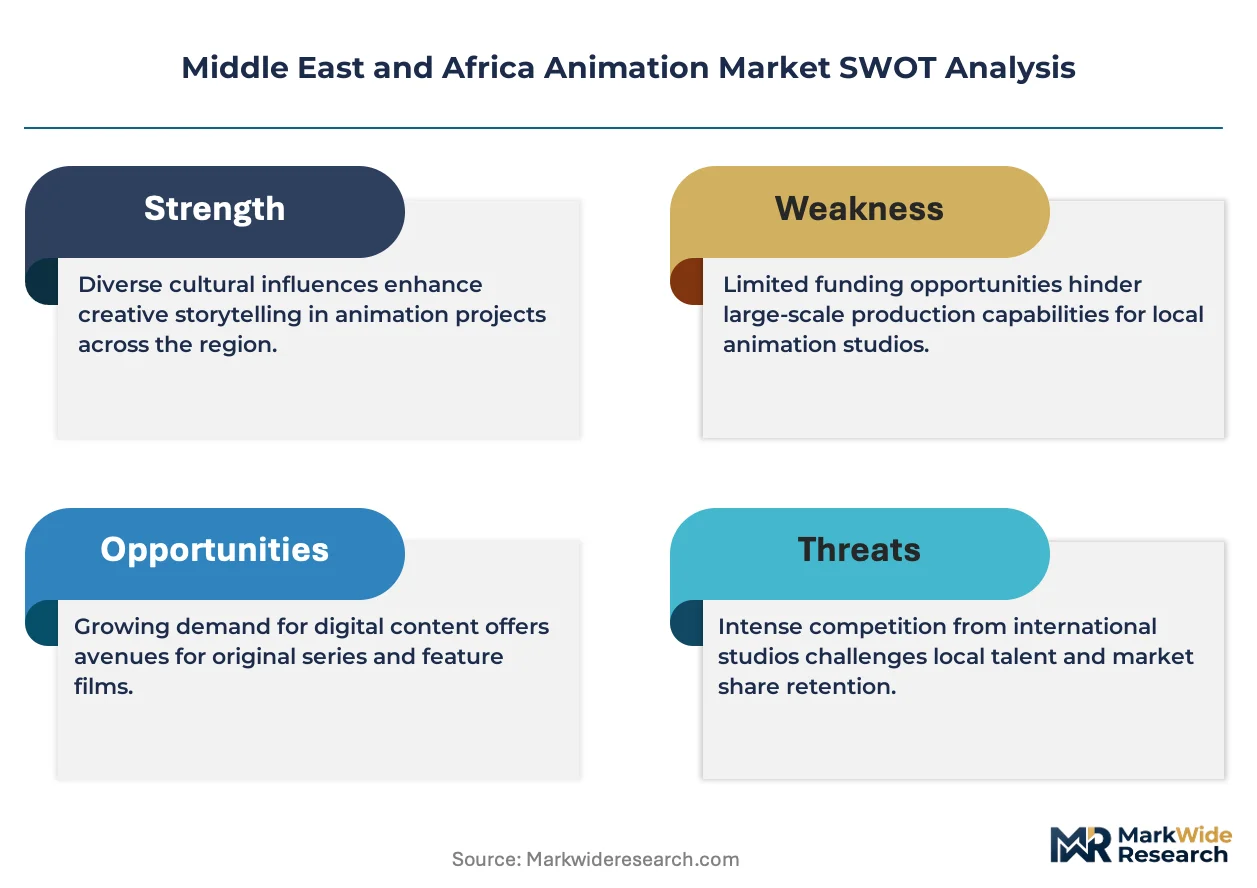
Concentration sits with streaming-commissioned original producers and government-contracted motion graphics specialists, while mid-tier commercial studios fragment across advertising and corporate training verticals. The competitive terrain divides between premium IP holders leveraging established licensing infrastructure and regional houses competing on localization speed and regulatory compliance. Strategic moves center on securing pre-approved supplier status with Emirates government procurement rosters and obtaining GCAM platform authorization for Saudi distribution. Talent acquisition for character rigging technical artists represents a secondary battleground as Cape Town and Nairobi studios compete for scarce specialized labor.
Among Gulf-based commissioned specialists, Animation DXB Design Studios exemplifies the government-contracted motion graphics archetype, while Triggerfish Animation Studios occupies the streaming-original production tier for African IP. DreamWorks Animation represents the premium IP licensing infrastructure archetype sustaining revenue across Gulf markets through established franchise distribution. These three anchors illustrate how competitive positioning stratifies between regulatory-complying regional execution and globally portable content libraries.
| Leading Market Players |
|---|
| Studio Ghibli |
| Production I.G |
| DreamWorks Animation |
| Animation DXB Design Studios |
| Karbonat |
| Triggerfish Animation Studios |
| MAPPA |
| Vinno Media |
| Toei Animation |
| Others |
Supply & Pricing Matrix
Real-time rendering engine adoption is displacing traditional render farm dependency across Middle East and Africa animation studios, simultaneously shifting supply geography toward software licensing hubs in the United States and Europe while compressing project-based pricing economics for legacy pipeline operators.
Pricing Analysis
Streaming platform buyers anchor project-based pricing structures across Gulf entertainment budgets. Three-tier pricing structure across premium streaming commissions, mid-tier advertising projects, and economy educational content reflects divergent technical specifications and timeline pressures. Cost compression in mid-tier segments is intensifying as Nigerian and South African studios compete for Nollywood and government contracts with compressed margins. Independent production houses exhibit highest price sensitivity, while Emirates government clients demonstrate lowest sensitivity due to pre-approved supplier roster procurement.
Supply Chain Analysis
Container availability constraints on Asia-Gulf trade lanes inflate inbound logistics costs for physical render farm hardware and workstation components. Software licensing supply concentrates in the United States, Ireland, and Singapore through Autodesk and Adobe distribution networks. Raw material dependencies span GPU chipsets from Taiwan, storage arrays from South Korea, and cooling systems from Germany. Single-source vulnerability rests on Autodesk Maya's dominance in character rigging pipelines. Distribution runs through Dubai Media City and twofour54 procurement channels for government clients, direct vendor relationships for independent studios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Live-action content substitution threatens animation market share as Gulf streaming platforms expand original production budgets; incumbents must demonstrate cost efficiency and localization speed that live-action cannot replicate.
For Market Incumbents: Compound defensive positioning through backward integration into render farm infrastructure and exclusive talent retention pacts with Cape Town and Nairobi technical artists. Secure pre-approved supplier status with Emirates government procurement rosters before non-incumbent competitors establish relationships. Counter emerging studio entrants by locking long-term platform authorization contracts with Saudi GCAM.
For New Entrants and Emerging Players: NFVCB certification fast-tracks create protected market access for Nigerian studios serving Nollywood distribution channels. Target healthcare visualization segments in Egypt and Morocco where incumbent competition remains sparse and procurement cycles favor rapid turnaround. Pursue white-label motion graphics partnerships with Dubai tourism authorities seeking alternatives to incumbent Animation DXB Design Studios.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed streaming-commissioned studios in South Africa and the UAE seeking exit liquidity. Five-to-ten year viability hinges on original IP ownership rather than work-for-hire dependency. Monitor Saudi GCAM platform authorization approvals as inflection indicator for Kingdom distribution access.
| Strategic Initiative | Industry Significance |
|---|---|
| Render Farm Infrastructure Investment | Cape Town and Lagos studios reduce per-frame processing costs below Gulf benchmarks through captive GPU clusters. |
| GCAM Platform Authorization | Saudi distribution access unlocks Kingdom streaming revenue previously blocked by theatrical-only pathways. |
| NFVCB Certification Fast-Track | Nigerian studios secure protected market access under local content quotas for Nollywood distribution. |
| Healthcare Visualization Partnership | Cairo and Alexandria medical training institutions commission anatomical animation for surgical simulation revenue. |
| twofour54 Supplier Roster Inclusion | Emirates government procurement channels concentrate motion graphics contracts among pre-approved incumbents. |
Research Methodology
A spread of perspectives from animation studio executives, streaming platform commissioning editors, National Media Council regulatory officers, and healthcare visualization procurement managers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against UAE National Media Council classification databases, South African Film and Publication Board release records, Nigerian NFVCB content codes, and streaming platform technical specification disclosures. Bottom-up project pipeline tracking and top-down entertainment budget allocation estimates were triangulated to derive market sizing.
Segmentation dimensions modeled span content type, industry vertical, distribution channel, and target audience across the projection horizon. CAGRs were derived from trajectory fitting to historical production volume data and forward-looking platform commissioning announcements. Industry-specific forecast inputs include Dubai Media City facility utilization rates and Saudi GCAM licensing framework implementation pace.
Decision-makers should treat outputs as directional under stable regulatory enforcement and streaming platform investment assumptions; material deviation in censorship regime stringency or platform budget allocation would warrant model refresh. Practitioners should keep alternative scenarios live as Saudi cinema infrastructure expansion and Nigerian grid stability conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
North America Online Gambling Market
Digital Media
India Webtoons Market
Digital Media
Video Production Market
Digital Media
Europe Online Video Platform Market
Digital Media
Saudi Arabia Webtoons Market
Digital Media
Sound Effects Services Market
Digital Media
Asia Pacific Photography Service Market
Digital Media
Anime Derivatives Market
Digital Media
Animation and VFX Market
Digital Media
Manga Market
Digital Media
3D Anaglyph Glasses Market
Digital Media
3D Animation Market
Digital Media
Digital Rights Management in Media and Entertainment Market
Digital Media
Digital Media Switchers Market
Digital Media
Indonesia Digital Media Market
Digital Media
Stock Music Software Market