
 Online Art Market | 2026-2036
Online Art Market Size, Share, and Industry Trends Forecast 2026-2036
Online Art Market Analytics
Digital print substrates are consolidating as the dominant material base for accessible online art, displacing traditional canvas in entry-level segments. Saatchi Art leverages its artist-discovery algorithms to sustain a curated marketplace model. Christie's International anchors high-value digital auctions through controlled release strategies. Sotheby's competes with hybrid live-digital events that extend reach beyond physical salerooms.
Online art constitutes commercial transactions of visual creative works conducted through internet-based platforms, encompassing digital files, physical works with remote provenance verification, and blockchain-authenticated editions with cryptographic ownership records. The medium serves collectors, investors, and interior designers seeking price-transparent access across geographies without physical gallery intermediation. Contemporary art and digital art command premium attention within product type and medium categories, where scarcity-engineered drops concentrate margin pools. Marketplaces and online auctions represent the fastest-expanding sales channels, though direct sales sustain higher per-transaction yields for established artists.
The EU's GDPR shapes data handling for collector platforms serving European buyers, while the SEC monitors fractional art investment vehicles in the United States. China's SAMR enforces consumer protection standards on domestic art e-commerce operators. Stakeholders must monitor evolving authentication liability frameworks as AI-generated works proliferate and challenge traditional provenance systems.
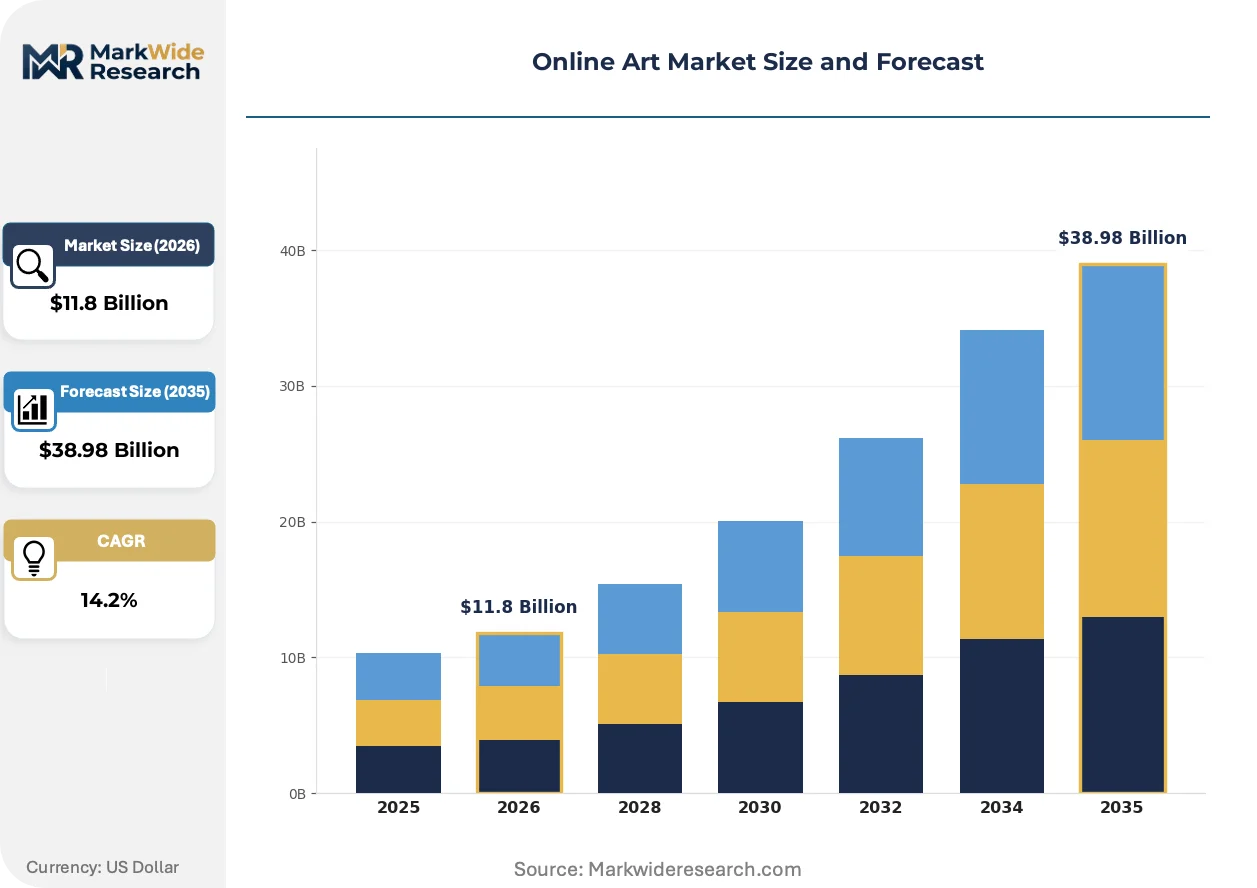
Market Dynamics
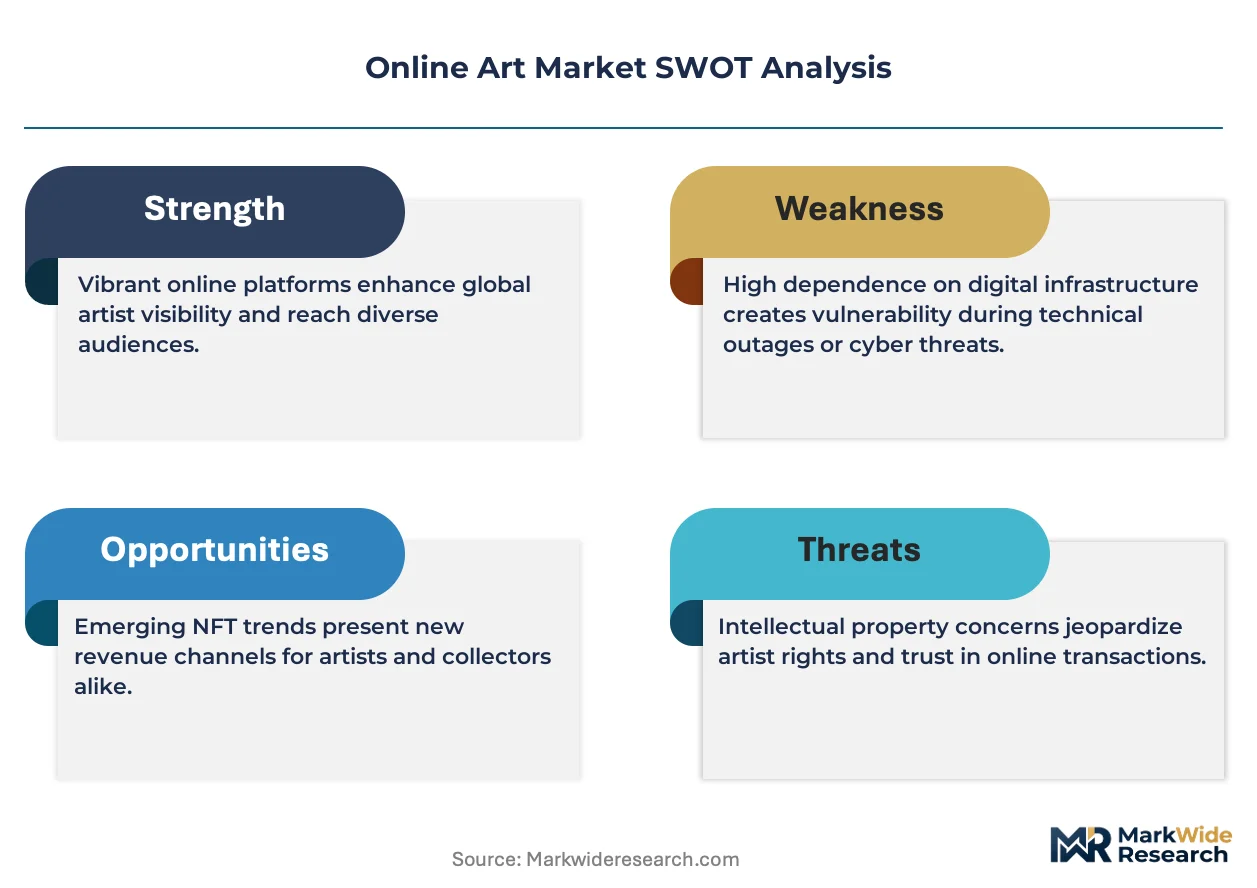
Blockchain-based provenance tracking is compressing authentication timelines and redistributing trust from physical inspection to cryptographic verification, forcing established auction houses to rebuild their value propositions around digital custody infrastructure.
Growth Catalysts
- Hospitality procurement expansion:Corporate art buyers and hotel groups are scaling digital art acquisition for property staging, creating volume demand that sustains platform liquidity.
- GDPR-compliant data frameworks:The EU's data protection rules have forced collector platforms to invest in privacy-first architecture, reducing buyer friction in European markets.
- Scarcity-engineered release models:Controlled drops with cryptographic edition limits concentrate collector attention and sustain secondary market velocity for digital works.
Market Restraints
- Authentication liability fragmentation:No unified legal framework governs disputes over AI-generated versus human-created works, exposing platforms to litigation risk.
- Collector platform concentration:Discovery and transaction infrastructure clusters among a handful of dominant marketplaces, creating single-point-of-failure vulnerability.
- Physical-digital arbitrage complexity:Buyers face persistent valuation gaps between screen-displayed works and their physical print substrates, complicating resale pricing.
Strategic Opportunities
- South Korean digital infrastructure:Seoul's government-backed metaverse initiatives and high smartphone penetration create a testbed for immersive art display technologies.
- Fractional ownership vehicles:Regulatory clarity from the SEC around investment structures could unlock retail capital currently blocked from direct high-value acquisition.
- AI-assisted curation convergence:Machine learning recommendation engines paired with blockchain provenance are enabling personalized discovery at scale previously impossible in physical galleries.
Industry Challenges
- Digital conservation expertise gap:Few conservators possess training in file format migration, display technology obsolescence, and blockchain wallet recovery for long-term collection stewardship.
- Cross-border tax classification ambiguity:Customs authorities in multiple jurisdictions apply inconsistent treatment to digital art imports, creating compliance overhead for international transactions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Art Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $38.98 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contemporary Art, Prints, Photography, Sculptures Sales Channel: Art Galleries, Online Auctions, Direct Sales, Marketplaces Customer Type: Collectors, Investors, Interior Designers, Art Enthusiasts Medium: Oil Painting, Digital Art, Watercolor, Mixed Media |
| Companies Covered | Saatchi Art, Artnet AG, Artsy, Christie's International, Sotheby's, Fine Art America, Artfinder, Invaluable, Auction Technology Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Art Market Evolving Landscape
Authentication infrastructure is becoming the primary battleground for competitive differentiation, with cryptographic verification methods replacing institutional reputation as the core trust mechanism in high-value transactions.
Non-fungible token standards with embedded royalty mechanisms are unifying primary sale and resale revenue streams for artists. Digital creators in the United States and United Kingdom are adopting these smart contract structures to capture ongoing value from secondary market activity. This technology is compressing the traditional gallery-artist economic relationship and enabling direct platform-to-creator monetization without intermediation.
The EU's AI Act is imposing transparency requirements on platforms hosting algorithmically generated works, forcing disclosure of training data provenance and human oversight protocols. European marketplaces must now implement content labeling systems that distinguish synthetic from authentic creative output. Contemporary and digital art segments face the steepest compliance costs as classification ambiguity persists around collaborative human-AI production models.
Collector purchasing patterns are fragmenting across multiple discovery channels rather than consolidating on single platforms. Interior designers and investment buyers now conduct parallel searches across curated marketplaces, social media discovery layers, and direct artist storefronts before transacting. This behavior is most pronounced in United States metropolitan markets where platform fatigue has reduced loyalty to any single venue.
Online Art Market Segmentation
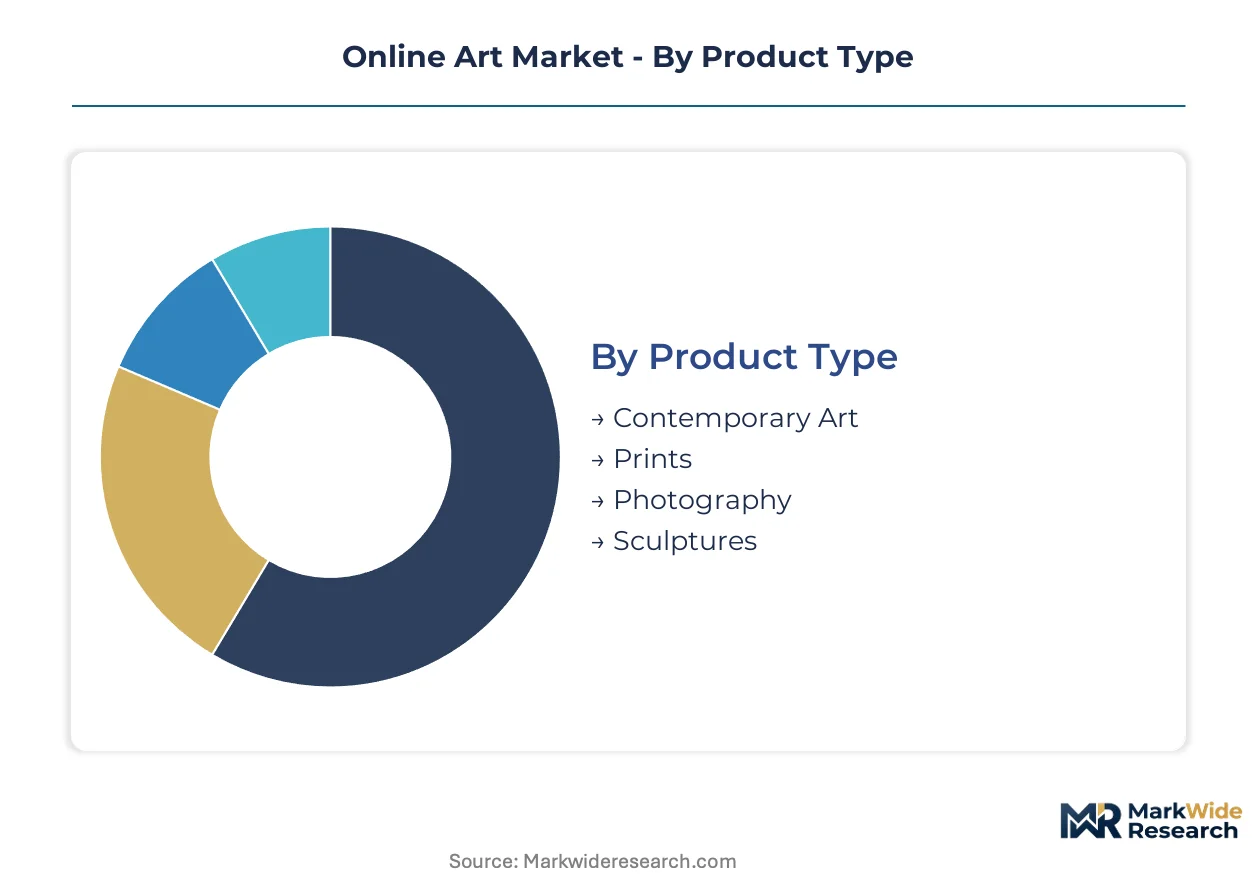
Online art segmentation reveals how authentication requirements, transaction infrastructure, and buyer sophistication stratify across product categories. Regulatory frameworks from the SEC to the EU AI Act impose distinct compliance burdens on specific segments, reshaping platform investment priorities and market entry barriers.
Product Type:
GDPR data handling requirements from the EU and SEC fractional investment rules in the United States create divergent compliance loads across product categories, with digital-native formats facing steeper transparency mandates than physical works.
- Contemporary Art:Works created from the late 20th century forward, encompassing painting, installation, and time-based media. Demand clusters among United States and United Kingdom collectors seeking provenance-verified pieces for portfolio diversification, constrained by authentication liability fragmentation around AI-assisted creation.
- Prints:Limited-edition reproductions on archival substrates, ranging from lithographs to digital inkjet outputs. Hospitality procurement in South Korea and corporate staging across United States metropolitan markets sustain volume liquidity, though physical-digital arbitrage complexity complicates resale valuation.
- Photography:Captured images delivered as digital files or physical prints. Blockchain-authenticated editions with embedded royalty mechanisms attract creator adoption in the United Kingdom.
- Sculptures:Three-dimensional works in traditional or mixed materials. Cross-border tax classification ambiguity elevates compliance overhead for international transactions.
Leading the category by volume: Prints. Growing fastest: Contemporary Art.
Sales Channel:
Channel selection determines which custody infrastructure investments platforms must prioritize, from cryptographic wallet systems for marketplaces to hybrid event technology for auction houses.
- Art Galleries:Curated physical spaces with online catalog extensions. United States and United Kingdom galleries rebuild value propositions around digital custody infrastructure as blockchain verification displaces institutional reputation.
- Online Auctions:Time-limited competitive bidding conducted through dedicated platforms. Controlled release strategies concentrate collector attention and sustain secondary market velocity.
- Direct Sales:Artist-to-buyer transactions without intermediary platforms. Higher per-transaction yields sustain established creators, particularly in contemporary and digital art segments.
- Marketplaces:Aggregated discovery and transaction infrastructure. AI-assisted curation convergence enables personalized discovery at scale in South Korean and United States markets.
Platform liquidity concentrates in marketplaces. Auction velocity accelerates fastest.
Customer Type:
Buyer sophistication tiers dictate service requirements, from GDPR-compliant data frameworks for European collectors to investment-grade custody for institutional capital.
- Collectors:Individuals acquiring works for personal stewardship. Fragmented discovery behavior across multiple channels reduces platform loyalty in United States metropolitan markets.
- Investors:Capital-deploying entities treating art as alternative assets. SEC regulatory clarity around fractional ownership vehicles could unlock retail capital currently blocked from direct high-value acquisition.
- Interior Designers:Commercial procurement agents sourcing for property staging. Hospitality groups scaling digital art acquisition create sustained volume demand.
- Art Enthusiasts:Entry-level buyers prioritizing accessibility over scarcity. Price-transparent platform access across geographies supports this segment's expansion.
Transaction frequency peaks with enthusiasts. Revenue per transaction peaks with investors.
Medium:
Technical preservation requirements and display infrastructure demands create diverging long-term stewardship obligations across material bases.
- Oil Painting:Traditional pigment-in-oil application on prepared substrates. Established conservation protocols and physical provenance systems dominate high-value transactions.
- Digital Art:Screen-native or blockchain-authenticated works with cryptographic ownership records. Seoul's government-backed metaverse initiatives create testbed demand for immersive display technologies.
- Watercolor:Water-soluble pigment on paper supports. Entry-level price accessibility sustains volume in print substrate displacement trends.
- Mixed Media:Combined material approaches including collage, assemblage, and hybrid physical-digital works. EU AI Act transparency requirements impose steepest compliance costs as classification ambiguity persists around collaborative human-AI production models.
Commercial volume concentrates in oil painting. Expansion trajectory steepest in digital art.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freeport zones and cultural enterprise districts in Seoul, London, and New York concentrate platform infrastructure and creator residency programs. Tax-advantaged art storage facilities in Geneva and Singapore anchor high-value custody operations. Government-backed digital asset initiatives in South Korea and the UAE accelerate immersive display technology deployment.
United States
Corporate procurement from hospitality groups and technology sector campuses sustains platform liquidity in New York and Los Angeles. SEC oversight of fractional art investment vehicles shapes compliance architecture for domestic platforms. Miami's cultural enterprise district hosts blockchain-authenticated edition drops that concentrate collector attention during seasonal art fairs.
United Kingdom
Photography and digital print collectors drive transaction velocity through London-based marketplaces. GDPR data handling requirements from the EU impose privacy-first architecture investments on platforms serving European buyers. The city's Mayfair gallery cluster rebuilds value propositions around cryptographic verification infrastructure rather than institutional reputation alone.
South Korea
Seoul's government-backed metaverse initiatives and high smartphone penetration create testbed demand for immersive art display technologies. The country's national consumer protection regulator enforces standards on domestic art e-commerce operators. Gangnam district galleries scale digital acquisition programs for property staging across hospitality developments.
Germany
Contemporary art investors in Berlin and Munich seek provenance-verified pieces for portfolio diversification. The EU AI Act imposes transparency requirements on platforms hosting algorithmically generated works, forcing disclosure protocols. Cologne's media art festivals drive adoption of blockchain-authenticated editions among institutional collectors.
United Arab Emirates
Dubai's freeport zones offer tax-advantaged art storage that anchors custody infrastructure for high-value digital works. The country's national consumer protection framework applies consistent treatment to digital asset classifications. Abu Dhabi's cultural district developments procure screen-native works for immersive property staging across hospitality portfolios.
Online Art Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with curated marketplaces commanding premium positioning against aggregator platforms. The vendor base clusters around three strategic archetypes: algorithm-driven discovery engines, hybrid auction houses with digital custody infrastructure, and direct-to-creator storefronts. Consolidation pressure concentrates among discovery-layer platforms as collector behavior fragments across multiple channels. Dominant competitive moves include strategic partnerships with blockchain custody providers and portfolio diversification into fractional ownership vehicles.
Within the heritage auction house tier, Christie's International and Sotheby's occupy positions that exemplify the shift toward cryptographic verification infrastructure. Saatchi Art represents the algorithm-driven discovery archetype among curated marketplaces. These three entities anchor the competitive structure through divergent approaches to artist-creator relationships and buyer acquisition economics.
| Leading Market Players |
|---|
| Saatchi Art |
| Artnet AG |
| Artsy |
| Christie's International |
| Sotheby's |
| Fine Art America |
| Artfinder |
| Invaluable |
| Auction Technology Group |
| Others |
Value Network & Pricing Analysis
EU AI Act transparency requirements for algorithmically generated works gate qualified supply access and premium-tier pricing power for compliant platforms serving European collectors.
Pricing Analysis
Short lead-time delivery of blockchain-authenticated editions commands premium positioning against spot inventory of unverified digital files. Three-tier pricing structure across cryptographic-verified premium, curator-attested standard, and open-edition economy levels separates buyer segments. Cost compression in the economy tier intensifies because generative AI tools flood entry-level supply. Hospitality procurement groups exhibit lowest price sensitivity; individual art enthusiasts show highest elasticity.
Supply Chain Analysis
Direct-to-creator storefronts handle established artist demand while aggregated marketplaces manage discovery-layer volume. Digital file storage infrastructure concentrates in the United States, United Kingdom, and South Korea. Archival substrate printing draws from specialized paper mills in Germany and Japan; cryptographic wallet services rest on cloud providers in Ireland and Singapore. Single-source vulnerability in blockchain custody providers elevates platform risk. Distribution runs through hybrid physical-digital channels with localized print fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act creates a barrier-to-entry moat where compliance investment separates viable platforms from marginal operators, concentrating returns among architecture-ready incumbents.
For Market Incumbents: Anticipate authentication liability fragmentation by building in-house cryptographic verification infrastructure rather than outsourcing custody. Secure exclusive partnerships with blockchain custody providers before regulatory clarity hardens supplier relationships. Vertical integration into artist residency programs locks creator supply against emerging platform competitors. For New Entrants and Emerging Players: Begin with South Korea's immersive display technology segment where government metaverse initiatives subsidize early deployment costs. Target interior designer procurement workflows in United States metropolitan markets where platform fatigue has reduced loyalty to incumbents. Lead with AI-assisted curation tools that personalize discovery at scale without legacy technical debt. For Investors and Strategic Acquirers: SEC guidance on fractional art investment vehicles is the leading indicator that retail capital will flood compliant platforms, revaluing early movers. Platforms with GDPR-compliant data frameworks and established European collector bases represent priority acquisition targets. Watch for consolidation signals when discovery-layer platforms report sustained customer acquisition cost inflation.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Custody Partnership | Christie's and Sotheby's anchor competitive positioning through exclusive cryptographic verification infrastructure. |
| AI-Assisted Curation Deployment | Saatchi Art leverages machine learning recommendation engines to sustain artist-discovery algorithm differentiation. |
| GDPR-Compliant Architecture Investment | European market access requires privacy-first data handling that compliant platforms have already operationalized. |
| Fractional Ownership Vehicle Development | Regulatory clarity from the SEC would unlock retail capital currently blocked from direct high-value acquisition. |
| Immersive Display Technology Pilot | Seoul's government-backed metaverse initiatives create subsidized testbed demand for screen-native art presentation. |
Research Methodology
Document review covered SEC filings, EU regulatory submissions, and art marketplace transaction databases, complemented by interviews with platform executives, gallery directors, blockchain custody providers, and hospitality procurement officers. Secondary sources included customs records, cultural enterprise district development filings, and contemporary art auction catalogs. Bottom-up transaction volume estimates triangulated against top-down market sizing from platform revenue disclosures.
Output metrics span product type, sales channel, customer sophistication tier, and medium-specific preservation requirements across the projection horizon. CAGRs derive from regression analysis of historical transaction velocity against platform infrastructure investment cycles. Forecast inputs incorporate blockchain adoption curves and regulatory implementation timelines without assuming specific enforcement dates.
Underlying measurement precision varies by segment; digital-native formats carry tighter precision than physical-digital hybrid categories where cross-border tax classification ambiguity persists. Forecasts reflect assumptions around regulatory clarity timelines and authentication technology standardization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Video Wall Market
Digital Media
China Webtoons Market
Digital Media
Global Playout Automation and Channel in a Box Market
Digital Media
Europe Inflight Entertainment and Connectivity Market
Digital Media
ACGN Subculture Market
Digital Media
4K Content Market
Digital Media
North America Photographic Services Market
Digital Media
Entertainment Market
Digital Media
Europe Online Video Platform Market
Digital Media
Anime Derivatives Market
Digital Media
Digital Entertainment in the Home Market
Digital Media
Adult Animation Market
Digital Media
Playout Solutions Market
Digital Media
Animation Services Market
Digital Media
Online Gambling Market
Digital Media
LED Stadium Screens Market