
 Middle East and Africa Inflight Entertainment and Connectivity Market | 2026-2036
Middle East and Africa Inflight Entertainment and Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Inflight Entertainment and Connectivity Market Insights
Business aviation is expanding its share of the Middle East and Africa Inflight Entertainment and Connectivity Market as corporate operators retrofit existing fleets with streaming-capable systems. Thales Group leverages its satellite connectivity portfolio to anchor long-haul contracts with Gulf-based flag carriers. Gogo Inc. competes in the business aviation segment through specialized air-to-ground hardware optimized for regional density gaps. Viasat Inc. dominates Ka-band capacity deployment across African trunk routes where terrestrial infrastructure remains sparse.
Inflight entertainment and connectivity encompasses the integrated hardware, software, and network services that deliver audio-visual content, internet access, and real-time communications to aircraft occupants during flight, typically operating through Ku-band or Ka-band satellite links with latency thresholds under 700 milliseconds for acceptable passenger experience. The primary commercial purpose centers on passenger satisfaction metrics, crew operational efficiency, and ancillary revenue generation through tiered service monetization. Wireless IFE systems lead product-type deployment in narrowbody retrofit programs across the region due to lower certification burden and faster installation cycles. Satellite Connectivity technology anchors the technology segment as GEO and LEO constellation investments reshape bandwidth economics for over-ocean and remote-terrain routes. Streaming Services within the delivery mode dimension capture expanding margin pools as airlines shift from capital-intensive seatback hardware toward bring-your-own-device content platforms.
The General Civil Aviation Authority of the United Arab Emirates and the South African Civil Aviation Authority enforce equipment certification standards that shape supplier qualification timelines and retrofit scheduling. Saudi Arabia's Communications and Information Technology Commission coordinates spectrum allocation for in-flight connectivity, directly influencing which satellite operators and hardware vendors gain market access. The European Union Aviation Safety Agency's design approval requirements extend into North African operator fleets through bilateral recognition agreements, adding compliance layers for suppliers. Stakeholders must monitor LEO constellation coverage expansion and corresponding regulatory harmonization across the Gulf Cooperation Council to anticipate bandwidth cost inflection points and fleet upgrade cycles.
Market Dynamics
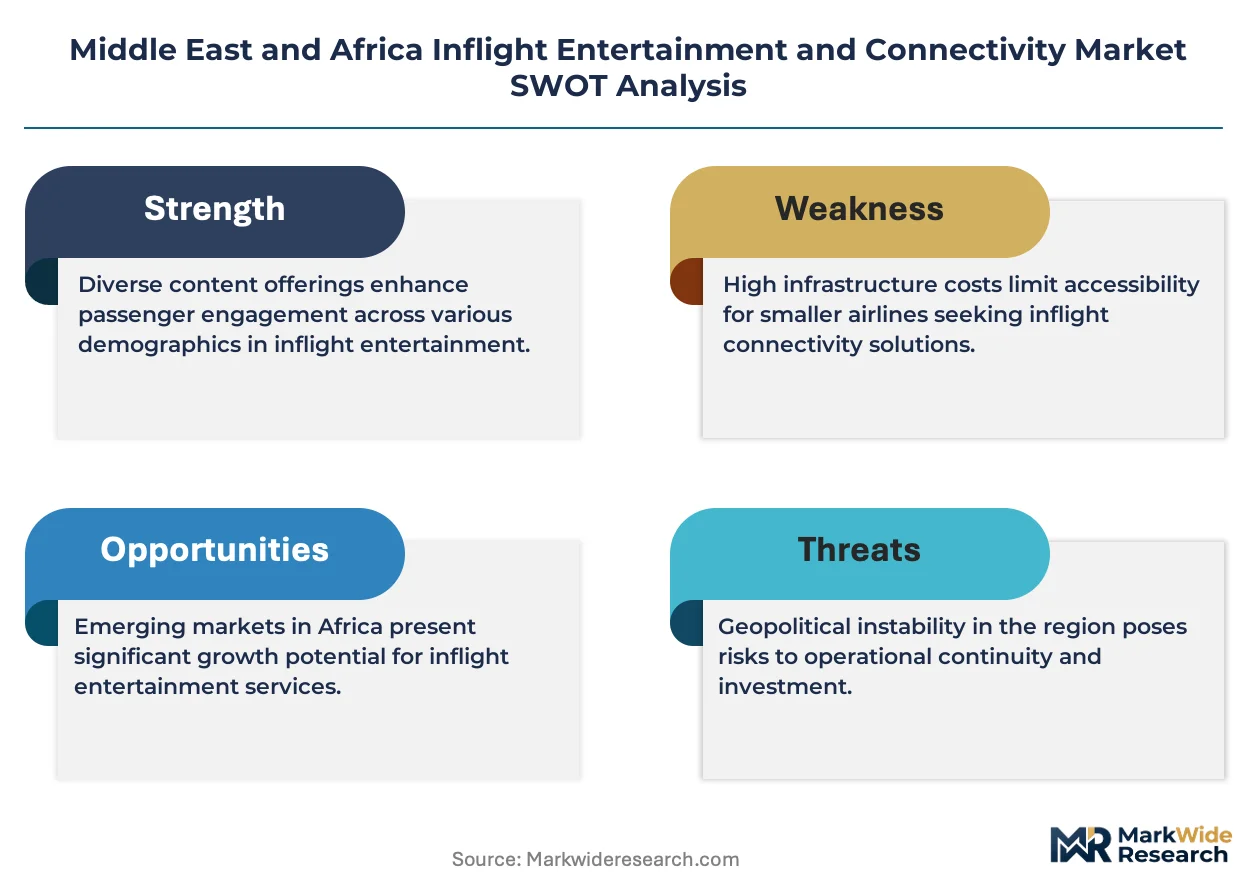
Satellite bandwidth cost deflation is compressing service provider margins while expanding addressable fleet coverage across Gulf Cooperation Council flag carriers and African trunk operators. This price erosion is electrifying retrofit cycles for narrowbody fleets previously excluded from connectivity economics.
Growth Catalysts
- Spectrum liberalization frameworks:South Africa's communications regulator and Nigeria's spectrum authority have accelerated air-to-ground network approvals, reducing deployment timelines for regional operators.
- Ka-band capacity expansion:High-throughput satellite deployments over African trunk routes are eliminating coverage dead zones that previously forced aircraft onto expensive roaming agreements.
- Bring-your-own-device platforms:Airlines across the United Arab Emirates and Saudi Arabia are shifting capital expenditure from seatback hardware toward streaming-capable wireless systems.
Market Restraints
- Geostationary satellite latency:Round-trip signal delays above 500 milliseconds degrade real-time applications, limiting premium service tiering for business aviation clients.
- Equipment certification bottlenecks:The General Civil Aviation Authority of the United Arab Emirates and South African Civil Aviation Authority impose extended qualification timelines that compress retrofit scheduling windows.
- Terrestrial infrastructure substitution:Ground-based 5G networks in dense Middle Eastern urban corridors threaten short-haul connectivity demand for domestic routes.
Strategic Opportunities
- Low Earth orbit constellation integration:LEO satellite mesh architectures promise sub-100 millisecond latency, enabling latency-sensitive applications previously impossible over geostationary links.
- Business aviation retrofit demand:Corporate operators across the Gulf Cooperation Council are retrofitting existing fleets with streaming-capable systems, creating a secondary equipment market distinct from airline original equipment.
- Saudi Arabia's regulatory coordination:The Communications and Information Technology Commission's spectrum allocation processes are creating preferential market access for early-mover satellite operators and hardware vendors.
Industry Challenges
- Legacy system integration complexity:Narrowbody retrofit programs must reconcile new wireless IFE architectures with existing avionics buses and power distribution frameworks.
- Certified installation technician scarcity:The specialized workforce required for Supplemental Type Certificate modifications concentrates in Dubai and Johannesburg, creating geographic bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Inflight Entertainment and Connectivity Market |
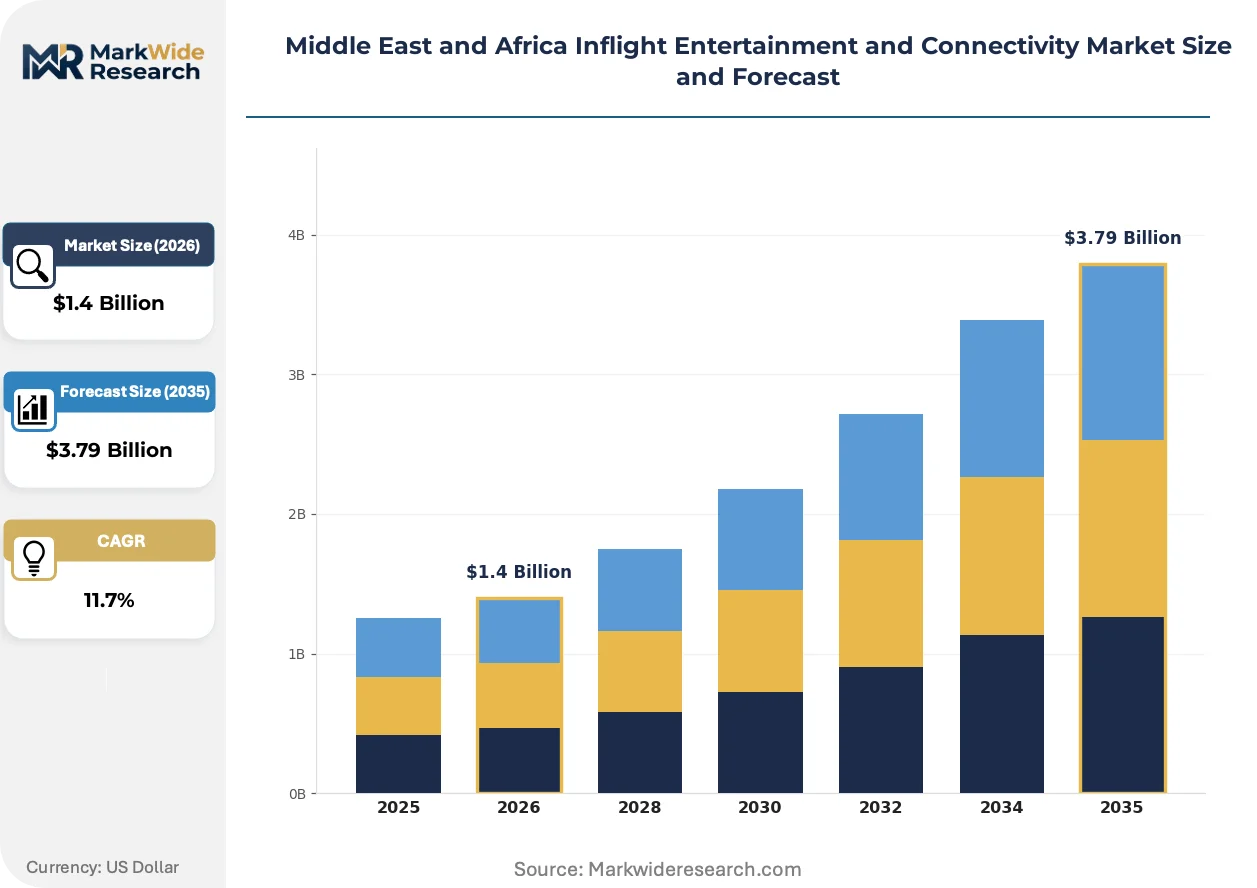
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.79 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless IFE, Seatback IFE, Connectivity Systems, Streaming Services Technology: Satellite Connectivity, Air-to-Ground, Wi-Fi, In-Flight Broadband End User: Airlines, Charter Services, Military, Business Aviation Delivery Mode: Online, Offline, Hybrid, Subscription |
| Companies Covered | Gogo Inc., Thales Group, Panasonic Corporation, Viasat Inc., Inmarsat plc, Burrana Inc., Emirates Group, Qatar Airways Group, Saudi Arabian Airlines Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Inflight Entertainment and Connectivity Market Trends and Innovations
Connectivity architecture decisions are migrating from IT procurement to executive-level fleet strategy as passenger satisfaction metrics hardwire into carrier brand positioning. Three developments are compressing technology refresh cycles and reshaping supplier relationships.
Wireless IFE distribution is electrifying narrowbody cabin retrofits across Middle Eastern low-cost carriers. These systems eliminate seatback screen weight and maintenance burden while enabling personalized content delivery to passenger devices. Airlines in Saudi Arabia and the United Arab Emirates are completing 48-hour installation cycles that previously required week-long hangar stays.
The European Union Aviation Safety Agency's design approval requirements extend into North African operator fleets through bilateral recognition agreements with Morocco, Egypt, and Tunisia. This regulatory harmonization is compressing supplier qualification timelines for equipment vendors seeking multi-territory certification. Hardware manufacturers are consolidating testing protocols to satisfy both EASA standards and Gulf Cooperation Council national aviation authorities.
Service unbundling is fragmenting traditional connectivity procurement. Airlines are separating bandwidth contracts from hardware provision and content licensing, creating discrete vendor relationships rather than single-source system integration. This pattern concentrates in the United Arab Emirates and Qatar, where procurement teams possess technical sophistication to manage multi-party service orchestration.
Middle East and Africa Inflight Entertainment and Connectivity Market Segmentation
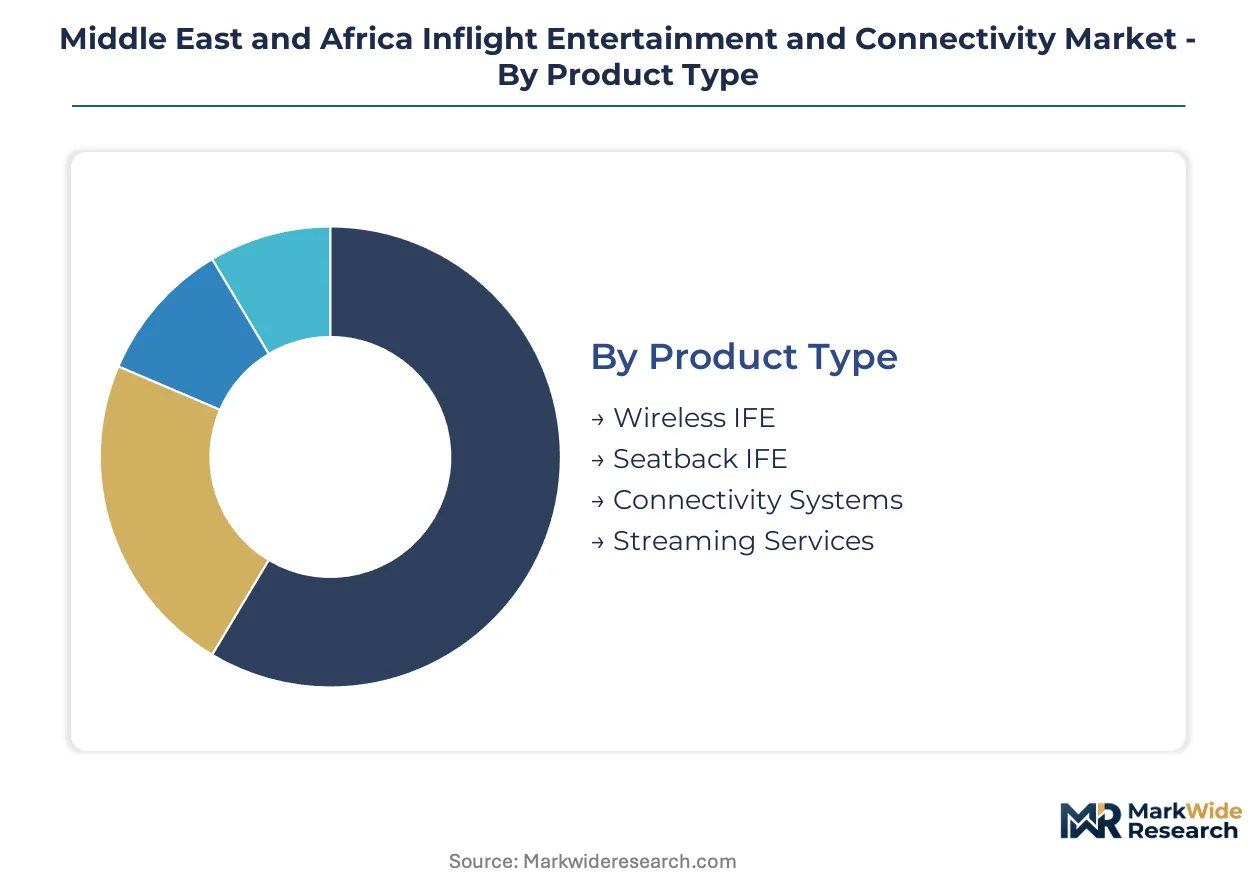
Segmentation in the Middle East and Africa Inflight Entertainment and Connectivity Market reveals how certification requirements, bandwidth economics, and fleet modernization priorities reshape supplier strategies across distinct equipment categories and service models.
Product Type:
The General Civil Aviation Authority of the United Arab Emirates and South African Civil Aviation Authority impose differentiated certification timelines across hardware architectures, with wireless systems clearing faster than seatback installations.
- Wireless IFE:Distributed content delivery via cabin Wi-Fi networks eliminates seatback screen weight and maintenance burden. Demand concentrates in Saudi Arabian and UAE low-cost carriers completing 48-hour installation cycles that previously required week-long hangar stays, driven by narrowbody retrofit economics.
- Seatback IFE:Integrated display and control units at each passenger position deliver premium content experiences with dedicated power and audio infrastructure. UAE and Qatar flag carriers anchor demand for these capital-intensive systems, treating seatback density as a brand differentiator on long-haul routes.
- Connectivity Systems:Satellite and air-to-ground transceiver hardware enabling internet access, certified under GCAA and SACAA equipment standards.
- Streaming Services:Content licensing and platform delivery shifting airline capex toward opex models across Gulf Cooperation Council fleets.
Leading the category by volume: Wireless IFE. Growing fastest: Streaming Services.
Technology:
Cost tier separation between geostationary satellite capacity and emerging low-earth orbit alternatives is restructuring procurement patterns for bandwidth-intensive applications.
- Satellite Connectivity:Ku-band and Ka-band links via geostationary and emerging LEO constellations deliver over-ocean and remote-terrain coverage. Viasat Inc. anchors Ka-band deployment across African trunk routes where terrestrial infrastructure remains sparse, with Nigerian and South African operators prioritizing high-throughput satellite to eliminate roaming dead zones.
- Air-to-Ground:Cellular tower networks provide lower-altitude connectivity for domestic corridors. TRAI-equivalent frameworks in South Africa and Nigeria are accelerating regulatory approvals, compressing deployment timelines for regional operators previously blocked by spectrum allocation delays.
- Wi-Fi:Cabin distribution infrastructure enabling passenger device connectivity, standard across retrofit programs.
- In-Flight Broadband:High-speed data services supporting streaming and real-time applications, expanding with LEO constellation integration.
Highest capex concentration: Satellite Connectivity. Steepest expansion trajectory: Air-to-Ground.
End User:
Customer type determines service tier architecture, with business aviation demanding sub-100 millisecond latency unavailable to commercial airline procurement.
- Airlines:Full-service and low-cost carriers operating scheduled passenger services. Gulf Cooperation Council flag carriers treat connectivity as core service differentiation, embedding passenger satisfaction metrics into fleet strategy rather than ancillary revenue optimization.
- Business Aviation:Corporate and private aircraft operators requiring specialized installation. Retrofit demand concentrates across UAE and Saudi Arabia as corporate operators upgrade existing fleets with streaming-capable systems, creating equipment market distinct from airline original equipment.
- Charter Services:On-demand passenger operators balancing equipment cost against competitive positioning.
- Military:Government and defense aircraft with hardened connectivity requirements and separate certification pathways.
Largest installed base: Airlines. Fastest-climbing investment: Business Aviation.
Delivery Mode:
Margin structure varies sharply between capital-heavy hardware ownership and recurring subscription revenue, driving unbundling of traditional single-source procurement.
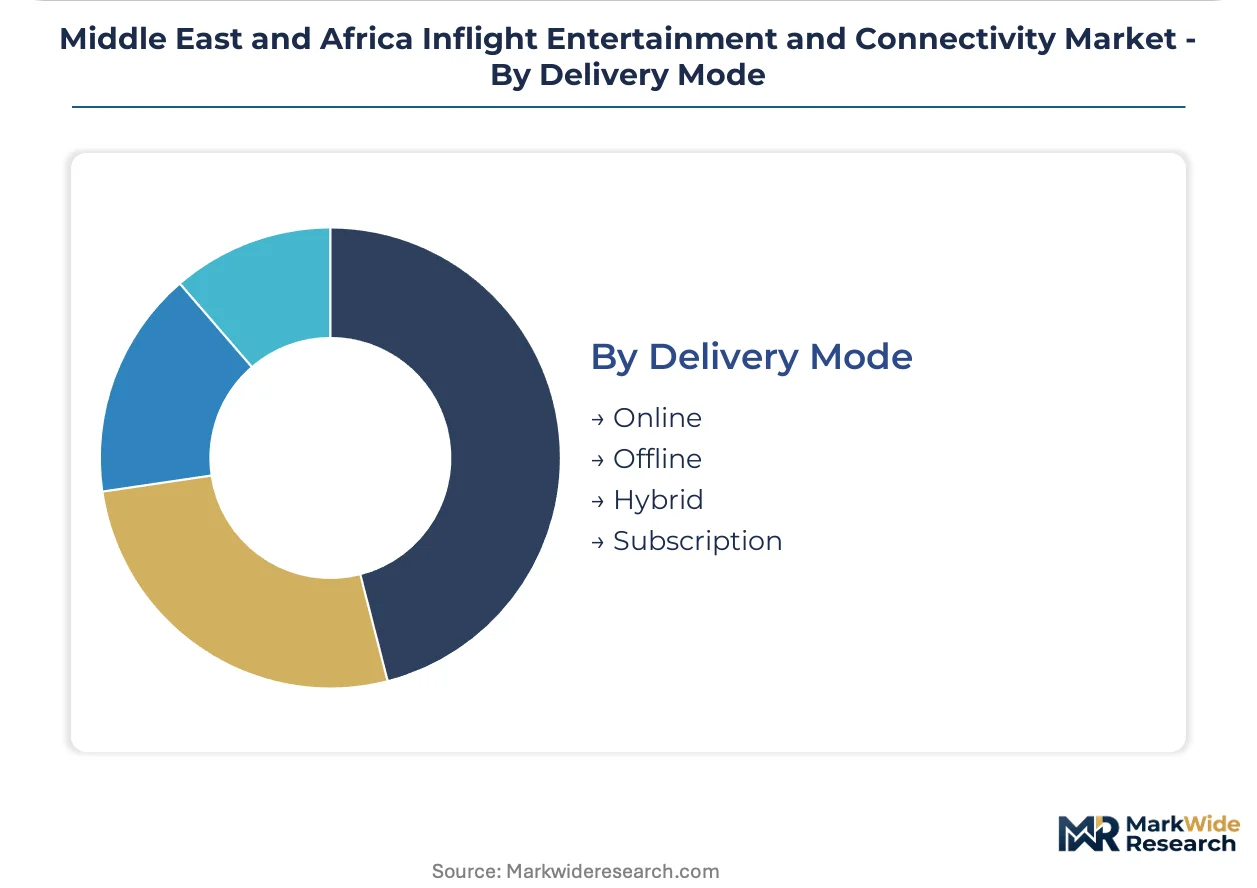
- Online:Continuous connectivity services billed per flight or data volume. UAE and Qatar procurement teams are separating bandwidth contracts from hardware provision, managing multi-party service orchestration with technical sophistication unavailable to smaller African operators.
- Hybrid:Combined offline content caching with intermittent connectivity bursts. Saudi Arabian low-cost carriers favor this architecture for regional routes with intermittent satellite coverage, optimizing cost against passenger experience thresholds.
- Offline:Pre-loaded content delivery without real-time connectivity, residual demand in price-sensitive segments.
- Subscription:Recurring passenger or airline service fees, emerging as preferred monetization for bring-your-own-device platforms.
Dominant revenue model: Online. Gaining share fastest: Hybrid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Gulf Cooperation Council aviation hubs, while African trunk routes rely on satellite coverage where terrestrial infrastructure remains sparse. Fleet retrofit cycles accelerate as bandwidth economics improve across both regions.
United Arab Emirates
Dubai and Abu Dhabi flag carriers treat passenger connectivity as core brand differentiation, embedding fleet-wide streaming systems into long-haul operations. The General Civil Aviation Authority enforces equipment certification standards that compress supplier qualification timelines for hardware vendors. Dubai International Airport anchors the region's largest retrofit technician cluster, where 48-hour wireless IFE installation cycles now replace week-long hangar stays.
Saudi Arabia
Saudi Arabian Airlines Group and emerging low-cost operators are shifting capital expenditure from seatback hardware toward bring-your-own-device platforms across narrowbody fleets. The Communications and Information Technology Commission coordinates spectrum allocation for in-flight connectivity, creating preferential market access for satellite operators. Riyadh and Jeddah maintenance facilities concentrate certified installation capacity for Supplemental Type Certificate modifications.
South Africa
Domestic operators prioritize air-to-ground network deployment for coastal and Johannesburg-Cape Town corridors as spectrum frameworks accelerate regulatory approvals. The country's communications regulator has reduced deployment timelines previously blocked by allocation delays. Cape Town hosts specialized avionics integration facilities serving sub-Saharan retrofit demand.
Nigeria
Lagos-based carriers leverage high-throughput satellite capacity to eliminate roaming dead zones across West African trunk routes. TRAI-equivalent spectrum authority frameworks now permit faster air-to-ground network approvals than previous regulatory regimes allowed. Murtala Muhammed International Airport concentrates regional maintenance capabilities for connectivity hardware installation.
Qatar
Qatar Airways Group procurement teams possess technical sophistication to manage multi-party service orchestration, separating bandwidth contracts from hardware provision. The country's civil aviation authority aligns certification requirements with Gulf Cooperation Council harmonization protocols. Doha maintenance, repair and overhaul facilities specialize in business aviation retrofit programs for streaming-capable systems.
Middle East and Africa Inflight Entertainment and Connectivity Market Competitive Landscape
Top-tier vendors anchor long-haul fleet contracts across Gulf flag carriers, while specialized air-to-ground hardware providers compete for regional density gaps. The vendor base stratifies between satellite bandwidth aggregators, wireless IFE system integrators, and business aviation retrofit specialists. Three archetypes dominate: full-service system integrators, component specialists, and airline-affiliated technology divisions. Competitive moves concentrate on strategic partnerships with constellation operators and geographic expansion into African trunk route coverage.
Among satellite connectivity specialists, Viasat Inc. and Inmarsat plc occupy positions anchoring Ka-band and LEO constellation deployment across African routes where terrestrial infrastructure remains sparse. Thales Group exemplifies the full-service system integrator archetype, leveraging aerospace and defense heritage for long-haul contracts with Gulf-based flag carriers. Gogo Inc. represents the business aviation-focused tier, competing through specialized hardware optimized for regional density gaps and corporate retrofit demand.
| Leading Market Players |
|---|
| Gogo Inc. |
| Thales Group |
| Panasonic Corporation |
| Viasat Inc. |
| Inmarsat plc |
| Burrana Inc. |
| Emirates Group |
| Qatar Airways Group |
| Saudi Arabian Airlines Group |
| Others |
Pricing and Supply Chain Analysis
Satellite bandwidth costs cascade through equipment procurement decisions, compressing service provider margins while expanding fleet coverage economics for Gulf Cooperation Council flag carriers and African trunk operators. This input-cost deflation reshapes tiered pricing structures across connectivity systems, wireless IFE hardware, and streaming platform subscriptions as buyers shift from capital-intensive seatback installations toward operational expenditure models.
Pricing Analysis
Margin tightening in connectivity services reflects satellite capacity oversupply from GEO and LEO constellation expansion. Three-tier pricing structure across premium streaming, standard browsing, and economy messaging tiers differentiates service levels based on bandwidth allocation and latency performance. Cost compression accelerates as airlines unbundle hardware from bandwidth contracts, with low-cost carriers exhibiting highest price sensitivity while business aviation clients absorb premium rates for sub-100 millisecond latency guarantees.
Supply Chain Analysis
Certified installation technician scarcity in Dubai and Johannesburg concentrates final assembly capacity for Supplemental Type Certificate modifications. Hardware manufacturing draws from aerospace electronics clusters in France, the United States, and Singapore, with Ku-band and Ka-band transceiver components sourced from specialized satellite communications foundries. Single-source vulnerability persists in LEO constellation terminal supply where qualified vendors remain limited. Distribution runs through airline procurement teams, MRO facilities, and direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around bandwidth aggregators and system integrators capable of managing multi-party service orchestration as satellite cost deflation eliminates pure-play hardware margins. Equipment certification bottlenecks and specialized workforce scarcity force weaker component vendors toward acquisition or exit.
For Market Incumbents: Anticipate LEO constellation integration requirements by securing early-mover terminal certification with the General Civil Aviation Authority of the United Arab Emirates and South African Civil Aviation Authority. Vertical integration into streaming content licensing protects margin pools as hardware commoditization accelerates. Defensive consolidation of wireless IFE installation capacity in Dubai and Johannesburg locks out emerging competitors facing workforce scarcity. For New Entrants and Emerging Players: Business aviation retrofit demand across Saudi Arabia and Qatar offers the most penetrable entry vector, with corporate operators seeking streaming-capable systems distinct from airline procurement cycles. Narrowbody low-cost carriers in North Africa present secondary white-space where EASA bilateral recognition agreements compress supplier qualification timelines. Go-to-market positioning as LEO-first connectivity specialists bypasses incumbents' geostationary satellite legacy investments. For Investors and Strategic Acquirers: LEO constellation coverage expansion over African trunk routes is the leading indicator that bandwidth economics will displace remaining air-to-ground dominance in domestic corridors. Long-term viability centers on platform orchestration capabilities rather than hardware manufacturing scale. Acquisition targets include wireless IFE system integrators with GCAA and SACAA certification credentials and established MRO channel relationships. Material deviation in spectrum allocation timelines across Gulf Cooperation Council jurisdictions warrants reassessment of regional market access assumptions.| Strategic Initiative | Industry Significance |
|---|---|
| LEO Constellation Partnership | Sub-100 millisecond latency unlocks business aviation premium pricing previously unavailable over geostationary links. |
| Wireless IFE Certification Acceleration | 48-hour installation cycles with GCAA approval compress retrofit scheduling against seatback system competitors. |
| Spectrum Allocation Coordination | Saudi Arabia's CITC preferential access creates regulatory moats for early-mover satellite operators and hardware vendors. |
| MRO Capacity Consolidation | Dubai and Johannesburg technician clusters control narrowbody retrofit throughput across Middle East and Africa. |
| Content Licensing Platform | Streaming service unbundling shifts airline capex toward recurring opex with higher lifetime value capture. |
Research Methodology
Regulatory filings from the General Civil Aviation Authority of the United Arab Emirates, South African Civil Aviation Authority, and Saudi Communications and Information Technology Commission formed the secondary backbone for certification timeline and spectrum allocation analysis. Primary interviews with fleet procurement directors at Gulf Cooperation Council flag carriers, avionics integration engineers at Dubai and Johannesburg MRO facilities, and satellite bandwidth procurement managers informed equipment deployment patterns and pricing dynamics. Trade customs data, airline fleet modernization disclosures, and constellation operator coverage maps supplied volume and value triangulation against bottom-up installation estimates.
Historical trendline analysis of narrowbody retrofit cycles, satellite bandwidth cost deflation rates, and regulatory approval velocity established baseline growth trajectories across the projection horizon. The analytical framework modeled segmentation dimensions spanning product type, connectivity technology, end-user category, and delivery mode with regional regulatory cluster overlays. CAGRs derived from fleet commitment announcements, equipment order backlogs, and bandwidth contract disclosures. Forecast inputs incorporated LEO constellation launch schedules and air-to-ground network deployment timelines across South Africa and Nigeria.
Revisions become necessary when LEO constellation coverage expansion delays, spectrum reallocation decisions, or equipment certification standard changes materialize beyond modeled assumptions. Forecasts reflect documented stakeholder input and secondary data cross-references without claiming predictive certainty. Material deviation in satellite launch schedules, regulatory harmonization progress, or airline fleet restructuring warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Digital Music Services Market
Digital Media
Online Movie Market
Digital Media
Sports Graphics Market
Digital Media
Anime Market
Digital Media
China Webtoons Market
Digital Media
In Flight Entertainment Market
Digital Media
VFX Market
Digital Media
Asia Pacific Photography Service Market
Digital Media
Video Wall Market
Digital Media
Digital Media Switchers Market
Digital Media
Stock Photography Market
Digital Media
LED Stadium Screens Market
Digital Media
Anime Merchandising Market
Digital Media
Online Gambling Market
Digital Media
Europe Animation, VFX and Post Production Market
Digital Media
Video Production Market