
 Media Advertising in Southeast Asia Market | 2026-2036
Media Advertising in Southeast Asia Market Size, Share, and Industry Trends Forecast 2026-2036
Media Advertising in Southeast Asia Market Insights
IAB Southeast Asia's digital certification is collapsing as a gatekeeping standard for programmatic traders and ad-tech vendors across the region. GroupM Asia Pacific Holdings Ltd. leverages its centralized trading desk to secure premium inventory across Indonesia and Thailand. Dentsu International Asia Pte. Ltd. anchors its competitive position through deep creative-production integration in Tokyo and Singapore hubs. Omnicom Media Group Asia Pacific Pte. Ltd. competes by embedding data science teams directly inside client marketing organizations.
Media advertising in Southeast Asia encompasses paid message placement across digital, print, broadcast, and outdoor channels to influence consumer purchase decisions, with programmatic algorithms now executing over half of all digital transactions through real-time bidding protocols. The primary commercial purpose is to allocate brand communication budgets toward measurable audience attention outcomes rather than proxy metrics like circulation or ratings. Digital ad formats command the dominant share of regional spend as mobile-first consumption patterns in Indonesia and Vietnam displace legacy broadcast allocations. Outdoor advertising is experiencing structural renewal through transit-oriented digital screen networks in Bangkok, Manila, and Kuala Lumpur, where JCDecaux Singapore Pte. Ltd. and VGI Global Media Public Co. Ltd. occupy prime concession contracts.
Singapore's Personal Data Protection Commission and the Philippines' National Privacy Commission enforce consent-based frameworks that restrict third-party data deployment without explicit user authorization, compelling advertisers to build first-party data infrastructure. Thailand's Personal Data Protection Act and Indonesia's forthcoming data protection regulations extend similar compliance burdens across the Mekong sub-region and the archipelago. Vietnam's Ministry of Information and Communications maintains content licensing requirements for foreign digital platforms that alter market access conditions for cross-border ad-tech providers. Stakeholders must monitor how fragmented data sovereignty rules across ASEAN reshape platform economics and media buying workflows.
Market Dynamics
Programmatic real-time bidding protocols now execute the majority of digital transactions across Indonesia, Vietnam, and Thailand, compressing traditional media-buying workflows and collapsing intermediation margins for non-certified traders.
Growth Catalysts
- Mobile-first consumption patterns:Indonesian and Vietnamese consumers now spend more daily hours on smartphones than television, redirecting brand budgets toward in-app and mobile web inventory. Advertisers capture measurable attention metrics rather than proxy reach estimates.
- Transit-oriented digital screen networks:Bangkok, Manila, and Kuala Lumpur are deploying connected out-of-home infrastructure along mass rapid transit corridors. JCDecaux Singapore Pte. Ltd. and VGI Global Media Public Co. Ltd. hold prime concession contracts in these metropolitan clusters.
- Personal Data Protection Act enforcement:Thailand's consent-based framework is compelling advertisers to build first-party data infrastructure. Brands investing in customer data platforms gain targeting precision while competitors face operational disruption.
Market Restraints
- Consent framework fragmentation:Singapore's Personal Data Protection Commission and the Philippines' National Privacy Commission impose divergent explicit authorization requirements. Cross-border campaigns face compliance complexity that inflates legal and technical overhead.
- Platform licensing restrictions:Vietnam's Ministry of Information and Communications maintains content licensing requirements for foreign digital platforms. Cross-border ad-tech providers encounter market access friction that limits inventory liquidity.
- Certification standard erosion:IAB Southeast Asia's digital certification is losing gatekeeping authority for programmatic traders. Talent quality variability rises as unqualified operators enter auction-based buying environments.
Strategic Opportunities
- First-party data infrastructure:Indonesia's forthcoming data protection regulations will mirror ASEAN consent frameworks. Early movers in Jakarta and Surabaya can establish proprietary audience graphs before compliance mandates tighten.
- E-commerce platform budgets:Shopee, Lazada, and Tokopedia sellers across Indonesia, Malaysia, and Vietnam are expanding performance marketing allocations. Retail media networks capture closed-loop attribution that brand advertisers covet.
- Creative-production integration:Tokyo and Singapore hubs demonstrate how co-located data science and creative teams compress campaign iteration cycles. Regional advertisers can replicate this model to accelerate dynamic creative optimization.
Industry Challenges
- Programmatic talent scarcity:Certified traders with cross-platform expertise remain concentrated in Singapore and Bangkok. Indonesian and Vietnamese operations face recruitment bottlenecks that delay auction-based buying capability builds.
- Legacy broadcast integration:National television networks in the Philippines and Thailand maintain residual audience share among older demographics. Unified planning across linear and digital channels requires workflow redesign that many agencies have not completed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Media Advertising in Southeast Asia Market |
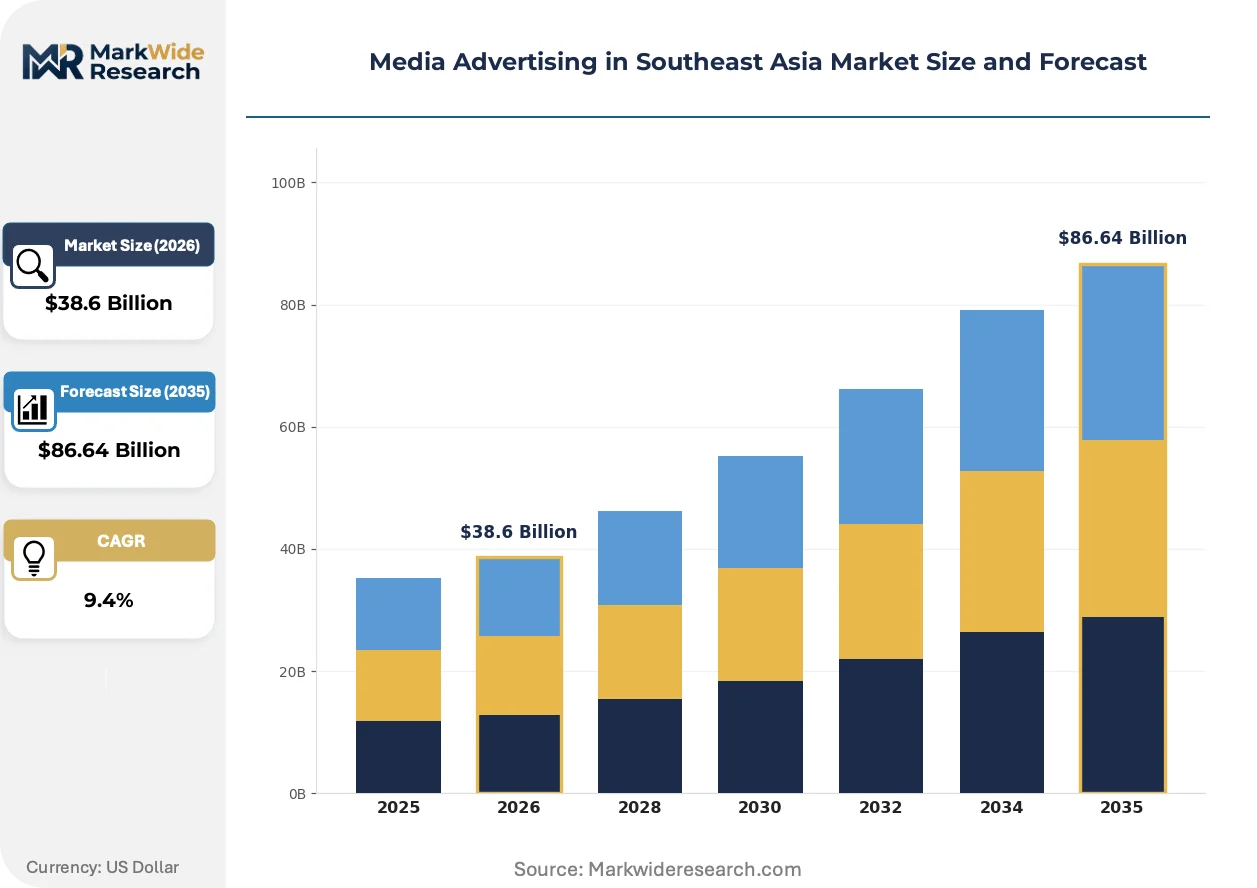
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $86.64 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ad Format: Digital, Print, Broadcast, Outdoor Industry Vertical: Retail, Automotive, Healthcare, Technology Platform Type: Social Media, Search Engines, Websites, Television Target Audience: Millennials, Gen Z, Professionals, Families |
| Companies Covered | Dentsu International Asia Pte. Ltd., GroupM Asia Pacific Holdings Ltd., Omnicom Media Group Asia Pacific Pte. Ltd., Publicis Groupe SA, Havas Media Asia Pacific Pte. Ltd., IPG Mediabrands Singapore Pte. Ltd., JCDecaux Singapore Pte. Ltd., Clear Channel Singapore Pte. Ltd., VGI Global Media Public Co. Ltd., Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Media Advertising in Southeast Asia Market Trends and Innovations
Artificial intelligence is restructuring how Southeast Asian advertisers plan, execute, and measure campaigns. Three developments merit particular attention.
Retail media networks is supplanting open-web programmatic as the preferred performance channel for consumer brands. Shopee and Lazada marketplace sellers in Indonesia and Vietnam are redirecting search and display budgets toward on-platform sponsored placements. Closed-loop transaction data enables attribution precision that third-party cookies never delivered, compressing media mix modeling cycles from quarterly to weekly.
Singapore's Personal Data Protection Commission is tightening consent granularity requirements for cross-context behavioral targeting. Advertisers must now obtain separate authorizations for audience segmentation, lookalike modeling, and measurement pixel deployment. Financial services and healthcare verticals in the city-state face the steepest compliance burden, prompting accelerated investment in customer data platform infrastructure.
Out-of-home inventory procurement is fragmenting across direct publisher relationships, programmatic guaranteed deals, and automated guaranteed platforms. Transit authorities in Bangkok and Manila are unbundling concession contracts to enable shorter-term, data-driven placements. Real estate developers and quick-service restaurant chains now optimize location-based creative rotation based on foot traffic sensors rather than static flight schedules.
Media Advertising in Southeast Asia Market Segmentation
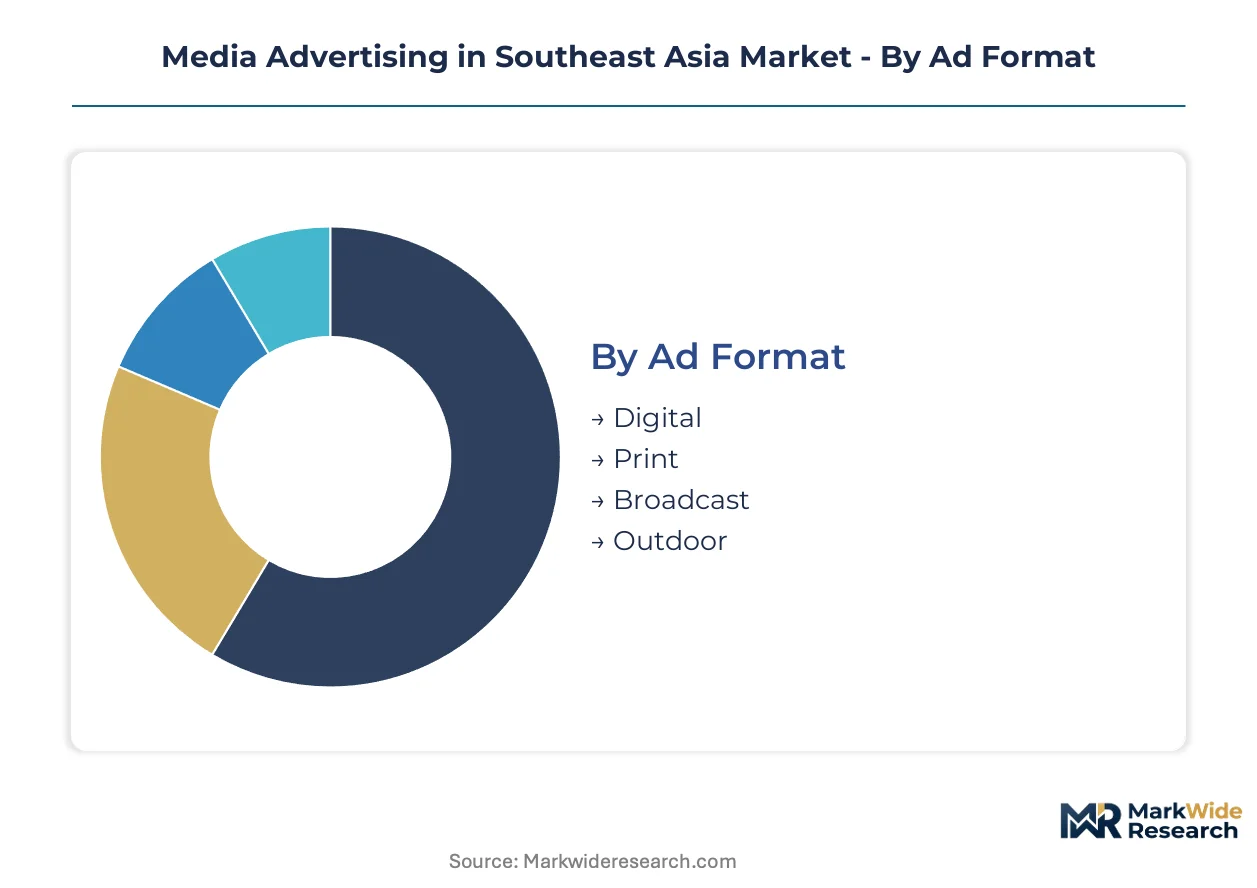
Segmentation reveals how advertising budgets fragment across competing channels and audience cohorts in Southeast Asia. Understanding where margin pools concentrate helps stakeholders allocate resources between high-growth digital formats and legacy inventory that still commands premium pricing in specific metropolitan corridors.
Ad Format:
Margin pools concentrate disproportionately in auction-based digital transactions where real-time bidding protocols compress intermediation costs and redirect value toward publishers with proprietary audience data.
- Digital:Programmatic algorithms execute the majority of transactions through real-time bidding protocols across Indonesia, Vietnam, and Thailand. Mobile-first consumption patterns in Jakarta and Ho Chi Minh City concentrate demand for in-app and mobile web inventory, with advertisers capturing measurable attention metrics rather than proxy reach estimates.
- Outdoor:Transit-oriented digital screen networks along Bangkok's BTS corridors and Manila's MRT lines are displacing static billboards. JCDecaux Singapore Pte. Ltd. and VGI Global Media Public Co. Ltd. hold prime concession contracts where foot traffic sensors now enable dynamic creative rotation based on real-time pedestrian flows.
- Broadcast:National television networks in the Philippines and Thailand retain residual audience share among demographics over 45. Unified planning across linear and digital channels requires workflow redesign that many agencies have not completed.
- Print:Circulation declines continue across regional newspaper markets, though niche business publications in Singapore maintain targeted reach among financial services decision-makers.
The dominant share belongs to Digital, while Outdoor is closing the gap fastest as metropolitan transit authorities unbundle concession contracts for data-driven placements.
Industry Vertical:
Application intensity varies sharply, with consumer-facing sectors deploying closed-loop attribution while regulated industries navigate consent framework complexity.
- Retail:E-commerce platforms across Indonesia, Malaysia, and Vietnam are expanding performance marketing allocations aggressively. Shopee and Lazada marketplace sellers redirect search and display budgets toward on-platform sponsored placements where transaction data enables weekly media mix modeling cycles.
- Technology:Hardware and software vendors concentrate spend in Singapore and Bangkok where professional audiences cluster. Customer data platform investments accelerate as Singapore's Personal Data Protection Commission tightens consent granularity requirements for cross-context behavioral targeting.
- Automotive:Dealership networks in Thailand and Indonesia blend brand awareness campaigns with lead generation focused on test drive appointments. First-party data infrastructure builds lag behind retail and technology verticals.
- Healthcare:Pharmaceutical and medical device advertisers face the steepest compliance burden under Singapore's consent frameworks. Separate authorizations for audience segmentation, lookalike modeling, and measurement pixel deployment inflate legal overhead.
Retail captures the dominant share through e-commerce platform budget expansion, with Technology climbing fastest on data infrastructure investment.
Platform Type:
Customer type differentiation separates closed ecosystems with proprietary transaction data from open-web inventory dependent on deprecating third-party identifiers.
- Social Media:Short-form video platforms command disproportionate attention hours from Indonesian and Vietnamese consumers. Brand safety concerns persist as user-generated content scales faster than moderation capacity.
- Search Engines:Google maintains auction liquidity across Southeast Asian markets, though retail media networks are capturing product search queries previously routed through general search.
- Websites:Publisher-direct relationships and programmatic guaranteed deals fragment procurement workflows. Premium news outlets in Singapore and Malaysia negotiate rate premiums based on contextual relevance rather than behavioral targeting.
- Television:Addressable TV inventory remains limited outside Singapore and metropolitan Bangkok. Legacy broadcast integration challenges delay unified planning capabilities at most agencies.
Social Media holds the dominant share, while Search Engines face pressure from retail media network encroachment on product discovery.
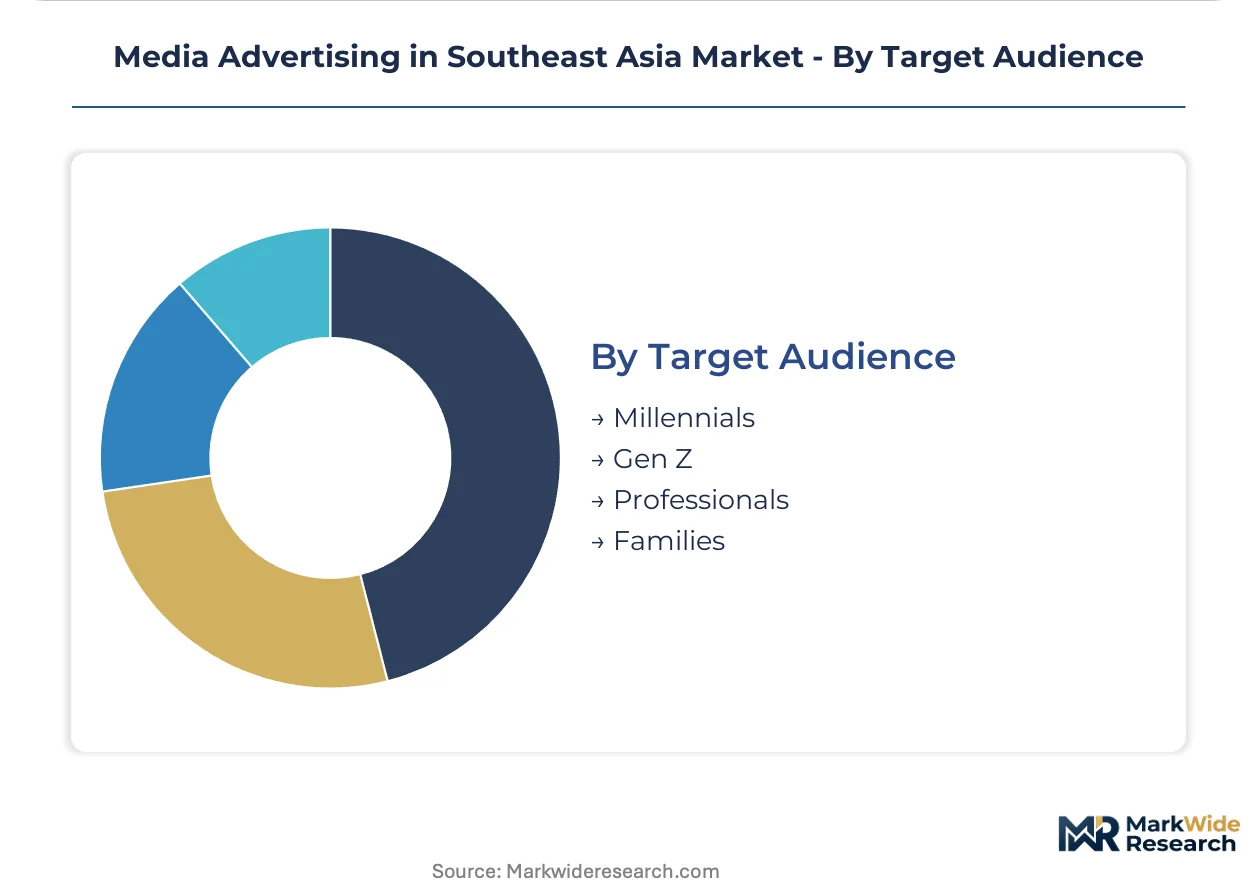
Target Audience:
Geographic concentration of specific cohorts drives inventory pricing power, with metropolitan millennials and Gen Z consumers commanding premium CPMs.
- Gen Z:Indonesian and Vietnamese consumers in this cohort spend more daily hours on smartphones than any other demographic. Short-form video consumption patterns favor vertical creative formats and influencer-mediated brand messaging.
- Millennials:Jakarta-to-Surabaya corridor and Bangkok metropolitan area concentrate this cohort's purchasing power. E-commerce platform penetration rates peak among this segment across Shopee and Lazada marketplaces.
- Professionals:Singapore and Kuala Lumpur financial services and technology sectors concentrate high-income earners. LinkedIn and niche business publications capture disproportionate B2B advertising allocations.
- Families:Household purchase decision-makers in the Philippines and Thailand retain multi-generational media consumption patterns. Broadcast television maintains residual reach among this cohort that digital channels have not fully replicated.
Millennials retain the dominant share through purchasing power concentration, with Gen Z expanding most quickly as platform algorithms optimize for engagement-driven monetization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brand advertisers and e-commerce platforms concentrate purchasing power across five Southeast Asian markets where mobile-first consumption patterns and transit-oriented infrastructure reshape budget allocation. Each national market presents distinct regulatory constraints and metropolitan demand clusters.
Indonesia
Shopee and Tokopedia sellers are redirecting search budgets toward on-platform sponsored placements. The forthcoming data protection regulations will mirror ASEAN consent frameworks and compel first-party data infrastructure builds. The Jakarta-to-Surabaya metropolitan corridor concentrates demand for out-of-home digital inventory as transit authorities unbundle concession contracts.
Singapore
Financial services and technology advertisers accelerate customer data platform investments to capture professional audiences. The Personal Data Protection Commission enforces separate authorizations for audience segmentation, lookalike modeling, and measurement pixel deployment. The city-state's hub status concentrates programmatic trading expertise and certified talent pools.
Thailand
Automotive dealership networks blend brand awareness campaigns with lead generation focused on test drive appointments. The Personal Data Protection Act imposes consent-based compliance burdens on cross-context behavioral targeting. Bangkok's BTS corridor hosts connected out-of-home infrastructure where JCDecaux and VGI Global Media hold prime concession contracts.
Vietnam
Lazada marketplace sellers expand performance marketing allocations as retail media networks capture product search queries. The Ministry of Information and Communications maintains content licensing requirements that alter market access conditions for foreign ad-tech providers. Ho Chi Minh City concentrates mobile-first consumption demand for in-app and mobile web inventory.
Philippines
Multi-generational households retain broadcast television reach among family purchase decision-makers. The National Privacy Commission tightens consent frameworks for programmatic targeting and restricts third-party data deployment. Manila's MRT lines are deploying transit-oriented digital screen networks that displace static billboard inventory.
Media Advertising in Southeast Asia Market Competitive Landscape
Player mix skews toward multinational agency holding companies with centralized trading desks and creative-production integration capabilities. The vendor base concentrates around three strategic archetypes: global media networks leveraging cross-market scale, out-of-home specialists controlling prime transit concessions, and independent agencies building localized first-party data infrastructure. Competitive moves center on embedding data science teams inside client marketing organizations and securing premium inventory through programmatic guaranteed deals.
Among the global media network tier, Dentsu International Asia Pte. Ltd. and GroupM Asia Pacific Holdings Ltd. exemplify contrasting positioning archetypes. Dentsu anchors its competitive posture through deep creative-production integration in Tokyo and Singapore hubs. GroupM occupies a position emphasizing centralized trading desk scale across Indonesia and Thailand. Omnicom Media Group Asia Pacific Pte. Ltd. represents the embedded service model, situating data science capabilities directly within client organizations rather than maintaining arm's-length advisory relationships.
| Leading Market Players |
|---|
| Dentsu International Asia Pte. Ltd. |
| GroupM Asia Pacific Holdings Ltd. |
| Omnicom Media Group Asia Pacific Pte. Ltd. |
| Publicis Groupe SA |
| Havas Media Asia Pacific Pte. Ltd. |
| IPG Mediabrands Singapore Pte. Ltd. |
| JCDecaux Singapore Pte. Ltd. |
| Clear Channel Singapore Pte. Ltd. |
| VGI Global Media Public Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
First-party data infrastructure is displacing third-party cookie dependencies across Indonesian and Vietnamese programmatic markets, simultaneously concentrating supply chain value in Singapore and Bangkok trading hubs while compressing intermediation margins for non-certified traders in secondary metropolitan corridors.
Pricing Analysis
Cost-plus contracts with CPM indexation to attention-quality metrics dominate premium inventory negotiations between Indonesian e-commerce platforms and agency trading desks. Price differentiation hinges on certification tier—IAB Southeast Asia's eroding standard versus platform-specific vendor badges—and geographic delivery cost differentials between Jakarta-Surabaya and Ho Chi Minh City. Pricing pressure stems from retail media networks capturing closed-loop attribution that brand advertisers previously purchased through open-web auctions. SME marketplace sellers on Shopee and Lazada exhibit highest price sensitivity, while multinational CPG brands in Singapore demonstrate lowest.
Supply Chain Analysis
Inbound logistics costs through Singapore's port infrastructure and container availability on intra-ASEAN trade lanes shape ad-tech hardware deployment timelines for transit-oriented digital screen networks. Supply concentrates in Singapore, Thailand, and Vietnam for programmatic platform infrastructure, with creative production capabilities anchored in Tokyo and Singapore hubs. Raw material dependencies span LED display components from South Korea, server hardware from Taiwan, and data center capacity from Malaysia. Single-source vulnerability concentrates in Singapore's trading desk talent pools. Distribution runs through agency holding company networks and direct publisher relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a cyclical recovery phase driven by e-commerce platform budget expansion following pandemic-era pullbacks, with performance marketing allocations now exceeding pre-crisis trajectories across Indonesia, Malaysia, and Vietnam.
For Market Incumbents: Consolidate trading desk capabilities in Jakarta and Bangkok to capture Shopee and Lazada seller demand before compliance mandates fragment operations. Acquire certified programmatic talent pools in Singapore as IAB Southeast Asia's standard erodes. Build proprietary audience graphs in Indonesia's metropolitan corridor ahead of forthcoming data protection regulations.
For New Entrants and Emerging Players: Differentiate on first-party data infrastructure specialization for healthcare and financial services verticals facing Singapore's consent granularity requirements. Target Vietnam's performance marketing segment where Ministry of Information and Communications licensing creates friction for cross-border ad-tech providers. Pursue white-label retail media network partnerships with emerging marketplace sellers.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors creative-production integration capabilities over pure-play trading scale. Long-term viability over the next decade hinges on closed-loop attribution infrastructure rather than open-web programmatic liquidity. Monitor Indonesia's data protection regulation promulgation as the inflection signal for first-party data infrastructure valuation resets.
| Strategic Initiative | Industry Significance |
|---|---|
| First-Party Data Infrastructure Build | Captures targeting precision as Singapore's PDPC tightens consent granularity for financial services advertisers. |
| Transit Concession Contract Securement | Locks prime inventory access along Bangkok BTS and Manila MRT corridors where JCDecaux and VGI dominate. |
| Creative-Production Hub Integration | Compresses campaign iteration cycles through Tokyo-Singapore co-location models that Dentsu has operationalized. |
| Retail Media Network Partnership | Captures closed-loop attribution from Shopee and Lazada sellers redirecting search budgets from Google. |
| Certified Talent Pool Acquisition | Defends auction-based buying capabilities as IAB Southeast Asia's digital certification loses gatekeeping authority. |
Research Methodology
The analysis maps digital programmatic, out-of-home transit networks, and retail media sub-sectors, each validated through programmatic traders, agency holding company executives, e-commerce platform advertising leads, and transit authority concession managers. Primary interview insights combined with secondary validation from IAB Southeast Asia certification records, Personal Data Protection Commission enforcement notices, and Ministry of Information and Communications licensing disclosures. Bottom-up spend estimates from marketplace seller allocations triangulate against top-down agency billings data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include ad format, industry vertical, platform type, and target audience cohort with geographic concentration overlays. CAGRs derive from trend extrapolation of mobile-first consumption patterns and transit infrastructure deployment schedules. Forecast inputs incorporate e-commerce GMV trajectories and consent framework implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce platform budget expansion or accelerated data protection enforcement would require recalibration. Forecasts reflect assumptions about programmatic algorithm adoption rates and retail media network penetration. Recalibration cycles align with material shifts in ASEAN regulatory harmonization and transit concession contract renewal schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Magazine Advertising Market
Advertising and Marketing Media
South Africa Out-Of-Home (OOH) and Digital Out-Of-Home (DOOH) Market
Advertising and Marketing Media
Digital Out of Home (DOOH) Market
Advertising and Marketing Media
Adtech Market
Advertising and Marketing Media
United Kingdom Marketing Agencies Market
Advertising and Marketing Media
Turkey OOH and DOOH Market
Advertising and Marketing Media
Retail Media Creative Optimization Market
Advertising and Marketing Media
Asia-Pacific Marketing Agencies Market
Advertising and Marketing Media
Finland OOH and DOOH Market
Advertising and Marketing Media
Middle East and North Africa Digital Out-Of-Home (DOOH) Market
Advertising and Marketing Media
Hong Kong OOH and DOOH Market
Advertising and Marketing Media
United States Public Relation Services Market
Advertising and Marketing Media
Global Advertising Software Market
Advertising and Marketing Media
Digital Advertising Market
Advertising and Marketing Media
Out of Home Advertising Market
Advertising and Marketing Media
Saudi Arabia OOH and DOOH Market