
 Meat Seasonings Market | 2026-2036
Meat Seasonings Market Size, Share, and Industry Trends Forecast 2026-2036
Meat Seasonings Market Foresight
Asset-light co-manufacturing partnerships is tilting competitive dynamics toward mid-tier brands that lack captive production. McCormick & Company Inc. leverages its scale to dominate North American retail shelf space. Kerry Group plc anchors European supply through integrated taste and nutrition platforms. Sensient Technologies Corporation specializes in natural color and flavor extraction for premium meat applications.
Meat seasonings comprise blended spice, herb, extract, and flavoring preparations applied to raw or processed meat to enhance sensory properties, extend shelf stability, or mask off-notes from reduced-sodium formulations. Dry Rubs retain the largest volume share due to manufacturing simplicity and extended ambient stability, while Marinades capture margin pools in foodservice channels where labor reduction carries premium value. Pouch packaging outpaces bottles in growth as single-use formats align with food processing automation and portion-control requirements.
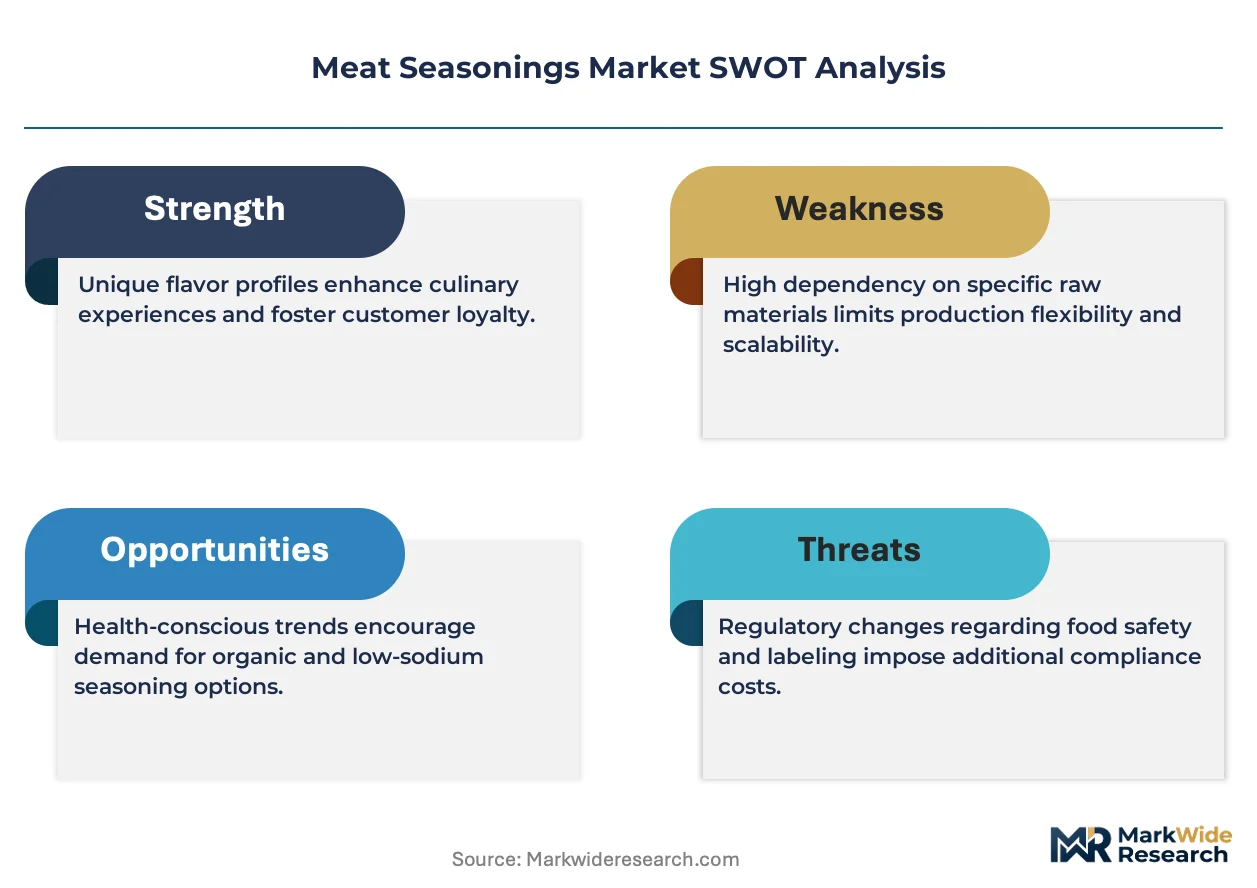
FDA food additive regulations and USDA organic certification standards govern ingredient permissibility and label claims in the United States, while EFSA safety assessments under EU regulation shape novel extract approvals. The EU Green Deal's Farm to Fork strategy is forcing reformulation away from artificial preservatives toward plant-derived antimicrobial compounds. Stakeholders must monitor evolving natural claim thresholds and build regulatory intelligence into NPD timelines.
Market Dynamics
Food processing facilities are accelerating reformulation timelines as clean-label mandates compress product development cycles from eighteen months to under nine months.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:The EU Green Deal is mandating ingredient transparency across meat supply chains, forcing processors to adopt plant-derived antimicrobial compounds and natural extract-based seasonings.
- Single-use pouch automation:Food processing facilities are integrating single-use pouch formats into high-speed production lines, reducing labor costs and enabling precise portion control for institutional buyers.
- Germany's industrial meat processing corridor:Concentrated R&D investment in natural extract-based seasonings across Bavaria and Lower Saxony is establishing technical benchmarks that diffuse into adjacent European markets.
Market Restraints
- Raw material input volatility:Spice and herb commodity prices fluctuate with climate-induced harvest variability, compressing margins for seasoning blenders without long-term agricultural contracts.
- EFSA novel extract approval timelines:Safety assessments for plant-derived antimicrobial compounds extend eighteen to thirty-six months, delaying commercialization of clean-label preservatives.
- Artificial flavor substitution ceiling:Technical limitations in replicating Maillard reaction complexity with natural extracts constrain full reformulation in premium processed meat categories.
Strategic Opportunities
- Reduced-sodium masking technology:Off-note masking formulations for low-sodium meat products represent underexploited white space as hypertension-linked labeling expands.
- REACH chemical standard compliance services:Seasoning suppliers can capture value by pre-certifying ingredient portfolios for EU chemical disclosure requirements, reducing processor compliance burden.
- Direct-to-processor digital platforms:B2B e-procurement channels are disintermediating traditional ingredient distributors, enabling mid-tier seasoning brands to access national foodservice accounts.
Industry Challenges
- Flavor chemist talent scarcity:The intersection of food science and natural product chemistry requires specialized expertise that outpaces university program output.
- Clean-label certification timeline compression:USDA organic and non-GMO verification processes create bottlenecks as processors accelerate reformulation schedules.
- Legacy ERP integration friction:Food processing facilities struggle to synchronize seasoning inventory management systems with automated pouch-filling equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meat Seasonings Market |
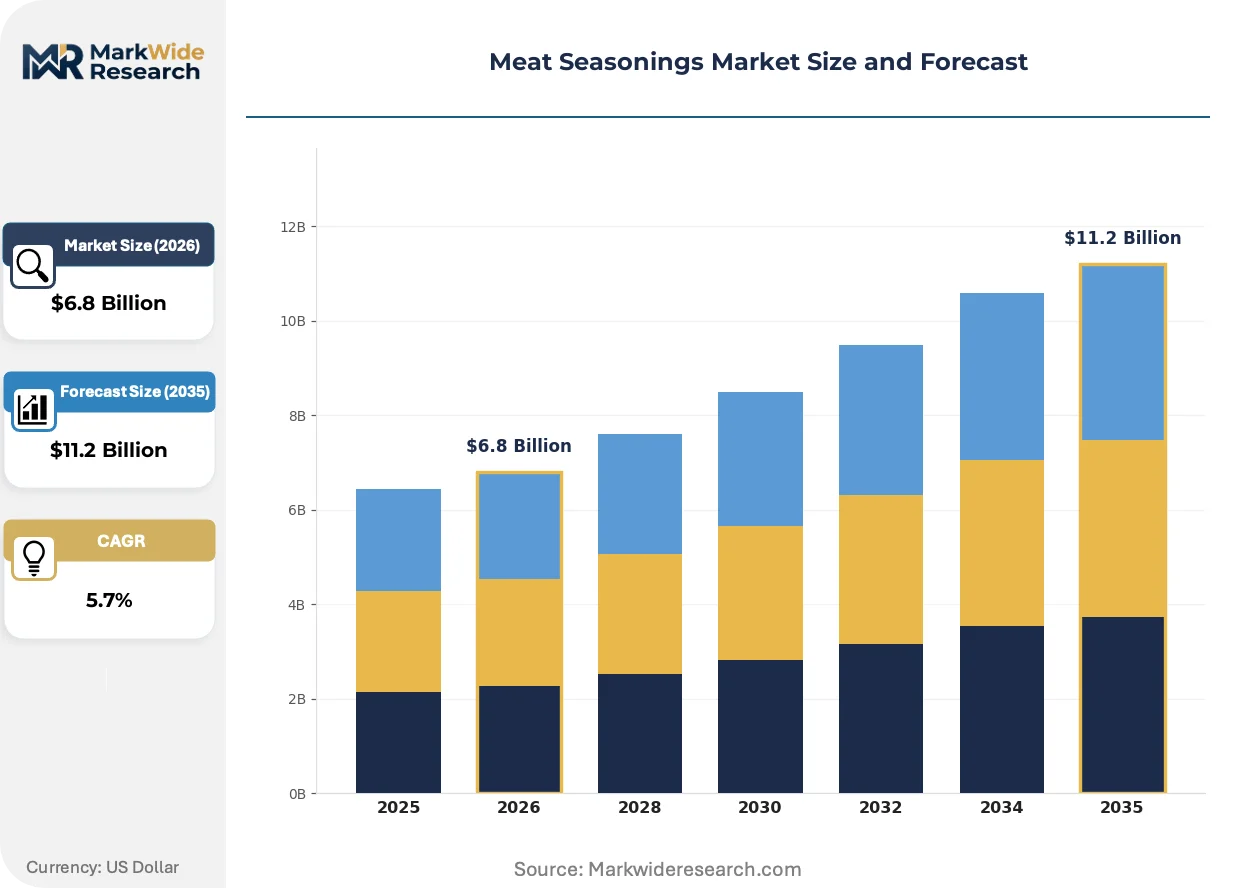
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Rubs, Marinades, Sauces, Brines Packaging Type: Bottles, Sachets, Jars, Pouches End User: Restaurants, Households, Catering Services, Food Processing Flavor Profile: Spicy, Savory, Sweet, Smoky |
| Companies Covered | Ajinomoto Co. Inc., Sensient Technologies Corporation, McCormick & Company Inc., Givaudan SA, Symrise AG, Kerry Group plc, Döhler Group, International Flavors & Fragrances Inc., Olam International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat Seasonings Market Shifts & Advancements
Extraction technologies and regulatory disclosure requirements are converging to redefine competitive advantage around ingredient provenance and sensory fidelity.
Supercritical CO2 extraction systems are isolating volatile aromatic compounds from herbs and spices with solvent-free precision. Mid-sized seasoning houses in Germany and the Netherlands are deploying these systems to produce concentrated oleoresins for industrial meat processors. Batch-scale supercritical extraction is rendering obsolete traditional steam distillation methods that degrade heat-sensitive terpenes.
REACH chemical standards under ECHA jurisdiction now require full supply chain disclosure for substances of very high concern in food contact applications. Seasoning suppliers must document extraction solvents and residual limits across multi-tier supplier networks. European meat processors are consolidating supplier bases to reduce compliance audit burden, favoring integrated taste houses with captive extraction capabilities.
Foodservice operators are unbundling seasoning procurement from protein sourcing, creating standalone category management for flavor systems. Institutional buyers in the United States and Germany are establishing direct relationships with seasoning specialists rather than accepting bundled protein-plus-seasoning contracts. This disintermediation is most visible in contract catering and quick-service restaurant supply chains, where menu localization demands rapid flavor customization.
Meat Seasonings Market Segmentation
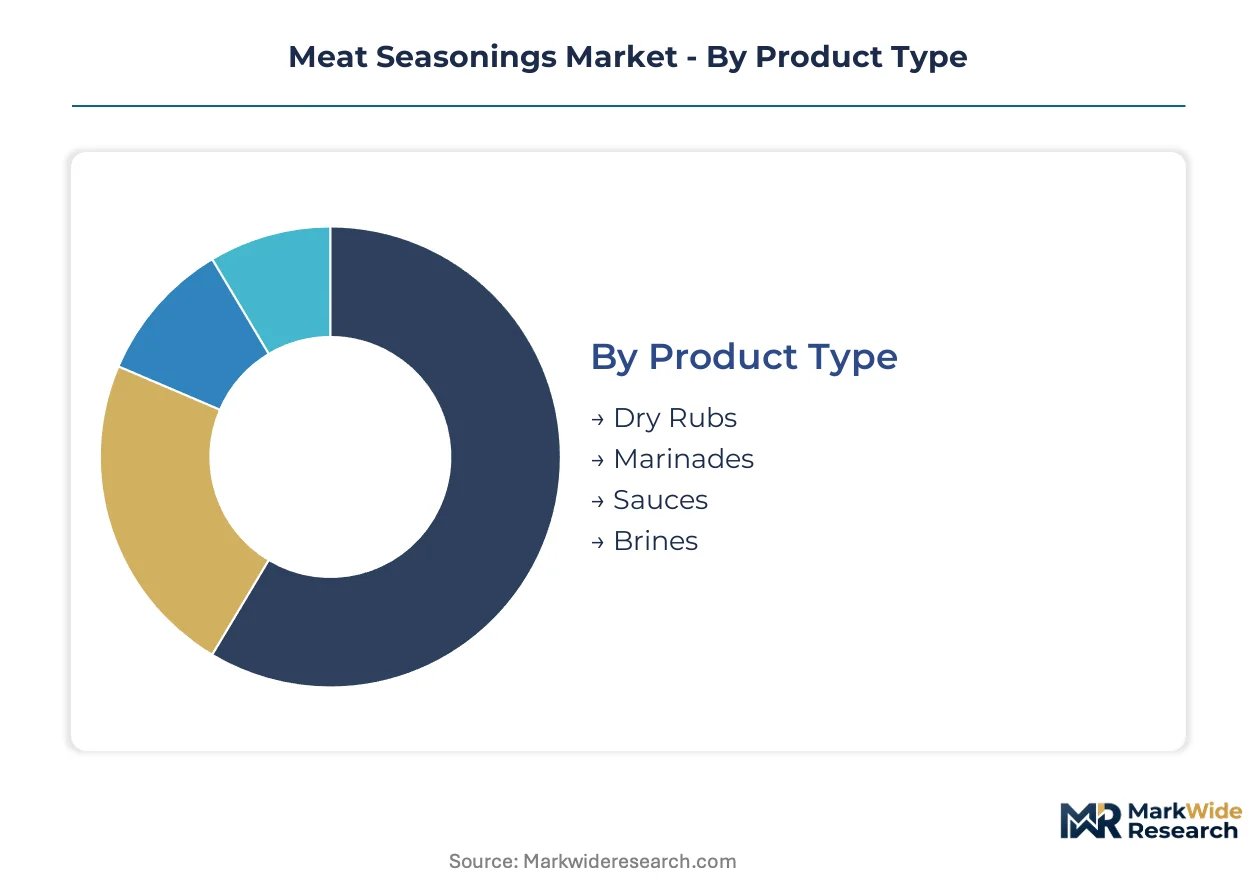
Segmentation in meat seasonings reveals how formulation complexity, packaging automation readiness, and end-user technical specifications create divergent margin structures. Procurement patterns across food processing facilities and foodservice channels demand distinct product architectures.
Product Type:
After-sales service intensity varies sharply across product types, with marinades requiring formulation troubleshooting support while dry rubs need minimal technical intervention post-sale.
- Dry Rubs:Blended spice and herb preparations with low moisture content enable extended ambient shelf stability without preservative systems. German industrial meat processors in Bavaria specify custom rub formulations for automated tumble-drum applications, driving standardization around particle size distribution and flowability metrics.
- Marinades:Liquid or semi-liquid systems combining acids, oils, and flavor compounds for protein penetration and tenderization. US foodservice distributors concentrate procurement for labor-reducing pre-marinated protein programs, though EFSA novel extract approvals delay clean-label antimicrobial variants.
- Sauces:Viscous finishing applications applied post-cooking or as dipping accompaniments.
- Brines:Salt-sugar-phosphate solutions for moisture retention and yield enhancement in processed meats.
By volume, Dry Rubs leads. By growth pace, Marinades is ahead.
Packaging Type:
Cost tier stratification separates premium jar formats for retail gifting from economy pouch systems for institutional procurement.
- Pouches:Flexible single-use formats integrating with high-speed form-fill-seal automation in food processing facilities. REACH chemical disclosure requirements for food-contact layers favor suppliers with captive film extrusion capabilities and documented solvent residual testing.
- Sachets:Individual-portion foil or laminate packets for foodservice portion control. Quick-service restaurant chains in the United States specify sachet formats for back-of-house consistency, though legacy ERP integration friction complicates inventory synchronization.
- Bottles:Rigid PET or glass containers for retail shelf presence and repeated dispensing.
- Jars:Wide-mouth glass or plastic containers for thick sauces and rubs requiring spoon access.
By installed base, Bottles retains the largest footprint. By expansion trajectory, Pouches is climbing the fastest.
End User:
Application requirements dictate formulation sophistication, with food processing facilities demanding batch-scale consistency unmatched by household usage patterns.
- Food Processing:Industrial-scale seasoning for standardized output across production runs. USDA organic certification timelines and compressed clean-label reformulation cycles create procurement bottlenecks as facilities accelerate from eighteen-month to nine-month development schedules.
- Restaurants:Foodservice channels prioritizing labor reduction through pre-blended systems. Independent operators in Germany's Lower Saxony corridor source direct from seasoning specialists rather than bundled protein suppliers, disintermediating traditional distribution.
- Catering Services:High-volume institutional feeding with menu localization demands.
- Households:Retail consumers selecting on label claims and culinary trend alignment.
By revenue concentration, Food Processing dominates. By margin expansion, Restaurants is gaining share fastest.
Flavor Profile:
Customer type segmentation separates premium positioning around complex savory-smoky combinations from commodity spicy formulations.
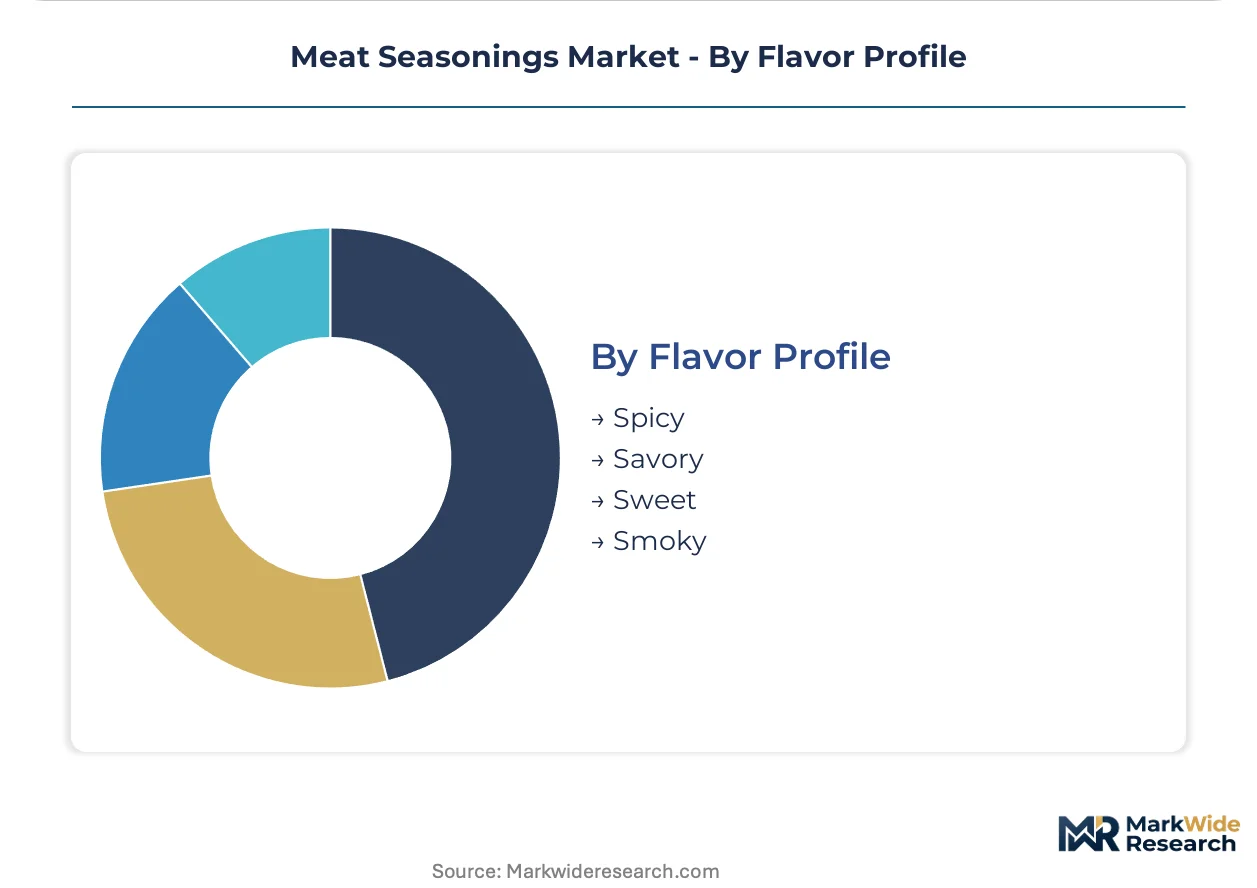
- Savory:Umami-forward systems leveraging hydrolyzed proteins, yeast extracts, and fermented compounds. Supercritical CO2 extraction of natural glutamate precursors in Dutch and German facilities is displacing traditional steam distillation for heat-sensitive aromatic preservation.
- Smoky:Liquid smoke, smoked salt, or pyroligneous acid systems replicating wood-fired characteristics. Technical limitations in Maillard reaction complexity constrain full natural substitution for artificial smoke flavors in premium processed meat categories.
- Spicy:Capsaicin-based heat systems from chili, pepper, or extract sources.
- Sweet:Sugar, molasses, or fruit-based profiles for barbecue and glaze applications.
By formulation prevalence, Savory leads. By menu trend velocity, Smoky is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in seasoning concentrates and natural extracts are redirecting procurement strategies across major meat processing economies. Germany and the United States maintain structural trade surpluses in value-added seasoning systems, while emerging processors in Asia-Pacific rely on imported oleoresin inputs.
United States
Foodservice operators drive seasoning procurement through direct contracts with flavor specialists rather than bundled protein suppliers. FDA food additive regulations and USDA organic certification standards govern ingredient permissibility and label claims. Chicago and the broader Midwest corridor concentrate industrial meat processing capacity, where facilities compress reformulation timelines from eighteen months to under nine months.
Germany
Bavaria and Lower Saxony anchor concentrated R&D investment in natural extract-based seasonings that establishes technical benchmarks diffusing across European markets. EU Green Deal Farm to Fork strategy mandates ingredient transparency, forcing adoption of plant-derived antimicrobial compounds. REACH chemical standards under ECHA jurisdiction require full supply chain disclosure for substances of very high concern in food contact applications.
China
Domestic meat processors are accelerating clean-label reformulation to capture premium retail shelf space previously dominated by imported seasoning brands. SAMR and GB standards govern food additive safety and labeling requirements. Yangtze River Delta processing clusters are integrating supercritical CO2 extraction capabilities to reduce dependence on European oleoresin imports.
Netherlands
Mid-sized seasoning houses deploy supercritical extraction systems to produce concentrated oleoresins for industrial meat processors across the Benelux region. EFSA safety assessments shape novel extract approvals, extending eighteen to thirty-six months for plant-derived antimicrobial compounds. Rotterdam-Antwerp logistics corridors enable just-in-time seasoning distribution to automated food processing facilities.
Brazil
Beef and poultry exporters are reformulating seasoning profiles to meet EU Green Deal chemical disclosure requirements for premium export segments. ANVISA regulates food additive safety and establishes maximum residue limits for extraction solvents. São Paulo state concentrates domestic meat processing capacity, where facilities adopt single-use pouch formats to align with international buyer automation standards.
Meat Seasonings Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with extraction and concentrate capabilities. The vendor base organizes into three tiers: multinational taste-and-nutrition platforms with integrated R&D, mid-sized regional blenders with captive extraction assets, and commodity spice traders without formulation services. Strategic moves concentrate on M&A to acquire natural extraction capabilities and geographic expansion through co-manufacturing partnerships that reduce capital intensity.
Within the integrated platform tier, McCormick & Company Inc. and Kerry Group plc exemplify scale-driven positioning across retail and foodservice channels. Sensient Technologies Corporation occupies a specialist position in natural color and flavor extraction for premium meat applications. These three anchors demonstrate how competitive advantage converges around regulatory pre-certification and captive supply of clean-label ingredients.
| Leading Market Players |
|---|
| Ajinomoto Co. Inc. |
| Sensient Technologies Corporation |
| McCormick & Company Inc. |
| Givaudan SA |
| Symrise AG |
| Kerry Group plc |
| Döhler Group |
| International Flavors & Fragrances Inc. |
| Olam International |
| Others |
Supply & Pricing Matrix
Raw material input volatility from climate-induced harvest variability determines both the spread between premium natural-extract and economy synthetic formulations and the geographic consolidation of backward-integrated suppliers. Spice and herb commodity fluctuations compress margins for blenders without long-term agricultural contracts, forcing tiered pricing stratification across certification levels and captive supply capabilities.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for food processing facilities seeking batch-scale consistency. Price differentiation rests on USDA organic certification tier and volume scale, with premium natural-extract formulations commanding substantial spreads over standard synthetic blends. Cost compression in the mid-tier is intensifying because EFSA novel extract approval timelines delay clean-label alternatives. Quick-service restaurant chains exhibit highest price sensitivity due to menu localization demands, while premium retail channels show lowest sensitivity.
Supply Chain Analysis
Tariff exposure between Brazil and the European Union dominates risk calculations for beef and poultry exporters reformulating seasoning profiles. Geographic supply concentrates in India, Vietnam, and Indonesia for black pepper and chili inputs, while supercritical CO2 extraction equipment sources from Germany and the Netherlands. The supply chain draws from volatile spice harvests and specialized oleoresin concentrates. Single-source vulnerability persists for heat-sensitive terpene extracts. Distribution runs through Rotterdam-Antwerp logistics corridors serving automated food processing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward food processing facilities consolidating supplier bases to reduce REACH compliance audit burden, fragmenting traditional distributor channels. This concentration among institutional procurement teams reconfigures margin capture across the value chain.
For Market Incumbents: Harden regulatory pre-certification capabilities by building captive supercritical CO2 extraction assets in Germany's Bavaria corridor. Deepen backward integration into oleoresin production to offset raw material volatility. Kerry Group plc and McCormick & Company Inc. demonstrate how integrated taste platforms defend against mid-tier brands leveraging asset-light co-manufacturing partnerships. For New Entrants and Emerging Players: Establish a beachhead in reduced-sodium masking technology for hypertension-linked labeling expansion. Target direct-to-processor digital platforms disintermediating traditional ingredient distributors. White space exists in REACH chemical standard compliance services for EU-bound meat processors. Go-to-market angle: pre-certified ingredient portfolios reducing processor compliance burden. For Investors and Strategic Acquirers: Mid-sized regional blenders with captive extraction assets present attractive acquisition targets as European processors consolidate supplier bases. Long-term viability hinges on natural claim threshold evolution and supercritical extraction technology diffusion. Watch EFSA novel extract approval velocity as inflection indicator for clean-label preservative commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oleoresin Production | Captive supercritical CO2 extraction in Dutch and German facilities reduces dependence on volatile spice commodity markets. |
| REACH Pre-Certification Service Launch | Pre-validated ingredient portfolios capture value from EU processors consolidating supplier bases for chemical disclosure compliance. |
| Direct-to-Processor Digital Platform | B2B e-procurement channels enable mid-tier seasoning brands to access national foodservice accounts without distributor intermediation. |
| Reduced-Sodium Masking R&D Program | Off-note masking formulations for low-sodium meat products address expanding hypertension-linked labeling requirements. |
| Single-Use Pouch Format Expansion | Flexible packaging integrating with high-speed form-fill-seal automation aligns with food processing facility labor reduction priorities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA food additive filings, EFSA safety assessment databases, USDA organic certification records, and EU REACH chemical disclosure registries. Interviews with flavor chemists, food processing procurement directors, seasoning house R&D leads, and regulatory affairs specialists were cross-validated against trade data from customs authorities and industry association reports. Bottom-up segmentation modeling was triangulated with top-down macroeconomic indicators.
Forecast inputs include product type segmentation across dry rubs and marinades, packaging format adoption curves for pouches versus bottles, end-user concentration in food processing versus foodservice channels, and flavor profile velocity for smoky versus savory systems. CAGRs were derived from regression analysis against protein processing volume trends and clean-label reformulation cycle compression. Supercritical extraction technology diffusion rates and EFSA novel extract approval pipelines were incorporated as industry-specific variables across the projection horizon.
Stress conditions across spice commodity price volatility, EFSA approval timeline extension, and EU Green Deal enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reformulation cycle compression and natural claim threshold evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Global Clove Market
Spices and Seasonings
Cardamom Oil Market
Spices and Seasonings
Achiote Powder Market
Spices and Seasonings
Dried Herbs Market
Spices and Seasonings
Turkey Flavors Market
Spices and Seasonings
Dill Oil Market
Spices and Seasonings
Middle East and Africa Ashwagandha Market
Spices and Seasonings
Thyme Extract Market
Spices and Seasonings
Spice Grinders Market
Spices and Seasonings
Turmeric Market
Spices and Seasonings
North American Seasonings and Spices Market
Spices and Seasonings
Dried Spices Market
Spices and Seasonings
Herb Oil Market
Spices and Seasonings
Serrata Extract Market
Spices and Seasonings
Gourmet Seaweed Seasoning Market
Spices and Seasonings
Garlic Salt Market