
 Herb Oil Market | 2026-2036
Herb Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Herb Oil Market Analysis
Organic-certification tier demand is collapsing the conventional segment's premium position. Symrise AG leverages captive botanical sourcing across Mediterranean growing zones. Young Living Essential Oils anchors its position through seed-to-seal vertical control over lavender and peppermint estates. doTERRA International LLC differentiates via Co-Impact Sourcing partnerships with harvester cooperatives in developing origins.
Herb oil comprises volatile aromatic compounds, fixed lipids, and bioactive phytochemicals extracted through steam distillation, cold pressing, or solvent extraction, serving as functional ingredients across flavoring, fragrance, therapeutic, and preservation applications. Essential oils command the widest application breadth yet face margin compression from adulteration scrutiny, while carrier oils sustain steadier volume flows into cosmetic manufacturing. Pharmaceutical-grade extracts attract the fastest qualification cycles as healthcare providers validate standardized compositions for clinical aromatherapy protocols.
FDA oversight of dietary supplement labeling under DSHEA, EPA pesticide residue tolerances for imported botanicals, and EU REACH registration requirements for fragrance allergens collectively elevate compliance costs for cross-border suppliers. Organic certifiers including USDA National Organic Program and EU organic regulation further segment market access by cultivation standard. Stakeholders must monitor evolving pharmacopeial monographs that redefine acceptable heavy-metal thresholds before committing to multi-year distillation capacity.
Market Dynamics
Organic-certification requirements are compressing conventional herb oil margins while concentrating procurement power among vertically integrated suppliers with captive botanical estates.
Growth Catalysts
- Clean-label cosmetic mandates:Formulators at L'Oréal and Unilever now require certified organic herb oils for skincare launches, pulling volume away from conventional grades.
- REACH fragrance allergen disclosure:EU Regulation 2023/1545 forces full component transparency, advantaging suppliers with standardized phytochemical profiling capabilities.
- Ayurvedic export protocols:India's AYUSH ministry streamlined export documentation for traditional herb oils, accelerating shipments to European wellness distributors.
Market Restraints
- Wild-harvest supply concentration:Bulgarian rose otto and Moroccan argan depend on smallholder cooperatives with limited acreage expansion potential.
- Adulteration detection costs:Gas chromatography-mass spectrometry testing adds USD 400-800 per batch, eroding margins on mid-tier distillations.
- Synthetic terpene substitution:Biotechnology firms now produce nature-identical limonene and linalool at 40-60% below botanical extraction costs.
Strategic Opportunities
- Clinical aromatherapy protocols:Hospital systems in Germany and Switzerland now reimburse standardized essential oil interventions for post-operative nausea.
- Carbon-negative distillation:Biomass-powered stills using lavender straw waste qualify for EU Green Deal innovation grants.
- Direct-to-practitioner e-commerce:Licensed aromatherapists in Australia and Canada now source pharmaceutical-grade oils through specialized B2B platforms.
Industry Challenges
- Pharmacopeial monograph alignment:USP and EP revisions on heavy-metal thresholds require six-month requalification cycles for existing inventory.
- Skilled distiller scarcity:Traditional steam distillation expertise concentrates in Provence and Kashmir with limited training pipeline replication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herb Oil Market |
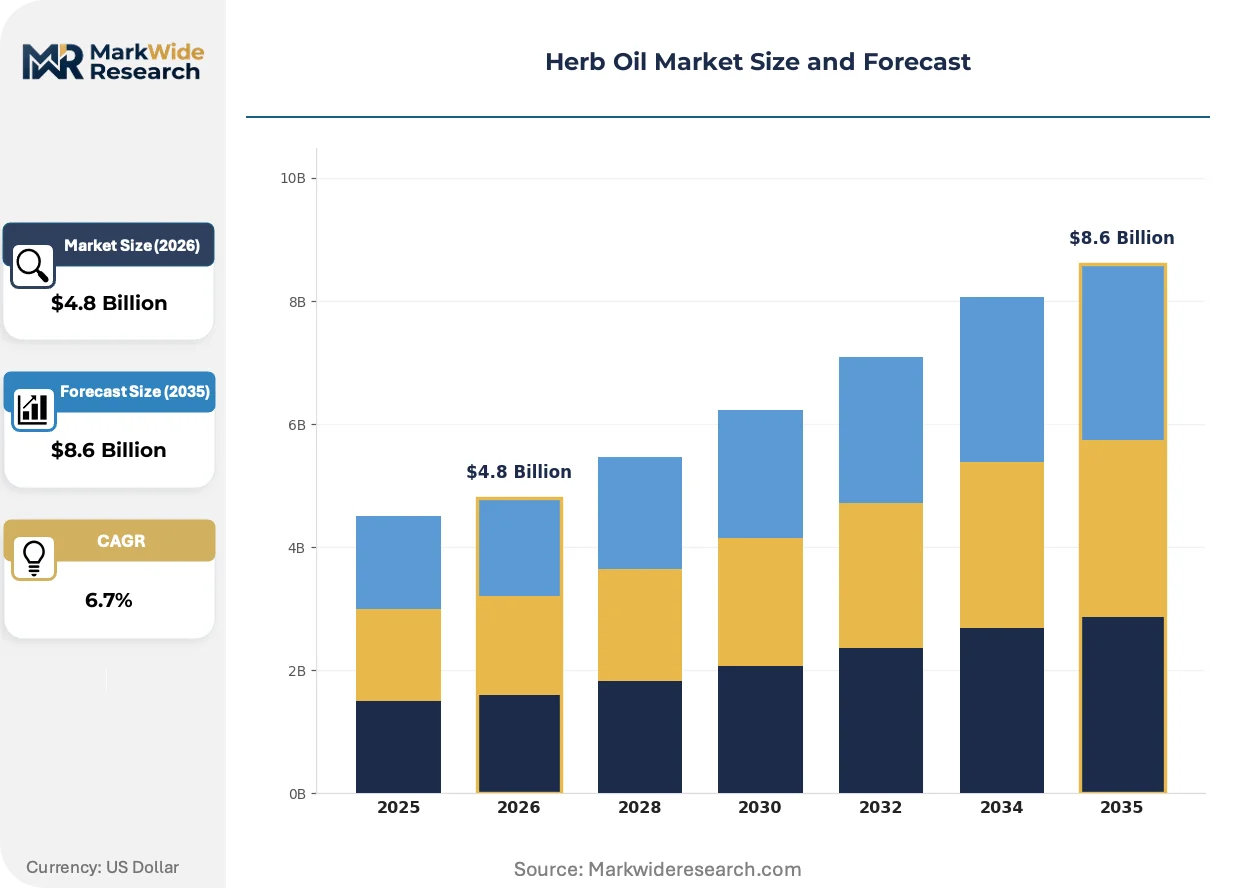
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Carrier Oils, Extracts, Infused Oils Application: Aromatherapy, Cosmetics, Food & Beverage, Pharmaceuticals End User: Households, Restaurants, Cosmetic Manufacturers, Healthcare Providers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Symrise AG, Aura Cacia, doTERRA International LLC, Sensient Technologies Corporation, Edens Garden, Young Living Essential Oils, International Flavors & Fragrances Inc., Synthite Industries Ltd., Givaudan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herb Oil Market Emerging Trajectories
Supercritical CO2 extraction is displacing conventional methods while blockchain traceability and personalized blending platforms reshape how buyers evaluate provenance and potency.
Supercritical CO2 extraction is fragmenting the premium segment by enabling selective compound isolation without thermal degradation. Boutique cosmetic labs in California and South Korea now specify CO2-derived chamomile and calendula for sensitive-skin formulations. This precision is compressing demand for traditional whole-essential-oil grades among performance-focused buyers.
EU REACH Annex III allergen labeling expansions now require disclosure of 82 fragrance compounds versus 26 previously. Small-batch distillers in France and Italy face six-figure compliance investments or exit from cosmetic-grade supply. The regulation is pushing consolidation toward laboratories with in-house toxicology departments.
Subscription-based personalized oil blending is displacing bulk commodity purchases among wellness practitioners. Platforms in the United Kingdom and Netherlands algorithmically match client symptom profiles to custom synergies, bypassing traditional distributor markups. This direct-channel model is most visible among millennial naturopaths seeking margin recovery from retail competition.
Herb Oil Market Segmentation
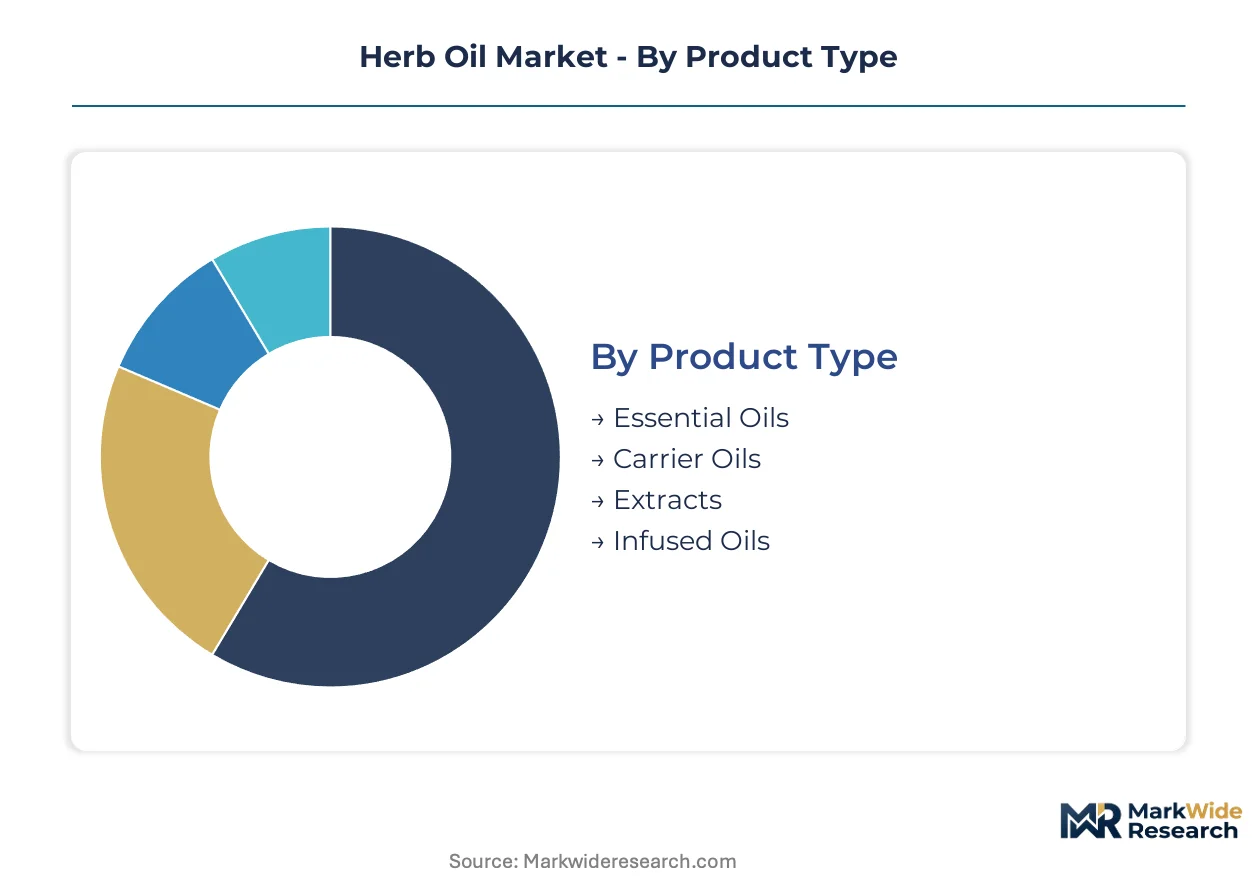
Herb oil buyers navigate four intersecting segmentation frameworks where product chemistry, end-use specification, and channel access determine procurement decisions. Certification requirements and formulation standards fragment what appears as a commodity market into sharply tiered supply relationships.
Product Type:
Essential oils flow predominantly through specialty stores and direct sales channels requiring technical consultation, while carrier oils and extracts move through higher-volume supermarket and online retail pathways.
- Essential Oils:Volatile aromatic compounds extracted via steam distillation or cold pressing deliver concentrated fragrance and therapeutic activity. Demand concentrates in German and Swiss hospital systems now reimbursing clinical aromatherapy protocols for post-operative nausea management.
- Carrier Oils:Fixed lipids including jojoba, argan, and coconut serve as dilution bases for topical application. Cosmetic manufacturers in South Korea and California specify CO2-derived grades for sensitive-skin formulations, compressing demand for conventional whole-oil grades.
- Extracts:Standardized phytochemical concentrates qualify for pharmaceutical-grade supply to healthcare providers requiring USP and EP monograph compliance.
- Infused Oils:Macerated botanical preparations in base oils serve artisanal cosmetic formulators and premium household segments through specialty retail channels.
Essential oils dominate installed base. Extracts are where expansion concentrates.
Application:
Margin structures diverge sharply across applications, with pharmaceutical and clinical aromatherapy commanding qualification premiums while food and beverage applications face cost-down pressure from synthetic terpene substitution.
- Aromatherapy:Therapeutic use spans home diffusion, clinical protocols, and wellness practitioner recommendations. German hospital systems now reimburse standardized interventions, creating qualified demand separate from commodity fragrance markets.
- Cosmetics:Clean-label mandates from L'Oréal and Unilever require certified organic grades, pulling volume from conventional supply tiers. REACH Annex III allergen disclosure rules favor suppliers with in-house toxicology capabilities.
- Food & Beverage:Flavoring applications face biotechnology competition from nature-identical limonene and linalool produced at 40-60% below botanical extraction costs.
- Pharmaceuticals:Standardized compositions for clinical validation attract the fastest qualification cycles as healthcare providers seek evidence-based botanical interventions.
Cosmetics commands current revenue concentration. Pharmaceuticals is climbing the fastest.
End User:
Procurement scale and specification intensity create three distinct service tiers: household buyers through retail, institutional food service through distributors, and qualified manufacturers through direct technical sales.
- Households:Direct-to-consumer purchases through online retail and specialty stores, increasingly subscription-based with personalized blending algorithms matching symptom profiles to custom synergies.
- Restaurants:Artisanal and premium food service operations sourcing traceable infused oils for menu differentiation.
- Cosmetic Manufacturers:Formulators requiring certificate-of-analysis documentation and batch-specific GC-MS profiling for clean-label compliance.
- Healthcare Providers:Hospital systems and licensed aromatherapists sourcing pharmaceutical-grade oils through specialized B2B platforms in Australia and Canada.
Cosmetic manufacturers dominate procurement volume. Healthcare providers are gaining share fastest.
Distribution Channel:
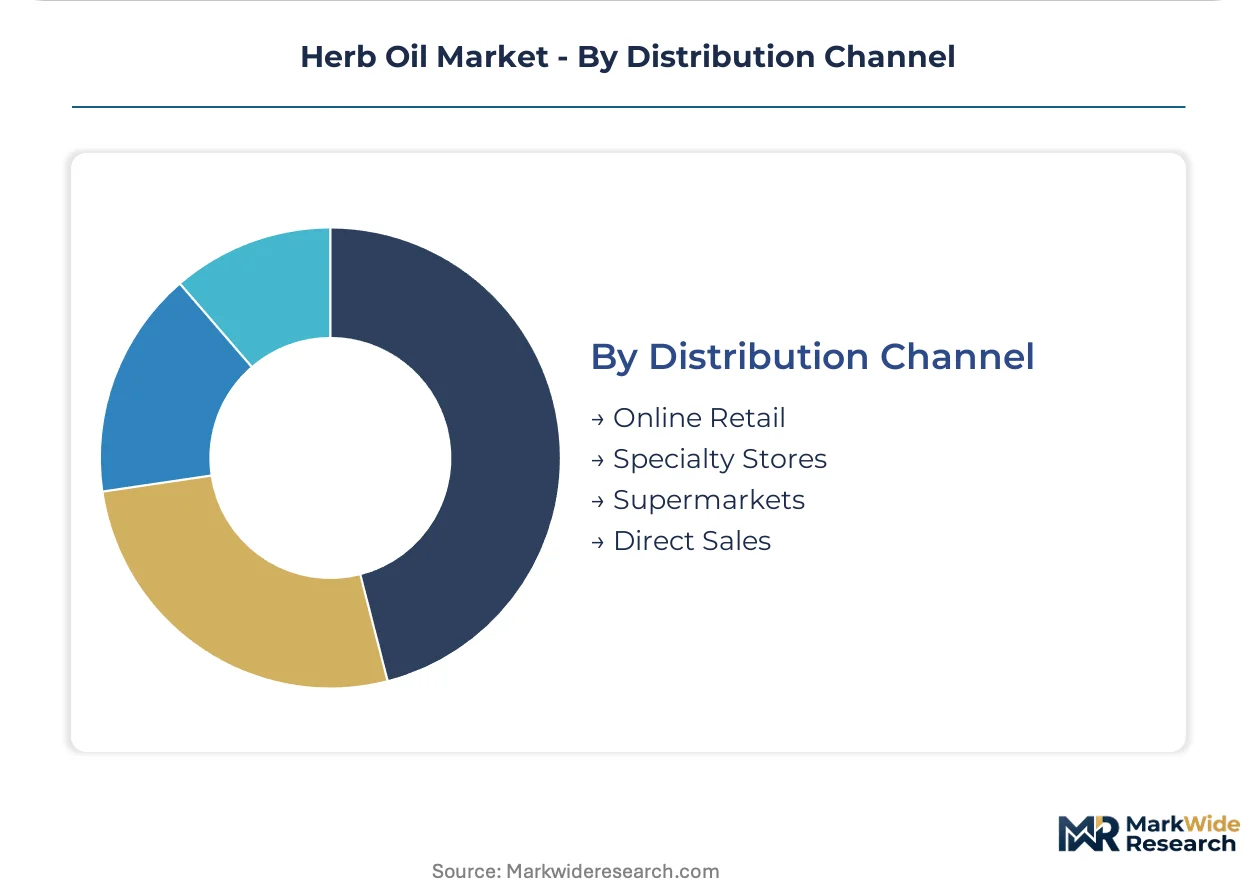
Channel selection determines margin capture and traceability depth, with direct sales preserving qualification premiums and online retail enabling subscription personalization at scale.
- Online Retail:Algorithmic matching platforms in the United Kingdom and Netherlands bypass traditional distributor markups, serving millennial naturopaths seeking margin recovery from retail competition.
- Specialty Stores:Technical consultation and olfactory evaluation support premium essential oil and aromatherapy purchases requiring education-intensive selling.
- Supermarkets:High-volume carrier oil and basic essential oil grades for household cooking and cosmetic DIY applications.
- Direct Sales:Seed-to-seal vertical control and Co-Impact Sourcing partnerships with harvester cooperatives enable provenance documentation for premium therapeutic grades.
Specialty stores dominate premium transaction value. Online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Distillation capacity clusters in specific agricultural zones with established botanical cultivation heritage. Regulatory divergence between jurisdictions creates distinct qualification barriers for cross-border suppliers. Regional demand patterns reflect varying acceptance of clinical aromatherapy protocols and clean-label cosmetic mandates.
United States
Cosmetic formulators in California and New York now require certified organic herb oils for clean-label skincare launches. FDA oversight under DSHEA elevates compliance costs for dietary supplement labeling. Distillation expertise concentrates in the Pacific Northwest where lavender and peppermint estates supply vertically integrated essential oil producers.
Germany
Hospital systems in Bavaria and Baden-Württemberg now reimburse standardized essential oil interventions for post-operative nausea management. REACH Annex III fragrance allergen disclosure rules force full component transparency from suppliers. The ECHA regulatory framework advantages laboratories with in-house toxicology capabilities in the Rhine-Ruhr industrial cluster.
India
Ayurvedic export volumes accelerate through streamlined AYUSH ministry documentation for traditional herb oils. FSSAI standards for food-grade botanical extracts create qualification tiers separating pharmaceutical and commodity supply. Cultivation concentrates in Karnataka and Tamil Nadu where smallholder cooperatives supply jasmine and sandalwood distillers.
France
Steam distillation expertise concentrates in Provence where generational knowledge of lavender and rosemary processing remains scarce to replicate. ANSM pharmacovigilance requirements for aromatherapy products tighten clinical validation standards. Grasse and surrounding Alpine foothills anchor premium fragrance-grade essential oil production for luxury cosmetic houses.
Australia
Licensed aromatherapists in New South Wales and Victoria now source pharmaceutical-grade oils through specialized B2B platforms bypassing traditional distribution. TGA therapeutic goods regulations distinguish cosmetic from medicinal-grade botanical extracts. Eucalyptus and tea tree distillation clusters in Queensland supply both domestic clinical protocols and Asian export markets.
Herb Oil Market Vendor Landscape
Concentration sits with vertically integrated suppliers controlling captive botanical estates and multi-regional distillation networks. Mid-tier distillers face margin compression from organic-certification requirements and adulteration detection costs. Two strategic archetypes dominate: seed-to-seal vertical integrators with estate-level provenance control, and Co-Impact Sourcing partnerships linking harvester cooperatives to laboratory-scale standardization. Competitive moves center on biomass-powered carbon-negative distillation capacity and blockchain traceability investments.
Among vertically integrated specialists, Symrise AG and Young Living Essential Oils exemplify estate-level control over Mediterranean and North American growing zones. doTERRA International LLC occupies a position within the ethical-sourcing archetype through harvester cooperative partnerships in developing origins. These three anchors represent contrasting approaches to provenance documentation and supply security.
| Leading Market Players |
|---|
| Symrise AG |
| Aura Cacia |
| doTERRA International LLC |
| Sensient Technologies Corporation |
| Edens Garden |
| Young Living Essential Oils |
| International Flavors & Fragrances Inc. |
| Synthite Industries Ltd. |
| Givaudan |
| Others |
Supply Flow & Price Mechanics
Small-batch distillation capacity utilization in Provence and Kashmir anchors price floors across all certification tiers, compressing margins for mid-tier operators lacking estate-level scale. REACH Annex III compliance investments now exceed six figures for artisanal producers, forcing exit or consolidation while vertically integrated suppliers capture widening spreads between organic and conventional grades.
Pricing Analysis
REACH Annex III dictates the pricing tier structure across the herb oil market, mandating disclosure of 82 fragrance compounds versus 26 previously and pushing compliance costs toward laboratories with in-house toxicology capabilities. Three-tier pricing stratifies across pharmaceutical-grade, certified organic, and conventional economy levels, with quality grade and certification level as primary differentiation drivers. Cost compression in the conventional tier intensifies because synthetic terpene substitution from biotechnology firms undercuts botanical extraction by 40-60%. Cosmetic manufacturers demonstrate least price sensitivity due to clean-label mandates, while food and beverage formulators exhibit highest sensitivity to cost-down pressure.
Supply Chain Analysis
Bulgarian rose otto harvest concentration in the Kazanlak Valley underwrites supply security for premium fragrance-grade production, with limited acreage expansion potential constraining volume growth. Raw material dependencies rest on smallholder cooperatives in Morocco for argan, Karnataka for jasmine, and Tamil Nadu for sandalwood. Single-source vulnerability concentrates in wild-harvested botanicals with generational cultivation knowledge scarce to replicate. Distribution runs through direct technical sales for qualified manufacturers, specialty retail for therapeutic grades, and algorithmic platforms for subscription-based personalized blending.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers, application specifications, and channel access creates multiple defensible niches for specialized operators. Clean-label cosmetic mandates and clinical aromatherapy reimbursement protocols generate demand-side shifts rewarding precise positioning.
For Market Incumbents: Consolidate distillation capacity around captive botanical estates in Mediterranean and North American growing zones to defend margin spreads from synthetic terpene substitution. Invest in biomass-powered carbon-negative stills qualifying for EU Green Deal innovation grants. Deepen backward integration into seed-to-seal vertical control over lavender and peppermint supply to secure provenance documentation against adulteration scrutiny. For New Entrants and Emerging Players: Differentiate on supercritical CO2 extraction precision serving boutique cosmetic labs in California and South Korea with chamomile and calendula for sensitive-skin formulations. Target pharmaceutical-grade extracts for hospital systems in Germany and Switzerland now reimbursing standardized essential oil interventions. Deploy direct-to-practitioner e-commerce platforms in Australia and Canada bypassing traditional distributor markups. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-based personalized blending platforms algorithmically matching symptom profiles to custom synergies. Long-term viability favors laboratories with in-house toxicology capabilities and blockchain traceability infrastructure spanning the analysis window. Acquisition targets should demonstrate Co-Impact Sourcing partnerships with harvester cooperatives in developing origins. Watch for pharmacopeial monograph revisions on heavy-metal thresholds as inflection indicators requiring inventory requalification.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Negative Distillation Buildout | Biomass-powered stills using lavender straw waste qualify for EU Green Deal innovation grants. |
| Blockchain Traceability Implementation | Seed-to-seal documentation satisfies REACH Annex III allergen disclosure mandates for cosmetic-grade supply. |
| Clinical Aromatherapy Protocol Validation | Standardized compositions enable reimbursement from German and Swiss hospital systems for post-operative nausea management. |
| Co-Impact Sourcing Partnership Expansion | Harvester cooperative relationships in developing origins secure supply for ethical-sourcing market positioning. |
| Supercritical CO2 Extraction Capacity Addition | Selective compound isolation without thermal degradation serves sensitive-skin formulation demand from South Korean cosmetic manufacturers. |
Methodological Framework
The analysis maps essential oils, carrier oils, pharmaceutical-grade extracts, and infused oils, each validated through distillation operators, cosmetic formulators, licensed aromatherapists, and regulatory affairs specialists. Primary interviews with estate managers in Provence and Kashmir, procurement leads at L'Oréal and Unilever, and AYUSH ministry export coordinators combined with secondary validation against EU REACH filings, FDA DSHEA guidance, USP and EP pharmacopeial monographs, and customs trade data. Bottom-up capacity assessments and top-down demand modeling triangulate volume and value estimates.
Consistency checks validated outputs against external benchmarks including ECHA regulatory compliance cost disclosures and AYUSH ministry export documentation statistics. The analytical framework segments by product chemistry, application specification, end-user procurement intensity, and distribution channel access across the projection horizon. CAGRs derive from installed base erosion rates, substitution elasticity to synthetic terpenes, and qualification cycle timelines for pharmaceutical-grade supply. Forecast inputs incorporate biomass-powered distillation adoption curves and blockchain traceability platform penetration.
The analysis sits within stated boundaries; outcomes outside continued REACH enforcement, stable Ayurvedic export protocols, and sustained clinical aromatherapy reimbursement would require recalibration. Forecasts reflect assumptions on pharmacopeial monograph stability, smallholder cooperative supply continuity, and synthetic terpene cost trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Coleus and Turmeric Market
Spices and Seasonings
Africa Spice and Herb Extracts Market
Spices and Seasonings
Boutique Salt Market
Spices and Seasonings
Bay Leaf Market
Spices and Seasonings
Herbs and Spices Market
Spices and Seasonings
Asia-Pacific Spice and Herb Extracts Market
Spices and Seasonings
Plastic Spice Jars Market
Spices and Seasonings
Nutmeg Oil Market
Spices and Seasonings
Global Clove Market
Spices and Seasonings
Cardamom Market
Spices and Seasonings
Low Sodium Sea Salt Market
Spices and Seasonings
Green Pepper Market
Spices and Seasonings
Garlic Oil Market
Spices and Seasonings
Tamarind Extract Market
Spices and Seasonings
Paprika Powder Market
Spices and Seasonings
North America Seasonings Market