
 Turkey Flavors Market | 2026-2036
Turkey Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Flavors Market Analytics
Premium clean-label specifications is redrawing competitive boundaries in turkey flavors. Kerry Group leverages vertical integration from raw material sourcing to finished seasoning blends. McCormick sustains brand strength through retail channel dominance and consumer recognition. Cargill anchors its position with manufacturing scale across multiple protein flavoring categories.
Turkey flavors encompass volatile and non-volatile compounds formulated to replicate or enhance the sensory profile of cooked turkey meat, typically delivered through Maillard reaction-derived pyrazines, lipid oxidation products, and added savory nucleotides. These formulations serve industrial meat processors and foodservice operators seeking consistent flavor replication across high-volume production runs. Liquid flavoring leads volume shipments due to ease of incorporation into brines and injection marinades, while dry seasoning commands margin premiums in retail and foodservice channels. Ready-to-eat meals represents the fastest-growing application as convenience-oriented protein products expand shelf space. Smoky and savory profiles dominate commercial formulations, though herbaceous variants gain traction in health-positioned product lines.
The USDA and FDA jointly govern turkey flavor labeling, with the USDA's Food Safety and Inspection Service overseeing meat product applications and the FDA regulating standalone flavor additives under 21 CFR 101.22. FSSAI standards in India and EFSA flavoring regulations in Europe create divergent compliance pathways for multinational suppliers. Stakeholders must monitor evolving natural flavor definitions and regional enforcement intensity to align R&D investment with compliant formulation strategies.
Market Dynamics
Clean-label ingredient declarations under USDA and FDA oversight are compressing formulation flexibility for turkey flavor suppliers, forcing R&D investment toward natural extraction methods and transparent supply chain documentation.
Growth Catalysts
- FSMA traceability mandates:The FDA's Food Safety Modernization Act rules for record-keeping are accelerating adoption of documented natural flavor sourcing, favoring suppliers with captive raw material networks.
- Ready-to-eat meal expansion:Foodservice operators and retail delis are scaling pre-cooked turkey protein SKUs, driving bulk procurement of consistent savory flavor systems.
- Southeastern processing concentration:Poultry slaughter and further-processing facilities cluster in Georgia, North Carolina, and Arkansas, creating dense demand nodes for regional seasoning distributors.
Market Restraints
- Natural extract cost volatility:Yeast extract and hydrolyzed vegetable protein prices fluctuate with agricultural commodity cycles, compressing margins on clean-label formulations.
- Single-source oleoresin dependency:Critical savory precursors for turkey flavor synthesis concentrate among three dominant suppliers, creating supply vulnerability.
- 21 CFR 101.22 labeling friction:The FDA's natural versus artificial flavor definitions generate compliance ambiguity, slowing new product approvals and reformulation cycles.
Strategic Opportunities
- Plant-based turkey analogs:Meat alternative manufacturers in California and Pacific Northwest metro areas seek authentic poultry flavor replication for hybrid and fully vegan product lines.
- IRAct clean energy incentives:The Inflation Reduction Act's bio-based manufacturing tax credits support fermentation-derived flavor production facility expansion.
- Direct-to-foodservice distribution:Bypassing traditional broadline distributors, flavor houses are building captive sales teams targeting independent restaurant chains and regional QSR operators.
Industry Challenges
- Flavor chemist talent scarcity:Maillard reaction expertise and savory nucleotide formulation knowledge concentrate among retiring specialists, constraining R&D throughput.
- Multi-jurisdiction certification lag:Achieving parallel USDA organic, Non-GMO Project, and SQF certifications extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Flavors Market |
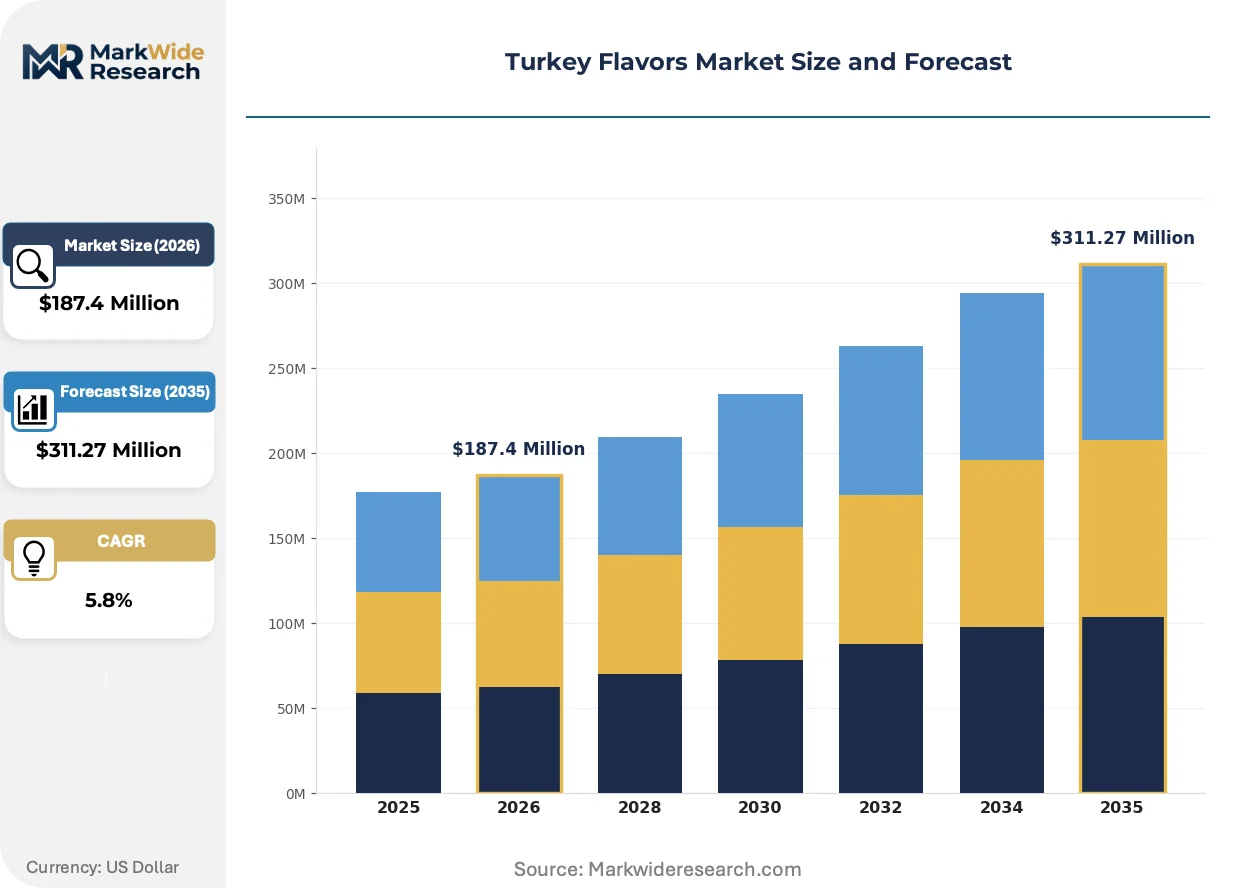
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Flavoring, Dry Seasoning, Flavor Enhancers, Marinades Application: Home Cooking, Food Processing, Foodservice, Ready-to-Eat Meals End User: Households, Restaurants, Catering Services, Manufacturers Flavor Profile: Smoky, Spicy, Savory, Herbaceous |
| Companies Covered | Kerry Group, McCormick, Cargill, International Flavors & Fragrances, Archer Daniels Midland, BASF, Takasago International Corporation, Wyler's, Casa M Spice Co, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Flavors Market Evolving Landscape
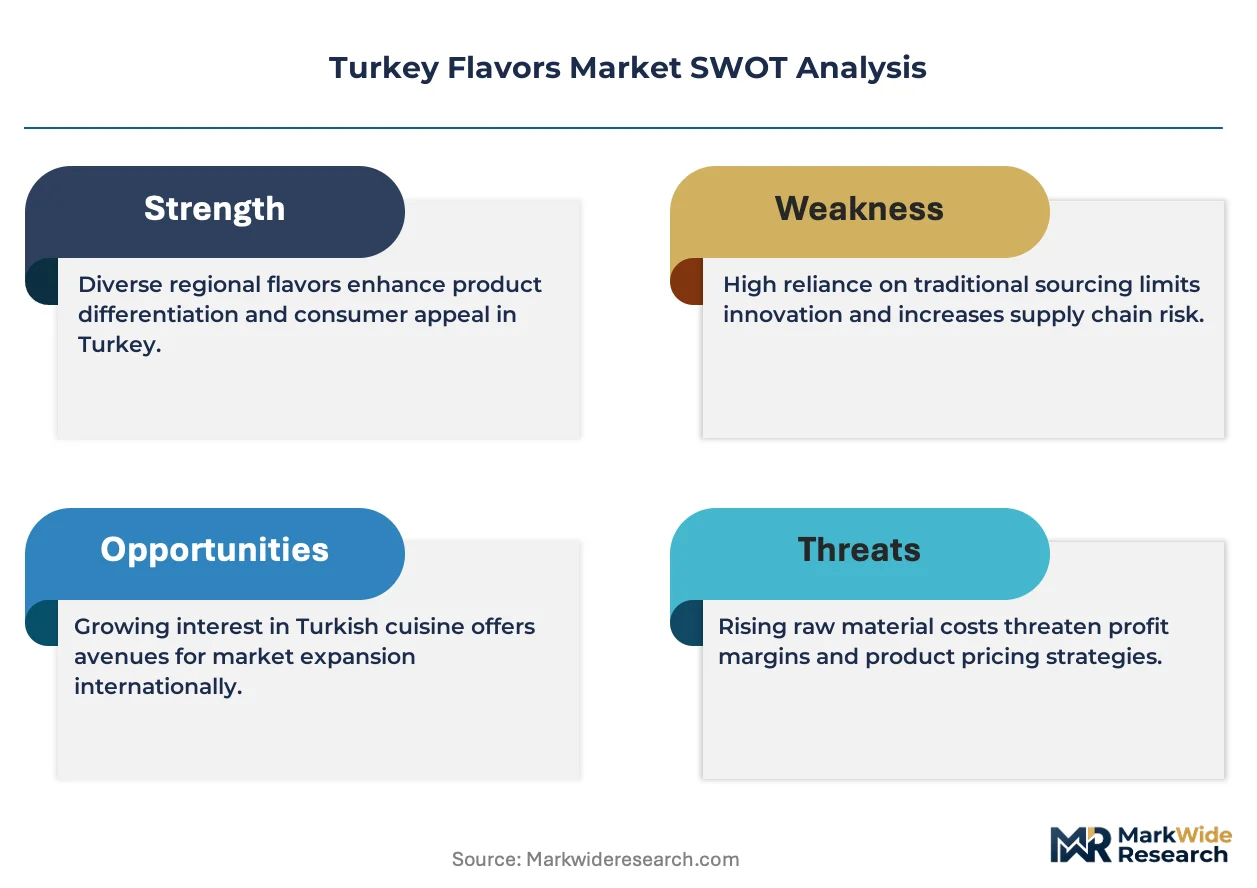
Biotechnology-derived flavor precursors and precision fermentation are redrawing ingredient sourcing maps, while regulatory tightening on natural claims forces transparency investments across the supplier base.
Fermentation-based savory nucleotides and pyrazine compounds are supplanting traditional thermal process flavors in premium clean-label formulations. Mid-sized meat processors in the Midwest and Mid-Atlantic regions are piloting these inputs at 15-20% volume substitution rates. This shift is compressing demand for conventional reaction flask production capacity and redirecting capital toward bioreactor infrastructure.
The FDA's updated guidance on "natural flavor" substantiation requirements is forcing suppliers to document extraction methods and raw material provenance. Industrial consequence includes mandatory supply chain audits and third-party verification costs that disproportionately burden smaller seasoning houses. Wet brine and injection marinade applications face the tightest scrutiny, with several regional processors accelerating reformulation timelines to preempt enforcement actions.
Foodservice procurement teams are consolidating vendor relationships from 8-12 flavor suppliers per protein category to 3-4 strategic partners with full formulation capabilities. This concentration is displacing single-ingredient commodity traders and favoring integrated seasoning houses that deliver finished blends, technical service, and regulatory documentation. The shift is most visible among multi-unit restaurant chains operating across Texas, Florida, and Ohio, where procurement centralization has advanced furthest.
Turkey Flavors Market Segmentation
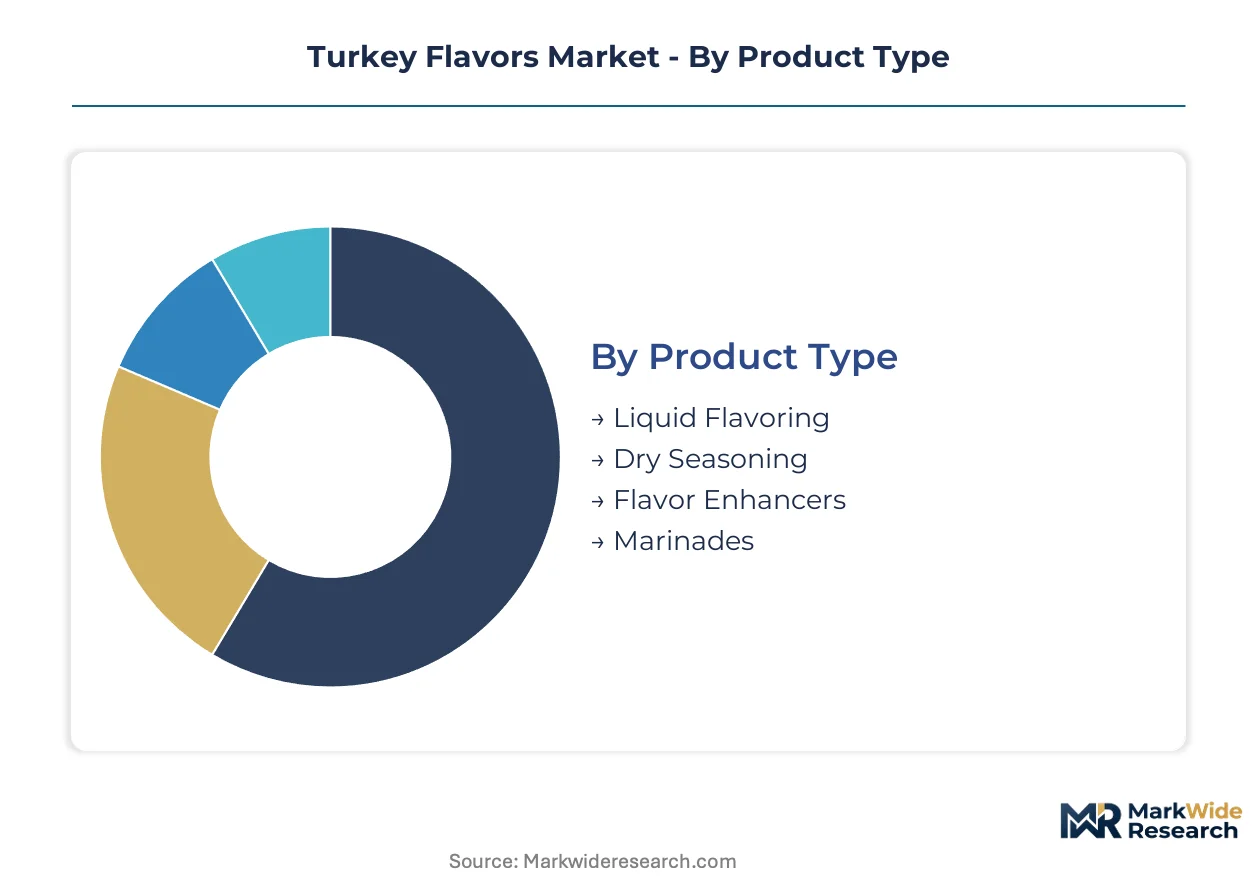
Turkey flavor suppliers allocate R&D and production assets unevenly across segment boundaries. Margin capture varies sharply by formulation complexity, regulatory exposure, and customer concentration.
Product Type:
Liquid formulations command the widest margin spreads due to technical barriers in brine stability and injection compatibility.
- Liquid Flavoring:Emulsion-based concentrates designed for brine incorporation and vacuum tumbling operations. Poultry processors in Georgia and North Carolina drive procurement volume for this format, prioritizing batch-to-batch consistency in high-speed injection lines.
- Dry Seasoning:Granular blends of salt, hydrolyzed proteins, and Maillard-reaction precursors. Retail and foodservice channels absorb this format at premium pricing, with independent restaurant chains in Texas and Florida consolidating purchases around finished blend suppliers.
- Flavor Enhancers:Purified nucleotides and yeast extracts delivering umami amplification without added sodium.
- Marinades:Pre-hydrated systems combining acid, oil, and aromatic compounds for surface application.
Liquid flavoring holds installed capacity. Dry seasoning is rotating up the share rankings.
Application:
Volume concentrates in industrial processing, though value migrates toward convenience-oriented finished goods.
- Ready-to-Eat Meals:Pre-cooked turkey protein for retail delis and foodservice heat-and-serve programs. Chains operating across the southeastern United States are expanding SKU counts in this category, requiring flavor systems that survive retort and sous-vide processing without degradation.
- Food Processing:Bulk seasoning for slaughter and further-processing facilities. The USDA's FSIS oversight of meat product labeling forces documented natural flavor sourcing, favoring suppliers with captive extraction capabilities.
- Foodservice:Custom blends for independent restaurants and regional QSR operators.
- Home Cooking:Retail bottles and packets for consumer pantry stocking.
Food processing anchors volume throughput. Ready-to-eat meals are climbing the fastest.
End User:
Procurement sophistication separates industrial buyers from fragmented foodservice and household accounts.
- Manufacturers:Industrial meat processors with technical staff evaluating flavor performance against yield, shelf life, and label claim requirements. These buyers negotiate multi-year supply agreements with integrated seasoning houses capable of delivering regulatory documentation packages.
- Restaurants:Multi-unit chains and independent operators seeking signature profile differentiation. Procurement centralization among Texas and Florida-based chains is compressing vendor counts from commodity traders toward full-service flavor partners.
- Catering Services:Volume buyers with limited technical specification capacity.
- Households:Price-sensitive retail consumers with minimal formulation input.
Manufacturers hold installed capacity. Restaurants are rotating up the share rankings.
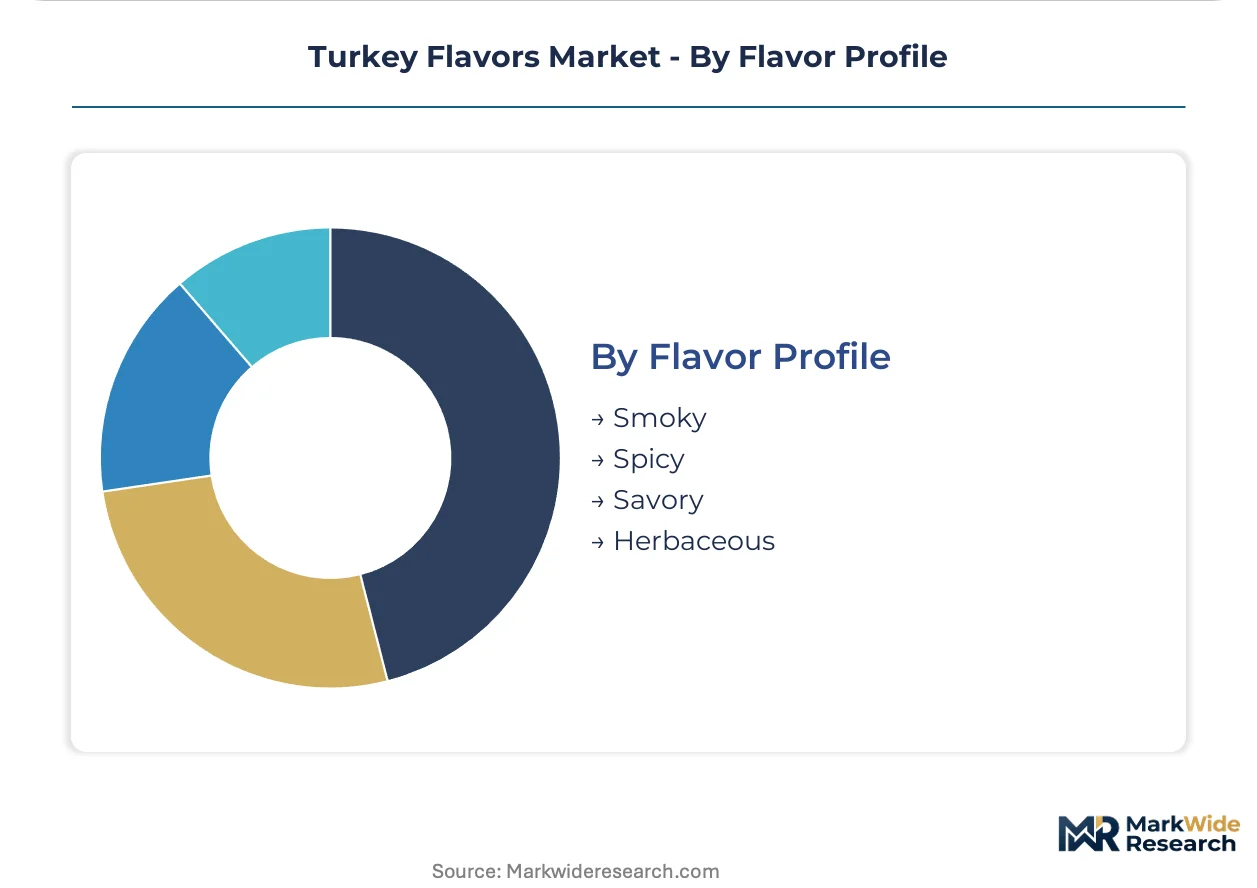
Flavor Profile:
Profile selection maps directly to end-use positioning and permissible ingredient declarations.
- Savory:Pyrazine-dominant formulations replicating roasted turkey depth through Maillard-derived compounds. Clean-label positioning in premium retail and foodservice channels drives yeast extract and fermentation-based nucleotide substitution for hydrolyzed protein bases.
- Smoky:Liquid smoke and natural smoke flavor applications for processed turkey products. The FDA's 21 CFR 101.22 natural flavor definitions create compliance friction for synthetic smoke alternatives, accelerating documented hickory and mesquite wood sourcing.
- Herbaceous:Rosemary, sage, and thyme oleoresin blends targeting health-positioned product lines.
- Spicy:Capsicum-derived heat systems for regional flavor differentiation.
Savory holds installed capacity. Herbaceous is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a structural surplus in turkey flavor exports to Canada and Mexico under USMCA provisions, while importing specialized European savory precursors to satisfy clean-label formulation demand. Import dependency concentrates on yeast extract and fermentation-derived nucleotides from German and Dutch suppliers.
United States
Poultry processing clusters in Georgia and Arkansas drive bulk liquid flavor procurement for injection and brine applications. The USDA's FSIS oversees natural flavor declarations in meat products, tightening documentation requirements for Maillard-derived compounds. Charlotte and Atlanta anchor southeastern distribution networks where regional seasoning houses compete for multi-year supply contracts with integrated processors.
Germany
Industrial bakeries and meat processors in Bavaria and North Rhine-Westphalia absorb yeast extract and hydrolyzed protein volumes for savory flavor systems. The EFSA flavoring regulations govern natural versus process-derived distinctions, creating compliance friction for thermal reaction flavors. Frankfurt's ingredient trading hub concentrates procurement offices for Central European meat manufacturers seeking documented supply chain transparency.
China
Domestic poultry processors in Shandong and Guangdong provinces scale flavor enhancement for ready-to-eat meal exports to Southeast Asia. The SAMR implements GB standards for food additive labeling, aligning with Codex Alimentarius frameworks for natural flavor substantiation. Qingdao's port infrastructure supports oleoresin importation from India and Southeast Asia for local compounding operations.
Brazil
Poultry exporters in São Paulo and Paraná states procure savory flavor systems to meet destination-country clean-label requirements in the European Union and United Kingdom. ANVISA regulates flavor additive safety assessments, requiring toxicological documentation for novel fermentation-derived ingredients. Campinas hosts technical service operations for multinational flavor houses serving Mercosur meat processors.
India
Processed food manufacturers in Maharashtra and Gujarat integrate turkey flavor analogs into snack and instant noodle applications for domestic and Middle Eastern markets. FSSAI standards distinguish natural extracts from synthetic flavorings, mandating source disclosure on packaged goods labels. Mumbai's ingredient distribution corridor channels imported savory precursors from European and Southeast Asian suppliers to regional compounders.
Turkey Flavors Market Competitive Landscape
Listed leaders compete with private specialists across formulation complexity and regulatory documentation capabilities. The supplier base concentrates around integrated seasoning houses with captive extraction infrastructure and commodity traders lacking technical service depth. Three archetypes dominate: vertically integrated multinationals with fermentation capacity, regional blend specialists serving single protein categories, and single-ingredient traders dependent on third-party compounding. Competitive moves center on backward integration into raw material sourcing and direct-to-foodservice distribution bypassing broadline networks.
Within the integrated multinational tier, Kerry Group and McCormick occupy positions defined by captive supply networks and retail channel penetration respectively. Cargill anchors the scale-driven segment with cross-protein flavor manufacturing infrastructure. These three entities exemplify divergent strategic postures: Kerry Group represents backward integration into raw material sourcing, McCormick exemplifies brand equity monetization through consumer-facing distribution, and Cargill sits within diversified agricultural processing conglomerates leveraging commodity flow advantages.
| Leading Market Players |
|---|
| Kerry Group |
| McCormick |
| Cargill |
| International Flavors & Fragrances |
| Archer Daniels Midland |
| BASF |
| Takasago International Corporation |
| Wyler's |
| Casa M Spice Co |
| Others |
Value Network & Pricing Analysis
Multi-year offtake agreements between Georgia-based poultry processors and regional seasoning houses lock in Maillard-reaction precursor supply while stabilizing input cost visibility against agricultural commodity swings. These contracts embed volume commitments that cascade backward to yeast extract suppliers in Germany and the Netherlands, compressing spot market liquidity for clean-label formulations.
Pricing Analysis
Industrial OEM buyers anchor contract structures around three-tier pricing separation across premium clean-label, standard natural, and economy synthetic tiers. Price differentiation rests on USDA organic certification status and captive extraction capabilities, with premium tiers commanding substantial uplifts for documented supply chain transparency. Cost compression in standard-tier formulations is intensifying because yeast extract and hydrolyzed vegetable protein prices fluctuate with agricultural cycles. Small independent restaurant chains exhibit highest price sensitivity, while integrated meat processors with technical staff demonstrate lowest sensitivity due to yield and shelf-life performance requirements.
Supply Chain Analysis
Single-source oleoresin dependency for critical savory precursors concentrates among three dominant suppliers, creating acute vulnerability for mid-sized seasoning houses. Raw material sourcing draws from Germany and the Netherlands for fermentation-derived nucleotides, India for spice oleoresins, and domestic agricultural bases for hydrolyzed proteins. Tariff exposure on European savory precursors compounds margin pressure for clean-label formulators. Distribution runs through southeastern U.S. processing clusters in Georgia and North Carolina, with regional distributors competing for captive logistics contracts with integrated poultry facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise for Maillard-reaction optimization and savory nucleotide balancing concentrates among retiring specialists, constraining R&D throughput and creating asymmetric capability advantages for employers with structured knowledge-transfer programs.
For Market Incumbents: Consolidate backward into captive yeast extract and fermentation capacity to secure precursor supply against agricultural commodity volatility and single-source oleoresin dependency. Acquire regional blend specialists in Texas and Florida to preempt procurement centralization among multi-unit restaurant chains. Kerry Group's vertical posture and McCormick's retail channel dominance illustrate divergent consolidation pathways. For New Entrants and Emerging Players: USDA organic certification fast-track programs in the southeastern United States open white-space entry for fermentation-based savory nucleotide suppliers targeting mid-sized Midwest meat processors piloting 15-20% volume substitution rates. California and Pacific Northwest plant-based turkey analog manufacturers represent the most penetrable segment, seeking authentic poultry flavor replication without incumbent supply relationships. Direct-to-foodservice distribution bypassing broadline networks offers the clearest go-to-market angle. For Investors and Strategic Acquirers: Regional blend specialists with single-protein category focus and documented natural flavor sourcing capabilities represent the most defensible acquisition archetype for portfolio exposure to clean-label tailwinds. Long-term viability hinges on bioreactor infrastructure deployment and fermentation-derived ingredient pipelines displacing conventional thermal process capacity. Watch FDA enforcement intensity on 21 CFR 101.22 natural flavor substantiation as the critical inflection signal for valuation compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Bioreactor infrastructure redirects capital from thermal reaction flask production toward biotechnology-derived savory precursors. |
| Backward Integration into Yeast Extract | Captive sourcing secures Maillard-reaction inputs against agricultural commodity price volatility and supply interruption. |
| Direct-to-Foodservice Distribution | Bypassing broadline distributors captures margin from independent restaurant chains and regional QSR procurement centralization. |
| USDA Organic Certification Investment | Documented supply chain transparency commands premium pricing tiers and preempts enforcement action on natural claims. |
| Regulatory Documentation Partnership | Integrated seasoning houses with FSMA traceability capabilities displace commodity traders in vendor consolidation trends. |
Research Methodology
Initial hypotheses were tested against primary input from flavor chemists at integrated seasoning houses, procurement directors at southeastern poultry processors, regulatory affairs specialists navigating USDA FSIS and FDA 21 CFR 101.22 requirements, and technical service managers at fermentation-derived ingredient suppliers, then refined against secondary validation from FDA guidance documents, USDA FSIS labeling directives, EFSA flavoring regulations, FSSAI standards, trade flow data through USMCA corridors, and SEC filings from publicly traded flavor houses. Bottom-up segment sizing and top-down macro constraint triangulation anchored volume and value estimates.
Variance decomposition across product type, application, end user, and flavor profile dimensions isolated growth contribution by segment over the projection horizon. CAGRs were derived from modeled segment trajectories incorporating regulatory enforcement intensity assumptions, clean-label penetration curves, and biotechnology substitution rates. Forecast inputs included poultry processing capacity expansion in Georgia and Arkansas, fermentation facility buildout under IRA bio-based manufacturing incentives, and foodservice procurement centralization patterns among Texas and Florida multi-unit chains.
Decision-makers should treat outputs as directional under base assumptions of sustained clean-label demand and stable regulatory enforcement intensity; material deviation in FDA natural flavor substantiation requirements or agricultural commodity price spikes would warrant model refresh. Practitioners should keep alternative scenarios live as biotechnology-derived precursor cost curves and plant-based turkey analog adoption rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
North American Seasonings and Spices Market
Spices and Seasonings
Cinnamon Market
Spices and Seasonings
Oregano Oil Market
Spices and Seasonings
Coleus and Turmeric Market
Spices and Seasonings
Mullein Leaf Market
Spices and Seasonings
Smoked Black Pepper Market
Spices and Seasonings
Organic Spice Market
Spices and Seasonings
Wild Cherry Powder Market
Spices and Seasonings
Carthamus Yellow Market
Spices and Seasonings
Bay Leaf Market
Spices and Seasonings
North America Seasonings Market
Spices and Seasonings
Spices Market
Spices and Seasonings
Europe Spice and Herb Extracts Market
Spices and Seasonings
Himalayan Salt Market
Spices and Seasonings
Glass Spice Jars Market
Spices and Seasonings
South America Seasoning and Spices Market