
 Thyme Extract Market | 2026-2036
Thyme Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Thyme Extract Market Analytics
EU REACH compliance is recalibrating extraction solvent documentation and residue thresholds for European suppliers. Symrise AG leverages captive thyme cultivation in Spain to sustain vertical control over raw material quality. Givaudan SA anchors its competitive position through specialized fractionation technology for high-purity thymol isolation. Martin Bauer Group dominates the organic-certified segment with long-term contracts across Alpine growing cooperatives.
Thyme extract comprises volatile oils, phenolic compounds, and flavonoids derived from Thymus vulgaris through steam distillation, solvent extraction, or supercritical CO2 processing, yielding standardized thymol concentrations between 20% and 80% for industrial use. Oil formulations lead in revenue contribution due to concentrated active content and extended shelf stability in flavor applications. Powder grades represent the fastest-expanding product type as nutraceutical manufacturers seek flowable, tableting-ready inputs with precise thymol standardization. Liquid extracts retain mature demand in pharmaceutical tincture preparations where alcohol-based solubility remains functionally necessary.
FDA dietary supplement GMPs and EMA herbal medicine directives jointly determine extract purity benchmarks and label claim substantiation for cross-Atlantic trade. USDA organic certification and EU organic regulation create parallel verification tracks that segment price tiers by cultivation method. BIS quality standards for herbal raw materials in India add a third compliance layer for suppliers targeting export manufacturing. Stakeholders must monitor evolving monograph revisions across these jurisdictions to preempt reformulation costs and secure uninterrupted market access.
Market Dynamics
EMA herbal monograph revisions are compressing supplier qualification timelines while concentrating procurement power among vertically integrated botanical extractors capable of certifying thymol standardization across multiple solvent residues.
Growth Catalysts
- Cosmetic clean-label mandates:L'Oréal and Estée Lauder procurement teams now require thymol traceability to specific Mediterranean cooperatives, pulling premium oil volumes through certified channels.
- Supercritical CO2 extraction adoption:This solvent-free process eliminates REACH documentation burdens for residue thresholds while yielding higher carvacrol retention for pharmaceutical-grade applications.
- India's AYUSH export push:The Ministry of AYUSH subsidizes GMP certification for thyme extractors targeting European nutraceutical contract manufacturers.
Market Restraints
- Wild thyme harvest volatility:Moroccan and Albanian wild collection faces climate-induced yield swings, forcing formulators to maintain six-month safety stocks.
- Thymol synthesis competition:Synthetic thymol from petrochemical feedstocks undercuts natural extract pricing in industrial disinfectant applications.
- EU REACH authorization delays:Ethanol and hexane solvent re-authorizations stretch 18-24 months, freezing capacity expansion for mid-scale extractors.
Strategic Opportunities
- Japanese functional food integration:FOSHU approval pathways for thymol-fortified beverages remain underexploited by European suppliers.
- Veterinary feed additive substitution:EU ban on zinc oxide in piglet feed creates demand for thymol-based gut health alternatives.
- Blockchain provenance platforms:Distributed ledger verification from Alpine harvest to final formulation commands 15-20% price premiums in cosmetic channels.
Industry Challenges
- Analytical chemist scarcity:Gas chromatography-mass spectrometry specialists capable of validating terpene profiles against EMA monographs command salaries exceeding mid-tier extractor margins.
- Multi-jurisdiction label harmonization:Reconciling FDA structure-function claims with EMA traditional use registrations requires parallel clinical documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thyme Extract Market |
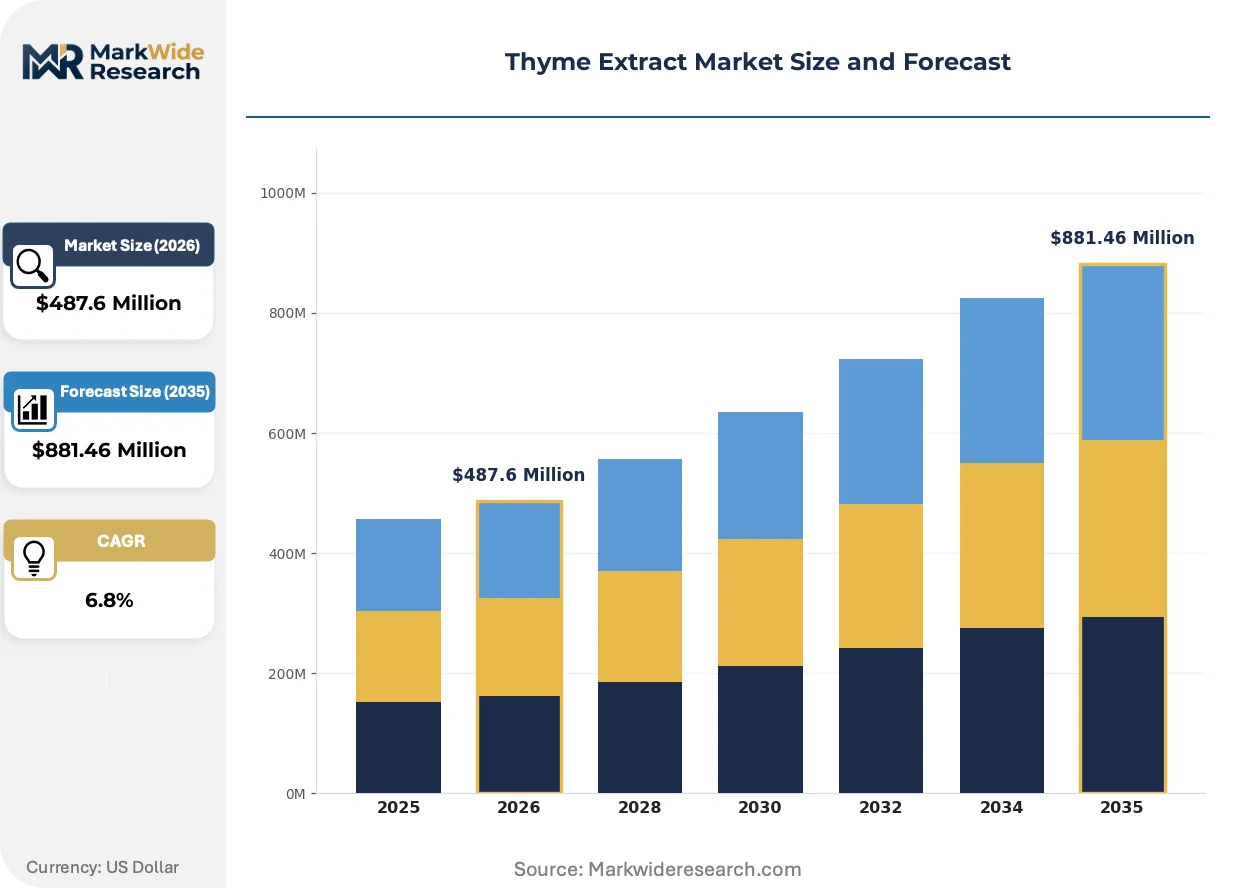
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil, Powder, Tincture, Liquid Application: Food & Beverages, Cosmetics, Pharmaceuticals, Nutraceuticals Form: Organic, Conventional, Wildcrafted, Standardized End User: Food Manufacturers, Cosmetic Companies, Health Stores, Research Institutions |
| Companies Covered | Symrise AG, Givaudan SA, Kalsec Inc., Firmenich SA, Martin Bauer Group, Doehler Group, Synthite Industries Ltd., Penta Manufacturing Company, Treatt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thyme Extract Market Evolving Landscape
Extraction technology convergence with digital quality assurance is compressing batch-to-batch variability while enabling real-time thymol potency verification at contract manufacturing sites.
Supercritical CO2 extraction systems with inline near-infrared spectroscopy are automating thymol concentration standardization during processing. Pharmaceutical contract manufacturers in Germany and Switzerland now require this capability for master batch record integration. The technology is automating quality release decisions that previously required 72-hour laboratory hold times.
EU REACH Annex XVII updates on residual solvent limits are forcing reformulation of alcohol-based tinctures toward glycerite alternatives. French and Italian extractors face 12-18 month revalidation cycles for existing product registrations. Powder-grade suppliers with spray-drying capabilities capture volume shifting from liquid extract discontinuations.
Direct sourcing contracts between cosmetic houses and Alpine growing cooperatives are displacing multi-tier botanical traders. L'Oréal's Grasse-based procurement team now maintains direct relationships with five Provence distillation clusters. This channel consolidation concentrates price-setting power among harvesters with organic and Demeter dual certification.
Thyme Extract Market Segmentation
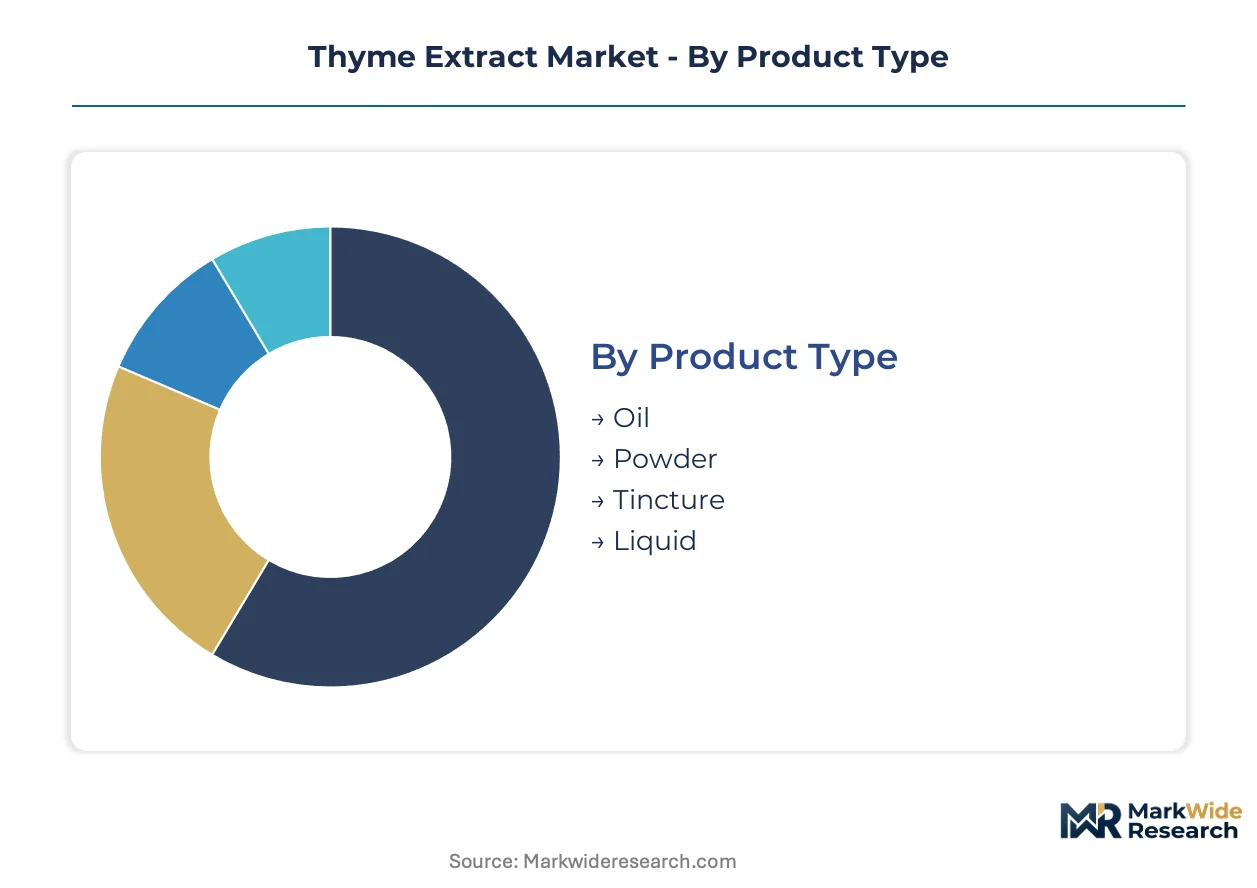
Thyme extract segmentation reveals distinct value capture patterns across product formats and end-use specifications. Formulators select grades based on thymol concentration thresholds, solvent residue limits, and certification requirements that vary by application channel.
Product Type:
Integration depth varies sharply: oils and tinctures serve as standalone finished ingredients, while powders embed into complex formulations requiring precise flow characteristics.
- Oil:Concentrated volatile oil delivers 20-80% standardized thymol content through steam distillation or supercritical CO2 processing. Cosmetic houses in France's Provence-Alpes-Côte d'Azur region source directly from artisanal distillation clusters for premium fragrance and preservative applications.
- Powder:Spray-dried or encapsulated formats provide tableting-ready inputs with precise thymol standardization for nutraceutical manufacturers. Demand is accelerating most quickly here as contract manufacturers automate high-speed tablet production lines.
- Tincture:Alcohol-based liquid preparations retain function in pharmaceutical applications where solubility requirements mandate ethanol carriers.
- Liquid:Aqueous or glycerite solutions serve food and beverage fortification where oil dispersion creates formulation challenges.
Volume placements concentrate in Oil; the steepest expansion trajectory belongs to Powder.
Application:
Cost tier stratification separates commodity flavor inputs from certified pharmaceutical and cosmetic grades commanding substantial premia.
- Food & Beverages:Flavor and natural preservative applications in seasoning blends and functional beverages. German and Italian processors drive specification tightening for clean-label positioning.
- Cosmetics:Antimicrobial and antioxidant active in skincare formulations. L'Oréal and Estée Lauder procurement teams now require thymol traceability to specific Mediterranean cooperatives, pulling premium volumes through certified channels.
- Pharmaceuticals:Traditional herbal medicine and botanical API sourcing under EMA monograph compliance. German formulators are expanding botanical API procurement as quality benchmarks tighten.
- Nutraceuticals:Dietary supplement inputs for immune and respiratory support claims. India's Ministry of AYUSH subsidizes GMP certification for extractors targeting European contract manufacturers.
Revenue concentration sits with Cosmetics; Nutraceuticals is gaining share fastest.
Form:
Supply concentration patterns differentiate cultivation-based from collection-based sourcing, with certification complexity determining accessible customer tiers.
- Organic:Cultivated under USDA or EU organic regulation with full traceability documentation. Martin Bauer Group dominates this segment through long-term contracts across Alpine growing cooperatives.
- Conventional:Standard cultivated grades without organic certification, serving cost-sensitive industrial applications. Symrise AG leverages captive thyme cultivation in Spain to sustain upstream control over conventional raw material quality.
- Wildcrafted:Harvested from native stands in Morocco and Albania, facing climate-induced yield volatility that forces formulators to maintain extended safety stocks.
- Standardized:Guaranteed thymol or carvacrol content through analytical verification, required for pharmaceutical and nutraceutical master batch records.
Procurement volumes cluster in Conventional; the premium expansion channel is Organic.
End User:
Customer type determines specification stringency, with direct manufacturer relationships displacing distributor intermediaries in high-value segments.
- Food Manufacturers:Industrial-scale processors of seasonings, sauces, and functional beverages. These buyers prioritize batch consistency and cost optimization over certification complexity.
- Cosmetic Companies:Premium skincare and fragrance houses requiring dual organic-Demeter certification. Direct sourcing contracts between cosmetic houses and Alpine cooperatives are displacing multi-tier botanical traders.
- Health Stores:Retail and e-commerce channels for consumer-facing supplement brands. These customers demand finished-product testing documentation and transparent supply chain narratives.
- Research Institutions:Academic and clinical trial sponsors investigating thyme extract bioactivity. This segment requires highest analytical rigor including full terpene profiling and solvent residue certificates.
Transaction volumes dominate through Food Manufacturers; margin expansion concentrates with Cosmetic Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical formulators in Germany drive concentrated demand for EMA-compliant botanical APIs. Cosmetic procurement teams in France's Provence-Alpes-Côte d'Azur region source directly from artisanal distillation clusters. India's AYUSH export subsidies are reshaping supplier qualification timelines for European nutraceutical contract manufacturers.
Germany
Pharmaceutical formulators in Baden-Württemberg and Bavaria expand botanical API sourcing as EMA herbal monographs tighten quality benchmarks. Germany's Federal Institute for Drugs and Medical Devices enforces thymol standardization documentation for traditional use registrations. The Rhine-Main cluster hosts analytical laboratories capable of validating terpene profiles against evolving monograph requirements.
France
Cosmetic houses in Grasse and Paris demand thymol traceability to specific Mediterranean cooperatives for clean-label positioning. ANSM oversees cosmetic ingredient safety assessments under EU Cosmetics Regulation. The Provence-Alpes-Côte d'Azur region concentrates artisanal distillation capacity supplying premium fragrance and preservative applications.
Spain
Captive thyme cultivation in Castilla-La Mancha sustains upstream control over raw material quality for flavor and fragrance applications. REACH compliance documentation from Spanish suppliers eliminates residue threshold disputes with German pharmaceutical buyers. The Murcia agricultural belt develops organic-certified cultivation for cosmetic channel premiums.
India
The Ministry of AYUSH subsidizes GMP certification for extractors targeting European nutraceutical contract manufacturers. BIS quality standards for herbal raw materials add compliance layers for export manufacturing. Karnataka and Tamil Nadu processing clusters automate high-speed tablet production lines for powder-grade thyme extract.
Switzerland
Swissmedic's traditional herbal medicine framework attracts master batch record integration from German pharmaceutical contract manufacturers. Alpine growing cooperatives in Valais and Graubünden supply organic-certified material under long-term procurement contracts. Zurich-based analytical services validate supercritical CO2 extraction outputs for real-time quality release.
Thyme Extract Market Competitive Landscape
European producers anchor the premium-certified tier; Indian specialists hold volume positions in conventional grades. The vendor base stratifies across vertically integrated botanical extractors, captive cultivation operators, and regional fractionation technology providers. Three archetypes dominate: organic-certified Alpine cooperatives, supercritical CO2 technology specialists, and spray-drying powder-grade suppliers. Competitive moves concentrate on direct sourcing contract displacement of multi-tier traders and REACH-compliant solvent-free process adoption.
Within the European premium tier, Symrise AG and Givaudan SA occupy positions exemplifying upstream control strategies. Martin Bauer Group represents the organic-certified cooperative archetype through Alpine supply relationships. These three companies illustrate the geographic and certification-based segmentation defining competitive positioning in EMA-compliant and cosmetic-grade channels.
| Leading Market Players |
|---|
| Symrise AG |
| Givaudan SA |
| Kalsec Inc. |
| Firmenich SA |
| Martin Bauer Group |
| Doehler Group |
| Synthite Industries Ltd. |
| Penta Manufacturing Company |
| Treatt |
| Others |
Value Network & Pricing Analysis
Thyme oil spot benchmarks in the Mediterranean basin cascade through extraction tiers into three pricing levels determined by thymol standardization and certification depth. EMA herbal monograph compliance costs compress margins for mid-scale extractors while concentrating procurement leverage among vertically integrated operators with captive cultivation.
Pricing Analysis
Volume placements cluster in conventional grades where per-unit margins remain thin, while premium-certified organic and pharmaceutical-grade tiers capture disproportionate value. Price differentiation hinges on dual organic-Demeter certification and REACH-compliant solvent documentation, with cosmetic houses in France showing lowest price sensitivity. Cost compression in industrial disinfectant applications intensifies as synthetic thymol from petrochemical feedstocks undercuts natural extracts. Food manufacturers exhibit highest price sensitivity, prioritizing batch consistency over certification complexity.
Supply Chain Analysis
Freight cost volatility from Moroccan and Albanian wild collection zones forces formulators to maintain extended safety stocks, inflating working capital requirements. Supply concentrates in Spain's Castilla-La Mancha cultivation belt, France's Provence-Alpes-Côte d'Azur distillation clusters, and India's Karnataka processing hubs. Raw material flows draw from cultivated thyme stands, wild Moroccan harvests, and Alpine growing cooperatives. Single-source vulnerability in wildcrafted channels creates exposure to climate-induced yield swings. Distribution runs through direct sourcing contracts displacing multi-tier botanical traders in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA herbal monograph revisions are compressing supplier qualification timelines, forcing consolidation among extractors incapable of certifying thymol standardization across multiple solvent residues.
For Market Incumbents: Cement backward integration into captive cultivation to insulate against wild harvest volatility and synthetic thymol competition. Secure long-term contracts with Alpine growing cooperatives before direct sourcing relationships displace trader intermediaries entirely. Prioritize supercritical CO2 extraction capacity to eliminate REACH documentation burdens and accelerate quality release timelines. For New Entrants and Emerging Players: Capture veterinary feed additive substitution demand created by the EU zinc oxide ban in piglet nutrition, where regulatory compliance barriers remain lower than pharmaceutical channels. Target India's AYUSH-subsidized GMP certification pathway to access European nutraceutical contract manufacturing. Lead with spray-dried powder grades serving automated tablet production lines. For Investors and Strategic Acquirers: Distressed-cycle entries favor analytical-chemistry-capable mid-cap specialists in Germany and Switzerland facing margin pressure from EMA compliance costs. Five-to-ten-year viability depends on master batch record integration capabilities for pharmaceutical contract manufacturers. Watch for supercritical CO2 extraction system adoption rates as inflection signal for technology-based competitive separation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Symrise AG's Spanish captive thyme operations eliminate wild harvest volatility exposure. |
| Supercritical CO2 Capacity Expansion | German pharmaceutical contract manufacturers now mandate inline near-infrared spectroscopy for quality release. |
| Direct Sourcing Contract Establishment | L'Oréal's Grasse procurement team bypasses traders through Mediterranean cooperative relationships. |
| Dual Organic-Demeter Certification | Martin Bauer Group's Alpine contracts command 15-20% cosmetic channel premiums. |
| Spray-Drying Powder Grade Investment | India's Karnataka clusters automate high-speed tablet production for nutraceutical manufacturers. |
Research Methodology
EMA herbal monograph databases, REACH authorization filings, and EU organic certification registries formed the secondary backbone for extraction process and compliance benchmarking. Primary interviews with pharmaceutical formulators, cosmetic procurement leads, botanical extraction plant managers, and Alpine cooperative cultivation directors validated thymol standardization practices and pricing tier structures. Bottom-up volume estimates from identified supplier capacities were triangulated against top-down demand projections from end-use application segments.
Historical trendline analysis of thymol concentration standardization, solvent residue documentation, and certification adoption rates informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product format (oil, powder, tincture, liquid), application channel (cosmetics, pharmaceuticals, nutraceuticals, food and beverages), and cultivation method (organic, conventional, wildcrafted, standardized). CAGRs were derived from regression analysis of premium-grade pricing trajectories and volume displacement patterns from liquid to powder formats.
The model holds under stable EMA monograph implementation schedules; deviation in REACH solvent re-authorization timelines or synthetic thymol cost curves would shift capacity expansion patterns. Forecasts reflect documented assumptions regarding supercritical CO2 adoption rates and AYUSH subsidy continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Tamarind Extract Market
Spices and Seasonings
Boswellia Extract Market
Spices and Seasonings
Asafoetida Market
Spices and Seasonings
Organic Spice Market
Spices and Seasonings
Basil Essential Oil Market
Spices and Seasonings
Ghost Pepper Salt Market
Spices and Seasonings
Global Black Pepper Market
Spices and Seasonings
Oregano Seasoning Market
Spices and Seasonings
Green Pepper Market
Spices and Seasonings
All-Purpose Seasoning Market
Spices and Seasonings
Mustard Market
Spices and Seasonings
Wasabi Market
Spices and Seasonings
Asia-Pacific Seasoning and Spices Market
Spices and Seasonings
Chipotle Salt Market
Spices and Seasonings
Oregano Oil Market
Spices and Seasonings
Europe Seasoning and Spices Market