
 Dried Herbs Market | 2026-2036
Dried Herbs Market Size, Share, and Industry Trends Forecast 2026-2036
Dried Herbs Market Intelligence
Single-serve sachet bundling is pivoting buyer choice away from bulk jars toward portion-controlled, multi-herb variety packs in retail channels. McCormick & Company leverages its retail shelf presence to anchor premium sachet lines in North American supermarkets. Frontier Co-op differentiates through cooperative sourcing structures that sustain organic quality grade consistency across its distributed supplier network. Van Drunen Farms specializes in bulk dehydration scale, competing on manufacturing throughput for food manufacturer contracts.
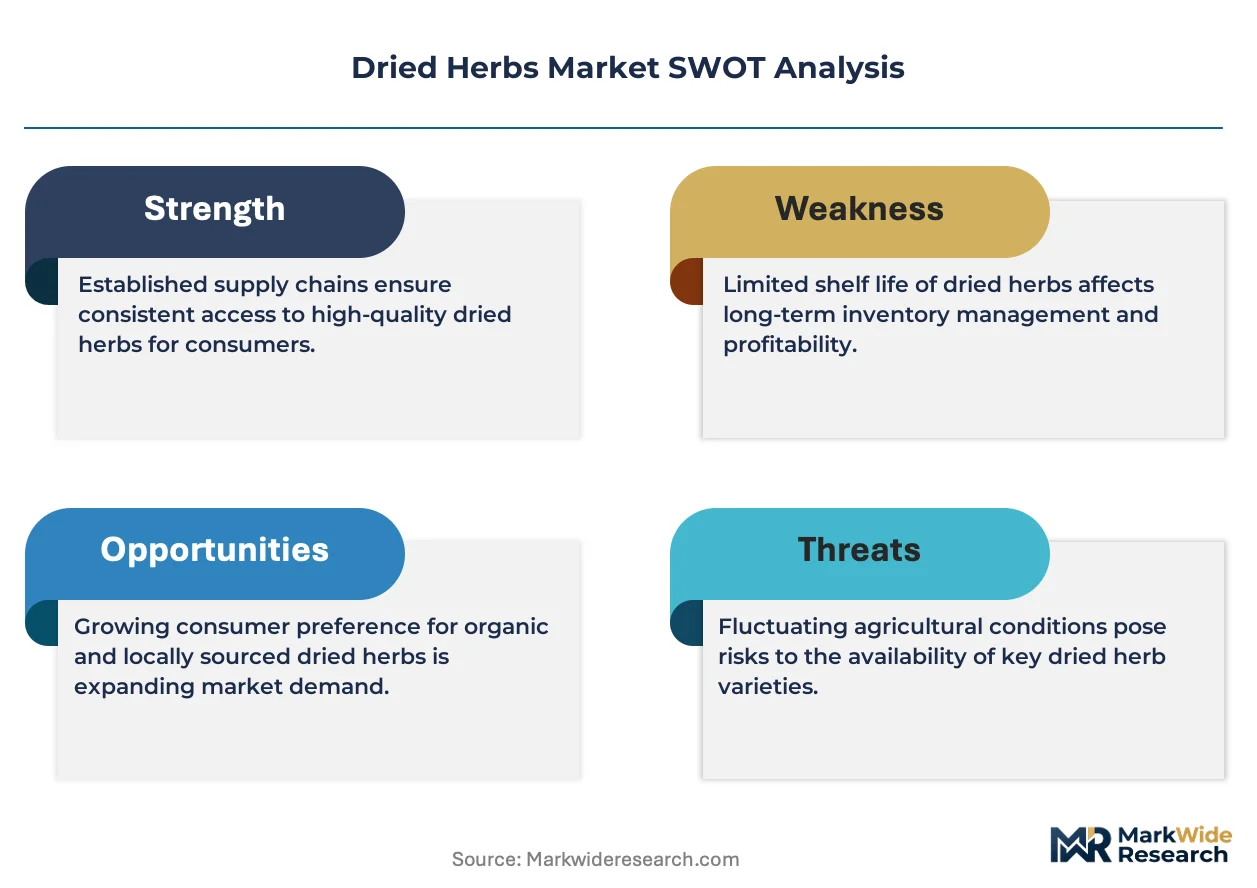
Dried herbs are plant materials preserved through controlled dehydration to moisture levels below 10 percent, maintaining volatile oil content for flavor, aroma, and antimicrobial function in food preparation. The primary commercial purpose centers on shelf-stable seasoning inputs that reduce perishability risk across restaurant, manufacturing, and home cooking environments. Basil and oregano occupy mature volume positions in pizza and pasta sauce manufacturing, while organic quality grade captures expanding margin pools as clean-label procurement intensifies among food manufacturers. Sachet packaging leads growth in direct-to-consumer channels where convenience and portion control override unit economics.
The FDA enforces Food Safety Modernization Act traceability requirements that compel lot-level tracking from field to finished dried herb product, elevating compliance costs for smaller dehydrators. USDA organic certification and ISO 22000 food safety management standards further gate market access for export-oriented suppliers. Stakeholders must monitor evolving mycotoxin threshold adjustments and emerging state-level pesticide residue limits that could reroute sourcing geography.
Market Dynamics
Clean-label procurement mandates from packaged food manufacturers are compressing supplier margins while elevating organic certification premiums across the value chain.
Growth Catalysts
- FSMA traceability compliance:The FDA's Food Safety Modernization Act rules are forcing lot-level digitization investments that favor scaled dehydrators with existing ERP infrastructure.
- Ready-to-eat meal formulation:Clean-label seasoning sachets in frozen and refrigerated prepared foods are displacing synthetic flavor systems in North American retail.
- Dehydration technology diffusion:Low-temperature vacuum drying systems are preserving volatile oil profiles previously lost to conventional hot-air methods.
Market Restraints
- Input cost volatility:Natural gas prices directly govern thermal dehydration economics, exposing margin-sensitive operators to energy market swings.
- Supply concentration risk:Premium organic basil and oregano sourcing clusters in specific Mediterranean and Californian growing districts.
- Regulatory friction:EU pesticide residue limits under EFSA oversight frequently diverge from USDA tolerances, complicating cross-Atlantic shipments.
Strategic Opportunities
- Direct-to-consumer channel expansion:Subscription herb sachet services are bypassing traditional retail slotting fees in United States metropolitan markets.
- Plant-based protein seasoning:Meat alternative manufacturers require antimicrobial herb blends to mask off-notes in pea and soy isolates.
- ISO 22000 certification arbitrage:Mid-tier dehydrators in emerging supply regions can capture food manufacturer contracts by front-running compliance investments.
Industry Challenges
- Organic certification timeline compression:Three-year land conversion requirements strain working capital for growers transitioning from conventional cultivation.
- Mycotoxin testing infrastructure:Aflatoxin and ochratoxin detection capacity bottlenecks at smaller dehydration facilities delay lot release.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dried Herbs Market |
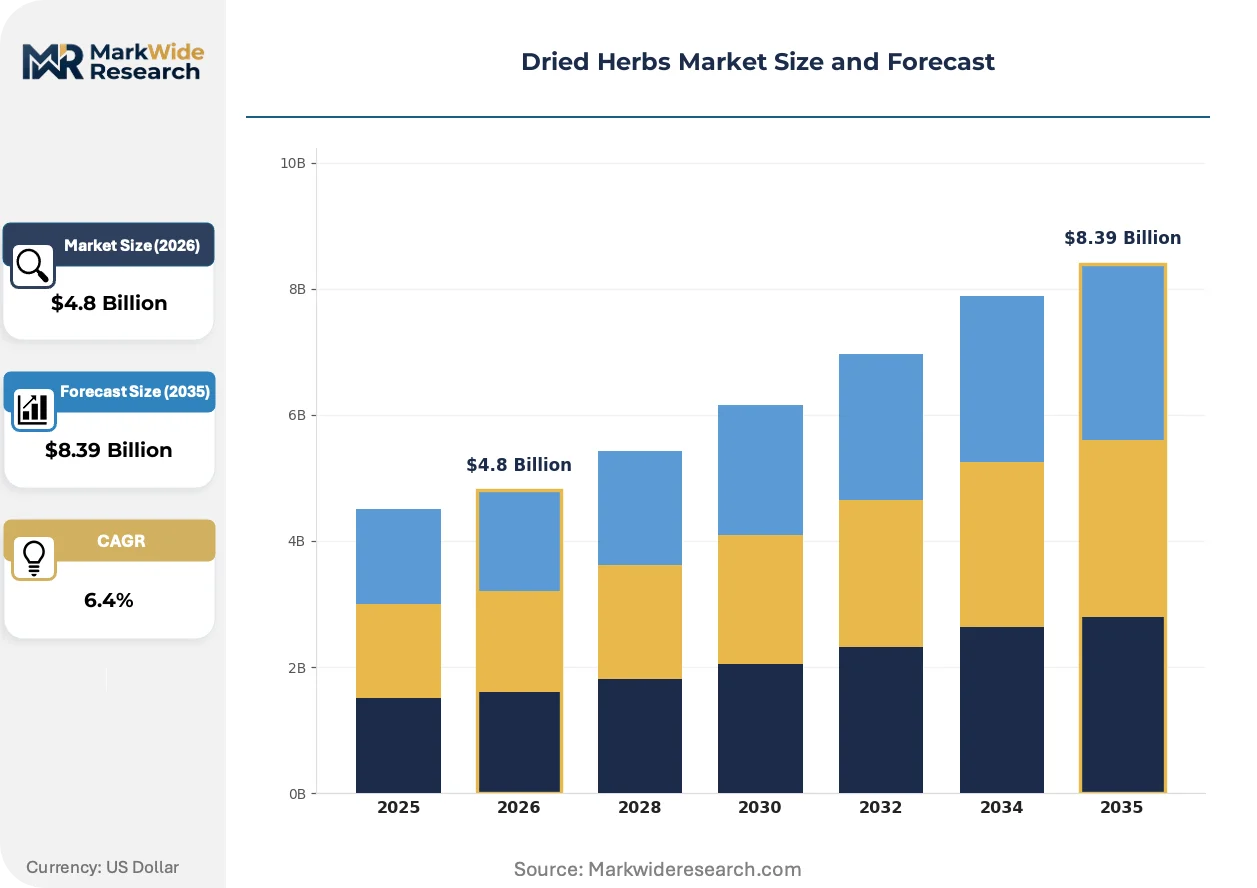
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basil, Oregano, Thyme, Rosemary End User: Restaurants, Retail Stores, Food Manufacturers, Home Cooks Packaging Type: Bags, Jars, Bulk, Sachets Quality Grade: Organic, Conventional, Premium, Standard |
| Companies Covered | Döhler Group, Mountain Rose Herbs, McCormick & Company, British Pepper & Spice Company, Van Drunen Farms, Archer Daniels Midland Company, Firmenich, Frontier Co-op, Kraft Heinz Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dried Herbs Market Strategic Shifts & Innovations
Controlled atmosphere dehydration and precision moisture monitoring are collapsing quality variance while enabling new product formats previously unachievable at scale.
Low-temperature vacuum drying is consolidating quality differentiation in the premium herb segment. Food manufacturers targeting clean-label claims are specifying sub-40°C processing temperatures to preserve volatile oil integrity. This thermal discipline is consolidating supplier tiers by excluding conventional hot-air operators from high-margin organic contracts.
The FDA's updated Food Safety Modernization Act traceability rules are mandating electronic record-keeping from field to finished product. Smaller dehydrators face compliance cost burdens that favor consolidation toward integrated operations with captive ERP systems. United States-based suppliers are responding fastest due to prior HACCP infrastructure investments.
Portion-controlled sachet formats are displacing bulk jar purchases in home cooking channels. Direct-to-consumer brands are capturing repeat purchase economics through subscription models that bypass retail intermediaries. This channel shift concentrates in United States urban markets where convenience premiums override unit cost sensitivity.
Dried Herbs Market Segmentation
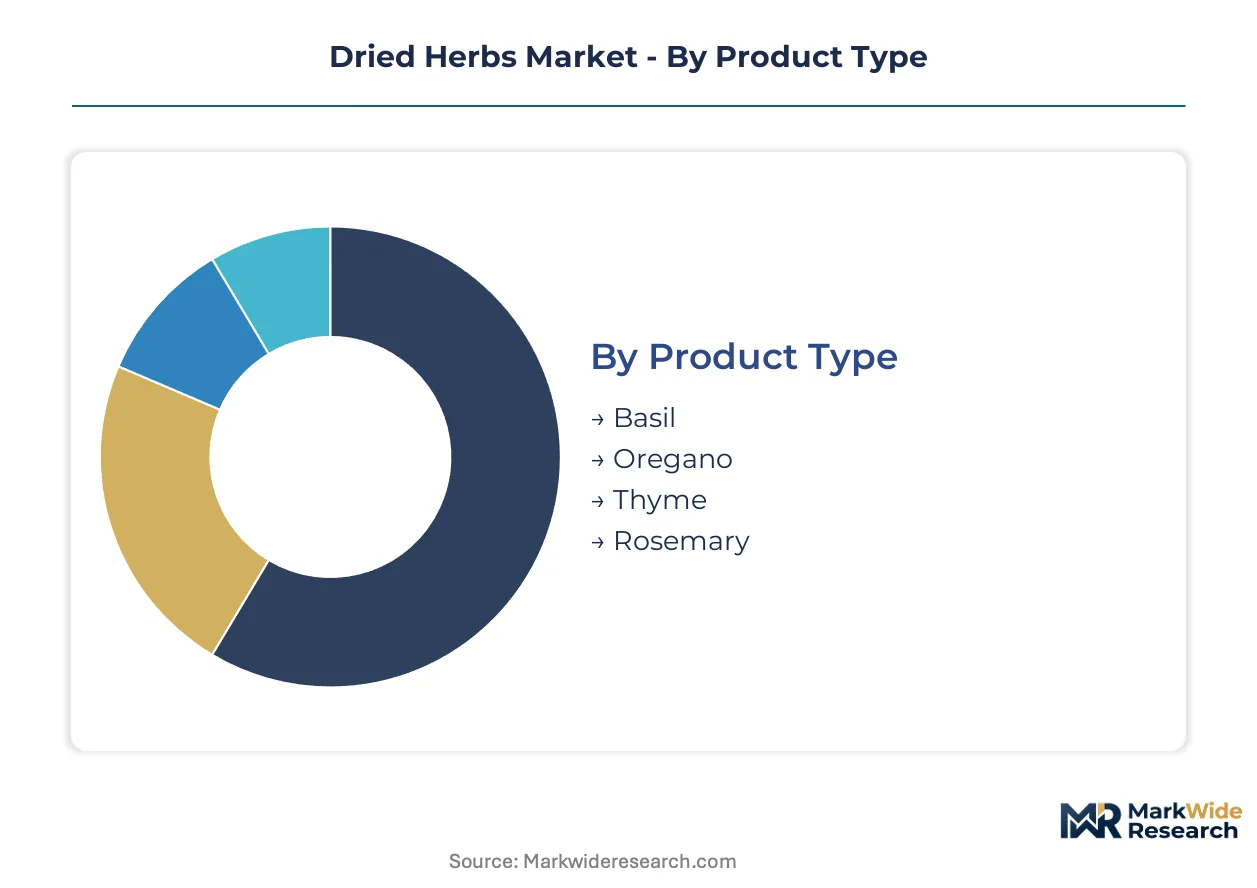
Dried herbs segment along four intersecting axes that determine procurement economics and margin capture. Product type defines volatile oil specifications, while quality grade gates access to clean-label supply chains. Packaging format and end-user channel dictate logistics infrastructure requirements and working capital intensity.
Product Type:
Volatile oil concentration and thermal stability differentiate herb varieties in commercial dehydration specifications.
- Basil:Sweet basil delivers 0.1-0.5% essential oil content dominated by linalool and estragole compounds. Pizza and pasta sauce manufacturers in the United States specify Mediterranean-origin basil for consistent methyl chavicol profiles.
- Oregano:Origanum vulgare contains carvacrol and thymol at 1-3% oil content, delivering antimicrobial properties valued in meat alternative formulations. Greek and Turkish growing districts supply the carvacrol-dominant chemotypes preferred by North American processors.
- Thyme:Thymus vulgaris offers thymol-rich oil profiles for pharmaceutical and culinary applications requiring shelf-life extension.
- Rosemary:Rosmarinus officinalis provides carnosic acid antioxidants for natural preservation systems in prepared foods.
Basil leads on scale; oregano leads on momentum.
End User:
Procurement scale and specification rigor separate institutional buyers from consumer channels.
- Food Manufacturers:Industrial buyers enforce lot-level traceability and organic certification for clean-label seasoning inputs. Frozen meal producers specify sub-40°C dehydration temperatures to preserve volatile oil integrity in finished products.
- Restaurants:Foodservice operators prioritize flavor consistency and supply reliability over organic premiums in high-turnover kitchen environments.
- Retail Stores:Supermarkets and specialty grocers stock branded jar lines and private-label sachet formats for home cooking segments.
- Home Cooks:Direct-to-consumer subscription services bypass retail intermediaries with portion-controlled variety packs in United States metropolitan markets.
Food manufacturers command volume; direct-to-consumer channels are climbing the fastest.
Packaging Type:
Unit economics and shelf-life engineering determine format selection across distribution tiers.
- Sachets:Single-serve foil laminates preserve volatile oils through moisture and oxygen barriers while enabling multi-herb variety packs. Subscription herb services in the United States deploy sachet formats to capture repeat purchase economics without retail slotting fees.
- Bulk:Food manufacturers procure dehydrated herbs in 25-50kg food-grade containers for industrial seasoning blends and sauce production.
- Jars:Glass containers with desiccant closures dominate supermarket spice aisles for home pantry storage.
- Bags:Flexible pouches serve foodservice and small-scale manufacturing with intermediate volume requirements.
Bulk leads on scale; sachets lead on momentum.
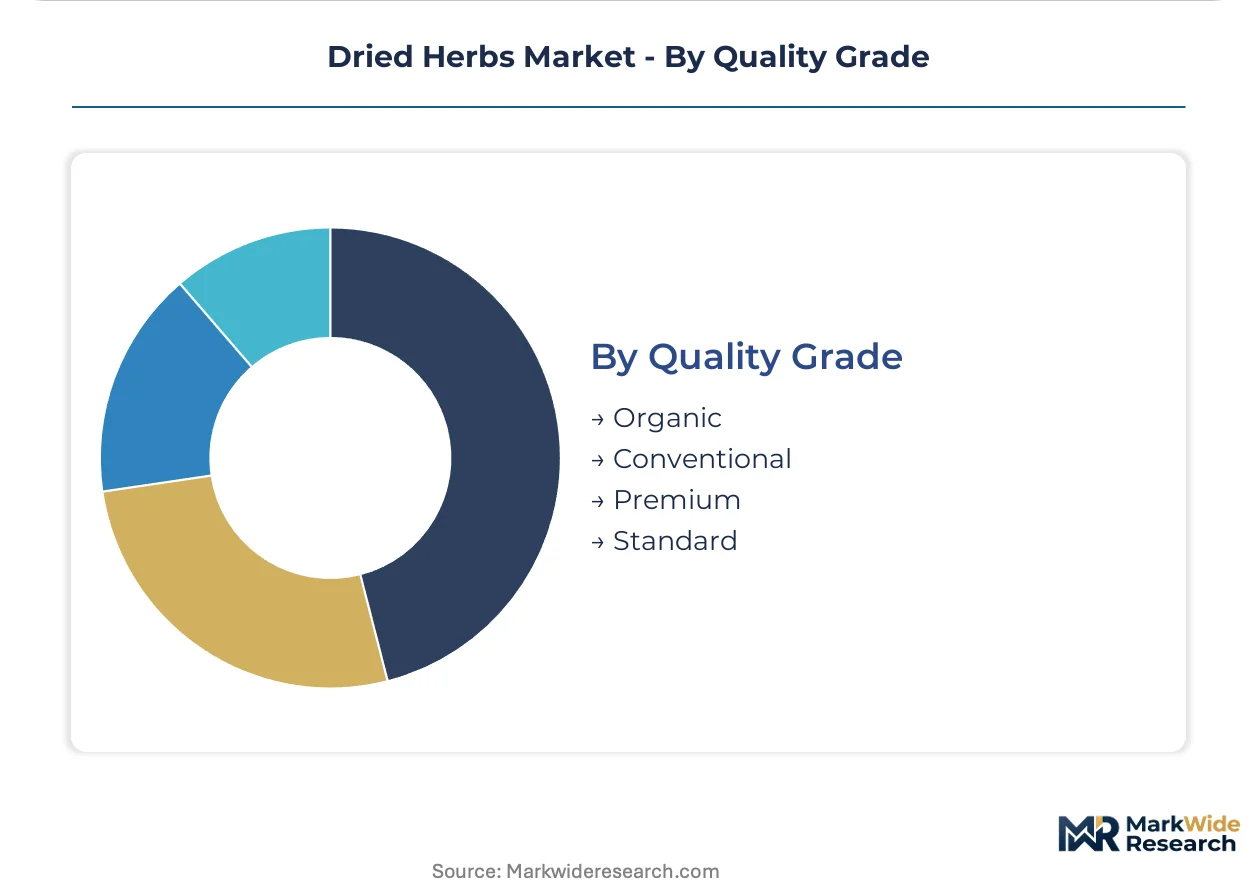
Quality Grade:
Certification status and processing discipline segment pricing tiers in procurement markets.
- Organic:USDA-certified organic herbs command premiums through three-year land conversion requirements and prohibited synthetic inputs. Clean-label mandates from packaged food manufacturers are compressing conventional supplier margins while elevating organic certification premiums.
- Conventional:Standard cultivation with EPA-registered pesticide tolerances serves cost-sensitive foodservice and industrial applications.
- Premium:Sub-40°C vacuum-dried herbs with specified volatile oil retention target high-margin direct-to-consumer and specialty retail channels.
- Standard:Conventional hot-air dehydration at 60-80°C meets basic flavor requirements for commodity seasoning applications.
Conventional leads on scale; organic leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial herb dehydration traces its industrial roots to Mediterranean trading ports where Phoenician merchants first standardized dried oregano and thyme for maritime commerce. Modern production networks now span temperate growing belts with access to controlled-atmosphere processing infrastructure.
United States
Clean-label procurement from frozen meal manufacturers and direct-to-consumer subscription services drive volume. FDA's Food Safety Modernization Act traceability rules compel lot-level digitization investments across California and Arizona growing districts. Central Valley dehydrators near Fresno anchor organic basil supply chains for pizza sauce manufacturers.
Germany
EFSA pesticide residue limits under EU Regulation 396/2005 shape sourcing decisions for herb importers serving Central European food processors. Bavarian spice houses near Munich specialize in premium-grade thyme and rosemary for pharmaceutical applications. The country's organic certification body, BNN, enforces stricter conversion timelines than USDA equivalents.
India
FSSAI's 2022 Food Safety and Standards Amendment Rules mandate contaminant testing for dried herb exports to Gulf Cooperation Council markets. Gujarat's Kutch district hosts dehydration clusters processing cumin and fenugreek for Middle Eastern buyers. Karnataka's contract farming networks supply organic oregano to European traders.
Egypt
EU preferential trade agreements under the Euro-Mediterranean Association Agreement accelerate basil and marjoram shipments to Italian sauce manufacturers. Nile Delta growing regions near Damietta concentrate conventional herb production for cost-sensitive North African markets. The country's agricultural export council subsidizes ISO 22000 certification for mid-tier dehydrators.
Turkey
Carvacrol-dominant oregano chemotypes from Aegean provinces command antimicrobial-grade premiums from meat alternative formulators in Western Europe. Turkish Ministry of Agriculture and Forestry enforces mycotoxin surveillance matching EFSA ochratoxin thresholds. Izmir processing zones consolidate bulk dehydration for re-export through Rotterdam distribution hubs.
Dried Herbs Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification-grade and processing-technology dimensions. The supplier base organizes into three functional tiers: integrated agricultural processors with captive growing operations, cooperative sourcing networks pooling organic smallholder output, and toll dehydration specialists serving food manufacturer contracts. Consolidation pressures intensify as FSMA compliance costs favor ERP-equipped operators over legacy facilities. Dominant competitive moves include backward integration into organic cultivation and strategic partnerships with clean-label meal kit services.
Among North American branded goods manufacturers, McCormick & Company and Kraft Heinz Company occupy positions anchoring retail shelf presence for jarred and sachet formats. Cooperative structures represented by Frontier Co-op exemplify alternative sourcing models sustaining organic grade consistency across distributed supplier networks. These three entities represent contrasting archetypes: vertically integrated consumer brands, agricultural cooperatives, and diversified food conglomerates respectively.
| Leading Market Players |
|---|
| Döhler Group |
| Mountain Rose Herbs |
| McCormick & Company |
| British Pepper & Spice Company |
| Van Drunen Farms |
| Archer Daniels Midland Company |
| Firmenich |
| Frontier Co-op |
| Kraft Heinz Company |
| Others |
Cost & Logistics Intelligence
Organic-to-conventional grade bifurcation generates divergent margin architectures across the dried herb value chain, with USDA-certified organic lots commanding procurement premiums that reflect three-year land conversion costs and synthetic input prohibitions while conventional grades compete on thermal dehydration throughput. This tiered quality ladder manifests in supply chain configurations where organic buyers mandate captive cultivation partnerships or cooperative pooling structures, whereas conventional volume flows through spot-market toll dehydration facilities optimized for energy cost arbitrage.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs dried herb procurement, with organic certification and sub-40°C vacuum dehydration temperature serving as the primary price differentiation drivers. Cost compression in conventional hot-air tiers is intensifying because natural gas price volatility directly governs thermal processing economics. Food manufacturers exhibit the least price sensitivity due to clean-label procurement mandates, while foodservice operators prioritize supply reliability over organic premiums.
Supply Chain Analysis
Dual-sourcing requirements from FDA-traceability-compliant food manufacturers mandate multi-supplier qualification across Mediterranean growing districts, California's Central Valley, and Turkish Aegean provinces. Raw material flows draw from basil and oregano cultivation clusters, natural gas-dependent thermal dehydration infrastructure, and foil-laminate sachet packaging inputs. Single-source vulnerability concentrates in premium organic oregano from Greek and Turkish carvacrol-dominant chemotypes. Distribution runs through Rotterdam re-export hubs for European food manufacturers and direct-to-consumer subscription fulfillment centers in United States metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dried herb market represents a late-cycle quality story where clean-label procurement mandates from frozen meal manufacturers are displacing synthetic flavor systems and elevating specification premiums across the value chain.
For Market Incumbents: Lock in organic certification premiums by securing captive cultivation acreage in California and Arizona growing districts before land conversion timelines compress available supply. Invest in ISO 22000-compliant ERP infrastructure to defend against FSMA traceability cost burdens that threaten smaller competitors. Channel control through direct-to-consumer subscription platforms offers margin protection against retail slotting fee escalation.
For New Entrants and Emerging Players: Capture white-space in antimicrobial-grade oregano blends for meat alternative formulators seeking carvacrol-dominant chemotypes to mask off-notes in pea and soy isolates. Target mid-tier dehydrators in emerging supply regions lacking ISO 22000 certification but possessing low-temperature vacuum drying capability. A certification-first go-to-market angle front-running compliance investments unlocks food manufacturer contracts.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale dehydrators possessing existing organic certification and ERP infrastructure but lacking branded channel presence. The five-to-ten year viability window favors acquisition targets with backward integration into cultivation and established lot-level digitization systems. Watch for mycotoxin threshold adjustments as the inflection indicator that would reroute sourcing geography and consolidate supplier tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Captures land conversion premiums and secures supply for FDA traceability compliance. |
| Low-Temperature Vacuum Drying Capacity Expansion | Preserves volatile oil integrity required by clean-label frozen meal manufacturers. |
| Direct-to-Consumer Subscription Launch | Bypasses retail slotting fees and captures repeat purchase economics in United States urban markets. |
| ISO 22000 Certification Investment | Unlocks food manufacturer contracts through compliance arbitrage in emerging supply regions. |
| Multi-Herb Sachet Format Development | Enables portion-controlled variety packs that pivot buyer choice away from bulk jars. |
Research Approach
Coverage spans North American, European, Mediterranean, and South Asian supply regions, with primary inputs from each combining interviews with dehydration facility operators, organic certification auditors, food manufacturer procurement leads, and spice house technical directors. Secondary validation draws from FDA FSMA guidance documents, USDA organic certification databases, EFSA pesticide residue limit registers, and customs trade flow records. Bottom-up facility capacity assessments and top-down consumption estimates were triangulated to derive market sizing.
Rate-of-change decomposition structured the analytical framework across the projection horizon, modeling volume and value trajectories by product type, quality grade, packaging format, and end-user channel. CAGRs were derived from segmented growth rate assumptions calibrated to input cost elasticity and substitution dynamics. Industry-specific forecast inputs included natural gas price scenarios for thermal dehydration economics and organic land conversion pipeline visibility.
Regulatory enforcement intensity, energy price volatility, and mycotoxin threshold adjustments are the dominant revision risks to modeled outcomes. Deviation in FDA traceability implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Himalayan Salt Market
Spices and Seasonings
Spice Coated Casing Market
Spices and Seasonings
South America Seasoning and Spices Market
Spices and Seasonings
Blended Spices Market
Spices and Seasonings
Ghost Pepper Salt Market
Spices and Seasonings
Lemon Salt Market
Spices and Seasonings
Smoked Black Pepper Market
Spices and Seasonings
US Gourmet Salt Market
Spices and Seasonings
Garlic Oil Market
Spices and Seasonings
Global Oregano Essential Oil Market
Spices and Seasonings
Ginger Market
Spices and Seasonings
Serrata Extract Market
Spices and Seasonings
Europe Seasoning Market
Spices and Seasonings
Global Clove Market
Spices and Seasonings
Fennel Powder Market
Spices and Seasonings
Europe and Asia Juniper Berries Market