
 Global Clove Market | 2026-2036
Global Clove Market Size, Share, and Industry Trends Forecast 2026-2036
Global Clove Market Analysis
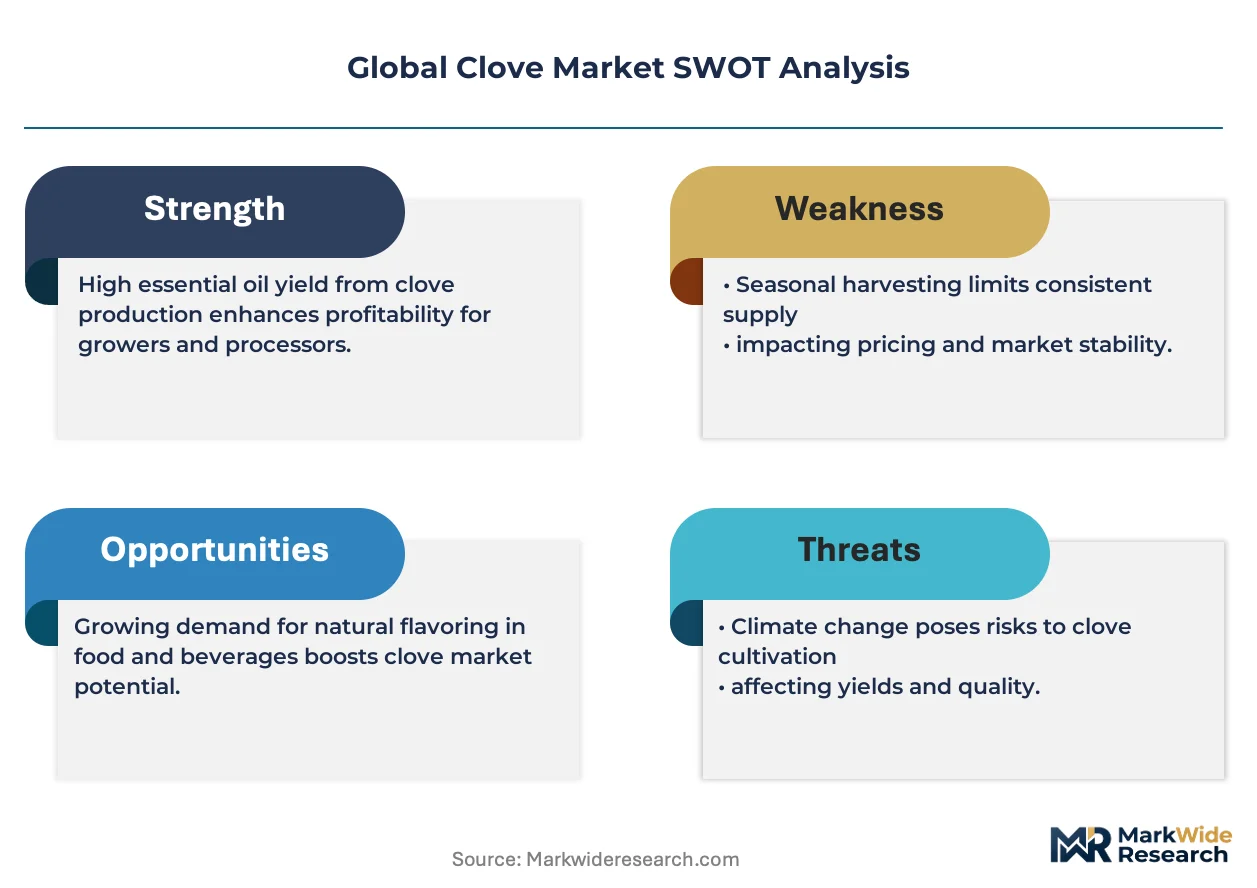
Pharmaceutical formulation is pivoting toward eugenol-rich clove derivatives as drug makers seek plant-based excipients and topical antiseptics. Symrise AG leverages its extraction technology leadership to supply standardized eugenol grades for European pharmaceutical customers. Olam International Limited anchors its sourcing network across Indonesian and Madagascan growing regions, sustaining year-round material availability. Frontier Co-op differentiates through organic certification and fair-trade channel control in North American retail.
Clove comprises the dried, unopened flower buds of Syzygium aromaticum, an evergreen tree native to the Maluku Islands; the buds contain 14–20% essential oil by weight, with eugenol constituting 70–90% of that oil fraction, and serve primarily as a flavoring agent, antimicrobial compound, and fragrance precursor across food, pharmaceutical, and cosmetic industries. Whole cloves retain dominant volume share in spice trade channels, though clove oil commands premium pricing in pharmaceutical and personal care applications where purity standardization justifies higher extraction costs. Clove powder occupies mature, cost-competitive territory among food manufacturers seeking bulk seasoning solutions.
FDA botanical drug guidance and EMA herbal medicine regulations shape clove extract approval pathways for pharmaceutical entrants, while EU REACH and F-Gas Regulation indirectly constrain solvent-based extraction methods used in European processing facilities. Indonesia's national standards body and India's FSSAI enforce pesticide residue limits that determine import eligibility for Asian manufacturing clusters. Stakeholders must monitor evolving pharmacopeial monographs and extraction solvent restrictions to secure long-term supply positions.
Market Dynamics
EU REACH compliance on botanical extracts is tightening purity thresholds for imports, forcing processors to reconfigure extraction solvent portfolios and validate residue elimination protocols across Indonesian and Madagascan supply bases.
Growth Catalysts
- Pharmaceutical formulation pivot:Drug makers seek plant-based excipients and topical antiseptics, widening eugenol-rich clove derivative demand among healthcare providers.
- Natural antiseptic traction:Health care providers favor botanical formulations over synthetic alternatives, accelerating clove oil adoption in wound care and dental applications.
- EU F-Gas Regulation:Solvent restrictions on conventional extraction methods create competitive openings for supercritical CO2 processors serving European pharmaceutical customers.
Market Restraints
- Input cost volatility:Weather-driven yield fluctuations in Indonesian and Madagascan growing regions create raw material price instability for processors.
- Supply concentration risk:Indonesia, Madagascar, and Sri Lanka concentrate bulk cultivation capacity, exposing buyers to single-origin disruption scenarios.
- Regulatory friction:FDA botanical drug guidance and EMA herbal medicine regulations impose lengthy approval pathways that delay pharmaceutical market entry.
Strategic Opportunities
- Underpenetrated therapeutic verticals:Veterinary medicine and companion animal care represent untapped demand for clove-derived antimicrobial formulations.
- Direct-to-manufacturer channels:Food and beverage processors bypass traditional spice traders through blockchain-verified farmgate sourcing platforms.
- EU Green Deal alignment:Carbon-neutral extraction certifications open premium pricing tiers for European cosmetic and personal care manufacturers.
Industry Challenges
- Analytical chemistry skill gaps:Validating eugenol standardization and pesticide residue compliance requires specialized chromatography expertise scarce in origin-country processing clusters.
- Pharmacopeial monograph alignment:Divergent purity specifications between USP, EP, and JP standards force processors to maintain multiple product grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Clove Market |
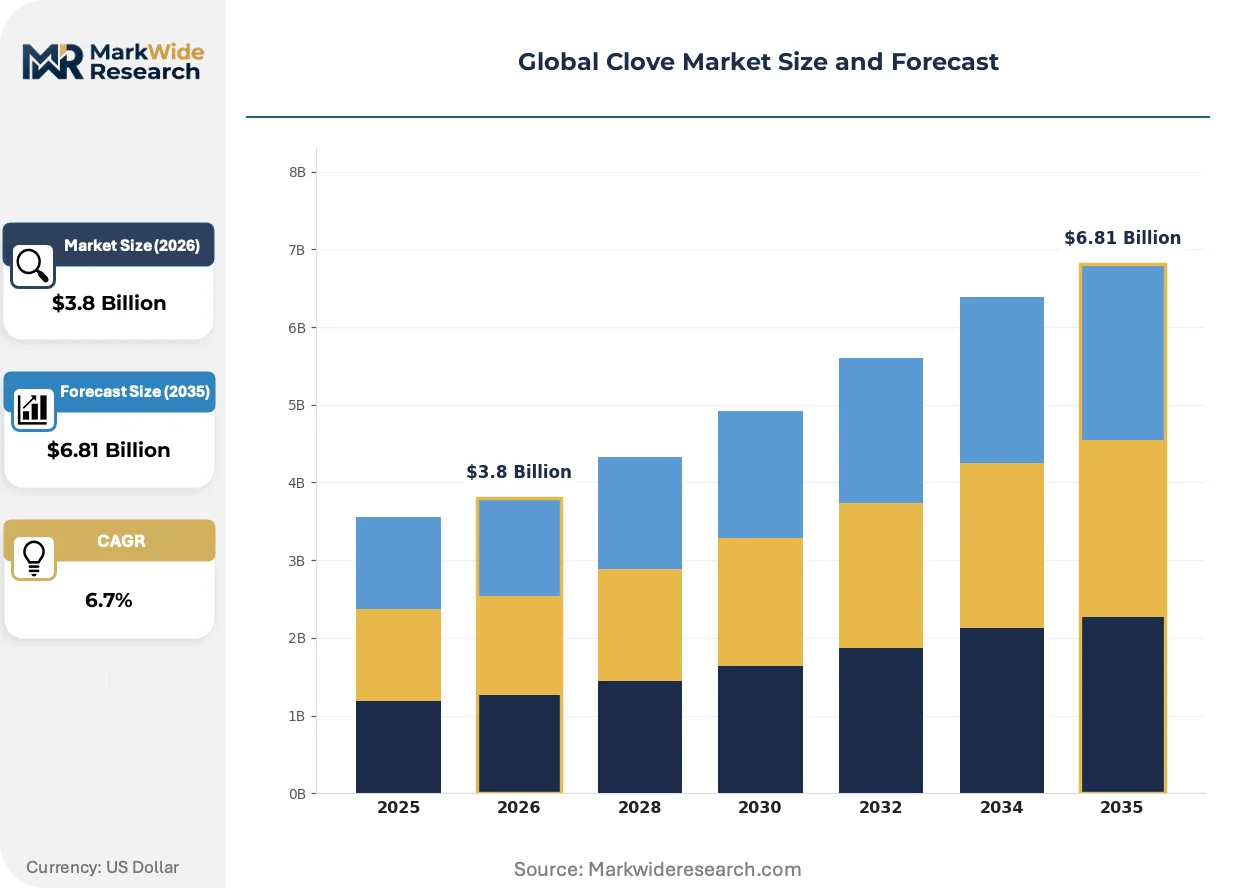
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Cloves, Clove Oil, Clove Powder, Clove Extract Application: Food & Beverages, Pharmaceuticals, Personal Care, Cosmetics Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Distributors End User: Households, Food Manufacturers, Cosmetic Companies, Health Care Providers |
| Companies Covered | International Flavors & Fragrances Inc., Frontier Co-op, McCormick & Company, NOW Foods, Wee Kiat Development Pte Ltd., Olam International Limited, Symrise AG, RO Royal Spices, Givaudan SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Clove Market Emerging Trajectories
Supercritical fluid extraction and green solvent substitution are compressing traditional hexane-based processing margins while enabling pharmaceutical-grade purity claims that command premium positioning.
Supercritical CO2 extraction technology is unifying solvent recovery efficiency with residue-free output quality. European pharmaceutical manufacturers adopt this method to satisfy EU REACH and F-Gas Regulation constraints. The technology is unifying previously separate extraction and purification stages, reducing capital footprint for mid-scale processors.
EU REACH Annex XVII updates on botanical extract purity are forcing solvent substitution across European processing facilities. Hexane-based methods face escalating compliance costs and capacity restrictions. Pharmaceutical and cosmetic extractors in Germany and France accelerate supercritical CO2 and ethanol-water co-solvent investments to maintain market access.
Certification-driven procurement now dominates European and North American buyer decision frameworks. Organic, fair-trade, and pharmacopeial-grade specifications displace generic commodity grades in premium channels. Food manufacturers and cosmetic formulators in Germany, the Netherlands, and California require third-party verified chain-of-custody documentation as a baseline qualification threshold.
Global Clove Market Segmentation
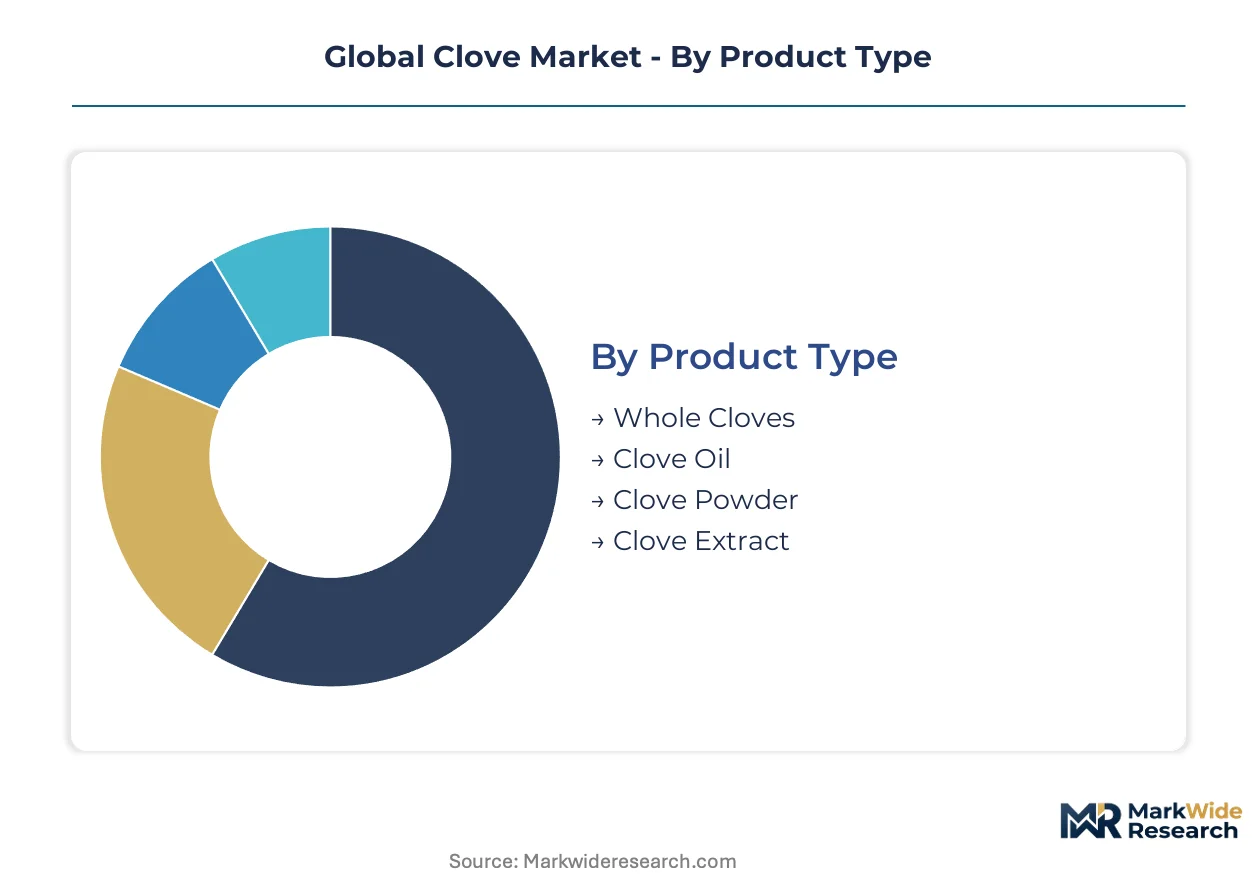
Clove market segmentation reveals divergent capital requirements across product formats, with extraction infrastructure commanding heavy upfront investment while commodity-grade processing operates on leaner asset bases. Understanding these structural cost tiers illuminates why pharmaceutical-grade supply concentrates among specialized processors.
Product Type:
Capital intensity peaks in solvent extraction and supercritical CO2 processing facilities, where pharmaceutical-grade purity standards necessitate precision equipment and validated cleanroom environments.
- Whole Cloves:Dried unopened flower buds retain 14–20% essential oil by weight and serve as the foundational raw material for downstream extraction. Bulk spice traders in Indonesian port cities handle dominant volume flows, though margin compression from weather-driven yield volatility constrains processor returns.
- Clove Oil:Eugenol-rich essential oil constitutes 70–90% of the extractable fraction and commands premium positioning in pharmaceutical antiseptic formulations. German and French cosmetic manufacturers drive demand for standardized grades that satisfy EU REACH Annex XVII purity thresholds.
- Clove Powder:Mature processing segment serving food manufacturers with cost-competitive bulk seasoning solutions.
- Clove Extract:Concentrated botanical preparations requiring advanced chromatography purification for pharmacopeial compliance.
Most installed capacity flows through Whole Cloves. Expansion is steepest in Clove Oil.
Application:
Application-driven segmentation tracks divergent regulatory burdens, with pharmaceutical pathways imposing lengthy validation timelines that favor incumbent specialists over new entrants.
- Food & Beverages:Dominant volume outlet spanning spice blends, cured meats, and aromatic beverage formulations. Indonesian and Madagascan origin material flows primarily into European and North American food manufacturing clusters, where organic certification commands measurable price premiums.
- Pharmaceuticals:Eugenol derivatives function as topical antiseptics, dental analgesics, and plant-based excipients in drug formulations. FDA botanical drug guidance and EMA herbal medicine regulations shape approval pathways, with supercritical CO2 extraction methods gaining preference among European manufacturers facing F-Gas Regulation constraints.
- Personal Care:Fragrance and antimicrobial applications in soaps, lotions, and oral hygiene products.
- Cosmetics:Premium skincare formulations leveraging natural preservative claims.
Food & Beverages absorbs the greatest raw material tonnage. Pharmaceuticals generates the highest unit margins.
Distribution Channel:
Channel segmentation reflects procurement sophistication gradients, with institutional buyers bypassing traditional intermediaries through direct sourcing platforms.
- Wholesale Distributors:Traditional aggregation layer connecting Indonesian and Madagascan processors to international buyers, though blockchain-verified farmgate platforms are compressing their historical role.
- Online Retail:Fastest-expanding channel for organic and fair-trade certified products targeting North American and European household consumers.
- Supermarkets:Mass-market spice and personal care product placement.
- Specialty Stores:Premium positioning for pharmacopeial-grade and artisanal product lines.
Wholesale Distributors still handle the majority of institutional volume. Online Retail is climbing the fastest among consumer-facing channels.
End User:
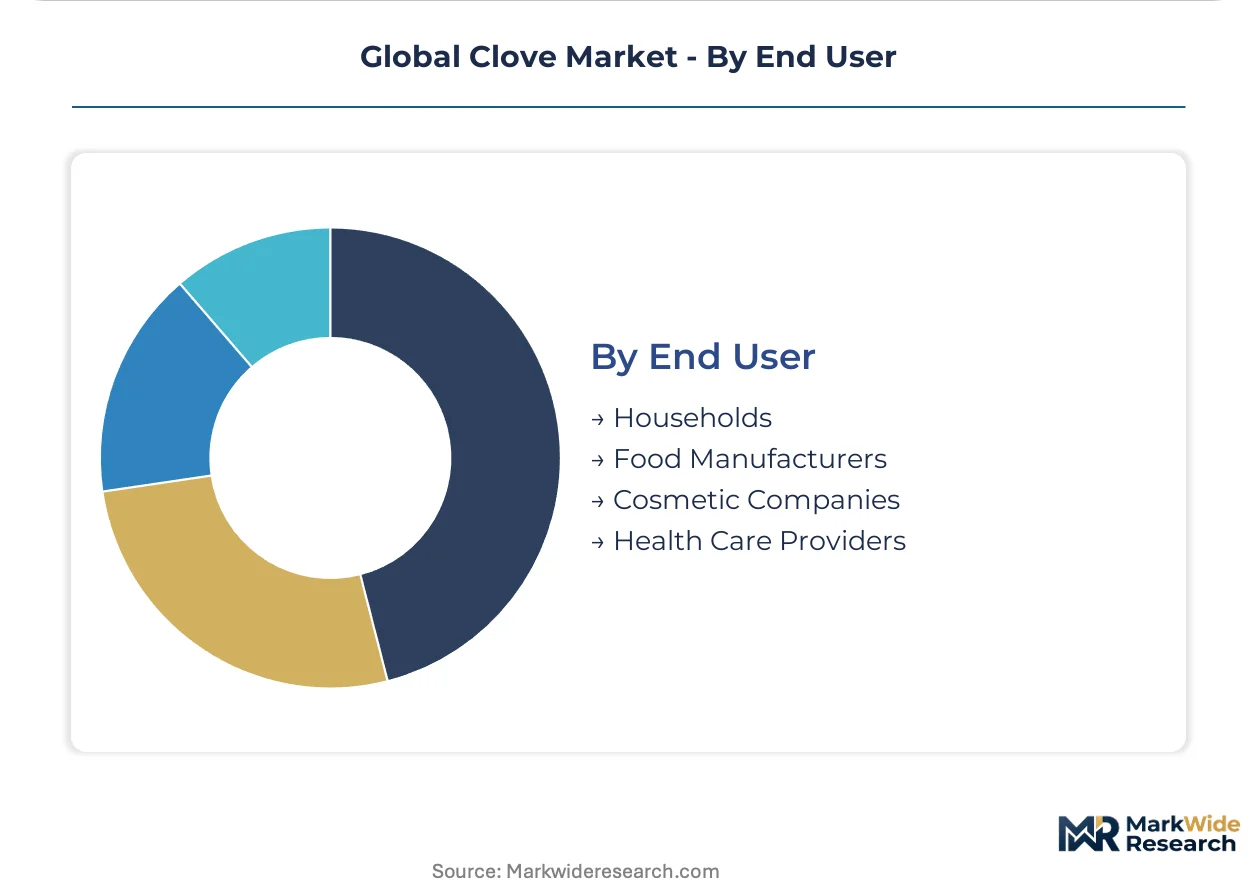
End-user segmentation maps divergent specification requirements, from bulk commodity grades for industrial food processing to residue-tested pharmaceutical batches.
- Food Manufacturers:Largest industrial consumer segment purchasing standardized powder and whole bud grades for seasoning and flavoring applications. FSSAI pesticide residue limits and Indonesia's national standards body certifications determine import eligibility for Asian manufacturing clusters.
- Health Care Providers:Hospitals and dental clinics drive demand for eugenol-based topical antiseptics and wound care formulations, with procurement decisions increasingly favoring botanical alternatives over synthetic compounds.
- Households:Direct consumer purchases through retail and e-commerce channels.
- Cosmetic Companies:Formulators seeking natural preservative and fragrance ingredients with third-party verified chain-of-custody documentation.
Food Manufacturers represent the largest volume sink. Health Care Providers are expanding most quickly as natural antiseptic formulations gain clinical traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting processing capacity toward jurisdictions with lower compliance burdens, as EU REACH and F-Gas Regulation constraints push extraction investment away from European facilities toward origin-country clusters in Indonesia and Madagascar.
Indonesia
Domestic clove production supplies both spice trade volumes and downstream oil extraction for pharmaceutical customers. The country's national standards body enforces pesticide residue limits that determine export eligibility to Asian manufacturing clusters. Surabaya and Makassar port cities concentrate bulk handling and primary processing infrastructure.
Madagascar
Island cultivation generates high-eugenol-yielding buds favored by European cosmetic formulators. The country's central pharmaceutical regulator maintains import documentation requirements for botanical extracts entering francophone African markets. Toamasina port anchors the bulk export corridor to European cosmetic manufacturers.
Germany
Specialized extraction facilities in Hamburg and Frankfurt serve EMA-regulated pharmaceutical customers with pharmacopeial-grade eugenol derivatives. ECHA REACH Annex XVII compliance costs are accelerating solvent substitution toward supercritical CO2 methods. The country's chemical processing corridor concentrates EU-facing botanical extract capacity.
India
Domestic spice consumption and re-export processing create dual demand channels for Indonesian and Madagascan raw material. FSSAI pesticide residue limits and CDSCO herbal medicine regulations shape import and formulation requirements. Kochi and Mumbai harbor zones concentrate customs clearance and secondary processing for Asian pharmaceutical clusters.
United States
FDA botanical drug guidance shapes approval pathways for clove-derived pharmaceutical entrants targeting topical antiseptic applications. EPA oversight of extraction solvent emissions influences processing facility siting decisions. New Jersey and California pharmaceutical corridors concentrate formulation demand for standardized eugenol grades.
Global Clove Market Vendor Landscape
Capacity expansion dominates the current landscape as processors scale supercritical CO2 infrastructure to capture EU pharmaceutical demand. The vendor base organizes around three tiers: integrated agricultural processors controlling origin-country supply, specialized extraction technology providers serving pharmacopeial specifications, and branded ingredient suppliers commanding premium positioning through certification stacking. Strategic archetypes include backward-integrated plantation operators, technology-licensing extraction specialists, and certification-heavy retail-facing brands. Portfolio diversification and geographic sourcing expansion represent the dominant competitive moves as buyers seek to mitigate single-origin concentration risk.
Among extraction technology leaders, Symrise AG and Givaudan SA occupy positions within the premium pharmaceutical-grade tier, leveraging European regulatory proximity to serve EMA-compliant formulation customers. Olam International Limited anchors the agricultural integration archetype, with naming conventions suggesting Singapore-based coordination of Indonesian and Madagascan supply networks. Frontier Co-op exemplifies the certification-driven retail channel strategy, with cooperative structure implying direct farmer relationships and fair-trade positioning in North American natural products distribution.
| Leading Market Players |
|---|
| International Flavors & Fragrances Inc. |
| Frontier Co-op |
| McCormick & Company |
| NOW Foods |
| Wee Kiat Development Pte Ltd. |
| Olam International Limited |
| Symrise AG |
| RO Royal Spices |
| Givaudan SA |
| Others |
Supply Flow & Price Mechanics
Backward integration into Indonesian and Madagascan plantation networks anchors supply security for processors while simultaneously compressing raw material acquisition costs and insulating margin structures against weather-driven yield volatility. This captive sourcing model concentrates pricing power among integrated operators who can bypass spot-market volatility that afflicts non-integrated traders.
Pricing Analysis
Distributor margin compression is intensifying as blockchain-verified farmgate platforms enable food manufacturers to bypass traditional wholesale layers. Three-tier pricing structure across pharmacopeial-grade, certified-organic, and commodity-standard levels separates pharmaceutical extractors from cosmetic formulators from bulk spice traders. Cost compression in commodity whole-clove tiers stems from Indonesian harvest volatility and Madagascan logistics bottlenecks. Food manufacturers exhibit highest price sensitivity due to thin seasoning margins, while pharmaceutical customers accept premium positioning for EU REACH-compliant eugenol standardization.
Supply Chain Analysis
Refurbishment flows for spent clove biomass into secondary extract applications are emerging as circular-economy compliance mechanisms under EU Green Deal procurement frameworks. Primary cultivation concentrates in Indonesia, Madagascar, and Sri Lanka, with Surabaya and Toamasina ports anchoring bulk export corridors. Processing draws from hexane-based, ethanol-water co-solvent, and supercritical CO2 extraction inputs. Single-origin concentration risk exposes buyers to Indonesian weather disruption and Madagascan infrastructure constraints. Distribution runs through wholesale distributors for institutional volume, though direct-to-manufacturer platforms are gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in pharmaceutical-grade extraction as supercritical CO2 technology cost curves flatten and EU F-Gas Regulation solvent restrictions displace legacy hexane processors. Premium-tier shift toward pharmacopeial certification commands measurable price premiums over commodity grades.
For Market Incumbents: Anchor supply security through plantation network expansion across Indonesian and Madagascan growing regions to mitigate single-origin disruption scenarios. Invest in supercritical CO2 extraction capacity to satisfy tightening EU REACH Annex XVII purity thresholds and capture pharmaceutical customer migration from solvent-based suppliers. Defend against emerging technology-licensing specialists by accelerating pharmacopeial monograph alignment across USP, EP, and JP standards. For New Entrants and Emerging Players: EU F-Gas Regulation in Europe opens a window for supercritical CO2 extraction specialists to capture displaced pharmaceutical demand from hexane-dependent incumbents. Veterinary medicine and companion animal care represent the most penetrable therapeutic vertical, with antimicrobial formulation demand running ahead of established supply. Pursue carbon-neutral extraction certification as the primary go-to-market angle for European cosmetic and personal care manufacturers. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale supercritical CO2 extraction specialists because EU regulatory compliance costs are consolidating fragmented European processing capacity into acquirable platforms. Long-term viability favors operators with backward-integrated plantation control and validated cleanroom infrastructure. Watch EU REACH Annex XVII enforcement intensity as the inflection signal for accelerated solvent-substitution investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Networks | Captive supply from Indonesian and Madagascan growing regions insulates processors against weather-driven yield volatility. |
| Supercritical CO2 Capacity Expansion | EU F-Gas Regulation compliance enables pharmaceutical-grade eugenol positioning with residue-free extraction claims. |
| Pharmacopeial Certification Investment | USP, EP, and JP monograph alignment opens premium pricing tiers for standardized clove extract grades. |
| Carbon-Neutral Extraction Certification | EU Green Deal procurement frameworks favor certified processors serving European cosmetic manufacturers. |
| Veterinary Medicine Formulation Development | Companion animal care demand for botanical antimicrobials remains underserved by incumbent human-pharma specialists. |
Methodological Framework
Multiple input streams — structured interviews with extraction technology directors, primary processing facility managers, and pharmaceutical procurement leads; trade data from Indonesian and Madagascan customs authorities; and EMA regulatory filing databases — were reconciled through bottom-up volume triangulation against top-down value estimates. Secondary validation drew from EU REACH Annex XVII guidance documents, FAO agricultural statistics, and pharmacopeial monograph repositories. Cross-referencing identified data gaps requiring targeted follow-up with specialty chemical distributors and cosmetic formulator procurement teams.
Historical volume trajectories were cross-referenced against panel-based growth assumptions across the analysis window. Segmentation modeling incorporated product type tiers, application-specific regulatory pathways, distribution channel procurement sophistication gradients, and end-user specification requirements. CAGRs were derived from slope-consistency checks against input cost elasticity parameters and pharmaceutical demand penetration curves. Forecast inputs included eugenol standardization technology adoption rates and EU solvent regulation enforcement timelines.
Revisions become necessary when EU REACH enforcement intensity exceeds modeled thresholds, supercritical CO2 equipment cost curves flatten faster than baseline assumptions, or Indonesian weather patterns disrupt harvest projections. Forecasts reflect documented assumptions regarding pharmaceutical formulation pivot velocity and certification-driven procurement adoption. Periodic stress-testing of base assumptions against regulatory filing volumes and plantation expansion announcements is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Wasabi Market
Spices and Seasonings
Middle East and Africa Botanical Extract Market
Spices and Seasonings
US Gourmet Salt Market
Spices and Seasonings
Plastic Spice Jars Market
Spices and Seasonings
Poultry Seasoning Market
Spices and Seasonings
North America Spice and Herb Extracts Market
Spices and Seasonings
South America Spice and Herb Extracts Market
Spices and Seasonings
Mint Oils Market
Spices and Seasonings
Meat Seasonings Market
Spices and Seasonings
Gourmet Seaweed Seasoning Market
Spices and Seasonings
Spices and Seasonings Market
Spices and Seasonings
Global Black Pepper Market
Spices and Seasonings
Spice Oils and Oleoresins Market
Spices and Seasonings
Smoked Salt Market
Spices and Seasonings
Europe Seasoning Market
Spices and Seasonings
Nutmeg Oil Market