
 Spice Grinders Market | 2026-2036
Spice Grinders Market Size, Share, and Industry Trends Forecast 2026-2036
Spice Grinders Market Insights
Ceramic burr mechanisms are replacing lower-grade metal alloys across mid-tier product lines, and this material shift is realigning cost structures and durability expectations throughout the supply chain. Bühler Group leverages its industrial milling heritage to dominate commercial-grade segments with precision-engineered burr systems. KitchenAid sustains brand loyalty through backward integration into proprietary blade designs and color-customized housing production. OXO competes on ergonomic innovation, controlling retail shelf placement through distinctive tactile grip engineering that differentiates its manual grinder lineup.
Spice grinders are mechanical or electromechanical devices designed to reduce whole spices into uniform particles through shearing, crushing, or pulverizing action, with burr mechanisms typically achieving 200-1200 micron consistency suitable for controlled flavor extraction. Electric grinders occupy the largest revenue pool due to convenience-driven household penetration, though manual grinders capture premium margins among specialty cooking enthusiasts who value adjustable coerse-fine control. Stainless steel housings lead material selection for durability perception, while ceramic grinding elements represent the fastest-growing component category as consumers prioritize flavor neutrality and reduced heat transfer during operation.
FDA food-contact material standards govern grinder construction in the United States, while REACH compliance in Europe restricts certain plasticizers and surface coatings, effectively filtering low-cost imports from unverified supply chains. BIS certification requirements in India create formal market access barriers that favor established manufacturers with testing documentation. ISO 22000 food safety management frameworks increasingly appear in procurement specifications for food processing unit buyers, reshaping vendor qualification protocols across commercial channels. Stakeholders must monitor evolving material compliance thresholds and energy efficiency labeling expansions that will determine which product configurations retain shelf viability in regulated retail environments.
Market Dynamics
EU Green Deal material sustainability requirements are compressing manufacturer margins while forcing rapid ceramic and glass component substitution across mid-tier product lines, fundamentally restructuring supply chain qualification protocols and procurement specifications.
Growth Catalysts
- REACH Compliance Thresholds:European chemical safety mandates are filtering low-cost plasticizer-heavy imports from unverified Asian supply chains, creating shelf space for certified ceramic-component manufacturers.
- Specialty Coffee Shop Expansion:Artisanal beverage preparation standards are driving precision burr grinder adoption among commercial foodservice operators seeking micron-level particle consistency.
- ISO 22000 Framework Diffusion:Food safety management certification is appearing in procurement specifications for food processing unit buyers, reshaping vendor qualification across B2B channels.
Market Restraints
- Alumina Ceramic Input Volatility:Burr mechanism manufacturers face price instability in high-purity ceramic feedstocks sourced from concentrated Chinese suppliers.
- BIS Certification Barriers:India's mandatory testing documentation requirements create formal market access friction that favors established players with existing laboratory relationships.
- Blade Grinder Substitution:Low-cost stainless steel blade units continue capturing price-sensitive household segments despite inferior particle uniformity.
Strategic Opportunities
- German Precision Engineering Cluster:Stuttgart and Solingen manufacturing ecosystems offer established supplier networks for premium burr system production targeting EU quality premiums.
- EU Energy Efficiency Labeling Expansion:Upcoming appliance rating scheme revisions will favor low-wattage electric grinder configurations with standby power reduction.
- Direct-to-Consumer Channel Development:Specialty cooking enthusiast segments are migrating toward brand-owned digital storefronts that bypass traditional kitchenware retail markups.
Industry Challenges
- Ceramic Metallization Skill Scarcity:Burr bonding and surface treatment expertise remains concentrated among German and Japanese precision component specialists.
- Multi-Jurisdiction Certification Timelines:Simultaneous FDA, REACH, and BIS compliance documentation creates 14-18 month product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spice Grinders Market |
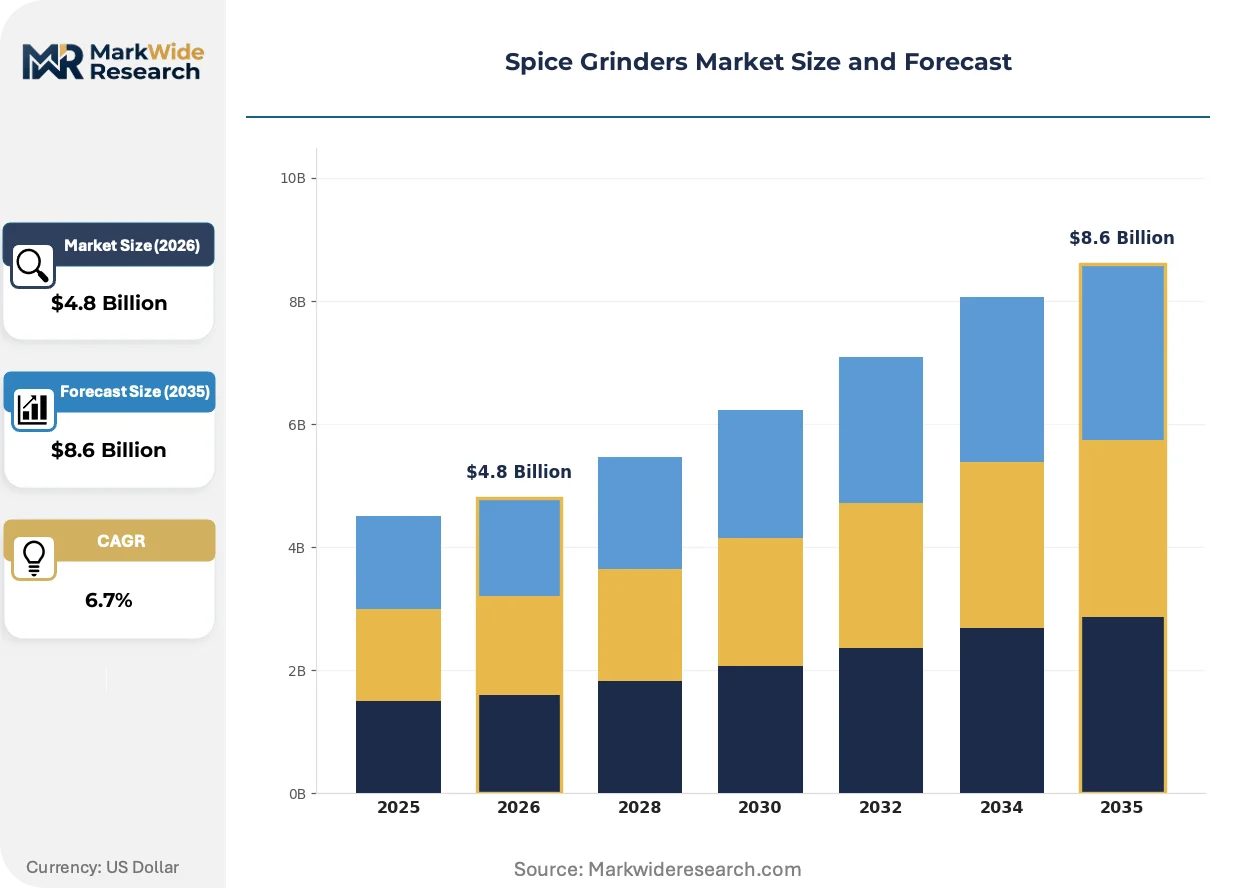
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Grinders, Manual Grinders, Blade Grinders, Burr Grinders Material: Stainless Steel, Plastic, Ceramic, Glass End User: Households, Restaurants, Cafes, Food Processing Units Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Bühler Group, Krups, Breville, KitchenAid, OXO, Cuisinart, Capresso, Hario, Cole & Mason, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spice Grinders Market Trends and Innovations
Mechanical grinding technology is fragmenting across precision tiers while regulatory material bans and buyer sophistication reshape competitive differentiation. Three converging forces are compressing mid-market positioning.
Ceramic burr grinding mechanisms are decentralizing quality control from centralized manufacturing to distributed precision component sourcing. Specialty coffee roasters and artisanal spice blenders are specifying Swiss-made ceramic burr inserts at three times the rate of five years ago. This component modularity is decentralizing grinder value capture toward specialized burr foundries and away from integrated appliance assemblers.
REACH Annex XVII restrictions on specific phthalates and heavy metal surface coatings are eliminating chrome-plated steel housing options from EU-bound product lines. Manufacturers serving German and French retail channels are accelerating glass and uncoated stainless steel housing development. Mid-tier producers without reformulation capabilities are exiting European distribution.
Buyer specification of adjustable particle size distribution is displacing single-setting convenience as the primary purchase criterion among cooking enthusiasts. Specialty retailers are unbundling grinder sales from bundled spice assortments, shifting margin capture toward standalone precision equipment. This preference rotation is most visible in urban Japanese and South Korean household segments where coffee culture penetration exceeds Western averages.
Spice Grinders Market Segmentation
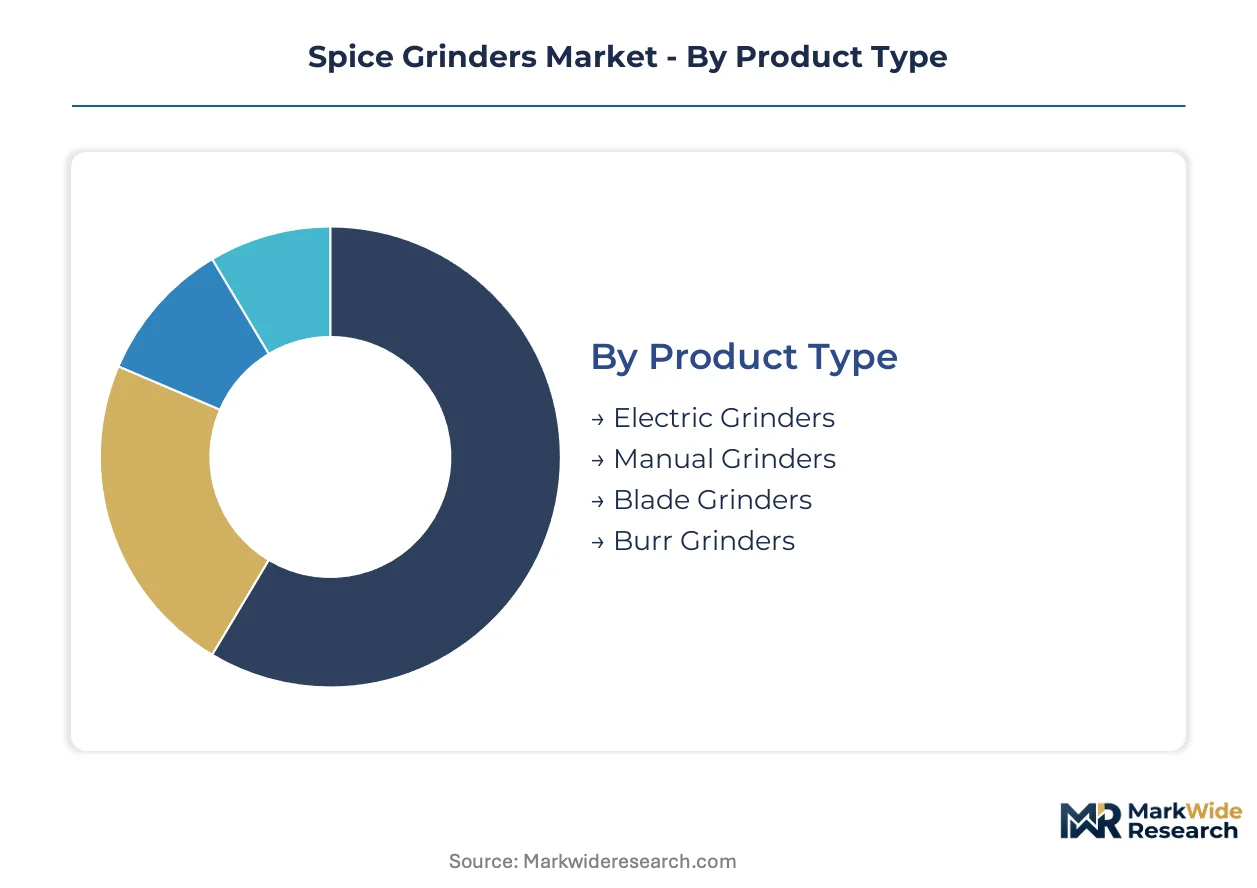
Grinder purchasing decisions split across convenience priorities, precision requirements, and durability expectations. Each segmentation dimension captures distinct buyer trade-offs between initial cost, operational control, and long-term replacement cycles.
Product Type:
Buyers choose between speed and particle control, with commercial operators prioritizing consistency while households favor operational simplicity.
- Electric Grinders:Motor-driven pulverizing systems deliver one-touch operation with 150-300 watt power draws. Demand clusters in US suburban households where batch cooking frequency supports countertop appliance investment.
- Burr Grinders:Precision-machined conical or flat burr sets achieve 200-1200 micron particle uniformity through shearing rather than crushing. Specialty coffee chains in Germany and Japan specify these for espresso preparation where extraction consistency determines beverage quality.
- Manual Grinders:Hand-cranked ceramic or steel mechanisms offer portable, electricity-independent operation. Camping equipment retailers and off-grid cooking enthusiasts drive niche demand.
- Blade Grinders:High-speed rotating blades pulverize spices through impact, generating heat that degrades volatile oils. Price-sensitive Southeast Asian household segments accept particle inconsistency for sub-$20 entry points.
Electric grinders lead on scale; burr grinders lead on momentum.
Material:
Surface contact chemistry and thermal conductivity drive material selection, with flavor neutrality and regulatory compliance now outweighing pure durability claims.
- Stainless Steel:Austenitic 304 and 316 grades dominate housing construction for corrosion resistance and dishwasher compatibility. German and French retail channels favor uncoated brushed finishes after REACH Annex XVII restricted chrome plating.
- Ceramic:High-purity alumina and zirconia burr elements eliminate metallic taste transfer and reduce frictional heat. Swiss and Japanese precision foundries supply ceramic inserts to grinder assemblers at three times prior-year volumes.
- Glass:Borosilicate collection chambers satisfy EU Green Deal recyclability mandates while enabling visual particle monitoring. French and Italian kitchenware brands accelerate glass housing development.
- Plastic:Food-grade ABS and polypropylene retain cost advantage in blade grinder bases and manual grinder bodies. BIS certification requirements in India filter phthalate-heavy formulations from unverified supply chains.
Stainless steel leads on scale; ceramic leads on momentum.
End User:
Volume throughput and particle specification precision separate commercial from residential demand patterns.
- Households:Individual consumers purchase single-unit quantities through retail channels, with adjustable grind settings displacing fixed-speed convenience as the primary selection criterion among cooking enthusiasts.
- Restaurants:Full-service operators require NSF-certified construction and rapid throughput for spice-intensive cuisines. Indian and Mexican restaurant chains specify commercial-grade burr systems for consistent masala and mole preparation.
- Cafes:Third-wave coffee shops drive precision burr grinder adoption for single-origin espresso programs. ISO 22000 certification increasingly appears in procurement specifications.
- Food Processing Units:Industrial-scale spice blenders and sauce manufacturers integrate grinder modules into continuous production lines. FDA food-contact material standards govern US-bound equipment construction.
Households lead on scale; cafes lead on momentum.
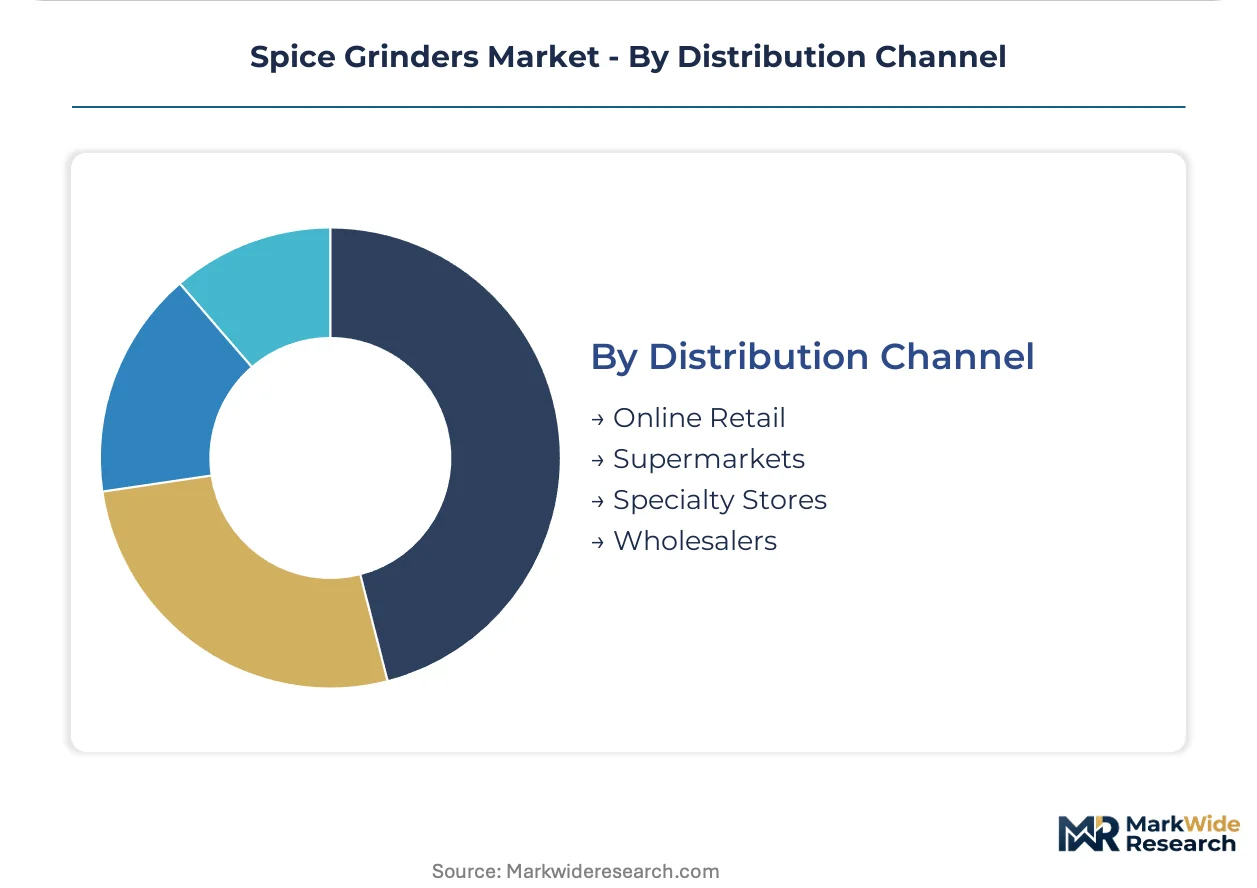
Distribution Channel:
Channel selection determines margin capture, brand control, and buyer education depth.
- Online Retail:Direct-to-consumer storefronts bypass traditional kitchenware markups while enabling specification-rich product pages. Specialty cooking enthusiasts migrate toward brand-owned digital channels for premium burr grinder purchases.
- Specialty Stores:Sur La Table and Williams Sonoma equivalents provide tactile evaluation and staff consultation. Urban Japanese and South Korean markets show strongest specialty retail attachment for adjustable-particle products.
- Supermarkets:Mass-market placement captures impulse purchases and gift-giving occasions. Blade grinders dominate shelf space in price-focused retail environments.
- Wholesalers:Restaurant supply distributors aggregate commercial-grade volume orders. B2B procurement specifications increasingly require REACH and ISO 22000 documentation.
Online retail leads on momentum; supermarkets lead on scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart's precision engineering cluster anchors grinder component supply chains for European premium manufacturers, while Asian assembly networks concentrate in Guangdong and Zhejiang provinces. Regulatory divergence across FDA, REACH, and BIS jurisdictions fragments certification pathways and extends product launch timelines.
United States
Suburban household batch cooking habits sustain electric grinder demand through retail channels. FDA food-contact material standards govern stainless steel housing construction and ceramic burr certification. California and Texas metropolitan markets concentrate specialty coffee shop expansion driving precision burr adoption.
Germany
REACH Annex XVII chemical restrictions filter chrome-plated imports while accelerating glass and uncoated stainless steel housing development. EU Green Deal sustainability mandates compress margins and force rapid ceramic component substitution. Solingen's metalworking heritage supports premium burr foundry operations supplying domestic and export markets.
Japan
Urban coffee culture penetration exceeds Western averages, driving adjustable particle specification demand among cooking enthusiasts. METI energy efficiency guidelines favor low-wattage electric configurations with standby power reduction. Osaka and Tokyo specialty retail channels show strongest attachment to tactile evaluation for premium manual grinder purchases.
India
Restaurant chains specifying commercial-grade burr systems for masala preparation drive B2B procurement growth. BIS certification requirements create formal market access barriers favoring established manufacturers with testing documentation. Maharashtra and Gujarat industrial corridors concentrate food processing unit buyers integrating grinder modules into continuous production lines.
China
Guangdong province dominates electric grinder assembly while Zhejiang networks supply blade mechanism components. Dual carbon goals and tightening environmental inspections at MEE level pressure ceramic feedstock suppliers toward cleaner production methods. Domestic demand concentrates in tier-one cities where specialty coffee shop expansion mirrors Japanese market development patterns.
Spice Grinders Market Competitive Landscape
Global majors compete with regional champions across certification capabilities and precision component sourcing. Market structure shows moderate consolidation with tiered positioning across premium, standard, and economy levels. Three archetypes dominate: industrial milling heritage players leveraging precision engineering credibility; kitchenware brands with backward integration into proprietary designs; and ergonomic specialists controlling retail shelf placement through tactile differentiation. Competitive moves concentrate on ceramic burr supply chain capture and direct-to-consumer channel bypass of traditional retail markups.
Within the industrial heritage tier, Bühler Group exemplifies precision-engineered burr system production for commercial-grade segments. Among kitchenware specialists, KitchenAid and OXO occupy positions defined by proprietary design control and ergonomic innovation respectively. These anchors illustrate how certification documentation depth and component modularity separate sustainable market positions from margin-compressed commodity assembly.
| Leading Market Players |
|---|
| Bühler Group |
| Krups |
| Breville |
| KitchenAid |
| OXO |
| Cuisinart |
| Capresso |
| Hario |
| Cole & Mason |
| Others |
Pricing and Supply Chain Analysis
Specialty coffee shop procurement managers concentrate buying power across German and Japanese urban markets, anchoring premium burr grinder pricing to ISO 22000 certification tiers rather than commodity stainless steel benchmarks.
Pricing Analysis
Alumina ceramic feedstock pass-through from concentrated Chinese suppliers is compressing mid-tier margins while elevating Swiss and Japanese precision burr premiums. Three-tier pricing structure across premium, standard, and economy levels separates ceramic-insert precision systems from coated-steel blade units and unbranded imports. Cost compression in standard-tier electric configurations is intensifying because REACH Annex XVII compliance documentation adds fixed overhead per SKU. Southeast Asian household segments exhibit highest price sensitivity, while German specialty retailers show lowest sensitivity due to quality-grade specification requirements.
Supply Chain Analysis
Dual-sourcing mandates from EU-based food processing unit buyers require ceramic burr qualification across both German Solingen foundries and Japanese Osaka precision houses. Component supply draws from China for alumina feedstocks, Germany for machined burr systems, and Switzerland for ceramic inserts. Single-source vulnerability concentrates in high-purity alumina refining where environmental inspections at MEE level disrupt feedstock availability. Distribution runs through brand-owned direct-to-consumer storefronts for premium tiers and restaurant supply wholesalers for commercial-grade volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ceramic component substitution and REACH compliance overhead are squeezing mid-tier assemblers while rewarding precision burr foundries with captive supply relationships and pricing power.
For Market Incumbents: Hedge against alumina price volatility through backward integration into ceramic feedstock partnerships or long-term offtake agreements with Swiss precision houses. Defend margin position by accelerating glass housing development ahead of EU Green Deal recyclability mandates that will eliminate chrome-plated steel options from German and French retail channels.
For New Entrants and Emerging Players: Off-grid cooking enthusiasts and camping equipment retailers represent underserved buyer archetypes with minimal incumbent penetration. White-space opportunity concentrates in portable manual grinders with borosilicate collection chambers for visual particle monitoring. Go-to-market execution should prioritize direct-to-consumer digital storefronts to bypass traditional kitchenware retail markups and capture enthusiast segment margins.
For Investors and Strategic Acquirers: Industrial milling heritage players are the most active acquirer in this space, seeking precision burr foundry capabilities to complete vertical integration. Long-term viability favors targets with established ISO 22000 documentation and ceramic metallization expertise. Signal to monitor: BIS certification timeline compression in India that would accelerate market access for documented manufacturers versus undocumented competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Burr Supply Chain Capture | Swiss and Japanese precision foundries command threefold volume premiums over commodity alternatives. |
| REACH-Compliant Housing Reformulation | Glass and uncoated stainless steel development filters chrome-plated competitors from EU retail. |
| Direct-to-Consumer Channel Launch | Brand-owned storefronts bypass Sur La Table and Williams Sonoma equivalent markups for enthusiast segments. |
| ISO 22000 Certification Investment | Food safety documentation opens food processing unit procurement specifications across B2B channels. |
| German Precision Engineering Cluster Expansion | Stuttgart and Solingen supplier networks anchor premium burr production for export markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with grinder product managers, ceramic component procurement leads at precision foundries, specialty coffee shop operations directors, and kitchenware category buyers at major retailers with secondary validation. Sources included customs and trade data for ceramic feedstock flows, SEC filings from listed appliance manufacturers, EU ECHA regulatory submission databases, and BIS certification registries. Bottom-up volume aggregation across product type, material, end user, and distribution channel segments was triangulated against top-down market sizing from comparable durable goods categories.
Comparable historical periods anchored the projection horizon, with growth trajectories modeled across electric, burr, manual, and blade product configurations alongside stainless steel, ceramic, glass, and plastic material tiers. CAGR derivation incorporated replacement cycle analysis for household versus commercial end users, regulatory compliance cost pass-through assumptions, and channel shift dynamics between online retail and specialty stores. Industry-specific inputs included REACH Annex XVII restriction timelines, BIS certification processing rates, and METI energy efficiency guideline adoption curves.
Underlying measurement precision varies by segment; ceramic burr grinder forecasts carry tighter precision than blade grinder projections due to concentrated supplier visibility. Forecasts reflect documented assumptions on regulatory enforcement intensity and ceramic feedstock price stabilization. Deviation in EU Green Deal material mandate acceleration or MEE environmental inspection frequency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Carthamus Yellow Market
Spices and Seasonings
Jalapeno Salt Market
Spices and Seasonings
Achiote Powder Market
Spices and Seasonings
Onion Oil Market
Spices and Seasonings
Cardamom Oil Market
Spices and Seasonings
Oregano Seasoning Market
Spices and Seasonings
Cajun Seasoning Market
Spices and Seasonings
Low Sodium Sea Salt Market
Spices and Seasonings
Serrata Extract Market
Spices and Seasonings
Boutique Salt Market
Spices and Seasonings
Cajun Spice Market
Spices and Seasonings
BBQ Seasoning Market
Spices and Seasonings
Global Clove Market
Spices and Seasonings
Green Pepper Market
Spices and Seasonings
Espresso Salt Market
Spices and Seasonings
Nutmeg Oil Market