
 Middle East and Africa Ashwagandha Market | 2026-2036
Middle East and Africa Ashwagandha Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Ashwagandha Market Foresight
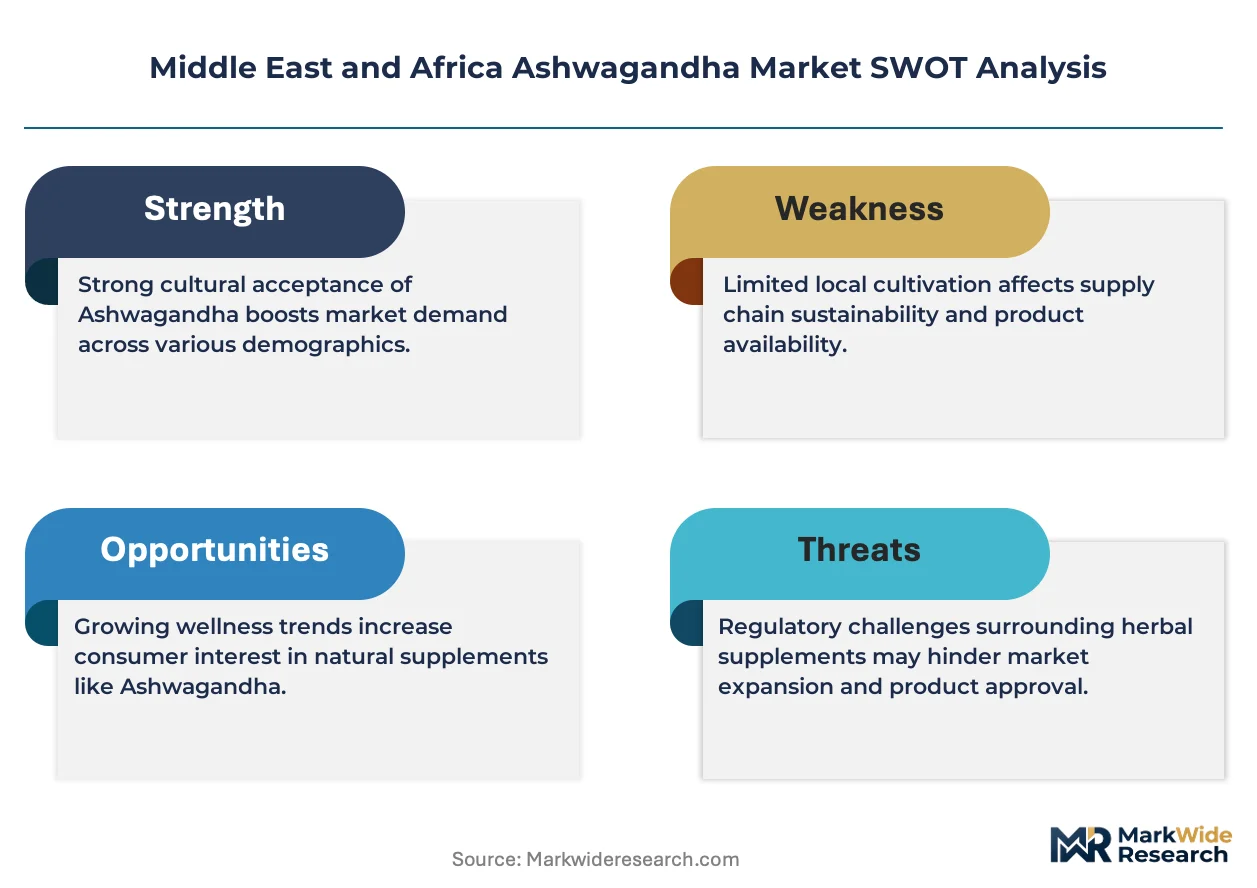
Fitness enthusiast demand is expanding across the Middle East and Africa Ashwagandha Market as gym chains and sports nutrition retailers add adaptogenic supplements to their core offerings. Himalaya Wellness dominates traditional pharmacy channels across the Gulf states with standardized root extract formulations. Gaia Herbs leverages its organic certification credentials to access premium health food stores in South Africa. Organic India anchors supply through Ayurvedic practitioner networks in Morocco and Egypt.
Ashwagandha (Withania somnifera) is a perennial shrub whose dried root and leaf material yields bioactive withanolides, typically standardized to concentrations between 2.5% and 5% for commercial supplement applications. The plant serves primarily as an adaptogenic ingredient in dietary supplements targeting cortisol modulation and neurological support. Powder formulations occupy the volume base of the market, serving bulk buyers and traditional medicine practitioners across North Africa. Capsules capture margin concentration through pharmacy and online channels where convenience commands pricing power. Liquid extracts lead within wellness center and healthcare professional segments due to customizable dosing protocols and faster perceived absorption profiles.
South Africa's Health Products Regulatory Authority and the Saudi Food and Drug Authority both enforce botanical ingredient disclosure and withanolide standardization requirements that filter uncertified suppliers from formal retail channels. The Emirates Authority for Standardization and Metrology (ESMA) applies halal certification protocols that shape import eligibility for finished ashwagandha products entering UAE distribution networks. Stakeholders must monitor evolving national pharmacopeia adoptions and adaptogen-specific monograph developments that will determine which extract grades gain formulary acceptance across the region's divergent regulatory regimes.
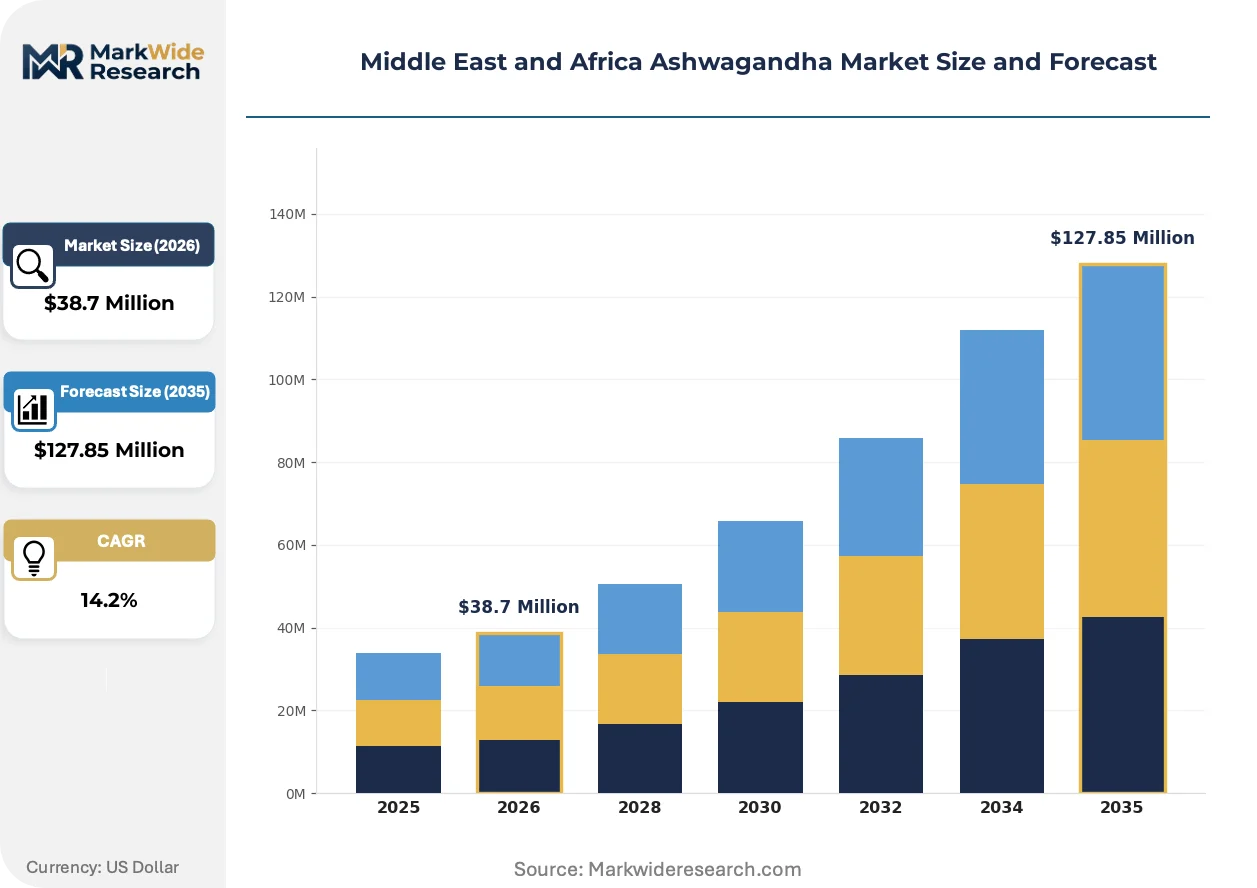
Market Dynamics
Halal certification protocols from the Emirates Authority for Standardization and Metrology are filtering import eligibility and reshaping supplier access across Gulf distribution networks, while South Africa's tightened botanical registration requirements are compressing formal retail participation.
Growth Catalysts
- Ayurvedic wellness tourism:The United Arab Emirates is attracting destination health travelers seeking traditional botanical therapies, creating dedicated demand channels for standardized root extracts in hospitality and clinical settings.
- Sports nutrition retail expansion:Gym chains across Saudi Arabia and the UAE are adding adaptogenic supplements to core offerings, embedding ashwagandha into performance-focused consumer routines.
- Withanolide standardization mandates:The Saudi Food and Drug Authority's disclosure requirements are legitimizing extract grades and accelerating pharmacy channel penetration for certified suppliers.
Market Restraints
- Raw material import dependence:Regional formulators rely on Indian and Chinese root supply, exposing margins to currency volatility and agricultural yield fluctuations.
- Dual regulatory compliance costs:Meeting both ESMA halal protocols and national pharmaceutical standards creates layered certification expenses that disadvantage smaller traders.
- Synthetic adaptogen substitution:Pharmaceutical-grade synthetic compounds targeting cortisol modulation compete for clinical practitioner preference in South African wellness centers.
Strategic Opportunities
- Morocco practitioner networks:Underdeveloped Ayurvedic professional infrastructure offers first-mover positioning for certified extract suppliers building B2B relationships.
- Liquid extract wellness center channels:Customizable dosing formats align with healthcare professional segments seeking faster absorption profiles and protocol flexibility.
- Egypt retail pharmacy modernization:Expanding pharmacy chains present shelf-space opportunities for capsule formats targeting convenience-driven urban consumers.
Industry Challenges
- Phytochemical assay standardization:Inconsistent withanolide testing methodologies across national laboratories create batch-to-batch quality disputes and commercial friction.
- Halal supply chain verification:Tracing root origin through processing facilities to finished product requires documentation systems many legacy suppliers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Ashwagandha Market |
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $127.85 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsules, Liquid Extract, Gummies End User: Healthcare Professionals, Fitness Enthusiasts, Wellness Centers, Retail Customers Distribution Channel: Online Stores, Pharmacies, Health Food Stores, Supermarkets Application: Stress Relief, Sleep Aid, Cognitive Function, Immune Support |
| Companies Covered | Patanjali Ayurved, Gaia Herbs, Himalaya Wellness, Unilever, Nature's Way, Organic India, NOW Foods, Kerry Group, Dabur India, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Ashwagandha Market Shifts & Advancements
Supercritical CO2 extraction technology is rewriting extract purity benchmarks across Middle East and Africa processing facilities, while regulatory harmonization pressures and shifting buyer channel preferences are compressing traditional distribution hierarchies.
Supercritical CO2 extraction systems are rewriting competitive positioning for premium extract grades by delivering higher withanolide concentrations without solvent residues. South African health food retailers and UAE wellness centers are adopting these extracts at accelerating pace to meet halal certification and organic credential requirements. The technology is compressing price premiums between pharmaceutical-grade and traditional solvent-extracted products.
ESMA's halal certification protocols for botanical supplements are tightening import documentation and facility audit requirements. Manufacturers must now demonstrate segregation of non-halal processing equipment and ingredient streams to maintain UAE market access. Finished product importers are responding by qualifying dedicated halal-certified production lines or switching to contract manufacturers with existing ESMA approvals.
Fitness enthusiasts are bypassing traditional pharmacy channels and purchasing ashwagandha directly through gym-affiliated e-commerce platforms and sports nutrition subscription services. Dubai and Johannesburg gym chains are disintermediating retail intermediaries by launching private-label adaptogenic lines. This channel compression is most visible in metropolitan UAE and South African urban centers where digital payment infrastructure supports seamless direct-to-consumer fulfillment.
Middle East and Africa Ashwagandha Market Segmentation
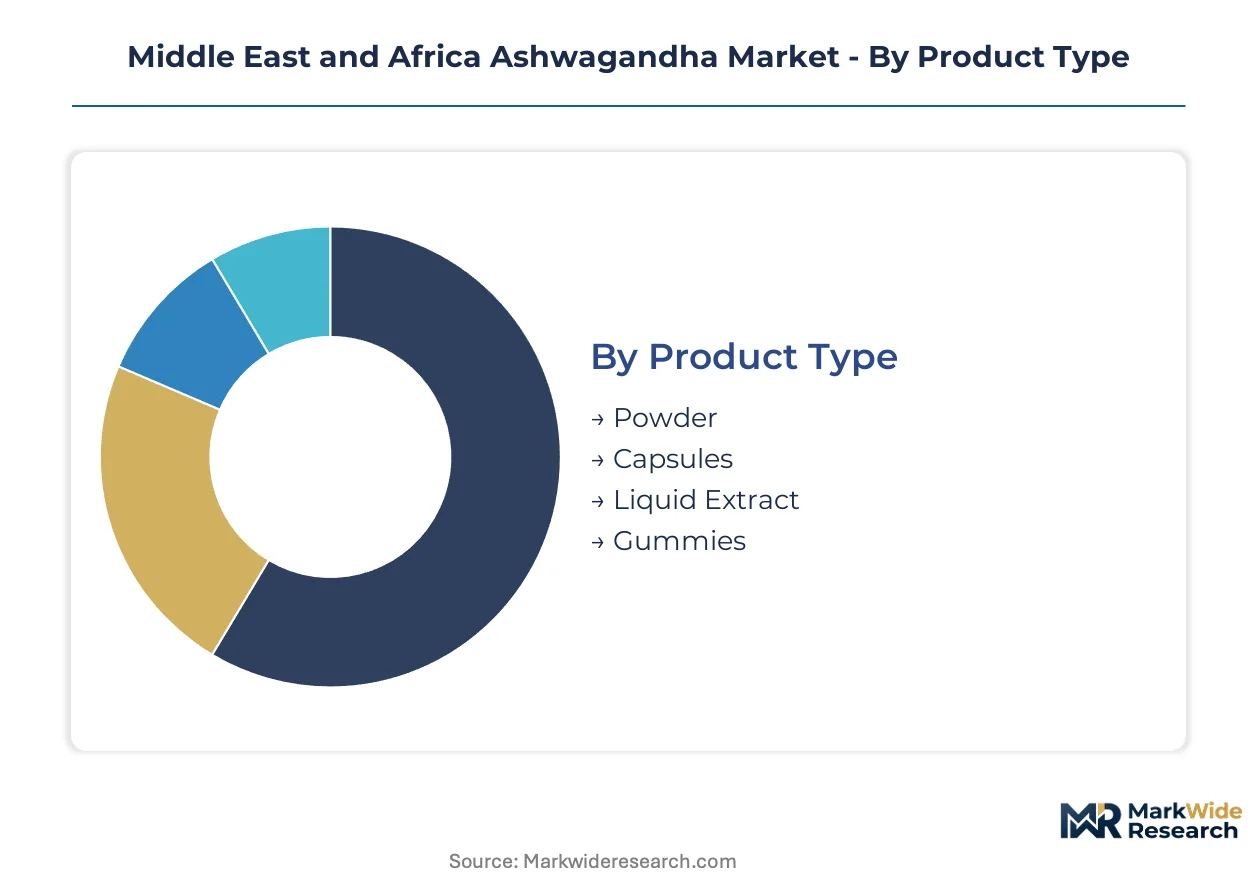
Segmentation reveals how ashwagandha formats align with divergent purchasing behaviors across the Middle East and Africa. Each axis—product form, end user, channel, and therapeutic claim—carries distinct margin structures and regulatory exposure that shape supplier strategy.
Product Type:
Standardization technology and extraction method determine bioactive potency, shelf stability, and halal certification feasibility across finished goods.
- Powder:Dried root material ground to coarse or fine particle size, typically bulk-packaged for traditional medicine practitioners and industrial formulators. North African herbalists in Morocco and Egypt source multi-kilogram sacks for compounding, though powder's moisture sensitivity complicates Gulf climate logistics.
- Capsules:Encapsulated standardized extracts delivering precise withanolide doses, commanding pharmacy shelf placement through convenience positioning. Saudi Arabian retail pharmacy chains and UAE hospital dispensaries favor blister-packed formats for patient compliance tracking.
- Liquid Extract:Hydroalcoholic or glycerin-based tinctures enabling titrated dosing protocols. South African wellness centers and Dubai integrative health clinics prescribe these for cortisol modulation programs requiring dose flexibility.
- Gummies:Pectin or gelatin matrices masking bitter alkaloid taste, targeting younger demographics through novelty positioning. ESMA halal gelatin sourcing requirements constrain supplier pools for UAE-bound production.
Powder leads on scale; gummies lead on momentum.
End User:
Professional credential requirements and purchase authorization rules segment demand into institutional and self-directed consumption pools.
- Healthcare Professionals:Physicians, naturopaths, and clinical herbalists prescribing standardized extracts within treatment protocols. South Africa's Health Products Regulatory Authority registration requirements filter uncertified products from practitioner-recommended portfolios.
- Fitness Enthusiasts:Gym members and amateur athletes seeking adaptogenic support for training recovery. Saudi Arabian and UAE gym chains now stock ashwagandha adjacent to protein supplements, embedding the botanical into performance nutrition routines.
- Wellness Centers:Destination health facilities and spa clinics integrating Ayurvedic therapies. Dubai's medical tourism corridor and Johannesburg integrative health hubs drive concentrated demand for high-grade extracts.
- Retail Customers:Self-selecting consumers purchasing without professional guidance. Egyptian pharmacy modernization and Moroccan supermarket expansion are opening shelf access for mass-market formats.
Retail customers lead on scale; fitness enthusiasts lead on momentum.
Distribution Channel:
Channel selection determines margin capture, brand control, and exposure to regulatory inspection intensity.
- Online Stores:E-commerce platforms and direct-to-consumer websites bypassing retail intermediaries. Dubai and Johannesburg gym-affiliated subscription services are disintermediating traditional pharmacy channels through digital payment infrastructure.
- Pharmacies:Licensed retail dispensaries with trained staff and cold-chain capabilities. Saudi Food and Drug Authority botanical registration requirements restrict pharmacy participation to certified suppliers meeting withanolide disclosure standards.
- Health Food Stores:Specialty retailers emphasizing organic and natural positioning. South African health food retailers are accelerating adoption of supercritical CO2 extracts to meet halal and organic credential demand.
- Supermarkets:Mass-market grocery channels reaching convenience-driven urban consumers. Egyptian retail pharmacy modernization and expanding supermarket chains present shelf-space opportunities for capsule formats.
Pharmacies lead on scale; online stores lead on momentum.
Application:
Therapeutic positioning determines regulatory classification, marketing claim permissibility, and competitive substitution risk.
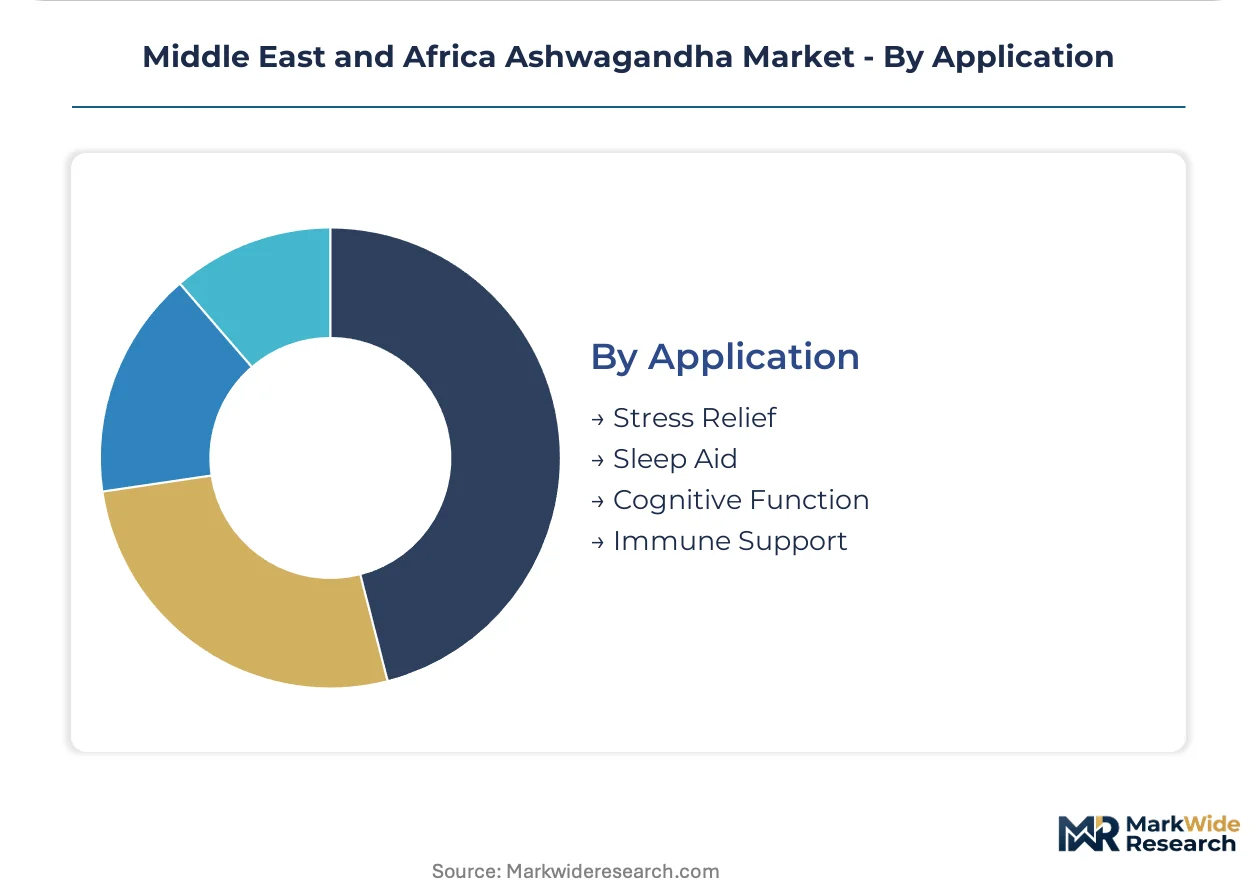
- Stress Relief:Cortisol modulation and anxiolytic positioning targeting chronic stress management. UAE wellness tourism marketing emphasizes traditional Ayurvedic stress protocols, creating hospitality and clinical demand channels.
- Sleep Aid:Sedative and sleep latency applications competing with pharmaceutical and botanical alternatives. South African wellness centers prescribe liquid extracts for insomnia protocols requiring dose titration flexibility.
- Cognitive Function:Nootropic claims around memory, focus, and neuroprotection. Saudi Arabian sports nutrition retail expansion embeds cognitive performance positioning into gym-affiliated product lines.
- Immune Support:Immunomodulatory marketing targeting general wellness maintenance. Moroccan and Egyptian practitioner networks present first-mover positioning for certified extract suppliers building B2B relationships in underdeveloped Ayurvedic infrastructure.
Stress relief leads on scale; immune support leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping supply chain configuration across the Middle East and Africa, as manufacturers migrate toward jurisdictions with streamlined botanical registration pathways while Gulf states tighten halal certification compliance costs.
United Arab Emirates
Dubai's medical tourism corridor attracts destination health travelers seeking Ayurvedic stress protocols, creating hospitality-linked demand for standardized root extracts. ESMA halal certification mandates filter import eligibility through facility audit requirements and equipment segregation protocols. Abu Dhabi wellness centers and Dubai integrative health clinics drive concentrated consumption of liquid extract formats for customizable cortisol modulation programs.
Saudi Arabia
Gym chains in Riyadh and Jeddah embed adaptogenic supplements into performance nutrition retail, embedding ashwagandha into amateur athlete recovery routines. The Saudi Food and Drug Authority enforces withanolide disclosure and botanical ingredient standardization that accelerates pharmacy channel penetration for certified suppliers. Riyadh's expanding retail pharmacy networks and Jeddah's sports nutrition subscription services disintermediate traditional distribution hierarchies.
South Africa
Johannesburg integrative health hubs and Cape Town wellness centers prescribe liquid extracts for insomnia protocols requiring dose titration flexibility. The Health Products Regulatory Authority tightened botanical supplement registration requirements, compressing formal retail participation to certified extract grades. Cape Town health food retailers accelerate adoption of supercritical CO2 extracts to meet halal credential and organic certification demand.
Egypt
Expanding pharmacy chains in Cairo and Alexandria present shelf-space opportunities for capsule formats targeting convenience-driven urban consumers. The country's national pharmaceutical regulator applies botanical ingredient disclosure requirements that filter uncertified suppliers from modernizing retail channels. Cairo supermarket expansion and Alexandria port logistics clusters facilitate import distribution for mass-market supplement formats.
Morocco
Underdeveloped Ayurvedic professional infrastructure in Casablanca and Rabat offers first-mover positioning for certified extract suppliers building B2B practitioner relationships. Moroccan national standards authorities are developing adaptogen-specific monograph frameworks that will determine extract grade formulary acceptance. Casablanca herbalist networks and Marrakech wellness tourism operators create dual-channel demand for traditional powder formats and standardized extracts.
Middle East and Africa Ashwagandha Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmacy-channel dominance concentrating around standardized extract suppliers while wellness center and sports nutrition channels fragment across regional formulators. The vendor base organizes into three strategic archetypes: Indian-origin Ayurvedic houses with Gulf distribution infrastructure, North American organic-certified specialists accessing premium health food retail, and regional contract manufacturers serving private-label gym and hospitality channels. Competitive moves center on halal supply chain certification investments and supercritical CO2 extraction capacity expansion.
Among Indian-origin Ayurvedic houses, Patanjali Ayurved, Himalaya Wellness, and Dabur India exemplify the traditional pharmacy-channel archetype with established Gulf state distribution infrastructure. These entities occupy positions shaped by decades of standardized root extract formulation and regulatory compliance across Middle Eastern botanical registration regimes. Gaia Herbs and Organic India represent the organic-certified specialist tier, anchoring premium health food store access in South Africa through certification credentials that satisfy halal and organic dual requirements. Kerry Group sits within the ingredient supply tier, serving regional formulators and contract manufacturers with extract grades for private-label production.
| Leading Market Players |
|---|
| Patanjali Ayurved |
| Gaia Herbs |
| Himalaya Wellness |
| Unilever |
| Nature's Way |
| Organic India |
| NOW Foods |
| Kerry Group |
| Dabur India |
| Others |
Supply & Pricing Matrix
Indian root procurement costs cascade through three distinct pricing tiers as raw material journeys from Mumbai export houses to Gulf retail pharmacies, with ESMA halal certification premiums layering atop standard extract grades.
Pricing Analysis
Distributor margins compress toward the pharmacy channel while direct-to-consumer wellness center sales capture fuller value. Three-tier pricing structure across pharmaceutical-grade, health food retail, and bulk practitioner formats separates certified supercritical CO2 extracts from traditional solvent-based products. Pricing pressure stems from synthetic adaptogen substitution in South African clinical settings. Retail customers exhibit highest price sensitivity; wellness centers and healthcare professionals accept premium positioning for customizable dosing protocols.
Supply Chain Analysis
Return flows of expired or non-conforming botanical material remain minimal given perishable extract degradation, though South African health food retailers increasingly demand supplier take-back programs for packaging sustainability compliance. Root supply concentrates in India and China, with processing capacity expanding in UAE free trade zones. Withanolide standardization testing, halal certification documentation, and moisture-controlled logistics constitute critical input dependencies. Single-source vulnerability runs through Indian monsoon-dependent agricultural yields. Distribution runs through Dubai Jebel Ali logistics clusters for Gulf state redistribution and Johannesburg pharmaceutical import hubs for Southern Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as buyer sophistication shifts toward withanolide-standardized extracts and halal-certified supply chains, displacing commodity-grade powder formulations.
For Market Incumbents: Extend certification infrastructure investments to defend pharmacy channel positioning against emerging organic-certified specialists from North America. Deepen backward integration into Indian contract farming arrangements to secure root supply with traceability documentation required by ESMA protocols. Counter synthetic adaptogen substitution threats in South African wellness centers through clinical study sponsorship and practitioner education programs. For New Entrants and Emerging Players: SFDA withanolide disclosure mandates in Saudi Arabia open a window for certified extract suppliers to capture shelf space in modernizing retail pharmacy networks. Target Morocco's underdeveloped Ayurvedic practitioner infrastructure through B2B relationship building with Casablanca herbalist networks. Pursue liquid extract wellness center channels in Dubai and Johannesburg where customizable dosing protocols command premium positioning and regulatory barriers filter uncertified competitors. For Investors and Strategic Acquirers: Consolidation pressure builds where halal certification compliance costs and supercritical CO2 extraction capital requirements disadvantage smaller regional formulators. Long-term viability favors vertically integrated players with captive Indian root supply and Gulf distribution infrastructure. Acquisition target archetype: mid-scale UAE-based contract manufacturers with existing ESMA approvals and wellness center channel relationships. Monitor Saudi pharmacy retail modernization and Egyptian supermarket expansion as inflection indicators for mass-market format demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Supply Chain Certification | ESMA facility audit compliance secures UAE market access and pharmacy channel eligibility. |
| Supercritical CO2 Extraction Capacity Expansion | Solvent-free processing meets organic credential demand from South African health food retailers. |
| Practitioner Network Development | B2B relationships with Moroccan herbalists capture first-mover positioning in underdeveloped Ayurvedic infrastructure. |
| Direct-to-Consumer Platform Launch | Gym-affiliated subscription services in Dubai and Johannesburg disintermediate traditional retail intermediaries. |
| Clinical Study Sponsorship | Evidence generation counters synthetic adaptogen substitution in South African wellness center protocols. |
Research Methodology
Multiple input streams — regulatory filing analysis, trade customs data, and channel inventory tracking — were reconciled against primary fieldwork with Ayurvedic practitioners, pharmacy procurement managers, wellness center directors, and sports nutrition retail buyers. Secondary validation drew from SFDA botanical registration databases, ESMA halal certification records, South African Health Products Regulatory Authority filings, and Indian export promotion council statistics. Bottom-up segment sizing and top-down macroeconomic anchoring were cross-referenced for triangulation.
Historical volume trajectories were cross-referenced against panel input from industry participants to construct projection frameworks across the analysis window. Segmentation dimensions modeled include product format, end-user archetype, distribution channel, and therapeutic application claim. CAGRs were derived from trend extrapolation moderated by regulatory adoption curves and channel modernization rates. Industry-specific forecast inputs encompassed withanolide standardization mandate implementation timelines and halal certification facility audit completion schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Indian agricultural yield disruption or abrupt regulatory harmonization across Gulf states. Practitioners should monitor ESMA monograph developments and Saudi pharmacy retail licensing acceleration for early signals of competitive access shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Lemon Salt Market
Spices and Seasonings
Asia-Pacific Spice and Herb Extracts Market
Spices and Seasonings
Mullein Leaf Market
Spices and Seasonings
Egypt Herbs and Spices Market
Spices and Seasonings
Onion Salt Market
Spices and Seasonings
South America Seasoning and Spices Market
Spices and Seasonings
Thyme Extract Market
Spices and Seasonings
Achiote Powder Market
Spices and Seasonings
Herbs and Spices Market
Spices and Seasonings
Garlic Oleoresin Market
Spices and Seasonings
Global Black Pepper Market
Spices and Seasonings
Tamarind Extract Market
Spices and Seasonings
Low Sodium Sea Salt Market
Spices and Seasonings
Global Spices and Stimulants Market
Spices and Seasonings
Europe Seasoning and Spices Market
Spices and Seasonings
Moringa Leaves Powder Market