
 Garlic Salt Market | 2026-2036
Garlic Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Garlic Salt Market Analytics
Multi-source procurement for dehydrated garlic feedstock is shifting toward vertically integrated salt-garlic operations in major producing zones. Morton Salt leverages captive brine evaporation capacity to secure cost-advantaged supply chains. Tata Group anchors its position through integrated farming partnerships in Gujarat. Windsor differentiates via specialty grinder-format packaging that commands premium placement in retail.
Garlic salt denotes a blended condiment comprising dried garlic particles dispersed within a sodium chloride carrier, typically containing two to five percent garlic by mass alongside flow agents to prevent caking during shelf storage. Manufacturers employ roller drying or freeze-drying of Allium sativum bulbs followed by precision blending with iodized or non-iodized salt bases to achieve flavor consistency across batches. Sea salt variants within the product type segment attract margin premiums due to perceived mineral complexity and artisan positioning in specialty stores. Pouch packaging formats among household end users expand fastest as single-use convenience aligns with meal-kit subscription channels, while jar formats sustain entrenched demand from restaurants seeking bulk visibility and moisture protection.
FDA oversight of food additive labeling and USDA organic certification requirements shape formulation choices and market access for domestic suppliers, while EU REACH compliance for anti-caking agents constrains export-oriented producers seeking European supermarket placement. Stakeholders must monitor evolving sodium-reduction mandates from health regulators and corresponding consumer acceptance of potassium-chloride partial substitutes in seasoned salt applications.
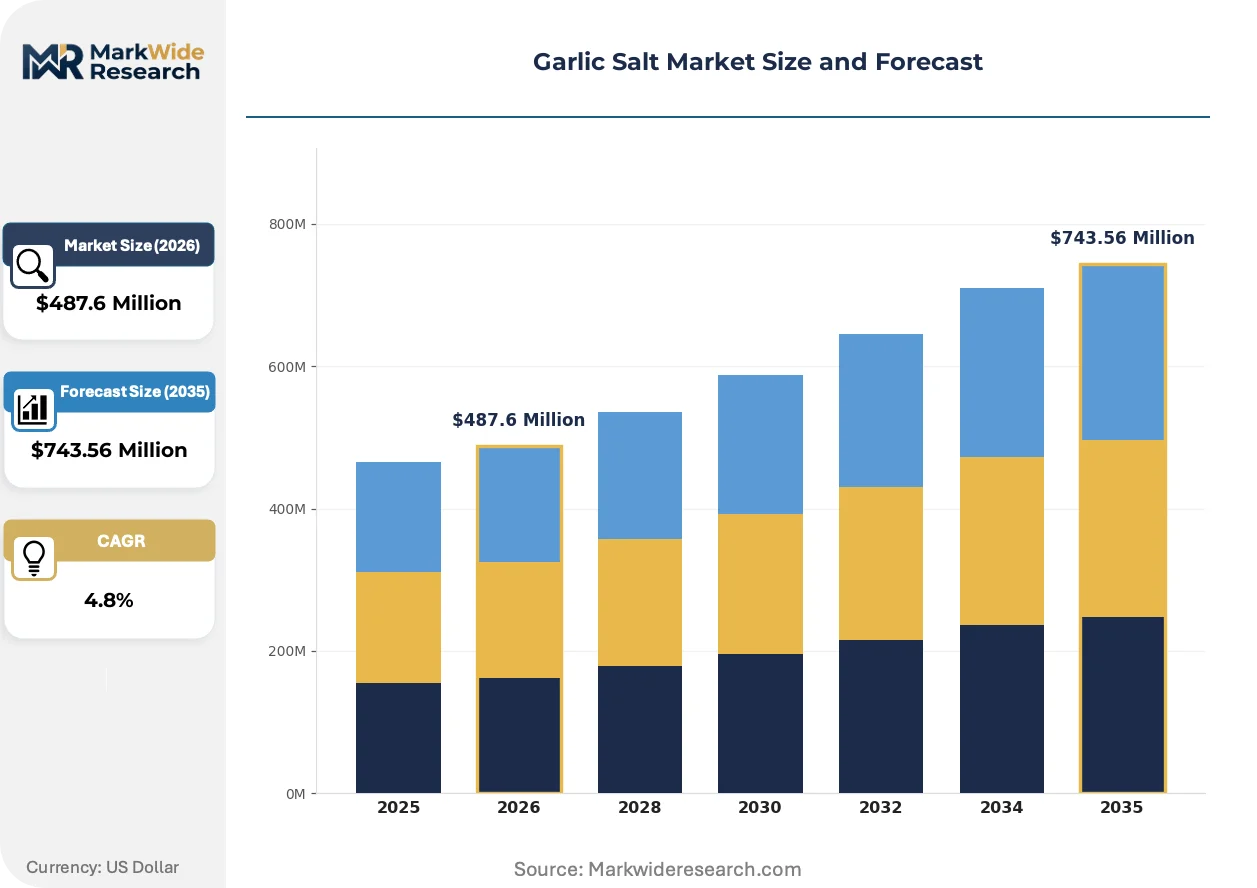
Market Dynamics
Clean-label mandates are forcing garlic salt manufacturers to reformulate anti-caking agents while meal-kit subscription channels accelerate single-serve packaging demand, compressing traditional jar-format dominance in household segments.
Growth Catalysts
- Meal-kit channel expansion:Subscription box services in the United States drive pouch-format adoption for portion-controlled seasoning, creating dedicated SKU demand from co-packing partners.
- EU organic certification:USDA organic and EU organic labeling requirements push conventional producers toward certified supply chains, opening premium placement in specialty retail.
- Sodium reduction mandates:Health Canada and FDA guidance on sodium limits stimulate potassium-chloride blend development, expanding the addressable product portfolio for reformulation specialists.
Market Restraints
- Dehydrated garlic input volatility:Climate-dependent harvests in Gujarat and Henan provinces generate raw material price swings that compress blender margins.
- REACH compliance costs:ECHA restrictions on silicon dioxide and tricalcium phosphate anti-caking formulations force European export producers into costly re-registration cycles.
- Fresh garlic substitution:Foodservice operators in quick-service restaurants increasingly specify fresh-minced or roasted garlic preparations, displacing dried-blend demand in back-of-house applications.
Strategic Opportunities
- Underpenetrated e-commerce:Direct-to-consumer seasoning subscriptions in Germany and France remain below US penetration rates, offering first-mover positioning for private-label aggregators.
- Potassium-enriched lines:Cardiovascular health positioning enables premium pricing for reduced-sodium variants targeting hypertensive consumer segments.
- Grinder-format premiumization:Adjustable-grind packaging technology converges with sea salt positioning to command shelf-space allocation in specialty grocers.
Industry Challenges
- Clean-label reformulation timelines:Removing silicon dioxide while maintaining flowability requires 12-18 month stability testing, delaying product launches.
- Moisture barrier engineering:Pouch formats demand multi-layer film expertise that legacy jar-oriented manufacturers must acquire through equipment retrofit or contract manufacturing partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Garlic Salt Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Table Salt, Sea Salt, Rock Salt, Himalayan Salt Packaging Type: Bottles, Sachets, Jars, Pouches Distribution Channel: Online Retail, Supermarkets, Wholesalers, Specialty Stores End User: Households, Restaurants, Food Manufacturers, Catering Services |
| Companies Covered | Windsor, Akzo Nobel, Morton Salt, Cheetam Salt, Dev Salt Private, Tata Group, United Salt Corporation, Dampier Salt, Cerebos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Garlic Salt Market Evolving Landscape
Freeze-drying technology is consolidating processing economics while regulatory pressure on additives intersects with shifting household consumption patterns toward convenience-oriented formats.
Freeze-drying of Allium sativum bulbs is consolidating cost structures previously dominated by roller-dried alternatives. Mid-tier seasoning blenders in the United States are adopting lyophilization equipment to capture flavor intensity premiums in specialty retail channels. This technology compression enables smaller-batch production with extended shelf stability, reshaping capital requirements for new market entrants.
EU REACH compliance for anti-caking agents is tightening permissible additive lists across exported formulations. Manufacturers targeting EFSA-authorized placements must substitute silicon dioxide with rice flour or cellulose alternatives, increasing per-unit ingredient costs. Sea salt variants face the steepest reformulation burden given their artisan positioning and consumer expectations around minimal processing.
Meal-kit procurement specifications are fragmenting bulk seasoning demand into single-serve sachet requirements. Recipe-box operators in the United Kingdom and Netherlands specify exact gram weights per portion, displacing traditional jar purchases among urban dual-income households. This channel shift forces garlic salt producers to install form-fill-seal lines previously unnecessary for retail grocery distribution.
Garlic Salt Market Segmentation
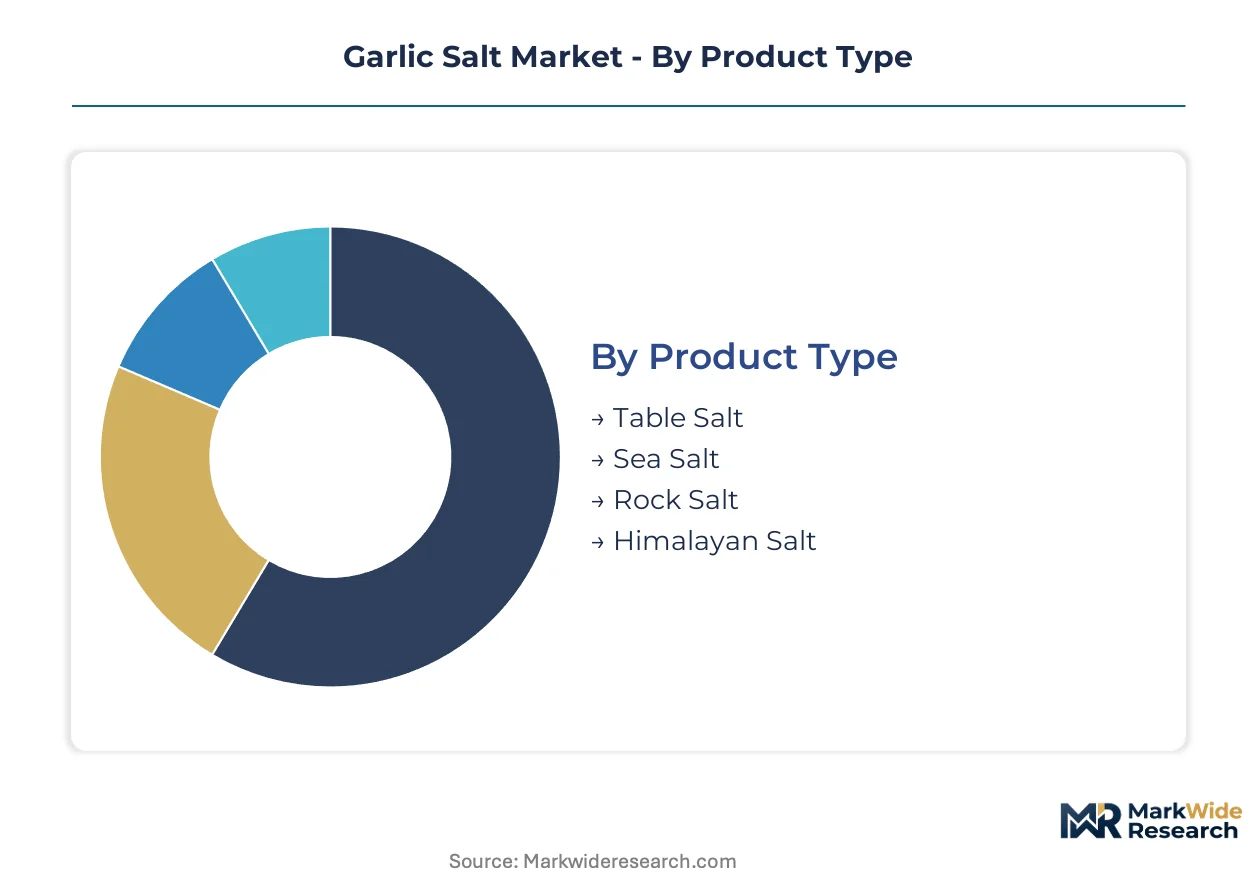
Segmentation in garlic salt reveals how sodium chloride carriers, convenience formats, and channel access determine margin capture. Manufacturers optimize across mineral sourcing, moisture protection engineering, and end-use specifications to defend position.
Product Type:
Volume concentrates in mass-market iodized variants while artisan positioning commands shelf-space premiums in specialty retail.
- Table Salt:Refined sodium chloride with standardized crystal size enables uniform garlic particle dispersion. Household demand in the United States concentrates here due to private-label penetration in conventional grocery. FDA iodization mandates shape fortification protocols.
- Sea Salt:Unrefined evaporated seawater retains trace minerals that support clean-label positioning. Demand clusters in coastal urban markets where consumers prioritize perceived mineral complexity over sodium purity. EFSA labeling scrutiny elevates compliance costs for European export variants.
- Rock Salt:Mined halite deposits with coarse granulation suit grinder-format applications. Industrial food manufacturers specify this carrier for controlled dissolution rates in processed meat applications.
- Himalayan Salt:Pakistani-mined halite with iron oxide-derived pink coloration supports premium placement. Specialty stores in Germany and France allocate disproportionate shelf space to this variant.
Today's leader: Table Salt. Tomorrow's challenger: Sea Salt.
Packaging Type:
Moisture barrier requirements diverge sharply between foodservice bulk handling and household convenience expectations.
- Bottles:Polyethylene terephthalate containers with desiccant closures protect flowability in humid climates. Restaurant chains in Florida and Louisiana specify this format for back-of-house durability.
- Sachets:Single-serve paper-foil laminates align with meal-kit portion specifications. United Kingdom recipe-box operators drive fastest adoption here, displacing jar purchases among urban dual-income households.
- Jars:Glass containers with metal lids sustain visibility-driven placement in conventional grocery. Established demand from institutional catering resists format migration despite higher unit costs.
- Pouches:Multi-layer flexible films with resealable zippers capture convenience-oriented household segments. Co-packing partnerships with subscription services accelerate capacity installation.
Sachets are expanding most quickly. Jars retain entrenched foodservice loyalty.
Distribution Channel:
Channel selection determines whether producers capture retail margin or cede value to intermediaries.
- Online Retail:Direct-to-consumer platforms enable subscription bundling and flavor customization. Private-label aggregators in France and Germany underpenetrate relative to United States benchmarks, offering first-mover positioning.
- Supermarkets:Conventional grocery chains dominate volume throughput via promotional slotting fees. Clean-label reformulations face compressed margins here due to price-point competition.
- Wholesalers:Broadline distributors consolidate restaurant and institutional demand into pallet-scale transactions. Food Manufacturers rely on this channel for input procurement efficiency.
- Specialty Stores:Gourmet retailers command placement premiums for sea salt and Himalayan variants. EU organic certification unlocks access here.
Supermarkets anchor current volume. Online Retail shows steepest expansion trajectory.
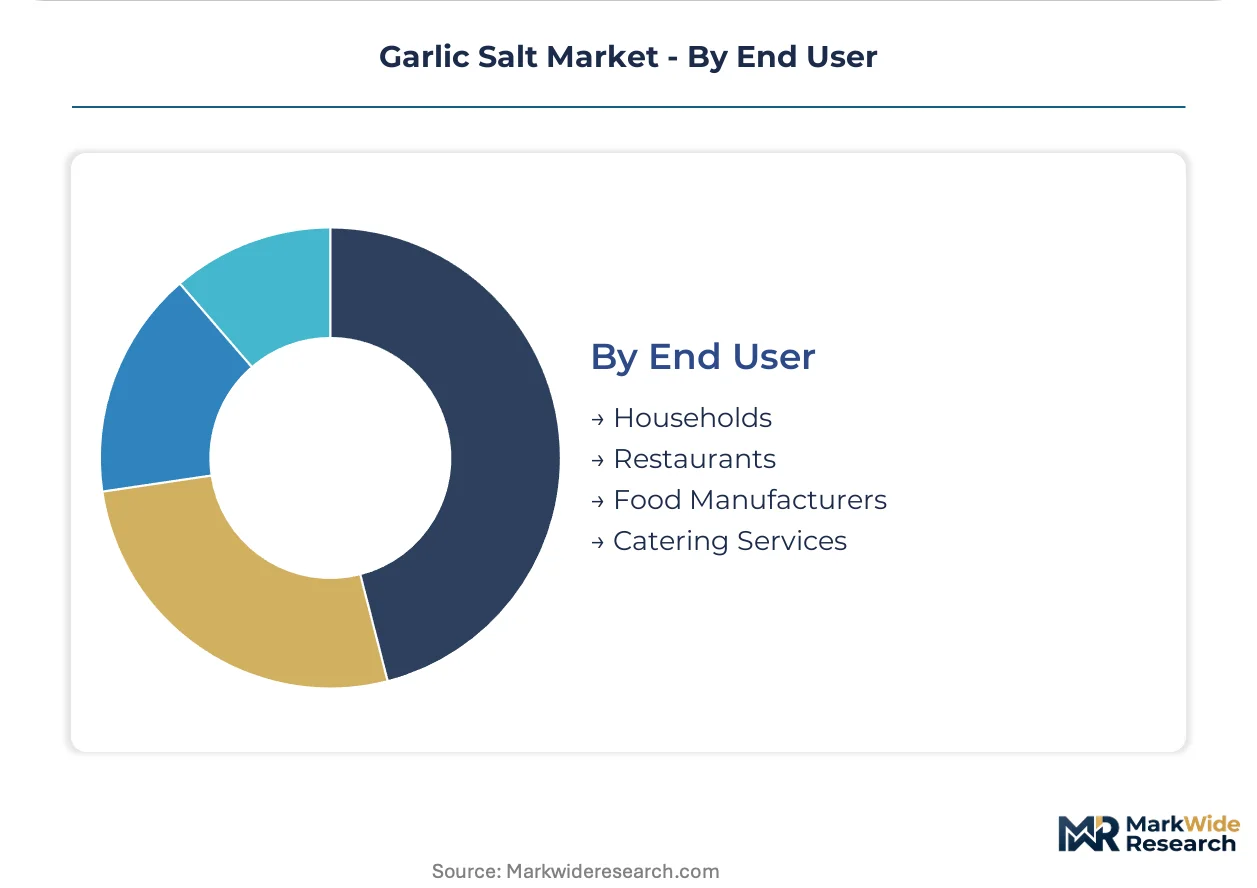
End User:
Application specifications separate commodity blending from value-added formulation services.
- Households:Convenience-driven consumers prioritize resealable pouches and single-serve sachets for meal-kit integration. Sodium reduction mandates from Health Canada influence reformulation acceptance.
- Restaurants:Quick-service operators increasingly specify fresh-minced garlic preparations, displacing dried-blend demand in back-of-house applications. Full-service chains sustain jar-format procurement for tabletop visibility.
- Food Manufacturers:Processed meat and snack seasoning applications require precise particle size distribution and anti-caking stability. REACH-compliant formulations are mandatory for European export customers.
- Catering Services:Institutional volume buyers prioritize cost efficiency over packaging aesthetics. Bulk tote deliveries with customized garlic concentration specifications dominate this segment.
Food Manufacturers drive formulation innovation. Households are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's integrated salt-garlic processing corridor anchors supply-side concentration for dehydrated feedstock, with vertically integrated operations extending from captive brine evaporation through precision blending facilities.
United States
Private-label penetration in conventional grocery chains drives volume concentration, with meal-kit subscription services fragmenting demand into single-serve sachet specifications. FDA oversight of food additive labeling shapes reformulation timelines for anti-caking agent substitutions. California and Florida restaurant chains sustain jar-format procurement for back-of-house durability in humid climates.
Germany
Specialty retailers allocate disproportionate shelf space to Himalayan and sea salt variants, with organic certification unlocking premium placement in gourmet channels. ECHA REACH compliance for anti-caking agents constrains silicon dioxide formulations, elevating rice flour substitute costs. The Eindhoven-Rotterdam corridor hosts co-packing partnerships serving Netherlands recipe-box operators.
India
Tata Group's captive farming partnerships in Gujarat secure dehydrated garlic feedstock through backward integration into bulb cultivation. FSSAI fortification mandates for iodized carriers shape blending protocols for domestic consumption. The Kutch salt pans concentrate solar evaporation capacity for cost-advantaged sodium chloride supply.
United Kingdom
Recipe-box operators in Greater London specify exact gram weights per portion, displacing traditional jar purchases among urban dual-income households. EFSA labeling scrutiny elevates compliance costs for exported formulations targeting continental European supermarkets. Manchester-based co-packers install form-fill-seal capacity for subscription channel fulfillment.
China
Henan province climate-dependent garlic harvests generate raw material price volatility that compresses blender margins. SAMR food safety standards govern additive disclosure requirements for domestic distribution. Qingdao processors supply freeze-dried Allium sativum to Japanese and South Korean seasoning blenders.
Garlic Salt Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty grinder formats and potassium-enriched lines to capture cardiovascular health positioning. The vendor base stratifies across captive brine evaporation operators, integrated farming partnerships, and contract manufacturing specialists serving meal-kit channels. Three archetypes dominate: vertically integrated salt-garlic processors, private-label aggregators, and premium-format packaging innovators. Capacity expansion in lyophilization equipment and strategic partnerships for pouch-format co-packing represent the dominant competitive moves.
Among North American salt processors, Morton Salt exemplifies captive supply chain control through brine evaporation infrastructure, while Windsor occupies a position in adjustable-grind packaging technology for premium retail placement. Tata Group anchors integrated farming partnerships in Gujarat, representing the backward-integration archetype for feedstock security. These three entities illustrate how scale-driven extraction, format innovation, and upstream agricultural control constitute distinct strategic vectors.
| Leading Market Players |
|---|
| Windsor |
| Akzo Nobel |
| Morton Salt |
| Cheetam Salt |
| Dev Salt Private |
| Tata Group |
| United Salt Corporation |
| Dampier Salt |
| Cerebos |
| Others |
Value Network & Pricing Analysis
Sea salt versus iodized table salt bifurcation generates divergent margin architectures across the garlic salt category, with artisan mineral sourcing commanding shelf-space premiums while commodity blending competes on private-label throughput. This tier divergence maps directly onto supply chain configurations: premium variants draw from evaporative operations in Gujarat and Pakistan with dedicated grinder-format packaging lines, whereas mass-market production leverages captive brine infrastructure with centralized pouch-co-packing partnerships.
Pricing Analysis
Dehydrated garlic feedstock volatility in Henan and Gujarat passes through to finished goods with 3-6 month lag structures, compressing blender margins during climate-driven harvest shortfalls. Three-tier pricing structure across premium, standard, and economy levels separates Himalayan grinder formats from conventional iodized jars and private-label pouches. Pricing pressure stems from REACH-compliant reformulation costs elevating per-unit ingredient spend for European export variants. Food manufacturers exhibit highest price sensitivity due to bulk procurement scale, while specialty retailers absorb premiums for clean-label positioning.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Chicago, and Singapore consolidate finished goods inventory before last-mile deployment to retail and foodservice channels. Supply concentrates in India, China, and the United States for dehydrated garlic feedstock, with Pakistan anchoring Himalayan salt extraction. Raw material dependencies center on Allium sativum bulb harvests, solar-evaporated sodium chloride, and anti-caking agent formulations. Single-source vulnerability in Gujarat garlic processing creates concentration risk during monsoon disruptions. Distribution runs through broadline wholesalers for institutional volume and direct-to-platform fulfillment for subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The garlic salt category has matured into a late-cycle quality story where cardiovascular health positioning and clean-label certification now determine margin capture ahead of commodity scale. Demand is shifting decisively toward premium specifications: potassium-enriched lines, sea salt variants, and adjustable-grind formats command disproportionate shelf-space allocation.
For Market Incumbents: To counter fresh garlic substitution in quick-service restaurant back-of-house applications, Morton Salt and Tata Group should deepen backward integration into captive farming partnerships while accelerating lyophilization capacity installation for flavor intensity differentiation. Defensive moves must prioritize REACH-compliant formulation pipelines to defend European supermarket placement against re-registration delays. For New Entrants and Emerging Players: EU organic certification in Germany and France opens a window for private-label aggregators to capture underpenetrated direct-to-consumer subscription demand. White-space targets include potassium-enriched lines for hypertensive consumer segments and co-packing partnerships with Netherlands recipe-box operators. The most penetrable entry vector is specialty grinder-format packaging for coastal urban markets. For Investors and Strategic Acquirers: Consolidation pressure builds where freeze-drying equipment scarcity meets meal-kit channel specification fragmentation. Long-term viability favors vertically integrated salt-garlic processors with captive brine evaporation and certified organic supply chains. Acquisition target archetype: mid-tier blenders with installed pouch-format capacity and EU organic certification. The signal to watch is potassium-chloride blend acceptance rates under Health Canada sodium reduction guidance.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Garlic Cultivation | Tata Group's Gujarat farming partnerships secure feedstock against Henan climate volatility. |
| Freeze-Drying Capacity Expansion | Lyophilization equipment captures flavor intensity premiums in specialty retail channels. |
| REACH-Compliant Reformulation | Rice flour anti-caking substitutes unlock EFSA-authorized European supermarket placement. |
| Meal-Kit Co-Packing Partnerships | Form-fill-seal lines serve United Kingdom recipe-box operators with exact gram specifications. |
| Premium Grinder-Format Launch | Adjustable-grind packaging commands shelf-space allocation in German and French specialty grocers. |
Research Methodology
Multiple input streams — procurement director interviews at seasoning blenders, regulatory filing analysis, and retail audit data — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged plant managers at dehydration facilities, category buyers at United States supermarket chains, technical R&D directors at salt processors, and supply planners at meal-kit subscription services. Secondary validation drew from FDA food additive filings, ECHA REACH registration databases, FSSAI fortification protocols, and customs trade records for dehydrated garlic and sodium chloride flows.
Historical volume trajectories were cross-referenced against panel input from industry participants to construct segment-level projections across the analysis window. The analytical framework modeled carrier type, packaging format, distribution channel, and end-use application as core segmentation dimensions. CAGRs were derived from regression analysis of input-cost pass-through patterns and channel-shift elasticity parameters. Forecast inputs included climate-derived harvest variability indices and regulatory compliance timeline assumptions for anti-caking agent substitutions.
Revisions become necessary when REACH restriction amendments, sodium reduction mandate accelerations, or fresh garlic substitution thresholds in foodservice materialize beyond baseline assumptions. Forecasts reflect documented parameter sets around input cost trajectories and channel penetration curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Spice Coated Casing Market
Spices and Seasonings
Wild Cherry Powder Market
Spices and Seasonings
Seasonings Market
Spices and Seasonings
Glass Spice Jars Market
Spices and Seasonings
Dried Spices Market
Spices and Seasonings
White Pepper Market
Spices and Seasonings
Hot Pot Seasoning Market
Spices and Seasonings
Kosher Salt Market
Spices and Seasonings
Thyme Extract Market
Spices and Seasonings
Cajun Seasoning Market
Spices and Seasonings
Blended Spices Market
Spices and Seasonings
Meat Seasonings Market
Spices and Seasonings
Carthamus Yellow Market
Spices and Seasonings
Mustard Market
Spices and Seasonings
Turmeric Oleoresin Market
Spices and Seasonings
Europe Seasoning and Spices Market