
 Dried Spices Market | 2026-2036
Dried Spices Market Size, Share, and Industry Trends Forecast 2026-2036
Dried Spices Market Analysis
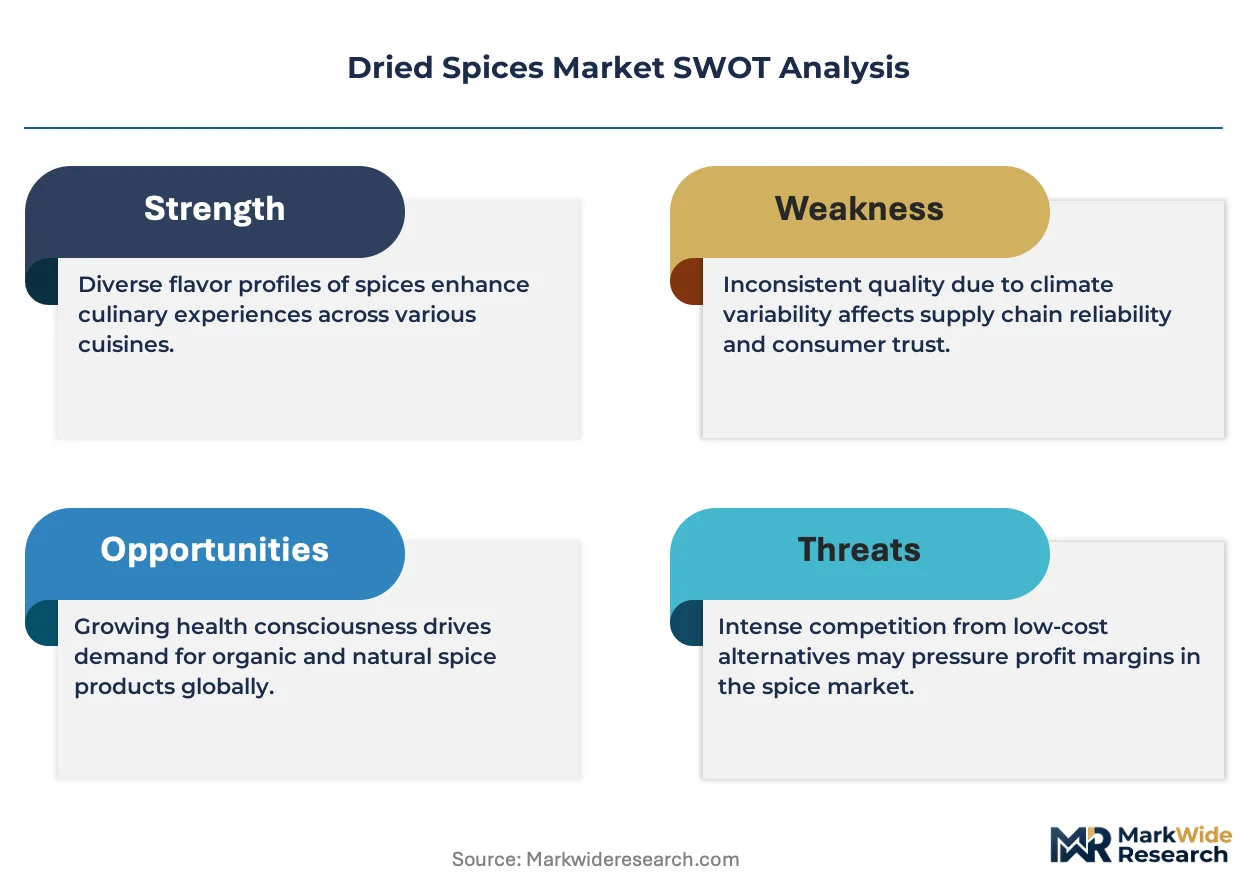
Food processing buyers is unwinding the traditional retail-dominated demand structure for dried spices. McCormick & Company, Inc. leverages its captive sourcing infrastructure across tropical origins to secure consistent supply. Everest Food Products Pvt. Ltd. anchors its position through deep distribution into India's household and food service channels. Sensient Technologies Corporation differentiates via extraction technologies that supply industrial flavor houses.
Dried spices encompass dehydrated plant materials—seeds, fruits, roots, bark, or flowers—processed to moisture levels below 10 percent to inhibit microbial activity and preserve volatile oil content for flavor delivery. The primary commercial purpose spans culinary seasoning, food preservation, natural coloring, and functional ingredient applications across packaged foods and food service formulations. Pepper and paprika command the largest volume positions, while ground and powder forms capture disproportionate margin pools through industrial food processing contracts. Whole spices retain strength in ethnic retail channels and premium food service segments where visual authenticity and extended shelf stability matter.
The US FDA enforces strict mycotoxin and pathogen thresholds for imported spice shipments, while India's FSSAI mandates traceability documentation and adulteration testing that shapes export market access. The EU's EFSA evaluates novel spice extracts and health claims, creating compliance layers for functional ingredient positioning. Stakeholders must monitor evolving pesticide maximum residue limits across destination markets and invest in spectroscopy-based testing infrastructure to sustain trade eligibility.
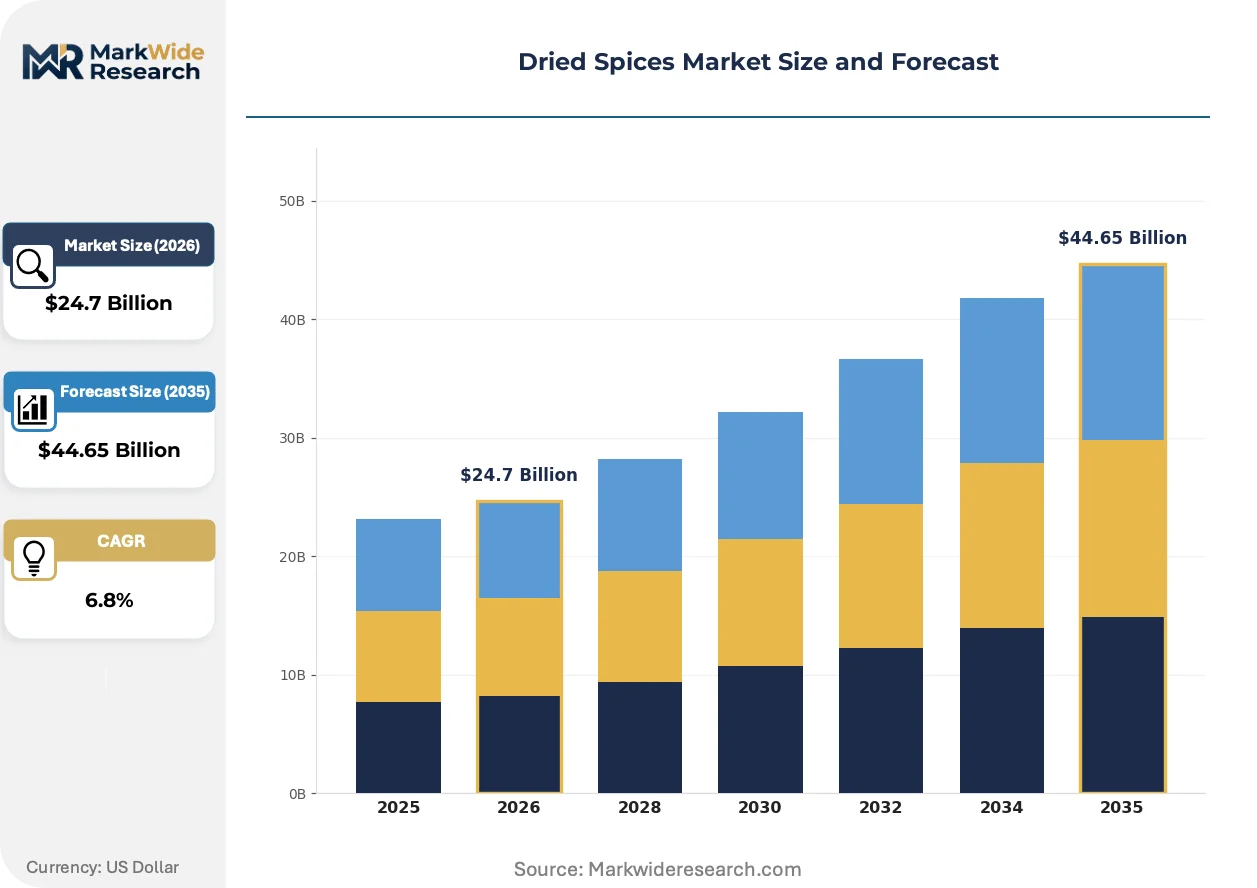
Market Dynamics
Food processing buyers are consolidating procurement around clean-label spice specifications, forcing suppliers to retool extraction and grinding infrastructure toward adulteration-free certification standards.
Growth Catalysts
- FSSAI Traceability Mandates:India's stricter documentation requirements for imported spices are accelerating investment in spectroscopy-based testing infrastructure across export-oriented processing clusters.
- Clean-Label Blends:Industrial food manufacturers are specifying preservative-free spice formulations, pulling demand toward vertically integrated processors with captive organic sourcing.
- Pepper Belt Concentration:Vietnam's Central Highlands region is expanding mechanized drying capacity, lowering moisture variance and securing volume contracts with European flavor houses.
Market Restraints
- Climate Volatility:Irregular monsoon patterns across India's Guntur and Byadgi chili belts are amplifying harvest uncertainty and spot price swings for red pepper derivatives.
- Mycotoxin Thresholds:The US FDA's strict aflatoxin limits for imported shipments create batch rejection risk that compresses margins for small-scale grinders lacking in-house testing labs.
- Synthetic Substitutes:Encapsulated oleoresins and nature-identical flavor compounds are capturing share in cost-sensitive beverage and snack applications.
Strategic Opportunities
- EU Novel Extracts Pathway:EFSA's evolving framework for health claim substantiation creates first-mover advantage for suppliers developing standardized polyphenol extracts from turmeric and ginger.
- Direct-to-Processor Platforms:Digital procurement exchanges linking Vietnamese pepper farmers to European industrial buyers are disintermediating traditional auction houses and capturing 8-12 point margin spreads.
- Carbon-Labelled Supply Chains:Early adoption of ISO 14064-aligned footprint tracking for Indonesian nutmeg and clove shipments is unlocking premium positioning with Nordic retail chains.
Industry Challenges
- Spectroscopy Talent Scarcity:Shortage of technicians trained in NIR and HPLC methods for adulteration detection is delaying certification timelines for mid-tier processors.
- Legacy Equipment Retrofit Costs:Converting traditional sun-drying yards to solar-assisted dehydration tunnels requires capital outlays that strain family-owned operations in Sri Lanka's cinnamon belt.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dried Spices Market |
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $44.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pepper, Oregano, Basil, Paprika Form: Whole, Ground, Flakes, Powder End User: Food Service, Retail, Food Processing, Home Cooking Packaging Type: Bags, Containers, Jars, Pouches |
| Companies Covered | McCormick & Company, Inc., Everest Food Products Pvt. Ltd., Sensient Technologies Corporation, Olam Group Limited, DS Group, Firmenich SA, Bart Ingredients Company Ltd., Frontier Co-op, The Fuchs Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dried Spices Market Emerging Trajectories
Processing technology and procurement specifications are diverging sharply between premium traceable supply and commodity-grade volume trade, creating parallel market tiers with incompatible infrastructure requirements.
Steam-treated spice sterilization is bifurcating the industrial supply base. This non-thermal pathogen reduction method preserves volatile oil integrity better than ethylene oxide fumigation. Large food manufacturers in Germany and the Netherlands are specifying steam-treated pepper and paprika for clean-label product lines. The technology is compressing ethylene oxide's addressable market to price-driven commodity segments while enabling 15-20 point margin premiums for certified steam-treated supply.
REACH-aligned pesticide residue protocols are tightening import requirements for European spice processors. The EU's evolving maximum residue limits for organophosphates and carbamates now exceed Codex standards in several categories. Indian and Vietnamese exporters are responding by shifting acreage toward integrated pest management zones with third-party audit trails, particularly for organic-certified turmeric destined for German retail.
Food service distributors are consolidating SKU portfolios around multi-spice blends with extended stability claims. This specification compression favors suppliers with in-house grinding, blending, and nitrogen-flush packaging capabilities. The shift is most visible in North American contract food service, where broadline distributors are reducing vendor counts from twelve to four per spice category.
Dried Spices Market Segmentation
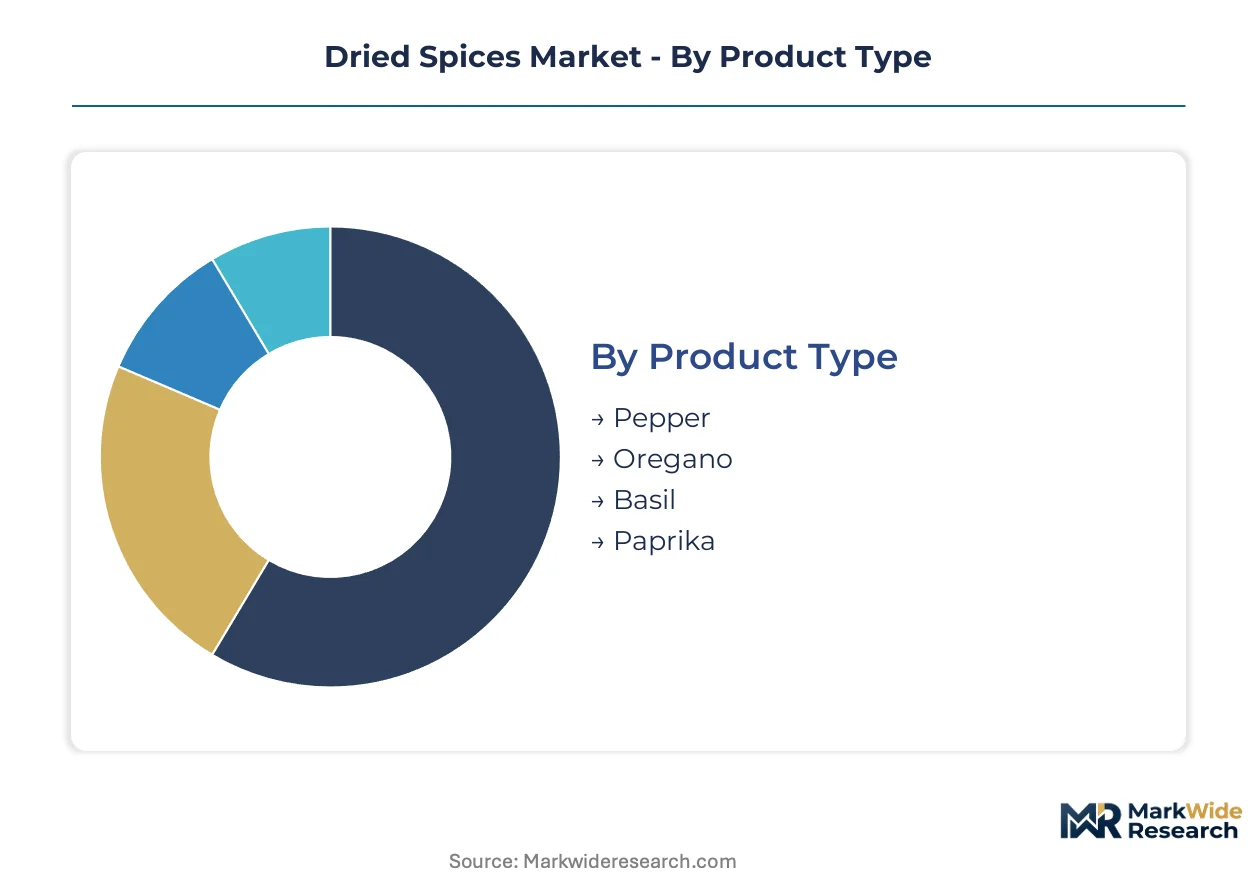
Dried spices fragment across product, form, end user, and packaging dimensions that shape margin capture and infrastructure requirements. Each segment carries distinct substitution pressures from synthetic alternatives and divergent compliance burdens across export markets.
Product Type:
Pepper and paprika face the most intense displacement threat from encapsulated oleoresins and nature-identical compounds in cost-sensitive industrial applications.
- Pepper:Piperine-rich berries dried to 8-12 percent moisture, with black pepper commanding premium positioning in European clean-label formulations. Vietnam's Central Highlands mechanized drying clusters are securing volume contracts with German flavor houses seeking steam-treated sterilization compliance.
- Paprika:Capsicum annuum varieties processed for color value (ASTA 120-180) and heat profiles ranging from sweet to hot. Spanish Murcia and Hungarian Szeged processors are investing in spectroscopy labs to meet US FDA aflatoxin thresholds for industrial food service contracts.
- Oregano:Origanum vulgare with carvacrol and thymol content driving antimicrobial functional claims. Greek and Turkish mountain cultivation zones supply Mediterranean food service channels.
- Basil:Ocimum basilicum with methyl chavicol and linalool volatiles preserved through freeze-drying for premium retail. Egyptian and Israeli greenhouse operations serve European organic retail chains.
Pepper retains volume leadership; paprika holds the steepest expansion curve through industrial colorant demand.
Form:
Cost tier stratification runs deepest here, with powder and ground forms capturing disproportionate margin pools through food processing contracts while whole spices serve premium positioning.
- Whole:Intact seeds, pods, or bark pieces retaining volatile oil integrity through extended storage. India's ethnic retail channels and Gulf food service segments specify whole cardamom and cinnamon for visual authenticity verification.
- Ground:Coarse to fine particle size distributions (US mesh 20-60) specified for sauce and seasoning manufacturers. Indonesian nutmeg processors are retrofitting hammer mills to REACH-aligned pesticide residue protocols for EU access.
- Flakes:Crushed leaf materials with larger surface area than powder for controlled release in slow-cooking applications. Mediterranean oregano flakes serve North American pizza chain specifications.
- Powder:Fine grind (US mesh 80+) maximizing surface area for rapid flavor dispersion in dry mix applications. Turmeric powder from India's Erode and Nizamabad clusters faces FSSAI adulteration testing mandates for curcumin standardization.
Ground forms dominate industrial procurement volumes; powder commands the widest price spreads across certification tiers.
End User:
Application concentration determines specification intensity, with food processing buyers driving the most stringent clean-label and traceability requirements.
- Food Processing:Industrial manufacturers of snacks, sauces, and ready meals specifying preservative-free blends with batch-level documentation. McCormick's captive sourcing infrastructure supplies this segment with steam-treated pepper meeting ethylene oxide bans.
- Food Service:Restaurant chains and contract caterers consolidating SKU portfolios around multi-spice blends with nitrogen-flush stability claims. North American broadline distributors are reducing vendor counts per category from twelve to four.
- Retail:Supermarket and specialty store channels emphasizing origin labeling and organic certification for household purchasers. Nordic retail chains are piloting carbon-labeled Indonesian clove shipments.
- Home Cooking:Direct-to-consumer sales through ethnic grocers and e-commerce platforms serving diaspora communities. India's Everest Food Products anchors this segment through deep distribution into household channels.
Food processing captures the highest specification premiums; food service is consolidating procurement fastest.
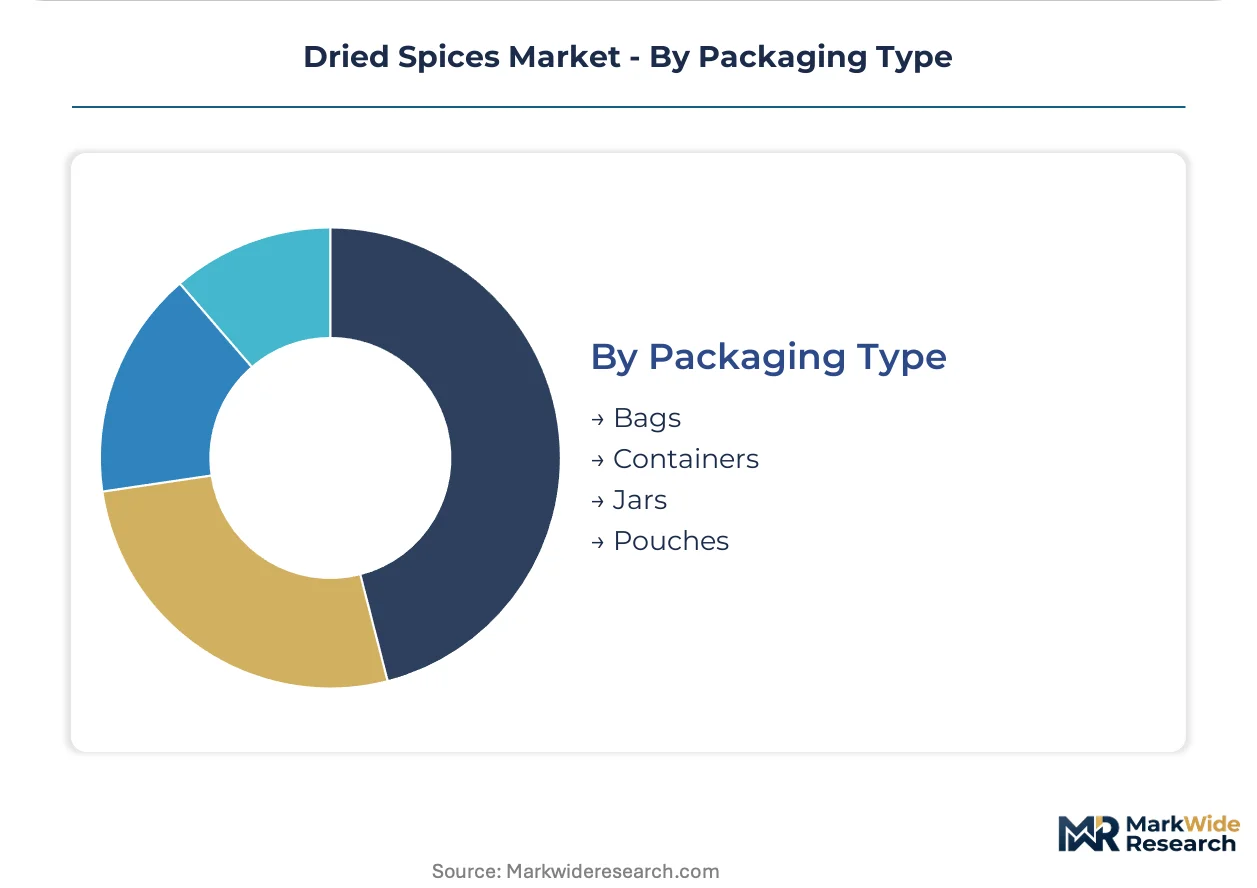
Packaging Type:
Customer type and channel economics dictate packaging selection, with industrial buyers favoring bulk formats and retail channels demanding shelf-ready presentation.
- Bags:Multi-layer laminated structures with oxygen barrier properties for 10-25 kg industrial shipments. Vietnamese pepper exporters are adopting vacuum-sealed bulk bags for European flavor house contracts.
- Containers:Rigid plastic or metal formats with resealable closures for food service high-turnover environments. North American contract food service distributors specify stackable containers for kitchen efficiency.
- Jars:Glass or PET containers with tamper-evident seals for retail premium positioning. German organic turmeric brands utilize amber glass to preserve curcumin photo-stability.
- Pouches:Flexible stand-up or flat formats with zipper closures for retail convenience and portion control. Indian retail chains are expanding private-label pouch offerings for chili powder and garam masala blends.
Bags retain industrial volume dominance; pouches are expanding most quickly in emerging market retail modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure underwrites Europe's gateway role for steam-treated pepper shipments from Vietnam's Central Highlands. India's Jawaharlal Nehru Port Trust anchors subcontinent export flows with dedicated spice handling terminals and FSSAI-certified inspection facilities.
United States
Food manufacturers in Chicago and New Jersey specify steam-treated sterilization for clean-label product lines. The FDA enforces strict aflatoxin thresholds that compress margins for small-scale importers lacking in-house testing labs. McCormick's captive sourcing infrastructure supplies industrial buyers from Baltimore processing facilities.
Germany
Flavor houses in Hamburg and Frankfurt consolidate procurement around REACH-aligned pesticide residue protocols. EFSA's evolving framework for health claim substantiation creates compliance layers for turmeric extract suppliers. The Port of Hamburg's dedicated spice terminals handle bulk pepper shipments from Vietnamese mechanized drying clusters.
India
FSSAI traceability mandates accelerate spectroscopy investment across Guntur and Byadgi chili processing belts. Stricter adulteration testing requirements shape export market access for Erode and Nizamabad turmeric clusters. Everest Food Products anchors domestic distribution through deep household channel penetration.
Vietnam
Mechanized drying capacity expansion in the Central Highlands lowers moisture variance for European flavor house contracts. Digital procurement exchanges linking pepper farmers to German industrial buyers disintermediate traditional auction houses. The Da Nang port corridor handles nitrogen-flush bulk bag shipments for clean-label specifications.
Indonesia
ISO 14064-aligned carbon footprint tracking for nutmeg and clove shipments unlocks premium positioning with Nordic retail chains. Integrated pest management zones with third-party audit trails serve organic-certified turmeric demand. Sulawesi and Maluku processing clusters retrofit sun-drying yards to solar-assisted dehydration tunnels.
Dried Spices Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers and sourcing infrastructure depth. The vendor base stratifies between vertically integrated multinationals with captive tropical origins and regional grinders serving ethnic retail channels. Three archetypes dominate: scale-driven processors with sterilization capabilities, specialty blenders with deep distribution networks, and extraction technology suppliers serving industrial flavor houses. Competitive moves concentrate on backward integration into mechanized drying clusters and spectroscopy-based testing infrastructure deployment.
Within the scale-driven tier, McCormick & Company, Inc. and Olam Group Limited exemplify vertically integrated sourcing models. Everest Food Products Pvt. Ltd. anchors the regional specialist archetype through distribution depth into India's household channels. Sensient Technologies Corporation occupies a position among extraction technology suppliers that differentiate via industrial flavor house relationships.
| Leading Market Players |
|---|
| McCormick & Company, Inc. |
| Everest Food Products Pvt. Ltd. |
| Sensient Technologies Corporation |
| Olam Group Limited |
| DS Group |
| Firmenich SA |
| Bart Ingredients Company Ltd. |
| Frontier Co-op |
| The Fuchs Group |
| Others |
Supply Flow & Price Mechanics
Encapsulated oleoresins displacing commodity-grade paprika in cost-sensitive beverage applications simultaneously redraws procurement geography toward South Asian extraction clusters and compresses pricing premiums for non-certified Spanish and Hungarian colorant suppliers. This substitution dynamic forces traditional paprika processors to absorb spectroscopy testing costs or retreat to premium food service channels where visual authenticity commands residual value.
Pricing Analysis
Volume-discount tiering separates steam-treated sterilization-compliant pepper from ethylene oxide-fumigated commodity supply, with certification grade and volume scale as the primary differentiation drivers. Pricing pressure stems from REACH-aligned pesticide residue protocols that disqualify small-scale Indian grinders lacking in-house testing infrastructure. Food processing buyers exhibit the least price sensitivity due to clean-label specification lock-in, while cost-sensitive snack manufacturers drive aggressive spot-market bargaining for non-certified supply.
Supply Chain Analysis
Inventory lead times stretch across monsoon-dependent harvest cycles in India's Guntur and Byadgi chili belts, with raw material sourcing drawing from Vietnamese pepper orchards, Indonesian nutmeg plantations, and Sri Lankan cinnamon bark. Supply chain risk centers on single-source vulnerability for organic-certified turmeric from Erode and Nizamabad clusters facing FSSAI adulteration testing bottlenecks. Distribution runs through Rotterdam's cold chain gateway for European flavor houses and Jawaharlal Nehru Port Trust's dedicated spice terminals for subcontinent exports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label regulatory inflections across FDA, FSSAI, and EFSA jurisdictions are accelerating market disruption, with spectroscopy-based certification emerging as the decisive capability differentiator between premium and commodity supply tiers.
For Market Incumbents: Secure captive sourcing infrastructure across Vietnam's Central Highlands mechanized drying clusters and India's chili processing belts to defend against digital procurement exchanges disintermediating traditional auction houses. Invest in NIR and HPLC testing laboratories to preempt batch rejection risk from tightening mycotoxin thresholds. For New Entrants and Emerging Players: Organic certification fast-tracks unlock premium positioning with Nordic retail chains piloting carbon-labeled Indonesian clove shipments. Target carbon-footprint-tracked supply chains as the most penetrable white space, leveraging ISO 14064-aligned documentation to bypass established commodity channels. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated processors with sterilization capabilities over fragmented regional grinders. Long-term viability hinges on backward integration into mechanized drying infrastructure and spectroscopy deployment. Watch EFSA health claim substantiation rulings on turmeric polyphenol extracts as the signal for functional ingredient valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mechanized Drying | Vietnam's Central Highlands clusters secure volume contracts with German flavor houses through moisture variance reduction. |
| Spectroscopy Testing Infrastructure Deployment | NIR and HPLC capabilities preempt FDA aflatoxin batch rejections for Indian paprika exporters. |
| Carbon-Labeling Certification Program | ISO 14064-aligned footprint tracking unlocks premium positioning with Nordic retail chains for Indonesian nutmeg. |
| Direct-to-Processor Digital Platform Launch | Farmer-to-flavor-house exchanges capture 8-12 point margin spreads by disintermediating traditional auction houses. |
| Steam-Treated Sterilization Scale-Up | Non-thermal pathogen reduction preserves volatile oil integrity for clean-label product lines in German and Dutch markets. |
Methodological Framework
Desk research of customs trade databases, FSSAI regulatory filings, and EFSA health claim submissions preceded structured interviews with spice processing plant managers, European flavor house procurement directors, and Indian export cluster compliance officers. Primary fieldwork across Vietnam's Central Highlands, India's Guntur chili belt, and Indonesia's Maluku islands validated secondary data on mechanized drying capacity and spectroscopy infrastructure deployment. Bottom-up volume modeling triangulated against top-down trade flow analysis.
Variance decomposition across product type, form specification, end-user application, and packaging format shaped the analytical framework over the projection horizon. CAGRs derived from segment-level demand elasticity modeling incorporated climate volatility indices for monsoon-dependent harvests and regulatory compliance cost trajectories for adulteration testing mandates. Forecast inputs included FSSAI traceability mandate implementation timelines and REACH-aligned pesticide residue limit evolution.
Decision-makers should treat outputs as directional under assumptions of sustained clean-label specification intensity and stable trade policy environments; material deviation in climate patterns or regulatory enforcement would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Middle East and Africa Botanical Extract Market
Spices and Seasonings
Boswellia Extract Market
Spices and Seasonings
Spice Grinders Market
Spices and Seasonings
Spices and Seasonings Market
Spices and Seasonings
Kosher Salt Market
Spices and Seasonings
Myrrh Gum Market
Spices and Seasonings
Asia-Pacific Seasoning and Spices Market
Spices and Seasonings
Nutmeg Oil Market
Spices and Seasonings
Espresso Salt Market
Spices and Seasonings
Paprika Color Market
Spices and Seasonings
US Spice and Seasonings Market
Spices and Seasonings
Asia-Pacific Spice and Herb Extracts Market
Spices and Seasonings
Smoked Black Pepper Market
Spices and Seasonings
Achiote Powder Market
Spices and Seasonings
Dill Oil Market
Spices and Seasonings
Garlic Salt Market