
 Spices and Seasonings Market | 2026-2036
Spices and Seasonings Market Size, Share, and Industry Trends Forecast 2026-2036
Spices and Seasonings Market Intelligence
The market's dependency on the food processing vertical for volume growth is hardening as household consumer purchasing shifts toward value-added products. McCormick & Company, Inc. leverages its extensive global supply chain to service multinational food manufacturers. Olam International specializes in sourcing and processing raw agricultural commodities, including bulk spices for industrial use. Meanwhile, Kerry Group Plc differentiates through its integrated taste and nutrition solutions for industrial clients.
Spices and seasonings are plant-derived substances used to impart flavor, aroma, and color to food and beverages. The quality is often determined by factors like volatile oil content, which is preserved through controlled grinding and extraction processes. Ground spices continue to represent the largest product category by volume, serving the mass market. However, high-margin growth is found in extracts and herb blends, driven by their application in the nutraceuticals and clean-label food processing sectors.
Regulatory frameworks established by bodies like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) govern allowable pesticide residues and allergen labeling. In countries like India, the FSSAI sets stringent standards against adulteration, impacting import and export requirements. Navigating these disparate international standards is a primary challenge for supply chain managers. Consequently, investment in blockchain-based traceability systems is becoming a critical decision point for maintaining market access.
Market Dynamics
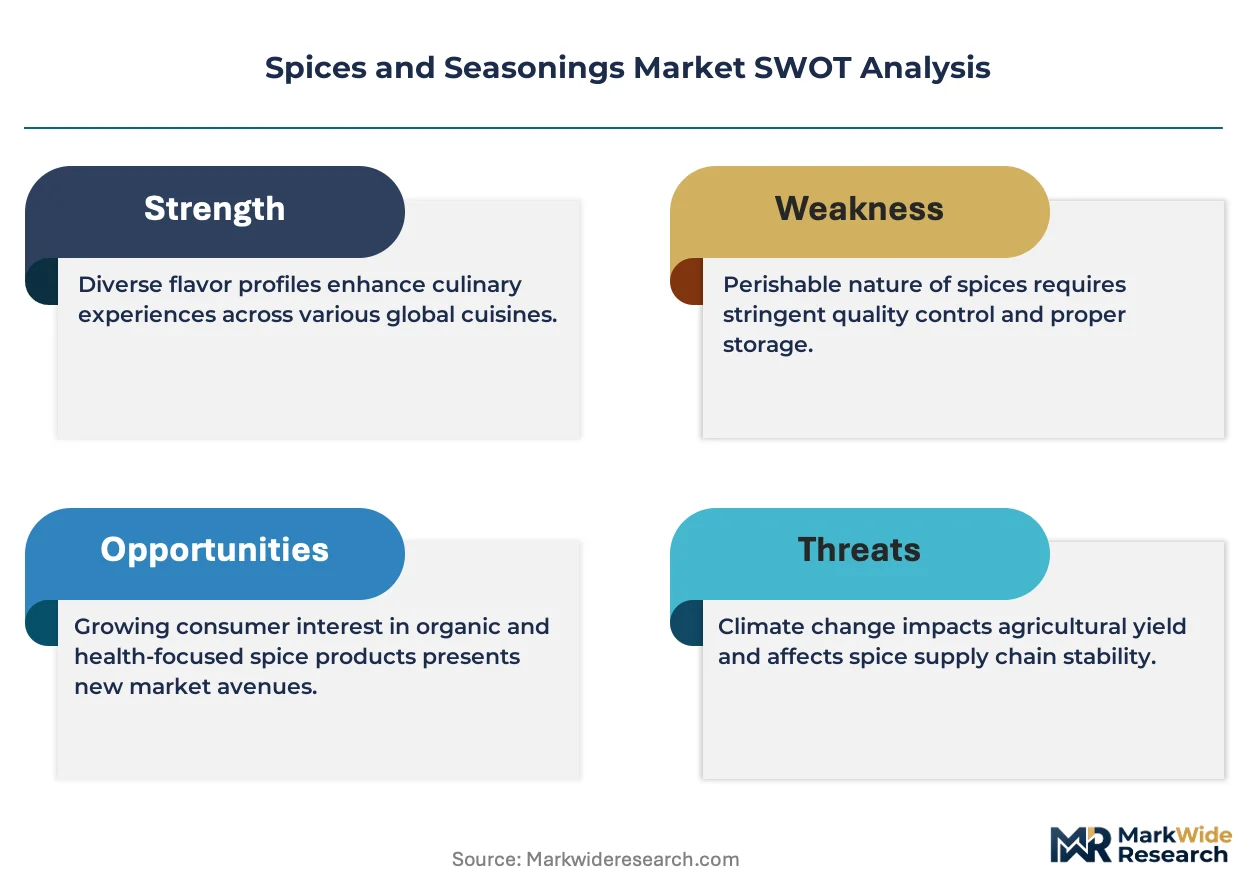
The market's central dynamic is the growing tension between the commoditized, volume-driven segment serving industrial food processors and the high-margin, value-added segment demanding traceable, clean-label ingredients. This bifurcation is forcing a strategic re-evaluation of supply chain architecture and quality control investments across the industry.
Growth Catalysts
- Food Safety Modernization:The FDA's Food Safety Modernization Act (FSMA) and similar EFSA mandates compel food manufacturers to demand greater traceability from spice suppliers, boosting investment in certified and controlled supply chains.
- Nutraceutical Applications:Demand from the nutraceutical industry for standardized spice and herb extracts with specific active compound levels, such as curcumin from turmeric, creates a high-margin growth vector.
- Premiumization in Europe:Consumer preference in key markets like Germany and France for single-origin spices, such as Tellicherry peppercorns or Ceylon cinnamon, supports premium pricing and product differentiation.
Market Restraints
- Input Cost Volatility:Prices for agricultural commodities are subject to extreme volatility due to climate events like droughts or monsoons in concentrated growing regions like India, Vietnam, and Indonesia.
- Geographic Supply Concentration:Over-reliance on a few countries for specific spices, such as vanilla from Madagascar or saffron from Iran, creates significant supply chain fragility and price instability.
- Regulatory Fragmentation:Navigating disparate international standards for pesticide residues and contaminants, set by bodies like the FDA, EFSA, and FSSAI, increases compliance costs and trade friction.
Strategic Opportunities
- Blockchain for Traceability:Implementing blockchain-based systems offers an opportunity to provide immutable proof of origin and quality, commanding premium prices and securing access to discerning markets.
- Plant-Based Flavoring:The expansion of the plant-based meat alternative sector presents a significant opportunity for developing sophisticated spice and herb blends that mimic traditional meat flavors.
- Ethnic Blend Mainstreaming:Introducing authentic, pre-packaged ethnic spice blends for cuisines like North African or Southeast Asian into mainstream Western retail channels taps into evolving consumer tastes.
Industry Challenges
- Pesticide Residue Compliance:A primary operational challenge is consistently meeting the varied and evolving Maximum Residue Limits (MRLs) for pesticides set by different import markets, risking shipment rejections.
- Identity Preservation Logistics:Maintaining the integrity of certified organic or single-origin products requires segregated storage and processing facilities, adding significant complexity and cost to the supply chain.
- Adulteration and Fraud:The persistent threat of economic adulteration, such as adding fillers or synthetic dyes to ground spices, necessitates continuous and costly investment in advanced testing and monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spices and Seasonings Market |
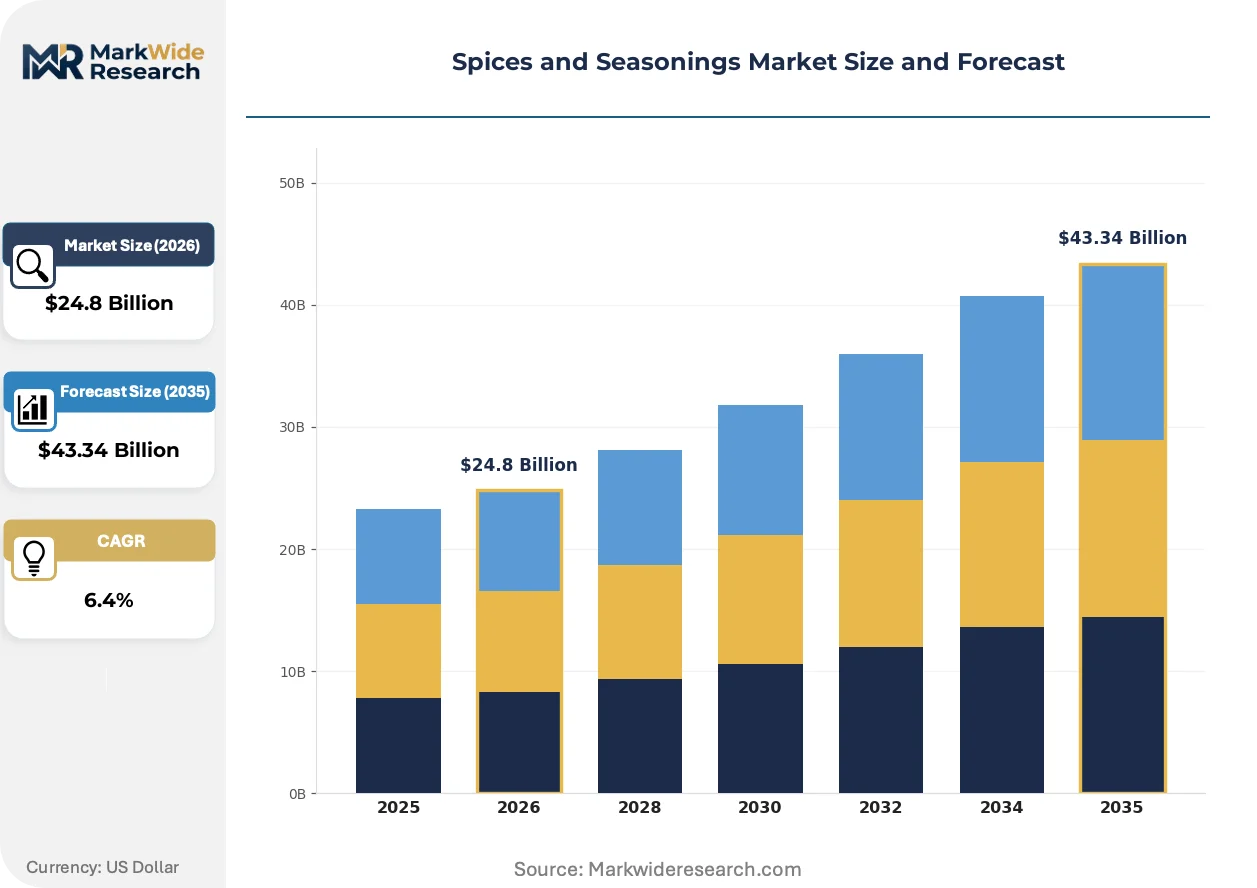
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Spices, Ground Spices, Mixed Seasonings, Herb Blends, Extracts, Salts Application: Food Processing, Culinary Use, Beverage Flavoring, Nutraceuticals, Cosmetic Industry, Traditional Medicine End User: Restaurants, Food Manufacturers, Household Consumers, Catering Services, Food Retailers, Spice Traders Packaging Type: Plastic Pouches, Glass Jars, Metal Tins, Paper Packets, Bulk Bags, Vacuum Sealed Packs |
| Companies Covered | McCormick & Company, Inc., Olam International, Kerry Group Plc, Ajinomoto Co., Inc., Associated British Foods Plc, Sensient Technologies Corporation, The Kraft Heinz Company, Döhler Group, Cargill Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spices and Seasonings Market Strategic Shifts & Innovations
Technological advancements in authentication and a consumer-led push for transparency are reshaping product development and sourcing strategies. This convergence is elevating the importance of verifiable claims related to origin, purity, and ethical production, forcing suppliers to adapt their operational models.
Advanced analytical techniques are becoming critical for product verification. Technologies like DNA barcoding and stable isotope ratio analysis provide definitive proof of a spice's species and geographic origin, combating fraud. Food manufacturers seeking to substantiate premium claims for products like single-origin pepper or vanilla are driving adoption. This technology is consolidating market access for suppliers who can provide scientifically validated, traceable ingredients.
Regulatory bodies are increasing their focus on contaminants and undeclared allergens. For example, the European Food Safety Authority (EFSA) has tightened regulations on ethylene oxide, a sterilizing agent, and requires stricter allergen labeling for ingredients like mustard and celery. This forces processors to re-evaluate their sterilization methods and supply chain documentation. The prepared foods and ready-to-eat meal segments are most affected, needing to reformulate products or secure new suppliers.
A notable behavioral shift is the move towards direct-to-consumer (DTC) models that emphasize storytelling and origin. Small-batch and single-estate spice companies are using online platforms to connect directly with consumers, bypassing traditional grocery retail gatekeepers. This trend, most visible in North American and UK markets, allows new entrants to build brand loyalty around authenticity and freshness, challenging the volume-based model of established incumbents.
Spices and Seasonings Market Segmentation
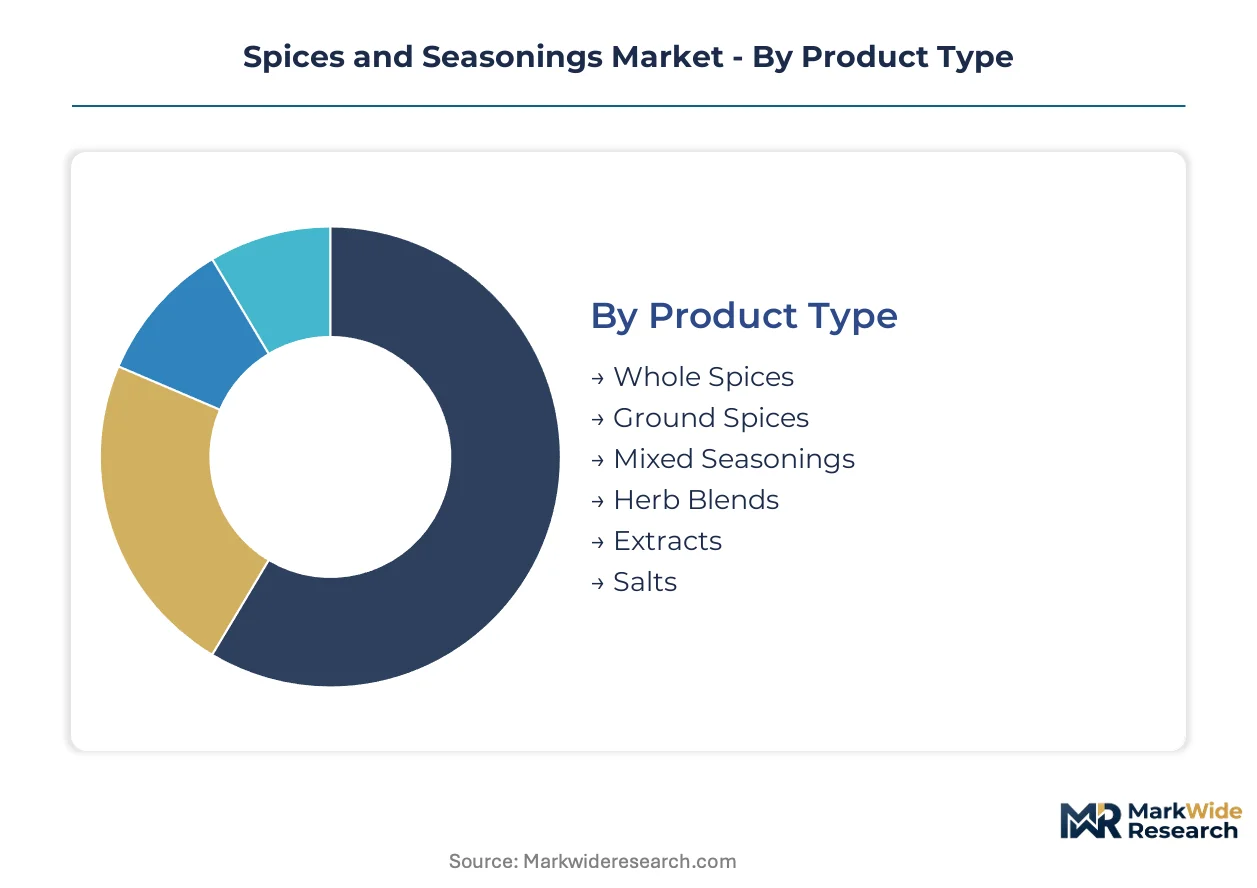
The Spices and Seasonings Market exhibits distinct segmentation, reflecting the diverse requirements of industrial processors and discerning consumers. Understanding these categories is essential for identifying market opportunities and navigating the complex supply chain dynamics. Each segment responds to specific demand drivers, from cost-efficiency to premium quality.
Product Type:
The market for product types illustrates a clear bifurcation between volume-driven commodities and high-value, specialized offerings.
- Ground Spices:These are dried spices that have been milled into a fine powder, offering convenience and consistent flavor dispersion in food matrices. Demand from the food processing sector for cost-effective, bulk ingredients drives significant volume for ground spices.
- Extracts:Concentrated forms of spices and herbs, obtained through various extraction methods to isolate specific flavor compounds or active ingredients. Nutraceutical applications and the beverage industry increasingly demand standardized extracts for their potency and clean-label appeal.
- Whole Spices:Unprocessed, dried plant parts, such as seeds, fruits, roots, or bark, retaining their full aromatic profile until grinding. Culinary use in restaurants and by household consumers values whole spices for freshness and longer shelf life.
- Mixed Seasonings:Pre-blended combinations of spices, herbs, and other flavorings, designed for specific cuisines or dishes. Convenience-seeking consumers and food service providers utilize mixed seasonings for ease of application.
- Herb Blends:Mixtures primarily composed of dried leafy herbs, often combined to create distinct flavor profiles for various culinary applications. The clean-label trend and home cooking drive demand for versatile herb blends.
- Salts:Specialized salts infused with spices or herbs, or unique mineral salts, used to enhance flavor and texture in prepared foods. Gourmet culinary applications and premium food manufacturers incorporate flavored salts for differentiation.
Today's leader: Ground Spices. Tomorrow's challenger: Extracts.
Application:
Application segments highlight the varied end-use needs, from large-scale industrial integration to specialized therapeutic uses.
- Food Processing:This segment involves the large-scale incorporation of spices and seasonings into manufactured food products like snacks, ready meals, and processed meats. Food manufacturers require consistent quality and bulk supply, adhering to strict regulatory standards for safety and labeling.
- Nutraceuticals:The use of spice and herb extracts for their health benefits, often standardized for specific active compounds, such as curcumin or piperine. Pharmaceutical and supplement companies drive demand for high-purity, traceable ingredients with scientifically backed claims.
- Culinary Use:Direct application of spices and seasonings by chefs in restaurants, catering services, and household kitchens to flavor dishes. This segment values product freshness, diverse origins, and unique flavor profiles.
- Beverage Flavoring:Spices and herbs are used to impart flavor to drinks, including teas, spirits, functional beverages, and non-alcoholic concoctions. Innovation in craft beverages and natural flavor trends are expanding this application.
- Cosmetic Industry:Spices and extracts are incorporated into personal care products for their aromatic properties, antioxidant content, or perceived skin benefits. Natural ingredient formulations in skincare and fragrances utilize these components.
- Traditional Medicine:Application of spices and herbs in traditional healing practices and herbal remedies, often based on ancient medicinal systems. This niche segment relies on specific botanical varieties and preparation methods.
Food Processing continues to hold the largest share, while Nutraceuticals are expanding most quickly.
End User:
The end-user landscape reflects a spectrum from industrial-scale procurement to individual consumer purchasing behaviors.
- Food Manufacturers:Large-scale industrial entities that integrate spices and seasonings as ingredients into their processed food products. These users prioritize consistent quality, bulk pricing, and reliable supply chain logistics.
- Household Consumers:Individual purchasers who buy spices and seasonings for home cooking and personal use. This segment is driven by convenience, brand reputation, and a growing interest in diverse international cuisines.
- Restaurants:Professional culinary establishments that use spices and seasonings to prepare meals for diners. Restaurants demand high-quality, often specialized, ingredients to create unique and authentic flavors.
- Food Retailers:Supermarkets, grocery stores, and specialty food shops that sell packaged spices and seasonings directly to household consumers. Retailers focus on product diversity, shelf appeal, and competitive pricing.
- Catering Services:Businesses providing food for events and functions, requiring spices and seasonings for large-volume meal preparation. Consistency and cost-effectiveness are important considerations for catering operations.
- Spice Traders:Intermediaries involved in the wholesale buying and selling of raw or semi-processed spices to various other end users. These traders manage global sourcing and distribution networks.
Food Manufacturers represent the largest volume segment; Household Consumers are gaining share fastest.
Packaging Type:
Packaging solutions vary significantly, influenced by product type, end-user requirements, and sustainability considerations.
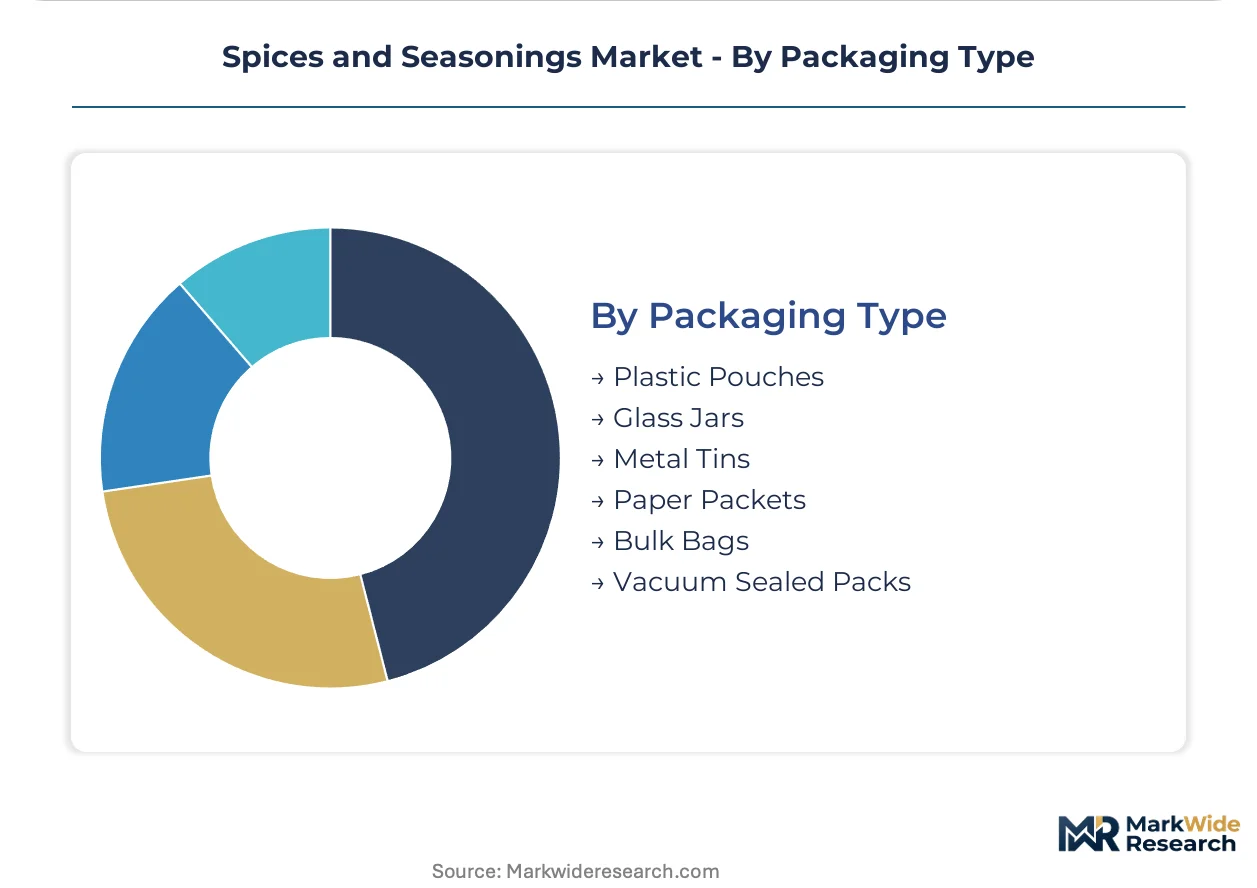
- Plastic Pouches:Flexible, lightweight packaging solutions offering cost-effectiveness and good barrier properties against moisture and oxygen. Mass-market ground spices and mixed seasonings often utilize plastic pouches due to their affordability and convenience.
- Bulk Bags:Large-capacity packaging, typically made from woven polypropylene, designed for transporting and storing significant quantities of raw or processed spices. Industrial food processors and spice traders rely on bulk bags for efficient, large-scale ingredient handling.
- Glass Jars:Rigid, transparent containers providing excellent product visibility and protection, often associated with premium products. Specialty spices and herb blends for household consumers frequently use glass jars, emphasizing aesthetic appeal and reusability.
- Metal Tins:Durable and opaque containers offering superior protection from light, moisture, and air, preserving product freshness over longer periods. High-value spices and traditional blends, particularly in gift sets, are often presented in metal tins.
- Paper Packets:Economical and environmentally friendly packaging, typically used for smaller quantities or single-use portions of spices and seasonings. Budget-conscious consumers and certain ethnic markets favor paper packets for their low cost.
- Vacuum Sealed Packs:Packaging where air is removed to extend shelf life and preserve the aroma and flavor of sensitive spices. Premium whole spices and extracts, which degrade quickly with oxygen exposure, benefit from vacuum sealing.
Plastic Pouches dominate the market today; Vacuum Sealed Packs show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence across major markets drives a strategic re-evaluation of production locations, as suppliers seek to balance compliance costs with market access. This dynamic creates opportunities for regions with robust quality control infrastructure to attract investment, while others face challenges in meeting stringent import standards.
India
Household consumption and food processing demand drive spice volumes across India. The FSSAI imposes strict standards against adulteration, influencing both domestic production and export protocols. Major processing hubs in Kerala and Gujarat focus on advanced grinding and extraction facilities for global markets.
United States
Demand for clean-label ingredients and nutraceutical applications propels growth in the United States. The FDA's Food Safety Modernization Act (FSMA) mandates enhanced traceability from spice suppliers, boosting investment in certified supply chains. California and the Midwest house significant food manufacturing clusters requiring high-quality, compliant ingredients.
Germany
European consumer preference for premium, single-origin spices and herb blends drives the German market. EFSA regulations on contaminants like ethylene oxide necessitate rigorous testing and supply chain documentation. Hamburg's port acts as a central European hub for spice imports, with specialized processors located nearby.
Vietnam
Vietnam's position as a major producer of black pepper and other spices supports its export-oriented industry. The Vietnamese government actively promotes sustainable farming practices to meet international food safety standards. Processing zones around Ho Chi Minh City specialize in bulk spice preparation for industrial food manufacturers.
France
French demand concentrates on high-quality, authentic ingredients for culinary use and sophisticated food products. Stringent EU allergen labeling rules influence ingredient sourcing for French food manufacturers. Paris and Lyon feature established culinary and food innovation centers that prioritize traceable and ethically sourced spices.
Spices and Seasonings Market Key Industry Players
Strategic partnerships and vertical integration dominate the current landscape, as companies seek to secure consistent supply and meet escalating quality demands. The market structure exhibits a tiered approach, ranging from large-scale commodity traders to specialized providers of taste and nutrition solutions. Major competitive moves include supply chain consolidation and portfolio diversification into higher-margin extracts.
Commodity-focused entities like Olam International exemplify the large-scale sourcing and processing segment, providing bulk ingredients to industrial clients. McCormick & Company, Inc. represents the global brand leader, leveraging its extensive supply chain to serve both household consumers and multinational food manufacturers. Kerry Group Plc occupies a position within integrated taste and nutrition solutions, offering complex ingredient systems to industrial customers.
| Leading Market Players |
|---|
| McCormick & Company, Inc. |
| Olam International |
| Kerry Group Plc |
| Ajinomoto Co., Inc. |
| Associated British Foods Plc |
| Sensient Technologies Corporation |
| The Kraft Heinz Company |
| Döhler Group |
| Cargill Incorporated |
| Others |
Cost & Logistics Intelligence
Food manufacturers, as the largest volume buyers, often procure spices through long-term contract-based pricing. This model provides cost stability amidst agricultural commodity volatility for industrial clients.
Pricing Analysis
Distributor margins for bulk spices are often thin, driven by high volume and competitive tenders. The dominant pricing structure is a hybrid of commodity spot pricing for raw materials and long-term contracts for processed ingredients. Price differentiation stems from certification levels, such as organic or fair trade, and the volume scale of the order. Pricing softness reflects intense competition among suppliers for large industrial contracts, while household consumers are generally less price-sensitive for premium single-origin products.
Supply Chain Analysis
Domestic content mandates, particularly in major importing regions, reshape sourcing strategies for spice suppliers. Geographic supply concentrates in India, Vietnam, and Indonesia for many bulk spices, relying heavily on raw agricultural commodities like peppercorns, turmeric, and cinnamon. Single-source vulnerability for specific high-value spices, such as vanilla from Madagascar, poses a significant supply chain risk. Downstream distribution primarily involves bulk shipments to industrial food processors and packaged goods for retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Spices and Seasonings market acts as a regulatory compounder, with the FDA's Food Safety Modernization Act driving demand for enhanced traceability systems. This regulatory push elevates quality control investments across the supply chain.
For Market Incumbents: Deploy advanced analytical capabilities to verify product authenticity and origin. This defends against margin pressure from commoditization and the threat of adulteration. Incumbents should also deepen upstream control over key raw material sourcing in concentrated geographies like India, mitigating input cost volatility. Investment in blockchain-based traceability platforms strengthens market access for discerning clients.
For New Entrants and Emerging Players: The price-point gap between premium single-origin products and mass-market ground spices offers entry points. Target the nutraceuticals application segment with standardized extracts, leveraging their high-margin potential and demand for specific active compounds. Developing authentic, pre-packaged ethnic spice blends for Western retail channels represents a penetrable white space. A direct-to-consumer model emphasizing storytelling and verified origin can build brand loyalty.
For Investors and Strategic Acquirers: Multinational food and beverage conglomerates are the most active acquirers in this space, seeking to secure high-quality ingredient supply. The market offers long-term viability over the next decade, driven by evolving consumer preferences and regulatory mandates. Target acquisition archetypes include specialized extract producers with proprietary technologies or regional suppliers with certified, traceable supply chains. The signal to watch is the increasing M&A activity around plant-based flavoring solution providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Blockchain Traceability | Blockchain technology provides immutable proof of origin, enhancing compliance with FDA and EFSA regulations for suppliers. |
| Develop Plant-Based Flavor Blends | Sophisticated spice blends are essential for mimicking traditional meat flavors in the expanding plant-based alternative sector. |
| Expand Nutraceutical Extract Portfolio | Standardized spice extracts with active compounds address high-margin demand from the pharmaceutical and supplement industries. |
| Secure Single-Origin Sourcing Contracts | Direct contracts for premium single-origin spices, like Tellicherry peppercorns, meet discerning consumer preferences in European markets. |
| Optimize Sterilization Technologies | Adopting non-ethylene oxide sterilization methods ensures compliance with tightening EFSA regulations and maintains product integrity. |
Research Approach
Direct dialogue with spice processors, food manufacturers, ingredient procurement managers, and flavor scientists formed the primary research backbone. This qualitative input was rigorously validated through extensive secondary research, including trade association reports, customs data, and company financial filings. The analysis employed both bottom-up and top-down triangulation to ensure robust market sizing and forecasting.
The quantitative model generated comprehensive volume and value forecasts across the analysis window. Segmentation dimensions included product type, application, end-user, packaging type, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical trends and market drivers. Key forecast inputs included raw material price volatility and evolving food safety mandates from bodies like the FDA and EFSA.
The model assumes a particular technology adoption path; alternative pathways for blockchain traceability or advanced analytical authentication would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and agricultural output, but geopolitical events or extreme climate patterns could revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Middle East and Africa Ashwagandha Market
Spices and Seasonings
Saffron Market
Spices and Seasonings
Seasonings Market
Spices and Seasonings
Oregano Seasoning Market
Spices and Seasonings
Turmeric Market
Spices and Seasonings
White Pepper Market
Spices and Seasonings
Peppermint Extract Market
Spices and Seasonings
Spice Grinders Market
Spices and Seasonings
Glass Spice Jars Market
Spices and Seasonings
Spices Market
Spices and Seasonings
Tamarind Extract Market
Spices and Seasonings
Cardamom Market
Spices and Seasonings
Gourmet Seaweed Seasoning Market
Spices and Seasonings
US Gourmet Salt Market
Spices and Seasonings
Thyme Extract Market
Spices and Seasonings
Onion Salt Market