
 Alkyl Polyglucoside (APG) Surfactant Market | 2026-2036
Alkyl Polyglucoside (APG) Surfactant Market Size, Share, and Industry Trends Forecast 2026-2036
Alkyl Polyglucoside (APG) Surfactant Market Outlook
Buyer concentration in European personal care is pivoting as multinational cosmetics houses consolidate surfactant procurement around certified green suppliers. BASF SE leverages its Ludwigshafen integrated glucose-fatty alcohol platform to sustain volume leadership in cosmetic-grade APG. Evonik Industries anchors specialty alkyl polyglucoside output for high-foam personal care applications. Kao Corporation competes through Asian manufacturing scale and food-grade certification breadth.
Alkyl polyglucoside surfactants are nonionic biosurfactants synthesized from renewable fatty alcohols and glucose via Fischer glycosidation, typically exhibiting HLB values between 13 and 15 and critical micelle concentrations ranging from 0.02 to 0.1 g/L depending on alkyl chain length. These compounds serve primarily as mild detergents, emulsifiers, and wetting agents where dermal tolerance and aquatic biodegradability are specified. Liquid APG dominates formulation flexibility in household and industrial cleaning, while cosmetic-grade material commands premium positioning due to ophthalmic and dermatological testing requirements. Powder APG is gaining traction in concentrated detergent tablets and solid personal care bars where water reduction drives logistics efficiency.
REACH registration and the EU Green Deal's sustainable chemistry criteria are tightening carbon-source traceability requirements for surfactants sold in Europe. EPA Safer Choice and FDA cosmetic ingredient reviews in the United States are converging on similar biodegradability and toxicology standards, reshaping import qualification protocols. Cosmetic-grade and food-grade segments face the steepest compliance escalation, concentrating certification investment among integrated manufacturers. Stakeholders must monitor regulatory divergence between European carbon-footprint accounting and U.S. toxicology-first frameworks when allocating R&D and regional capacity.
Market Dynamics
REACH registration deadlines and the EU Green Deal's sustainable chemistry criteria are forcing surfactant manufacturers to reconfigure carbon-source traceability systems. Cosmetic-grade certification requirements are concentrating procurement among integrated producers with captive glucose-fatty alcohol platforms.
Growth Catalysts
- EU Green Deal compliance mandates:REACH carbon-footprint accounting rules are accelerating biodegradable surfactant substitution in European personal care formulations. Brands now require certified renewable carbon chain documentation.
- Sulfate-free formulation pivot:Personal care manufacturers are eliminating sodium lauryl sulfate from shampoos and cleansers, redirecting procurement toward mild nonionic biosurfactants with established dermatological safety profiles.
- Concentrated detergent tablet demand:Powder APG grades are capturing share in solid-format household cleaning products where water reduction improves logistics economics and retail shelf density.
Market Restraints
- Fatty alcohol feedstock volatility:Coconut and palm kernel oil price swings transmit directly to APG production economics, compressing margin stability for non-integrated manufacturers.
- German production concentration:Ludwigshafen and Marl industrial clusters host disproportionate glucoside capacity, creating geographic supply risk for buyers seeking qualified alternative sources.
- Polyglucoside chain-length limitations:Standard C8-C14 alkyl distributions underperform in high-foam applications versus betaine co-surfactants, restricting standalone formulation penetration.
Strategic Opportunities
- India personal care expansion:BIS cosmetic ingredient standards are converging with EU biodegradability benchmarks, opening qualification pathways for certified APG suppliers in Mumbai and Ahmedabad formulation clusters.
- Food-grade emulsifier certification:FSSAI and FDA food-contact approvals for glucoside esters are enabling penetration into edible oil processing and beverage stabilization applications.
- Solid personal care bar formats:Waterless shampoo and cleansing bar growth is creating specification demand for low-water-content surfactant intermediates with compressed supply chains.
Industry Challenges
- Fischer glycosidation process engineering talent:Specialized carbohydrate chemistry expertise resides at a limited number of European and Japanese industrial research centers, constraining new entrant scale-up velocity.
- Cosmetic-grade ophthalmic testing timelines:Draize and in-vitro eye irritation protocols add 12-18 months to certification cycles for new alkyl chain length variants.
- Legacy sulfate surfactant inventory integration:Personal care brands must manage dual-stock transitions while reformulating around APG compatibility with existing preservative and fragrance systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alkyl Polyglucoside (APG) Surfactant Market |
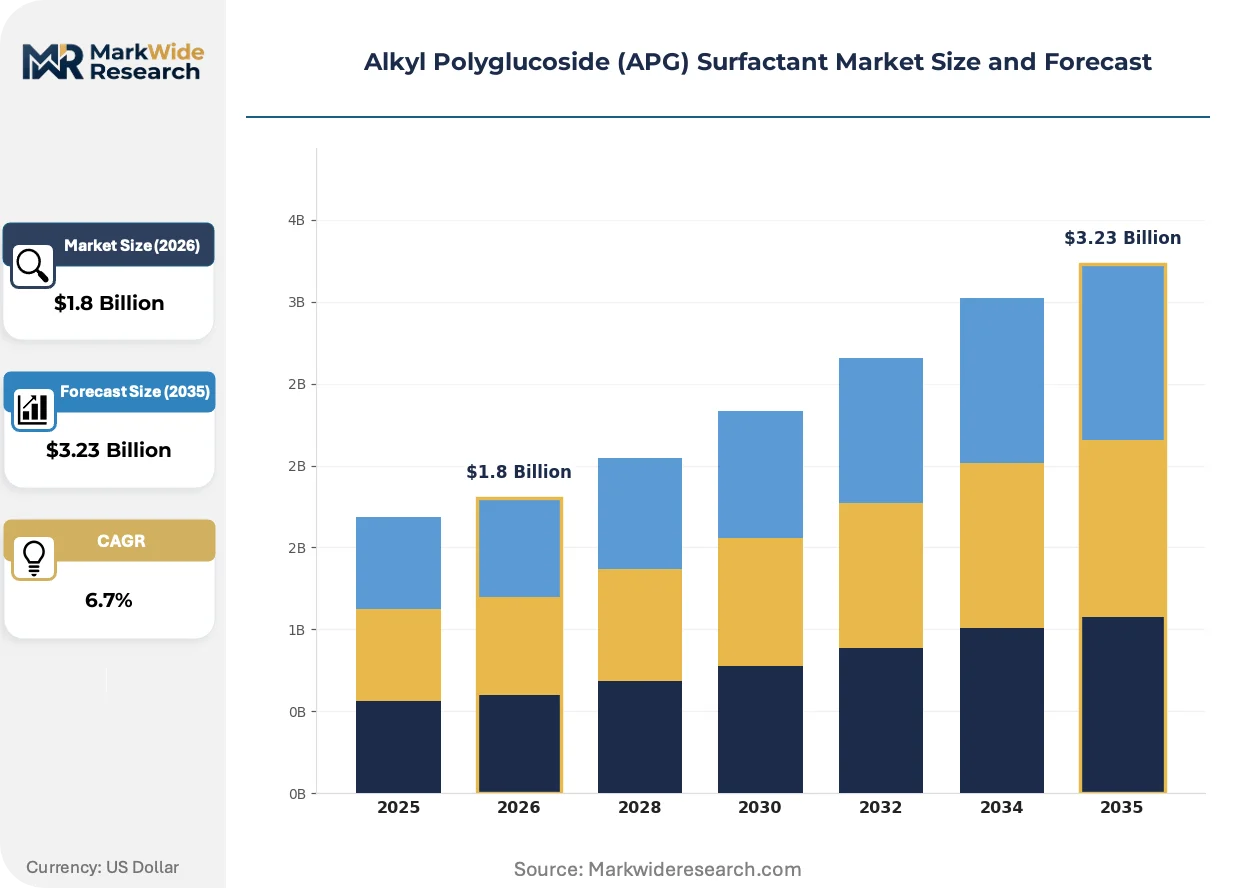
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid APG, Powder APG, Granular APG, Concentrate APG Application: Household Cleaning, Personal Care, Industrial Cleaning, Agricultural End Use Industry: Cosmetics, Detergents, Food Processing, Oil Field Grade: Food Grade, Cosmetic Grade, Industrial Grade, Pharmaceutical Grade |
| Companies Covered | Evonik Industries, Kao Corporation, BASF SE, SEPPIC, Galaxy Surfactants Ltd., Croda International Plc, Clariant AG, Stepan Company, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alkyl Polyglucoside (APG) Surfactant Market Strategic Shifts
Carbon-source verification technology and enzymatic synthesis routes are reshaping how manufacturers demonstrate compliance with tightening biodegradability mandates. These developments are compressing the gap between commodity and specialty grade positioning.
Enzymatic transglycosylation processes are absorbing investment from producers seeking to reduce Fischer glycosidation energy intensity and byproduct formation. Specialty chemical divisions at German and Japanese industrial groups are piloting these routes for cosmetic-grade output. The technology is absorbing market share from conventional acid-catalyzed production by enabling tighter molecular weight distribution control.
REACH Annex XVII restrictions on persistent organic pollutants are tightening surfactant impurity specifications for European cosmetic and cleaning product registrations. ECHA substance evaluation workflows now require detailed fatty alcohol source documentation back to plantation or fermentation origin. Cosmetic-grade APG segments face the steepest documentation burden, driving consolidation toward integrated glucose-fatty alcohol producers with captive supply chain transparency.
Direct long-term contracting between personal care brands and glucoside manufacturers is displacing traditional distributor-mediated procurement in European and North American markets. Beauty conglomerates are consolidating surfactant purchasing around certified green suppliers with REACH full registration status. This pattern is most visible in German and French cosmetics manufacturing clusters where procurement teams now mandate carbon-14 renewable content verification.
Alkyl Polyglucoside (APG) Surfactant Market Segmentation
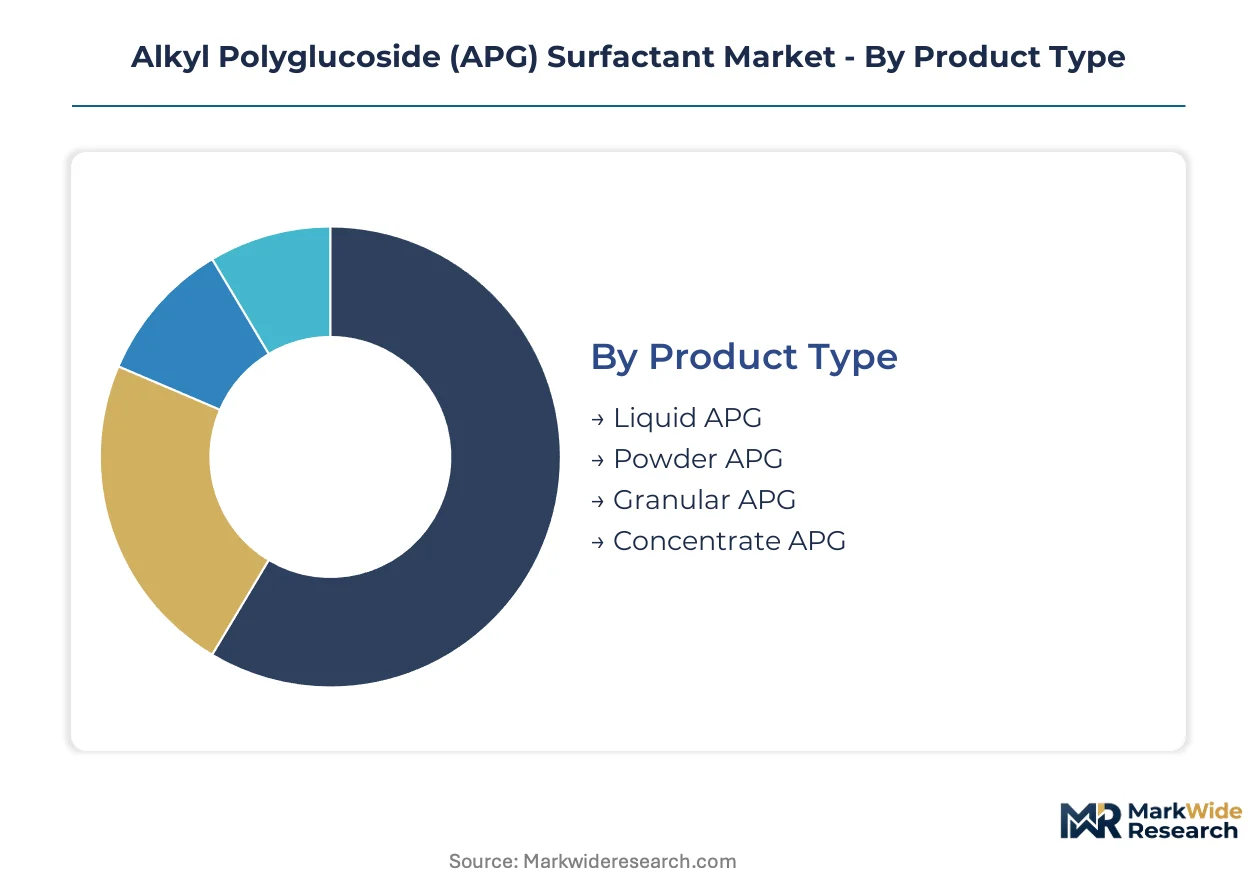
APG surfactant segmentation reflects divergent certification burdens and supply chain configurations. Formulators select product types and grades based on end-use regulatory thresholds, with cosmetic and food applications demanding the most intensive documentation.
Product Type:
Certification requirements vary sharply by physical form, with liquid grades facing simpler stability testing while solid formats trigger additional dissolution and dispersion protocols.
- Liquid APG:Aqueous solutions containing 50-70% active surfactant serve as the default input for formulated cleaners and personal care products. Demand concentrates in German and French cosmetics manufacturing where REACH-registered liquid grades dominate sulfate-free shampoo procurement.
- Powder APG:Spray-dried powders with sub-5% moisture content enable concentrated detergent tablets and solid personal care bars. Logistics efficiency drives adoption in European retail chains seeking reduced water-weight shipping economics.
- Granular APG:Agglomerated particles offer intermediate flow properties for industrial compounding operations. Mining and oil field chemical suppliers in Texas and Alberta specify granular formats for bulk handling systems.
- Concentrate APG:High-active formulations above 80% solids minimize transport costs for remote formulation sites. Agricultural adjuvant blenders in São Paulo and Mumbai source concentrates for on-site dilution.
Liquid APG sits at the top of the volume ranking, with powder APG climbing the fastest as waterless product formats gain shelf space.
Application:
Application selection determines whether suppliers must navigate cosmetic ingredient reviews, food-contact approvals, or industrial chemical registrations.
- Household Cleaning:All-purpose sprays, dishwashing liquids, and laundry detergents utilize APG for grease cutting combined with biodegradability claims. European supermarket private labels are consolidating procurement around EU Ecolabel-certified suppliers.
- Personal Care:Shampoos, facial cleansers, and baby care products require ophthalmic and dermatological safety data. FDA cosmetic ingredient reviews and EU SCCS opinions shape qualification timelines for new alkyl chain variants.
- Industrial Cleaning:Metal degreasers, vehicle washes, and food processing equipment cleaners demand high-foam or low-foam specifications. OSHA workplace exposure guidelines influence concentration limits in North American formulations.
- Agricultural:Pesticide adjuvants and fertilizer coatings exploit APG wetting and spreading properties. EPA inert ingredient listings and PMRA approvals in Canada gate market access for agricultural-grade material.
Household cleaning commands the largest application share, while personal care generates the steepest margin expansion.
End Use Industry:
Industry verticals impose distinct purity thresholds, with food and pharmaceutical segments requiring the most stringent contaminant controls.
- Cosmetics:Formulators demand cosmetic-grade APG with documented absence of 1,4-dioxane and ethylene oxide residues. ECHA substance evaluation workflows now require fatty alcohol source tracing back to plantation origin.
- Detergents:Laundry and dishwashing product manufacturers prioritize cost-efficient industrial-grade material with basic biodegradability certification. EU Ecolabel and EPA Safer Choice standards guide procurement specifications.
- Food Processing:Emulsifiers for edible oils and beverage stabilization require FSSAI and FDA food-contact approvals. Glucoside esters with specific HLB values serve niche applications in fat-reduced product formulations.
- Oil Field:Enhanced oil recovery and drilling fluid applications utilize APG for emulsion stability in high-salinity environments. Texas and North Dakota production sites specify thermal stability above 80°C for downhole conditions.
Detergents anchor volume demand, with food processing expanding most quickly as glucoside esters penetrate edible oil applications.
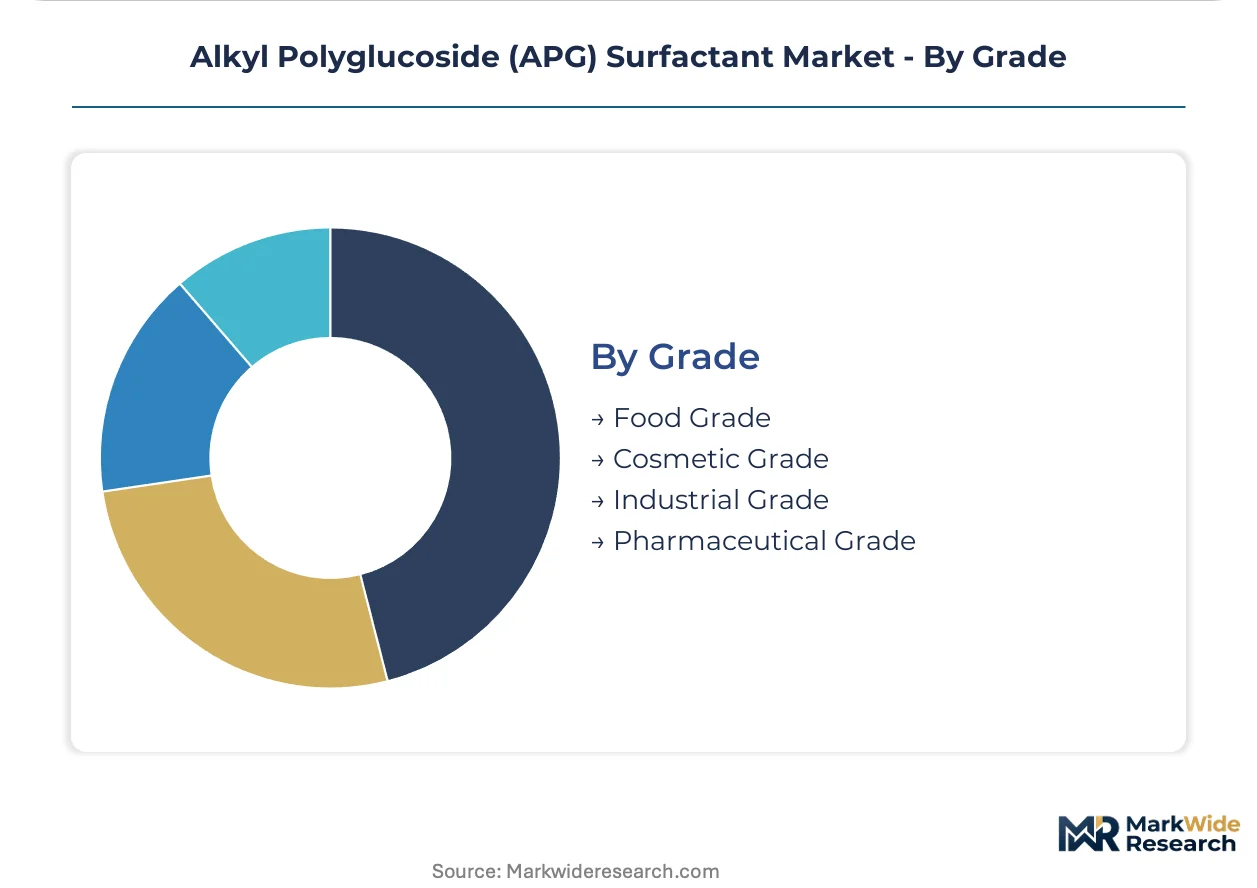
Grade:
Grade stratification directly maps to documentation intensity, with pharmaceutical and food grades demanding multi-year approval cycles.
- Food Grade:Meets FSSAI, FDA, and EFSA specifications for direct or indirect food contact. Indian edible oil processors in Mumbai and Ahmedabad are qualifying suppliers as BIS standards converge with EU benchmarks.
- Cosmetic Grade:Requires ophthalmic testing, dermatological safety data, and preservative compatibility studies. Draize and in-vitro eye irritation protocols add 12-18 months to certification for new variants.
- Industrial Grade:Standard biodegradability and aquatic toxicity documentation suffices for cleaning and agricultural applications. REACH registration without full cosmetic dossier reduces supplier qualification burden.
- Pharmaceutical Grade:Complies with USP-NF or EP monographs for excipient use in topical and oral drug delivery. CDSCO and PMDA reviews extend approval timelines beyond cosmetic-grade requirements.
Industrial grade holds the volume lead, with food grade gaining share fastest as emulsifier applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's integrated glucose-fatty alcohol platforms contrast with India's emerging formulation clusters, where BIS standards are converging with EU biodegradability benchmarks. Regional demand patterns diverge sharply between mature regulatory environments and fast-growing consumer markets.
Germany
Ludwigshafen and Marl industrial clusters host disproportionate glucoside capacity for REACH-registered cosmetic-grade output. The EU Green Deal's sustainable chemistry criteria enforce carbon-source traceability back to plantation origin. BASF SE leverages its integrated platform to sustain volume leadership in sulfate-free personal care formulations.
United States
EPA Safer Choice certification and FDA cosmetic ingredient reviews are converging on biodegradability standards that reshape import qualification protocols. OSHA workplace exposure guidelines influence APG concentration limits in industrial cleaning formulations. Texas and North Dakota oil field chemical suppliers specify thermal-stable grades for downhole applications.
India
Mumbai and Ahmedabad formulation clusters are expanding procurement as BIS cosmetic ingredient standards align with EU benchmarks. FSSAI food-contact approvals for glucoside esters enable penetration into edible oil processing. Domestic demand concentrates in waterless shampoo and cleansing bar formats for compressed supply chains.
Japan
PMDA reviews and METI chemical management frameworks extend approval timelines for pharmaceutical-grade APG beyond cosmetic requirements. Enzymatic transglycosylation expertise resides at a limited number of industrial research centers. Specialty producers anchor high-foam personal care applications for discerning domestic brands.
China
Dual carbon goals and GB standards for biodegradable surfactants are tightening manufacturing emissions requirements. NMPA cosmetic ingredient filings now require comprehensive toxicological dossiers. Yangtze River Delta chemical parks concentrate acid-catalyzed production capacity serving both domestic and export markets.
Alkyl Polyglucoside (APG) Surfactant Market Competitive Environment
German producers anchor the integrated tier; Asian specialists hold manufacturing scale advantages. The vendor base stratifies around three strategic archetypes: integrated petrochemical conglomerates with captive glucose-fatty alcohol platforms, specialty surfactant houses with cosmetic-grade certification depth, and regional scale players leveraging feedstock proximity. Competitive moves concentrate on backward integration into fatty alcohol supply and enzymatic process licensing for premium-grade positioning.
Within the integrated archetype, BASF SE and Evonik Industries exemplify European producers with Ludwigshafen-based operations. Kao Corporation represents Asian manufacturing scale with food-grade certification breadth. These three anchors demonstrate how geographic concentration in Germany combines with Asian feedstock access to define competitive positioning.
| Leading Market Players |
|---|
| Evonik Industries |
| Kao Corporation |
| BASF SE |
| SEPPIC |
| Galaxy Surfactants Ltd. |
| Croda International Plc |
| Clariant AG |
| Stepan Company |
| Dow Inc. |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal carbon-footprint accounting mandates gate qualified supply access and premium-tier pricing power for cosmetic-grade alkyl polyglucoside. Buyers lacking REACH-registered documentation face exclusion from German and French cosmetics procurement, compressing margin recovery for non-integrated suppliers.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for industrial-grade material, eroding legacy European premiums. Pricing stratifies across cosmetic, food, industrial, and pharmaceutical tiers, with certification depth and carbon-source traceability as primary differentiation levers. Cost compression in standard-grade liquid APG intensifies as Yangtze River Delta producers expand acid-catalyzed output. Detergent manufacturers exhibit highest price sensitivity; personal care brands absorb premium differentials for ophthalmic-tested cosmetic grades.
Supply Chain Analysis
Fischer glycosidation process engineering expertise concentrates in German and Japanese industrial research centers, constraining new entrant scale-up velocity. Supply draws from Germany, China, and India, with fatty alcohol feedstock anchored in coconut and palm kernel oil plantations across Southeast Asia. Single-source vulnerability runs through Ludwigshafen and Marl industrial clusters for REACH-registered cosmetic output. Distribution feeds from integrated glucose-fatty alcohol platforms through direct long-term contracting with personal care conglomerates, displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory escalation, with REACH Annex XVII restrictions on persistent organic pollutants accelerating biodegradable surfactant substitution. The EU Green Deal's sustainable chemistry criteria function as a demand multiplier for certified suppliers.
For Market Incumbents: To counter enzymatic transglycosylation process licensing by Japanese specialty houses, BASF SE and Evonik Industries should deepen backward integration into fatty alcohol supply and accelerate cosmetic-grade capacity expansion in Ludwigshafen. Captive glucose-fatty alcohol platforms remain the priority defensive lever against margin compression from Asian scale entrants. For New Entrants and Emerging Players: Waterless shampoo and cleansing bar formulators in India represent an underserved buyer archetype seeking low-water-content surfactant intermediates. White-space concentration appears in Mumbai and Ahmedabad formulation clusters where BIS standards convergence creates qualification pathways. A food-grade emulsifier certification-first go-to-market angle bypasses crowded cosmetic-grade competition. For Investors and Strategic Acquirers: Valuations sit cheapest among regional scale players with feedstock proximity but lacking REACH full registration status. Long-term viability over the next decade hinges on regulatory certification depth rather than manufacturing scale alone. The signal to watch is ECHA substance evaluation workflow acceleration for new alkyl chain variants, which would extend approval timelines and consolidate procurement among incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fatty Alcohol Supply | Captive coconut and palm kernel oil sourcing insulates margin from feedstock volatility. |
| Enzymatic Transglycosylation Licensing | Specialty chemical divisions at German and Japanese groups pilot reduced energy intensity routes. |
| Food-Grade Emulsifier Certification | FSSAI and FDA approvals enable penetration into Mumbai edible oil processing clusters. |
| Direct Long-Term Supply Contracting | Beauty conglomerates consolidate procurement around REACH-registered green suppliers. |
| Powder APG Capacity Expansion | Spray-dried formats capture concentrated detergent tablet and solid personal care bar demand. |
Study Parameters
Multiple input streams — primary interviews with plant managers and procurement leads at downstream personal care OEMs, secondary validation through customs data and Cefic surfactant reports, and technical R&D director consultations — were reconciled through bottom-up and top-down triangulation. Distribution channel partners and REACH regulatory consultants provided qualitative grounding for certification timeline assumptions.
Historical volume trajectories were cross-referenced against panel input from glucoside manufacturing executives to anchor projections across the analysis window. Segmentation dimensions modeled include physical form tier, end-use industry vertical, grade certification depth, and regional production hub concentration. CAGRs were derived from supply-side capacity announcements, demand elasticity estimates from sulfate-free formulation pivots, and regulatory compliance cost pass-through assumptions.
Underlying measurement precision varies by segment; liquid APG household cleaning applications carry tighter precision than pharmaceutical-grade excipient forecasts. Projections reflect assumptions on REACH registration timeline stability and fatty alcohol feedstock price corridors. Material deviation in ECHA substance evaluation workflow acceleration or EU Green Deal carbon accounting enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
North America Non-Ionic Surfactants Market
Surfactants
North America Surfactants Market
Surfactants
Emulsifying Wax Market
Surfactants
Cocamidopropyl Betaine Market
Surfactants
Global Methyl Soyate Market
Surfactants
Asia Pacific Surfactants Market
Surfactants
Amino Silicone Oil Market
Surfactants
Benzyl Trimethyl Ammonium Chloride Market
Surfactants
Superwetting Surfactants Market
Surfactants
Global Demulsifiers Market
Surfactants
Pharmaceutical Surfactants Market
Surfactants
Global Detergent Polymers Market
Surfactants
Acrylamide Tertiary-Butyl Sulfonic Acid (ATBS) Market
Surfactants
Global Amphoteric Surfactants Market
Surfactants
Global Saponin Market
Surfactants
Cocomonoethanolamide (CMEA) Market