
 Global Oilfield Surfactants Market | 2026-2036
Global Oilfield Surfactants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oilfield Surfactants Market Analysis
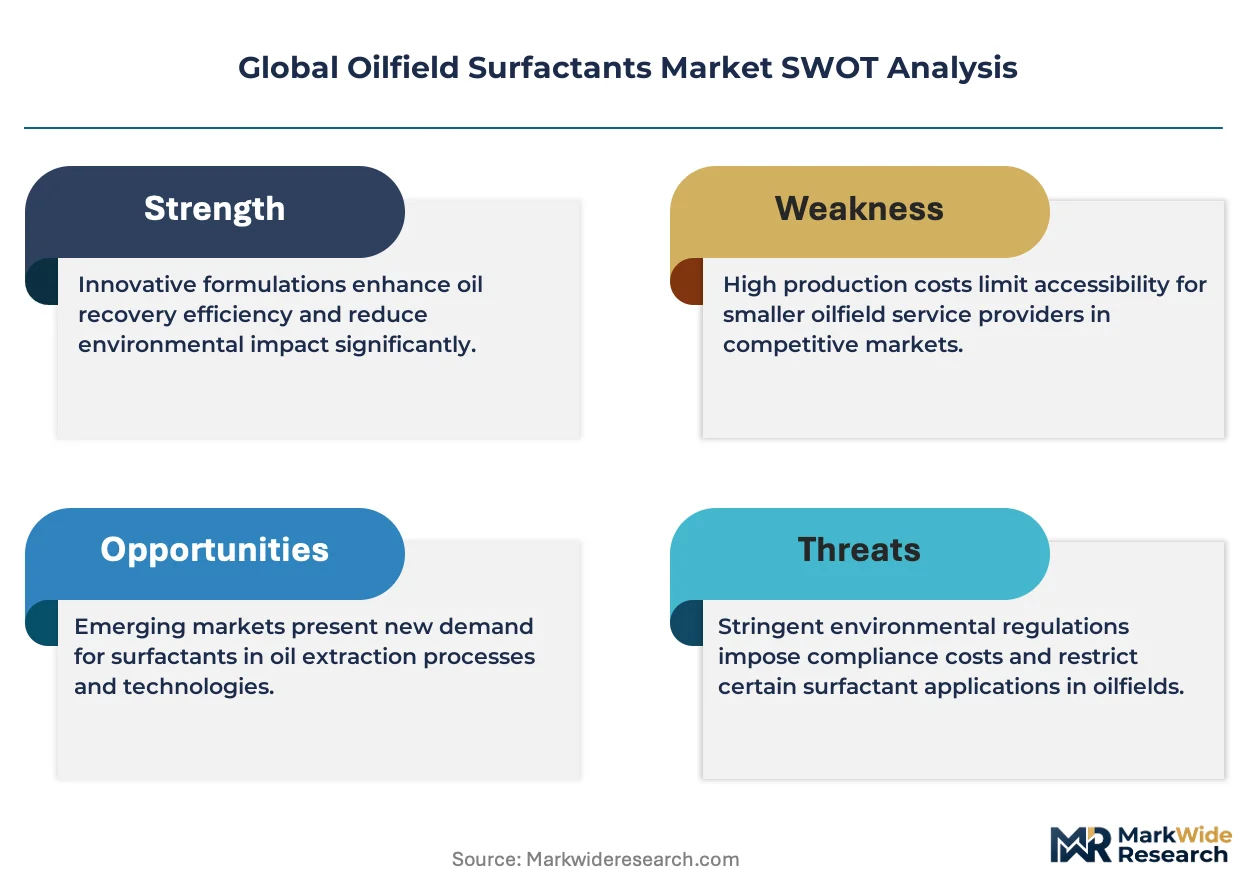
Biodegradable surfactant chemistry is reshaping how oilfield chemical systems are formulated and qualified for reservoir deployment. Dow leverages its ethylene oxide derivative backbone to sustain supply continuity across North American shale plays. BASF competes through alkyl polyglucoside platforms that reduce aquatic toxicity profiles. Stepan Company anchors its position via specialized anionic blends tailored for high-salinity formations.
Oilfield surfactants are amphiphilic compounds engineered with hydrophilic head groups and hydrophobic tails, typically synthesized through ethoxylation or sulfonation pathways, that reduce interfacial tension between crude oil, brine, and rock surfaces to mobilize trapped hydrocarbons. Anionic surfactants dominate drilling fluid applications where electrostatic stability governs clay dispersion control, while nonionic variants lead enhanced oil recovery segments due to superior salt tolerance and phase-behavior tunability. Zwitterionic chemistries occupy a premium niche in high-temperature carbonate reservoirs where competing charges prevent precipitation with divalent cations.
EPA guidelines under the Clean Water Act constrain discharge specifications for offshore surfactant packages, while REACH registration in Europe mandates full toxicological dossiers for ethoxylated alcohols used in North Sea operations. Saudi Arabia's national environmental regulator enforces increasingly stringent biodegradability thresholds for chemicals deployed in Red Sea and Arabian Gulf concessions. Stakeholders must monitor how divergent regulatory timelines across these jurisdictions reshape product registration costs and formulation lock-in periods.
Market Dynamics
REACH registration timelines in Europe and EPA discharge limits under the Clean Water Act are forcing formulation lock-in periods that extend product development cycles and concentrate supplier qualification around legacy chemistries.
Growth Catalysts
- Mature basin EOR deployment:Rising water-cut ratios in Permian Basin legacy wells are expanding surfactant consumption for chemical flooding operations.
- Biodegradability mandates:Saudi Arabia's national environmental regulator enforces stringent thresholds for Red Sea and Arabian Gulf concessions, accelerating qualification of alkyl polyglucoside platforms.
- High-salinity reservoir chemistry:Specialized anionic blends tailored for divalent cation tolerance are unlocking production from carbonate formations previously considered chemically incompatible.
Market Restraints
- Ethylene oxide supply concentration:North American ethoxylation capacity concentrates around Gulf Coast petrochemical clusters, exposing surfactant producers to hurricane-related disruption risk.
- Toxicological dossier costs:REACH registration for ethoxylated alcohols requires full mammalian toxicity studies that add eighteen to twenty-four months to European market entry timelines.
- Alkyl polyglucoside feedstock volatility:Fatty alcohol and glucose derivative prices fluctuate with palm oil and corn futures, compressing margin predictability for biodegradable formulations.
Strategic Opportunities
- Zwitterionic high-temperature niche:Competing charges in zwitterionic head groups prevent calcium and magnesium precipitation, opening carbonate reservoirs above 120°C previously closed to surfactant flooding.
- Red Sea concession chemistry:Saudi Arabia's biodegradability thresholds create first-mover advantage for suppliers with pre-qualified alkyl polyglucoside platforms against legacy ethoxylated competitors.
- Direct operator procurement:Supermajors in the Permian Basin are consolidating chemical purchasing away from oilfield service intermediaries, rewarding suppliers with captive manufacturing and technical service capabilities.
Industry Challenges
- Reservoir-specific formulation cycles:Each carbonate or sandstone formation demands customized phase-behavior testing that extends qualification timelines and fragments production runs.
- REACH-EPA regulatory divergence:Divergent data requirements between European toxicological dossiers and US ecological risk assessments force dual-track registration strategies that duplicate analytical expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oilfield Surfactants Market |
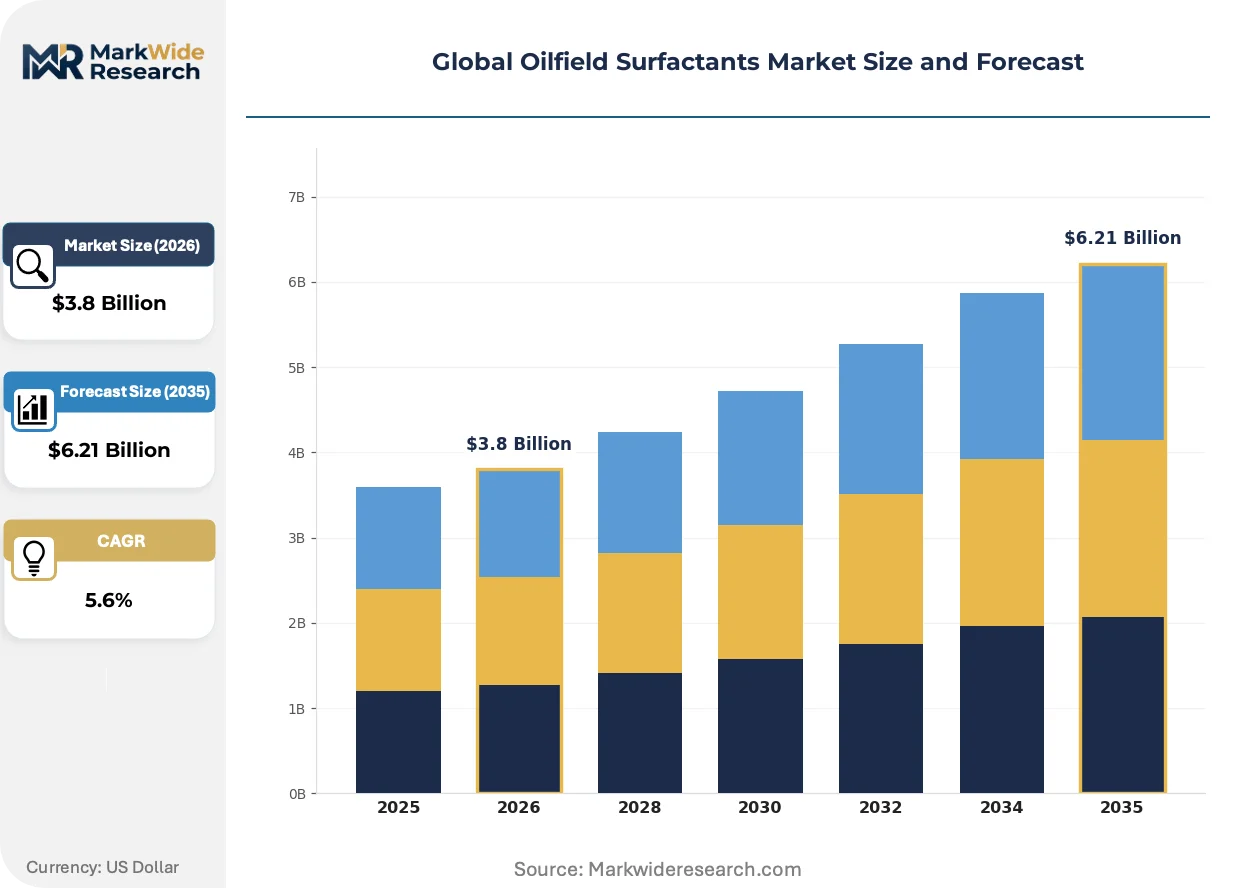
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nonionic Surfactants, Anionic Surfactants, Cationic Surfactants, Zwitterionic Surfactants Application: Enhanced Oil Recovery, Drilling Fluids, Cementing, Workover End User: Oil & Gas Companies, Service Providers, Contractors, Industrial Users Form: Liquid, Powder, Concentrate, Emulsion |
| Companies Covered | Dow, Stepan Company, BASF, Clariant, The Lubrizol Corporation, Halliburton, Evonik Industries, Solvay, Schlumberger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oilfield Surfactants Market Emerging Trajectories
Formulation chemistry is pivoting toward salt-tolerant and thermally stable architectures as operators push surfactant flooding into deeper, hotter, and more saline reservoirs previously considered uneconomic.
Bio-based surfactant platforms derived from renewable fatty alcohol and carbohydrate feedstocks are rendering obsolete petroleum-derived ethoxylates in environmentally sensitive concessions. Operators in the North Sea and Red Sea are mandating these chemistries in tender specifications. The shift compresses demand for conventional ethylene oxide derivatives in premium offshore segments while locking in supply contracts with agricultural feedstock processors.
EPA guidelines under the Clean Water Act now constrain discharge specifications for offshore surfactant packages in US federal waters. The industrial consequence is a bifurcation between Gulf of Mexico formulations meeting strict aquatic toxicity limits and onshore products optimized for cost rather than environmental fate. Offshore chemical suppliers are responding by pre-qualifying biodegradable alternatives ahead of anticipated tightening in 2026-2027 permit cycles.
Operator procurement departments are consolidating chemical purchasing away from oilfield service company intermediaries and toward direct manufacturer relationships. Supermajors in the Permian Basin now require technical service engineers embedded at district offices rather than remote support. This pattern is most visible among independents with concentrated Delaware Basin positions seeking to reduce markup layers and accelerate formulation troubleshooting response times.
Global Oilfield Surfactants Market Segmentation
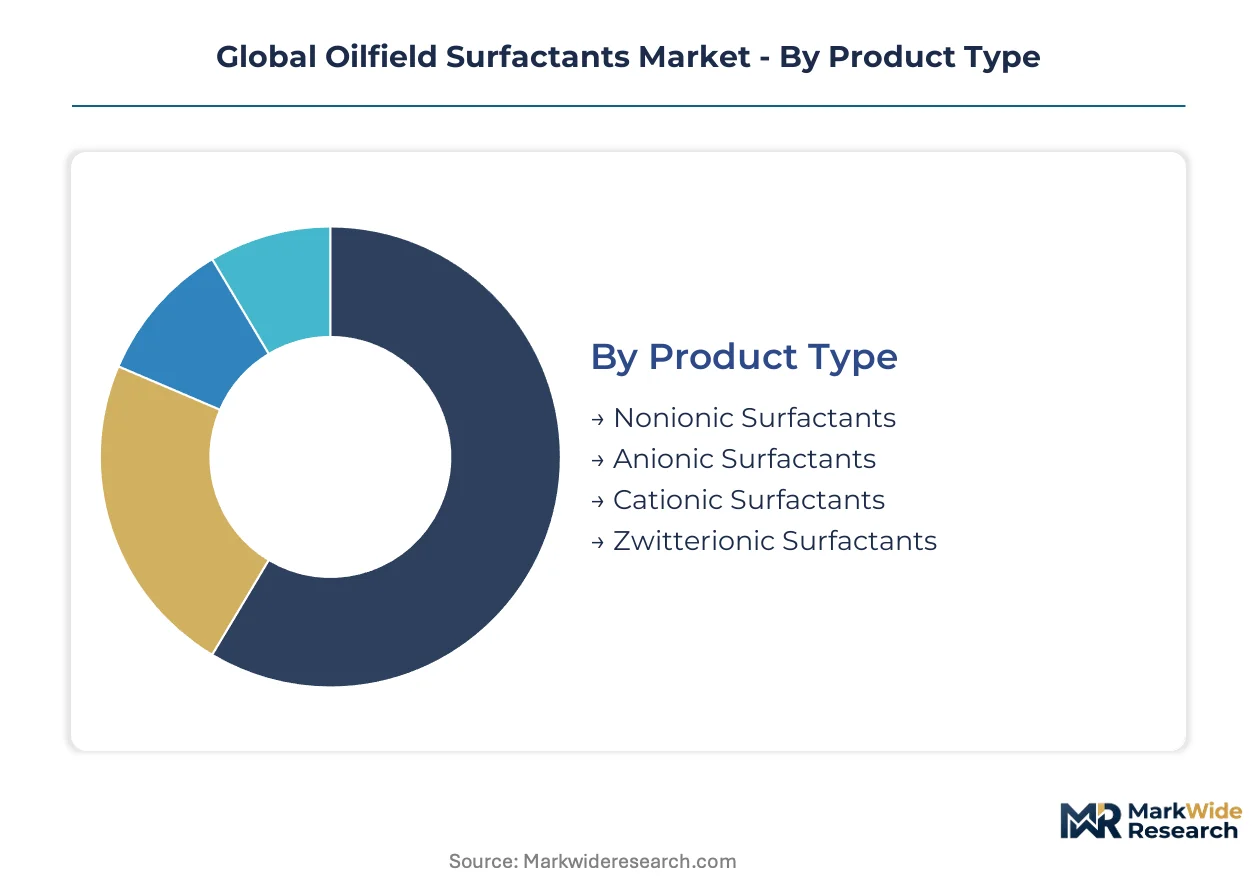
Oilfield surfactant procurement cycles vary dramatically by segment chemistry and application criticality. Understanding these turnover velocities helps suppliers align inventory positioning with operator consumption patterns and qualification timelines.
Product Type:
Nonionic and anionic formulations turn inventory fastest due to standardized qualification protocols, while zwitterionic and cationic variants lock in longer development cycles for reservoir-specific customization.
- Nonionic Surfactants:Ethoxylated alcohol and alkylphenol structures deliver superior salt tolerance and temperature stability for chemical flooding operations. Demand concentrates in Permian Basin EOR projects where operators face rising water-cut ratios in legacy wells.
- Anionic Surfactants:Sulfonate and sulfate head groups provide electrostatic stabilization critical for drilling fluid rheology control. Consumption clusters around Gulf Coast shale plays where high-salinity formations require divalent cation compatibility.
- Cationic Surfactants:Quaternary ammonium compounds serve corrosion inhibition and biocide synergy roles in completion fluids.
- Zwitterionic Surfactants:Competing positive-negative charges prevent precipitation in high-temperature carbonate reservoirs exceeding 120°C.
Nonionic surfactants dominate installed base. Zwitterionic platforms are where expansion concentrates.
Application:
Cost tier stratification separates commodity drilling fluids from premium EOR formulations commanding technical service premiums and extended qualification periods.
- Enhanced Oil Recovery:Surfactant-polymer and alkali-surfactant-polymer flooding systems mobilize residual oil through ultra-low interfacial tension reduction. Saudi Arabia's Red Sea concessions are mandating biodegradable alkyl polyglucoside platforms under national environmental regulator thresholds.
- Drilling Fluids:Emulsifiers and wetting agents stabilize oil-based and synthetic-based mud systems through elevated-pressure high-temperature conditions. North Sea operators under REACH compliance are phasing out persistent ethoxylated alcohols for offshore discharge.
- Cementing:Surfactant additives control fluid loss and improve bonding in primary and remedial cement jobs.
- Workover:Cleanup surfactants remove formation damage from prior drilling or production chemistry.
Drilling fluids command highest volume throughput. Enhanced oil recovery is climbing the fastest.
End User:
Procurement authority migration from service company intermediaries to direct operator relationships is reshaping segment purchasing patterns and technical support expectations.
- Oil & Gas Companies:Supermajors and large independents in the Permian Basin are consolidating chemical purchasing directly with manufacturers, bypassing oilfield service markups. Embedded technical service engineers at district offices now determine supplier selection.
- Service Providers:Schlumberger, Halliburton, and Baker Hughes historically controlled formulation specification but are ceding procurement authority to operator direct sourcing.
- Contractors:Regional drilling and completion contractors purchase spot volumes for non-critical applications.
- Industrial Users:Refinery and midstream operators deploy surfactants for desalting and corrosion control.
Oil & Gas Companies drive specification authority. Service Providers retain formulation integration expertise.
Form:
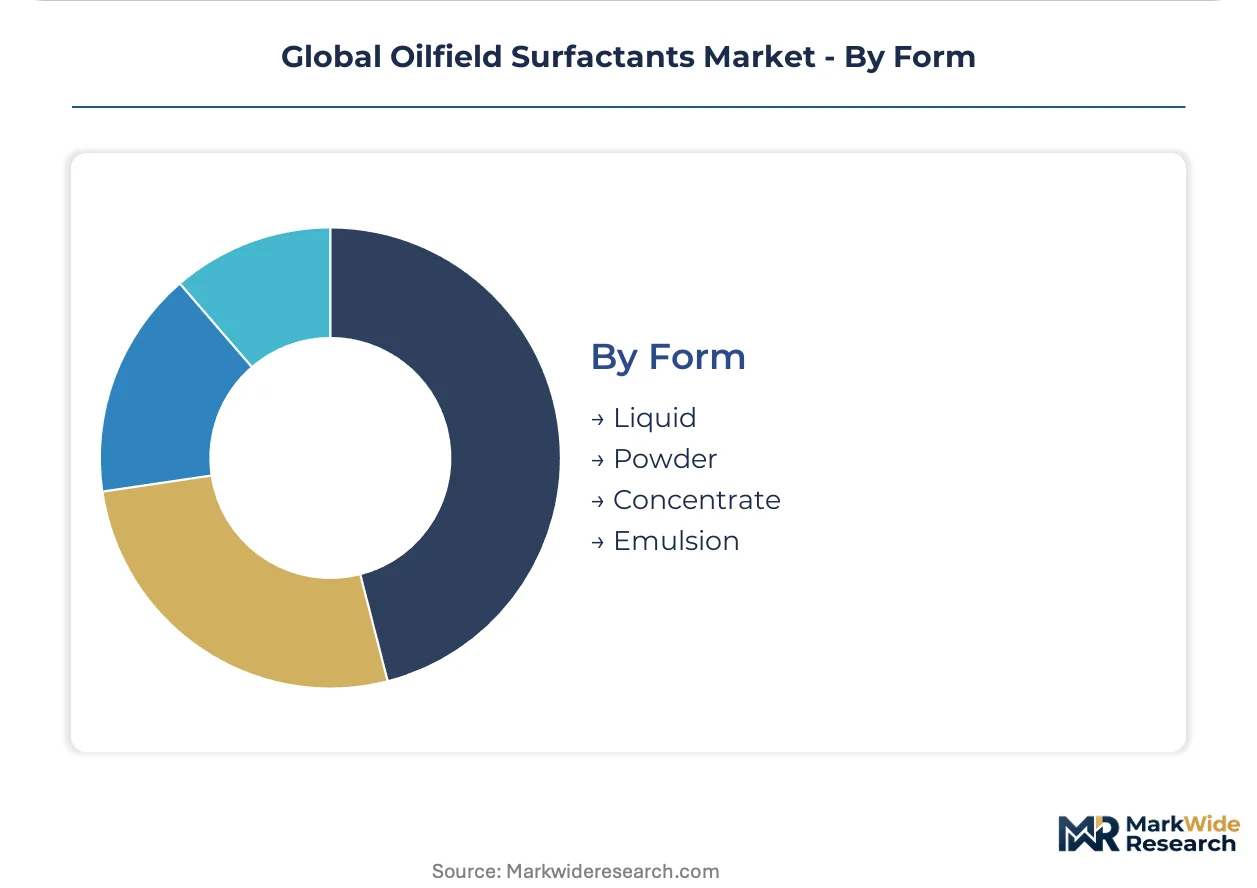
Supply chain configuration favors liquid bulk delivery for high-volume applications while powder and concentrate formats address remote logistics and custom blending requirements.
- Liquid:Bulk tanker and tote delivery dominates Permian Basin and Gulf Coast operations with established chemical terminal infrastructure.
- Powder:Spray-dried formulations reduce shipping costs for international and remote onshore locations lacking liquid handling capabilities.
- Concentrate:High-active formulations enable field dilution, cutting transport expense for overseas shipments to Saudi Arabian and North Sea concessions.
- Emulsion:Pre-dispersed water-in-oil systems simplify field mixing for workover and remediation applications.
Liquid forms anchor volume economics. Concentrate formats are gaining share fastest in international supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supermajors and large independents in the Permian Basin anchor the highest concentration of direct procurement authority. Saudi Aramco and ADNOC drive specification mandates across Middle Eastern concessions. European North Sea operators enforce the strictest environmental compliance thresholds for offshore discharge.
United States
Permian Basin operators facing rising water-cut ratios in legacy wells are expanding surfactant consumption for chemical flooding operations. EPA discharge limits under the Clean Water Act constrain offshore formulation specifications in federal waters. Houston-Gulf Coast petrochemical clusters concentrate ethoxylation capacity, exposing producers to hurricane-related disruption risk.
Saudi Arabia
Red Sea and Arabian Gulf concession operators are mandating biodegradable alkyl polyglucoside platforms under national environmental regulator thresholds. The country's national environmental regulator enforces increasingly stringent biodegradability requirements for chemicals deployed in sensitive marine ecosystems. Dhahran-based technical centers coordinate qualification protocols for high-temperature carbonate reservoir chemistries.
Germany
REACH registration mandates full toxicological dossiers for ethoxylated alcohols used in North Sea operations, extending market entry timelines. ECHA compliance requirements concentrate supplier qualification around legacy chemistries with completed registration packages. Ludwigshafen chemical complexes anchor European surfactant formulation capabilities for offshore drilling applications.
China
National oil companies are expanding surfactant-polymer flooding pilots in mature Daqing and Shengli oilfields. MEE environmental standards are tightening discharge specifications for Bohai Bay offshore operations. Sichuan-Chongqing shale gas development is driving demand for high-salinity tolerant anionic blends in complex carbonate formations.
Brazil
Pre-salt carbonate reservoir development is unlocking demand for thermally stable zwitterionic chemistries above 120°C. ANVISA and national environmental regulators are phasing in biodegradability requirements for Campos Basin offshore operations. Rio de Janeiro technical centers coordinate formulation qualification for deepwater chemical flooding systems.
Global Oilfield Surfactants Market Vendor Landscape
Channel-controlling players compete with product-specialist players across formulation integration and raw material supply. The market structure tiered between integrated petrochemical majors, specialized surfactant manufacturers, and oilfield service companies with captive chemical capabilities. Three archetypes dominate: ethylene oxide derivative suppliers with backward integration into feedstocks, bio-based platform specialists leveraging agricultural supply chains, and service-integrated formulators with embedded technical service networks. Capacity expansion and direct operator procurement relationships represent the dominant competitive moves reshaping supplier positioning.
Within the integrated petrochemical tier, Dow and BASF exemplify scale-driven players leveraging ethylene oxide derivative backbones. Stepan Company occupies a specialist position among North American anionic blend manufacturers. These three entities represent contrasting strategic anchors: global feedstock integration, bio-based platform diversification, and high-salinity formation specialization respectively.
| Leading Market Players |
|---|
| Dow |
| Stepan Company |
| BASF |
| Clariant |
| The Lubrizol Corporation |
| Halliburton |
| Evonik Industries |
| Solvay |
| Schlumberger |
| Others |
Supply Flow & Price Mechanics
Houston-Galveston petrochemical corridor freight costs transmit directly into surfactant pricing differentials, amplifying margin compression for suppliers without captive ethoxylation capacity while rewarding Gulf Coast producers with integrated logistics and raw material access.
Pricing Analysis
Cost-plus contracts indexed to ethylene oxide spot markets dominate long-term supply agreements between surfactant manufacturers and Permian Basin operators. Price differentiation rests on biodegradability certification tier and embedded technical service intensity, with REACH-compliant formulations commanding substantial premiums over standard onshore grades. Pricing pressure stems from alkyl polyglucoside feedstock volatility tied to agricultural commodity futures. National oil companies exhibit lowest price sensitivity due to formulation qualification lock-in, while regional drilling contractors face acute margin pressure on spot purchases.
Supply Chain Analysis
Export control regimes on specialized sulfonation catalysts and ethoxylation process technology limit equipment flows to certain national oil company laboratories, constraining indigenous capacity buildout in targeted jurisdictions. Manufacturing gravity centers on the United States, Germany, and China, with each hub serving distinct regulatory compliance zones. Raw material supply draws from Gulf Coast ethylene oxide crackers, European fatty alcohol distributors, and Southeast Asian palm oil derivatives. Single-source vulnerability concentrates around hurricane-exposed Texas-Louisiana petrochemical infrastructure. Distribution runs through bulk liquid terminals for domestic shale plays and concentrate packaging for international concession shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oilfield surfactants market sits in early-cycle expansion as biodegradability mandates penetrate premium offshore segments and chemical flooding deployment accelerates in mature basins previously written off for tertiary recovery.
For Market Incumbents: Harden formulation qualification databases against emerging bio-based platform competitors by accelerating alkyl polyglucoside registration dossiers ahead of regulatory tightening in Middle Eastern concessions. Anchor supply security through backward integration into ethylene oxide derivatives or captive agricultural feedstock partnerships, neutralizing margin volatility from commodity-indexed raw material exposure. For New Entrants and Emerging Players: Brazilian pre-salt carbonate formations represent the most penetrable white-space target, where thermally stable zwitterionic chemistries above 120°C remain undersupplied by incumbent ethoxylated alcohol portfolios. Target direct procurement relationships with supermajors consolidating chemical purchasing away from oilfield service intermediaries, embedding technical service engineers at district offices to accelerate troubleshooting response and secure formulation lock-in. For Investors and Strategic Acquirers: Saudi Arabia's national environmental regulator reshapes the acquisition landscape toward suppliers with pre-qualified biodegradable platforms and completed Red Sea concession chemistry dossiers. Five-to-ten-year viability favors specialists with captive manufacturing and reservoir-specific formulation capabilities over commodity ethoxylate traders. The signal to watch is permit cycle tightening in US federal waters under anticipated EPA discharge threshold revisions, which would accelerate obsolescence of legacy petroleum-derived surfactant inventories.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Gulf Coast ethoxylation buildout secures supply continuity against hurricane disruption risk. |
| Backward Integration | Captive fatty alcohol production from agricultural feedstocks stabilizes alkyl polyglucoside margin predictability. |
| Green Manufacturing Transition | Biodegradable platform qualification unlocks premium pricing in Red Sea and North Sea concessions. |
| Long-term Supply Agreement | Direct operator contracts with embedded technical service displace oilfield service intermediary markups. |
| Joint Venture | Regional formulation partnerships with national oil companies accelerate concession-specific qualification timelines. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with surfactant formulation chemists, oilfield procurement directors, and reservoir engineering specialists; and secondary validation through customs trade databases, EPA discharge permit filings, and ECHA registration dossiers. Bottom-up triangulation against top-down petrochemical capacity assessments ensured segment-level consistency.
Forecast inputs considered product chemistry, application criticality, end-user procurement authority, and regional regulatory framework across the projection horizon. CAGRs were derived from segment-level consumption modeling tied to mature basin EOR deployment schedules and biodegradability mandate adoption curves. Industry-specific inputs included water-cut ratio trajectories in Permian legacy wells and national environmental regulator threshold timelines in Saudi Arabia.
Macroeconomic conditions sit as an overlay; deviation in crude oil price bands and agricultural commodity futures would shift the trajectory for bio-based versus petroleum-derived surfactant competitiveness. Material shifts in REACH-EPA regulatory divergence or ethylene oxide supply disruption frequency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Anionic Surfactants Market
Surfactants
Selenium Sulphide Market
Surfactants
Dodecanol Market
Surfactants
Global Rhamnolipid Market
Surfactants
Global Detergent Polymers Market
Surfactants
Sugar-Based Surfactants Market
Surfactants
Secondary Alkane Sulfonate Market
Surfactants
Cyclotetrasiloxane Market
Surfactants
Global Detergents Market
Surfactants
Tetradecyl Chloride Market
Surfactants
Acrylamide Tertiary-Butyl Sulfonic Acid (ATBS) Market
Surfactants
Sodium Cumenesulfonate Market
Surfactants
Bitumen Emulsifier Market
Surfactants
Emulsifying Wax Market
Surfactants
Coconut Derived Surfactants Market
Surfactants
Sodium Naphthalene Sulphonate Formaldehyde Market