
 Mass Beauty & Personal Care Products Market | 2026-2036
Mass Beauty & Personal Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Mass Beauty & Personal Care Products Market Analytics
China is narrowing the gap between mass-market production scale and premium-grade quality benchmarks through automated manufacturing clusters in Guangdong and Jiangsu provinces. L'Oreal leverages its dermatological research pipeline to sustain innovation velocity across skincare and haircare lines. Procter & Gamble anchors volume leadership through supermarket and pharmacy distribution networks spanning multiple continents. Unilever differentiates via sustainability-certified sourcing programs that resonate with environmentally conscious buyers.
Mass beauty and personal care products encompass chemically formulated or naturally derived substances manufactured in high-throughput batch processes, with pH stability, preservative efficacy, and dermatological safety serving as core technical parameters. These products serve commercial purposes centered on daily hygiene maintenance, aesthetic enhancement, and skin barrier protection for broad consumer populations. Skincare commands the largest margin pool as consumers prioritize preventive regimens over reactive treatment, while e-commerce distribution channels represent the fastest-expanding access point due to direct-to-consumer subscription models and algorithm-driven personalization. Budget and mid-range price tiers absorb the majority of unit volume in emerging economies where per-capita spending constraints persist.
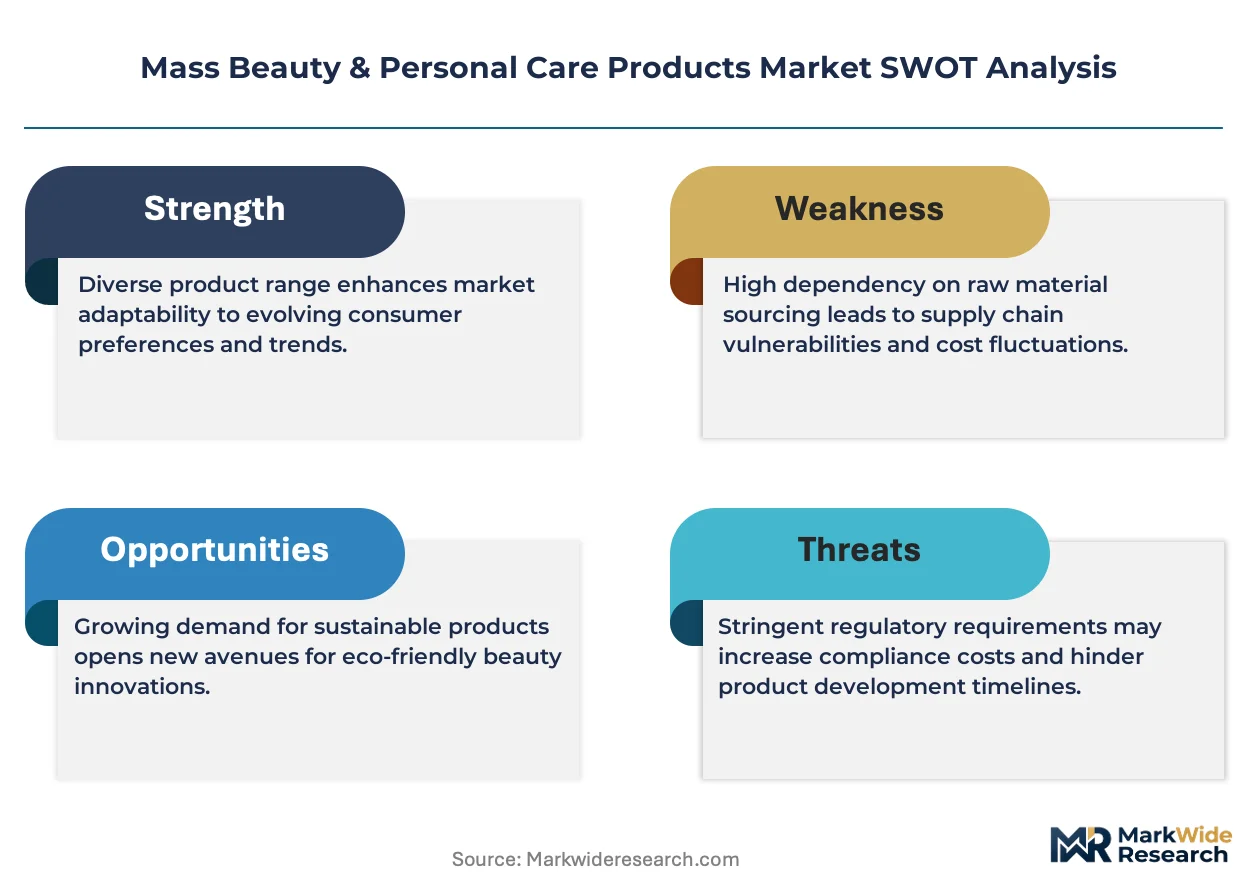
The EU's REACH chemicals framework and the FDA's cosmetic labeling requirements in the United States jointly elevate compliance costs for cross-border mass beauty suppliers, forcing reformulation investments and extended safety documentation cycles. China's SAMR enforces GB standards for cosmetic ingredient thresholds that diverge from Western protocols, creating fragmented regulatory terrain for multinational portfolios. Stakeholders must monitor evolving PFAS restrictions and state-level ingredient disclosure laws that threaten legacy product lines while opening avenues for clean-chemistry innovators.
Market Dynamics
Clean-label chemistry mandates from the EU's ECHA and China's SAMR are forcing simultaneous reformulation across legacy product portfolios, compressing R&D timelines while elevating compliance spend as the dominant structural pressure reshaping competitive economics.
Growth Catalysts
- REACH Chemicals Framework:The EU's regulatory elevation creates first-mover advantage for compliant suppliers accessing European pharmacy and supermarket channels ahead of enforcement deadlines.
- Skincare-First Routines:Teenage and young-adult cohorts in China's tier-one cities and India's metropolitan corridors drive preventive regimen adoption over reactive treatment models.
- Automated Manufacturing Clusters:Guangdong and Jiangsu provinces narrow the production-scale-to-quality gap through high-throughput batch processes with embedded dermatological safety testing.
Market Restraints
- Petrochemical Derivative Volatility:Surfactant and emollient input costs fluctuate with crude-linked feedstock markets, compressing margin predictability for mass-market price tiers.
- Regulatory Fragmentation:China's GB standards for cosmetic ingredient thresholds diverge from FDA and REACH protocols, forcing parallel documentation cycles and duplicative safety testing.
- PFAS Substitution Complexity:Legacy waterproofing and texture-enhancing chemistries face phase-out timelines without drop-in natural alternatives at equivalent cost-performance ratios.
Strategic Opportunities
- Direct-to-Consumer Subscription Models:Algorithm-driven personalization via e-commerce channels bypasses traditional supermarket and pharmacy distribution gatekeepers.
- India's Metropolitan Corridors:Underpenetrated mid-range price tiers absorb volume as per-capita spending constraints ease in secondary cities beyond Mumbai and Delhi.
- Sustainability-Certified Sourcing:Environmentally conscious buyer segments reward supply chain transparency with loyalty premiums and reduced price elasticity.
Industry Challenges
- Clean-Chemistry Talent Scarcity:Formulation chemists with dual competence in natural ingredient stability and high-throughput manufacturing scale command premium compensation.
- Cross-Border Compliance Timelines:Extended safety documentation cycles for divergent GB, REACH, and FDA requirements delay product launch windows by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mass Beauty & Personal Care Products Market |
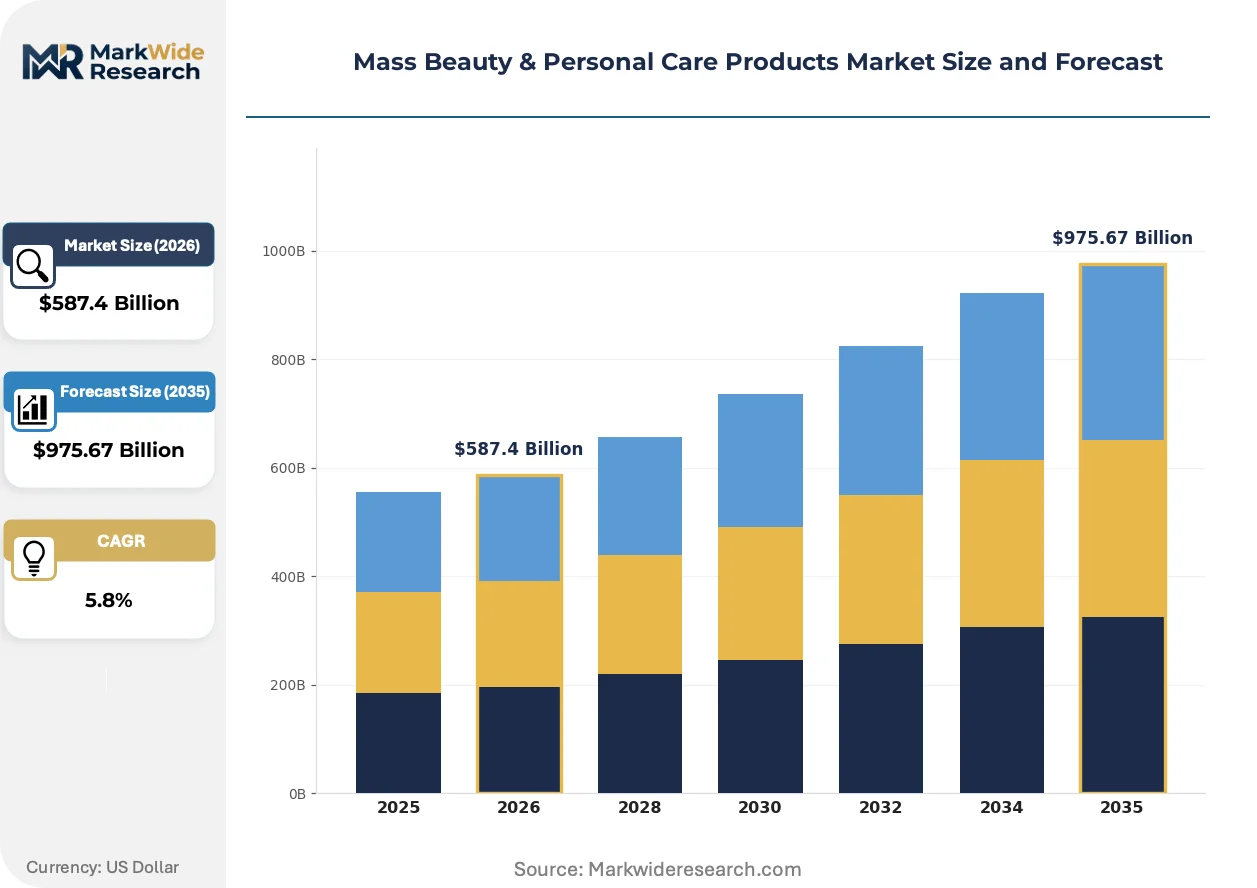
| Market Size in 2026 | $587.4 Billion |
| Market Size in 2035 | $975.67 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance Distribution Channel: Supermarkets, E-commerce, Pharmacies, Specialty Stores Price Tier: Mid-range, Budget, Premium, Luxury Customer Type: Female, Male, Teenagers, Professionals |
| Companies Covered | Shiseido, Estee Lauder, L'Oreal, Henkel, Colgate-Palmolive, Procter & Gamble, Beiersdorf, Revlon, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mass Beauty & Personal Care Products Market Evolving Landscape
Formulation science, distribution architecture, and regulatory compliance methods are converging to redefine how mass beauty products reach price-sensitive consumers.
Artificial intelligence-driven skin diagnostic tools are virtualizing the traditional in-store consultation experience. Younger consumer cohorts adopt these platforms at accelerating velocity through smartphone-integrated applications. The technology is virtualizing dermatological assessment workflows that previously required physical retail presence, compressing the path from need recognition to purchase completion.
China's SAMR enforcement of GB standards for cosmetic ingredient thresholds is tightening divergence from Western regulatory protocols. Multinational suppliers face parallel compliance documentation and extended safety testing cycles. Skincare and haircare lines with cross-border ambitions absorb the heaviest adaptation burden through dedicated China-specific formulation teams.
Subscription-based replenishment models displace single-transaction retail purchasing among digitally native demographics. Direct-to-consumer platforms with algorithm-curated product matching bypass traditional supermarket and pharmacy distribution hierarchies. This channel rotation concentrates visibility in China's tier-one cities and India's metropolitan corridors where logistics infrastructure supports reliable last-mile delivery.
Mass Beauty & Personal Care Products Market Segmentation
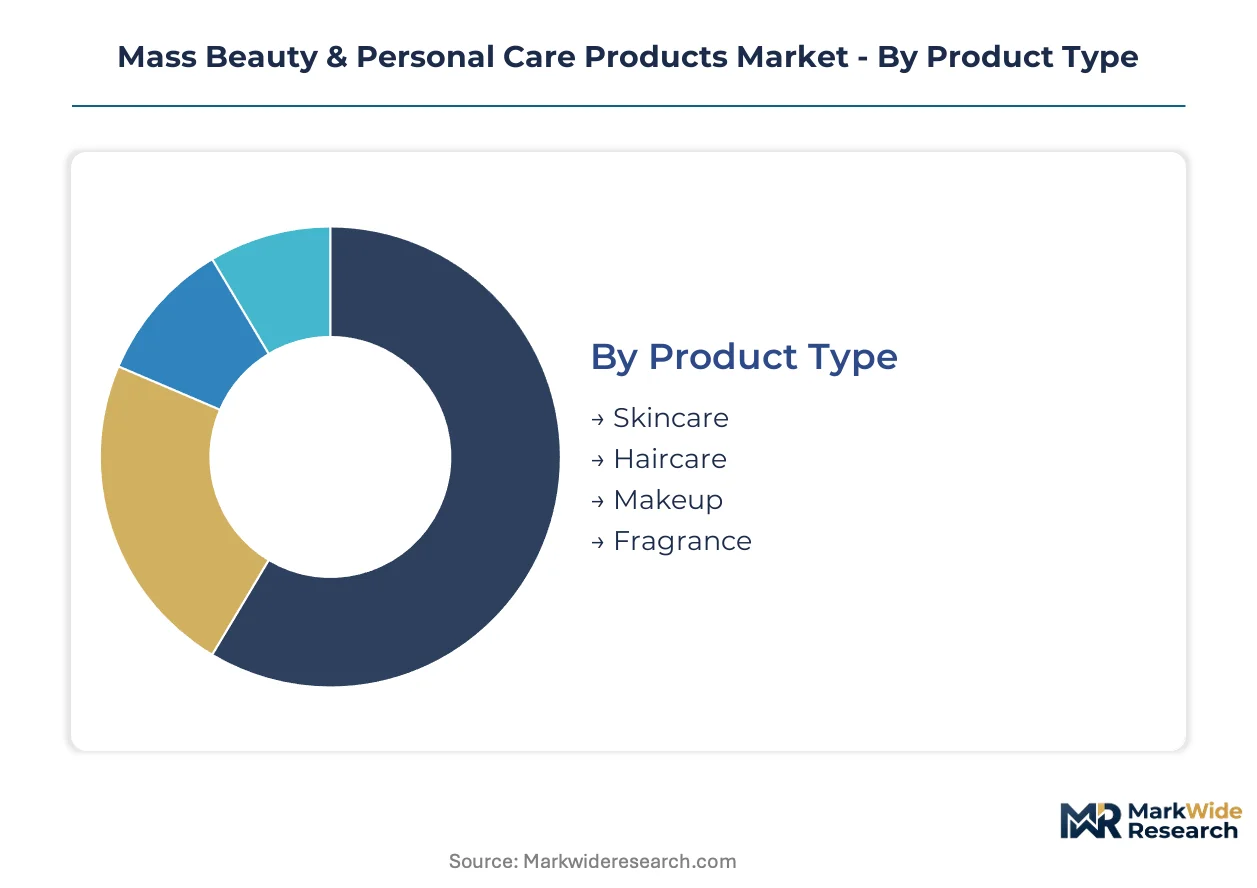
Mass beauty and personal care products fragment across four structural dimensions that determine formulation priorities, margin architecture, and channel access. Each segmentation axis carries distinct regulatory exposure and growth velocity profiles that reshape supplier resource allocation.
Product Type:
Use-case spectrum spans daily hygiene maintenance through aesthetic enhancement and therapeutic intervention, with dermatological safety thresholds varying sharply across functional claims.
- Skincare:Chemically formulated or naturally derived substances with pH stability and preservative efficacy as core technical parameters. Demand concentrates in China's tier-one cities where teenage and young-adult cohorts drive preventive regimen adoption over reactive treatment models.
- Haircare:High-throughput batch processes emphasizing surfactant performance and scalp compatibility. India's metropolitan corridors absorb volume as per-capita spending constraints ease and professional grooming standards intensify among urban professionals.
- Makeup:Color chemistry with pigment dispersion and wear-duration specifications. E-commerce subscription models accelerate trial-to-purchase conversion among digitally native demographics.
- Fragrance:Volatile compound stability and allergen disclosure compliance. EU ECHA mandates on fragrance ingredient labeling elevate documentation burdens for cross-border suppliers.
Established volume favors skincare; emerging adoption favors haircare.
Distribution Channel:
Cost tier determines margin retention, with direct access commanding premium economics over intermediary-heavy pathways.
- E-commerce:Algorithm-driven personalization and direct-to-consumer subscription models. China's tier-one cities and India's metropolitan corridors concentrate adoption where logistics infrastructure supports reliable last-mile delivery.
- Supermarkets:High-throughput retail with mass-market price tier dominance. Volume leadership anchors here through shelf-space negotiations and promotional bundling.
- Pharmacies:Dermatological credibility and regulatory compliance signaling. EU pharmacy channels reward REACH framework adherence with preferred placement.
- Specialty Stores:Curated assortment and consultation-assisted selling. Premium and luxury price tiers concentrate visibility through experiential retail formats.
Supermarkets retain volume leadership; e-commerce climbs the fastest.
Price Tier:
Application intensity varies from daily replenishment through occasional indulgence, with formulation sophistication scaling across economic levels.
- Budget:Essential hygiene functions with streamlined ingredient lists. Emerging economies absorb majority unit volume where per-capita spending constraints persist.
- Mid-range:Balanced performance claims with moderate dermatological testing. India's secondary cities beyond Mumbai and Delhi drive expansion as disposable income thresholds shift.
- Premium:Enhanced active ingredient concentrations and sustainability certifications. Environmentally conscious buyer segments reward supply chain transparency with loyalty premiums.
- Luxury:Patented delivery systems and exclusive distribution. Specialty store channels concentrate visibility through limited availability architecture.
Budget tier anchors unit economics; premium tier gains share fastest.
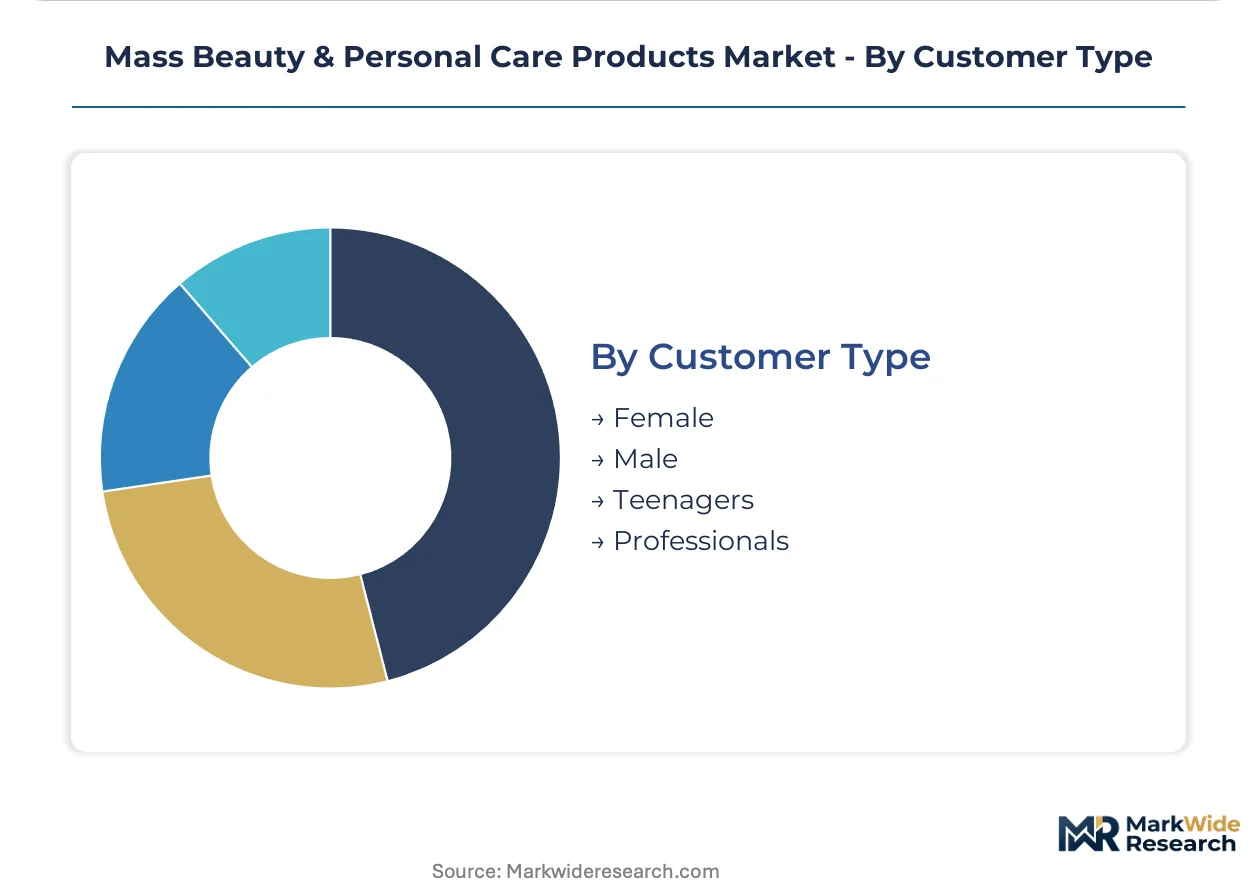
Customer Type:
Volume concentration maps to demographic penetration rates, with underserved segments offering expansion headroom.
- Female:Comprehensive category engagement across skincare, haircare, makeup, and fragrance. Established purchasing patterns with high trial frequency for innovation.
- Teenagers:Skincare-first routine adoption with social media-influenced brand discovery. China's tier-one cities concentrate early-adopter density.
- Male:Historically underpenetrated with accelerating grooming regimen formalization. Mid-range price tiers show strongest receptivity as category education expands.
- Professionals:Time-compressed consumption favoring multi-function products and subscription replenishment. India's metropolitan corridors concentrate white-collar demand density.
Female segment dominates current revenue; male segment shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong and Jiangsu provinces anchor high-throughput manufacturing clusters that narrow the production-scale-to-quality gap for mass-market formulations. Automated batch processes with embedded dermatological safety testing now export to pharmacy and supermarket networks across multiple continents.
China
Teenage and young-adult cohorts in Shanghai, Beijing, and Shenzhen drive skincare-first preventive regimens over reactive treatment models. SAMR enforces GB standards for cosmetic ingredient thresholds that diverge from Western protocols, forcing parallel documentation cycles. Guangdong province concentrates automated manufacturing clusters with high-throughput batch processes serving domestic e-commerce subscription channels.
United States
FDA cosmetic labeling requirements elevate compliance costs for cross-border suppliers entering pharmacy and supermarket distribution. State-level ingredient disclosure laws in California and New York threaten legacy product lines while opening avenues for clean-chemistry innovators. The Northeast Corridor and California absorb premium-tier volume through direct-to-consumer platforms with algorithm-driven personalization.
Germany
ECHA clean-label chemistry mandates through REACH framework create first-mover advantage for compliant suppliers accessing European pharmacy channels. The EU Green Deal accelerates PFAS phase-out timelines, compressing R&D timelines for waterproofing and texture-enhancing substitutions. North Rhine-Westphalia anchors formulation science clusters serving mass-market haircare and skincare lines.
India
Metropolitan corridors in Mumbai, Delhi, and Bangalore absorb mid-range price tier volume as per-capita spending constraints ease. BIS standards for cosmetic safety testing diverge from FDA and REACH protocols, extending product launch windows by quarters. Maharashtra and Karnataka concentrate white-collar professional demand for time-compressed multi-function product regimens.
Brazil
ANVISA regulatory elevation for cosmetic ingredient transparency reshapes formulation standards for mass-market price tiers. São Paulo and Rio de Janeiro concentrate demand for budget and mid-range skincare through supermarket and pharmacy distribution networks. Southeast region manufacturing clusters serve Latin American export markets with streamlined preservative efficacy testing.
Mass Beauty & Personal Care Products Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying active ingredient concentrates and surfactant bases. The supplier base organizes into three strategic archetypes: multinational conglomerates with dermatological research pipelines, mid-scale regional formulators with sustainability-certified sourcing programs, and specialized contract manufacturers serving private-label supermarket channels. Dominant competitive moves include portfolio diversification into clean-label chemistry and strategic partnerships with automated manufacturing clusters in Guangdong and Jiangsu.
Among Japanese-origin platform players, Shiseido occupies a position exemplifying dermatological research pipeline integration across skincare and haircare lines. L'Oreal and Unilever anchor the multinational conglomerate tier, with the former representing high-velocity innovation across mass-market price tiers and the latter exemplifying sustainability-certified sourcing programs that resonate with environmentally conscious buyer segments. These three entities collectively illustrate the competitive tension between research-driven formulation science and supply chain transparency credentials.
| Leading Market Players |
|---|
| Shiseido |
| Estee Lauder |
| L'Oreal |
| Henkel |
| Colgate-Palmolive |
| Procter & Gamble |
| Beiersdorf |
| Revlon |
| Unilever |
| Others |
Value Network & Pricing Analysis
Guangdong and Jiangsu province manufacturing clusters concentrate surfactant and emollient production capacity, anchoring cost structures that cascade through budget and mid-range price tiers while premium formulations capture margin pools through dermatological certification premiums.
Pricing Analysis
REACH chemicals framework dictates the pricing tier structure across European pharmacy channels, with compliance costs stratifying products across premium, standard, and economy levels based on ECHA documentation depth. Price differentiation rests on GB standard adherence for China entry versus FDA cosmetic labeling for US supermarket placement. Pricing pressure stems from petrochemical derivative volatility compressing mass-market margins. Budget tier buyers exhibit highest price sensitivity; premium segment purchasers demonstrate reduced elasticity around sustainability certifications.
Supply Chain Analysis
Cosmax, Intercos, and Kolmar Korea hold contract-manufacturing capacity for high-throughput batch processes serving private-label supermarket and pharmacy channels. Raw material dependencies center on palm-derived surfactants, synthetic emollients, and preservative systems sourced from Malaysia, Indonesia, and Germany. Single-source vulnerability concentrates in specialized active ingredient concentrates. Distribution runs through e-commerce direct-to-consumer platforms, supermarket retail networks, and pharmacy chains with divergent margin retention profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mass beauty and personal care products are entering a cyclical recovery phase as teenage skincare-first regimen adoption normalizes post-pandemic behavioral shifts, with preventive product cycles replacing reactive treatment purchasing patterns.
For Market Incumbents: Build regulatory compliance moats through parallel GB-REACH-FDA documentation teams that compress cross-border launch windows. Anchor volume leadership by securing shelf-space negotiations at supermarket chains while deploying algorithm-driven personalization engines for e-commerce subscription retention. Threats include clean-chemistry talent scarcity elevating R&D compensation costs.
For New Entrants and Emerging Players: Build out white-space positions in India's secondary cities beyond Mumbai and Delhi where mid-range price tier penetration remains underdeveloped. Target male grooming regimen formalization through multi-function product positioning. Deploy direct-to-consumer platforms with dermatological credibility signaling to bypass traditional pharmacy distribution gatekeepers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional formulators possessing sustainability-certified sourcing programs but limited cross-border regulatory infrastructure. Five-to-ten year viability favors platforms with automated manufacturing integration in Guangdong or Jiangsu. Watch PFAS substitution timelines as inflection signal for clean-chemistry innovators versus legacy portfolio write-downs.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Program | ECHA REACH compliance opens European pharmacy channel access ahead of enforcement deadlines. |
| Direct-to-Consumer Platform Launch | Algorithm-driven personalization captures China's tier-one city subscription replenishment demand. |
| Automated Manufacturing Cluster Partnership | Guangdong province integration narrows production-scale-to-quality gap for mass-market tiers. |
| Sustainability Certification Investment | Supply chain transparency credentials reduce price elasticity among environmentally conscious buyers. |
| India Metropolitan Corridor Expansion | Maharashtra and Karnataka white-collar demand absorbs mid-range volume as per-capita spending eases. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings. Conversations with brand managers, category buyers at retailers, channel sales heads, and supply planners inform demand-side dynamics. Secondary sources include Nielsen retail audit data, customs records, ECHA substance registrations, FDA cosmetic labeling databases, and SAMR GB standard publications. Bottom-up SKU-level analysis triangulates against top-down market sizing across product type, distribution channel, price tier, and customer type dimensions.
Calibration against historical volume trajectories and regulatory enforcement timelines shaped the analytical framework throughout the forecast period. Segmentation modeling incorporated product type, distribution channel, price tier, and customer type with regional regulatory cluster overlays. CAGRs were derived from regression analysis of pricing elasticity and volume penetration rates. Forecast inputs included clean-label chemistry adoption curves and e-commerce logistics infrastructure buildout in China's tier-one cities and India's metropolitan corridors.
Stress conditions across petrochemical feedstock volatility, PFAS phase-out acceleration, and cross-border compliance timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and consumer regimen persistence. Quarterly review of SAMR GB standard amendments, ECHA substance restriction proposals, and India BIS cosmetic safety testing updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
South America E-Commerce Skin Care Products Market
Beauty & Personal Care
Europe Hair Styling Products Market
Beauty & Personal Care
South America Deodorants Market
Beauty & Personal Care
North America Cosmetics Market
Beauty & Personal Care
Nail Polish Remover Market
Beauty & Personal Care
Powdered Hand Soap Market
Beauty & Personal Care
India Herbal Shampoo Market
Beauty & Personal Care
Cosmetic Oil Market
Beauty & Personal Care
US Personal Care Contract Manufacturing Market
Beauty & Personal Care
Cosmetics Face Serum Market
Beauty & Personal Care
Hand Soap in Retail Market
Beauty & Personal Care
Global Personal Care Market
Beauty & Personal Care
Nail Art Tools and Accessories Market
Beauty & Personal Care
North America Beauty Devices Market
Beauty & Personal Care
Beauty Products Market
Beauty & Personal Care
Global Bath Salts Market