
 North America Cosmetics Market | 2026-2036
North America Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cosmetics Market Insights
Cosmetic chemist and formulation scientist talent shortages across the United States and Canada is reorganizing how brands build product pipelines and manage quality assurance. L'Oréal S.A. leverages its dedicated North American R&D campus in New Jersey to sustain innovation velocity despite tight labor pools. The Estée Lauder Companies Inc. anchors its prestige portfolio through controlled distribution in high-traffic department stores and proprietary online channels. Procter & Gamble competes at mass-market scale with streamlined supply chains that offset premium-brand agility advantages.
Cosmetics encompass chemically formulated preparations applied to the human body for cleansing, beautifying, promoting attractiveness, or altering appearance, typically containing emulsifiers, active ingredients, preservatives, and fragrance compounds manufactured through batch processing, homogenization, and stability testing protocols. Skincare commands the largest value share within product type segmentation, driven by clinical-positioned serums and sun care with repeat-purchase economics. Online retail is expanding fastest among distribution channels, though specialty stores retain margin concentration through personalized consultation services and exclusive brand access. The unisex customer segment is gaining traction as gender-neutral branding and inclusive shade ranges reshape traditional demographic targeting.
FDA oversight through MoCRA mandates adverse event reporting, good manufacturing practice compliance, and fragrance allergen labeling that elevates compliance costs for smaller entrants. Health Canada and the EPA impose parallel restrictions on per- and polyfluoroalkyl substances (PFAS) and microplastic ingredients, forcing cross-border formulation standardization. California's Proposition 65 and Safer Consumer Products regulations add state-level disclosure burdens that de facto become national benchmarks. Stakeholders must monitor evolving state patchworks and ingredient ban momentum to determine whether centralized reformulation or market-specific SKU strategies deliver superior risk-adjusted returns.
Market Dynamics
The FDA's Modernization of Cosmetics Regulation Act (MoCRA) is compressing formulation-to-shelf timelines while elevating facility compliance burdens across the United States, Canada, and Mexico. This regulatory density is forcing brands to choose between centralized reformulation strategies or market-specific SKU proliferation.
Growth Catalysts
- Clean beauty mandates:California's Proposition 65 and Safer Consumer Products regulations are accelerating ingredient transparency investments. Brands reformulating to exclude PFAS and microplastics capture premium positioning in California, New York, and Ontario metropolitan corridors.
- Gen Z purchasing power:Younger demographics in the United States and Canada demonstrate higher willingness-to-pay for clinical-positioned serums and sun care with verified sustainability credentials.
- Biotechnology adoption:Fermentation-derived actives and lab-grown collagen are displacing traditional petrochemical feedstocks in prestige skincare pipelines.
Market Restraints
- Cosmetic chemist scarcity:Talent shortages across the United States and Canada extend product development cycles and inflate R&D compensation costs.
- Cross-border regulatory friction:Divergent PFAS restrictions between Health Canada, the EPA, and state-level California agencies force redundant safety testing.
- Fragrance allergen compliance:MoCRA's expanded disclosure requirements for fragrance compounds increase labeling complexity and litigation exposure for smaller entrants.
Strategic Opportunities
- Unisex segment expansion:Gender-neutral branding and inclusive shade ranges in the United States are capturing consumers previously underserved by binary product lines.
- Mexico manufacturing:Maquiladora zones near the United States border offer tariff-advantaged production capacity for brands serving both North American markets.
- Online retail infrastructure:Direct-to-consumer channels bypass specialty store margin extraction while capturing first-party consumer data for personalization.
Industry Challenges
- Formulation scientist recruitment:Competition for qualified cosmetic chemists between L'Oréal's New Jersey R&D campus and emerging indie brands compresses available talent pools.
- MoCRA facility registration:Mandatory FDA registration and good manufacturing practice compliance impose capital requirements that disadvantage smaller formulators.
- Legacy system integration:Adverse event reporting systems must interface with existing ERP infrastructure, creating implementation delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cosmetics Market |
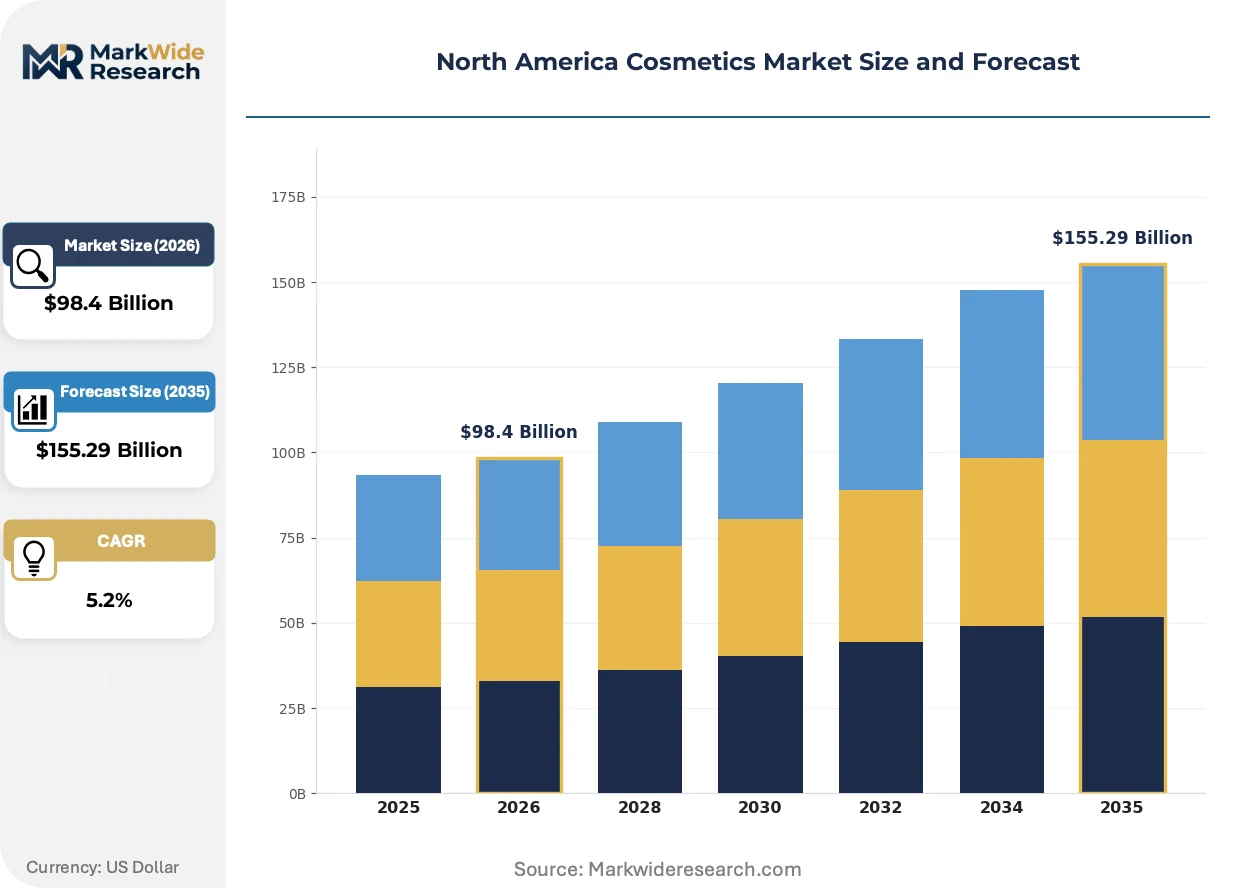
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $155.29 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Makeup, Fragrance, Haircare Distribution Channel: Online Retail, Department Stores, Specialty Stores, Drugstores Customer Type: Professional, Unisex, Female, Male Price Tier: Luxury, Mass, Premium, Budget |
| Companies Covered | L'Oréal S.A., The Estée Lauder Companies Inc., Procter & Gamble, Unilever, Johnson & Johnson, Shiseido, Beiersdorf AG, Coty Inc., Kao Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cosmetics Market Trends and Innovations
Biotechnology and precision fermentation are rewriting ingredient sourcing economics while regulatory disclosure mandates reshape competitive differentiation. Three developments warrant particular attention.
Precision fermentation platforms are miniaturizing active ingredient production from industrial-scale bioreactors to modular, distributed manufacturing units. Indie brands in Brooklyn and Austin are adopting these systems to produce customized peptides and ceramides on-demand. This distributed model is compressing minimum order quantities and enabling hyper-local supply chains that bypass traditional bulk chemical distributors.
Health Canada's parallel restrictions on per- and polyfluoroalkyl substances are forcing alignment with EPA and California regulatory timelines. Cosmetic manufacturers must now maintain three-tier compliance documentation for cross-border product lines. Prestige skincare segments absorb these costs through pricing power while mass-market brands consolidate formulations to single North America-wide specifications.
Specialty store consultation services are fragmenting as TikTok-driven discovery displaces in-person shade-matching and skin-type diagnostics. Ulta and Sephora are responding with virtual try-on tools and AI-powered recommendation engines. This channel compression is most visible in California and New York, where digital-native consumers prioritize algorithmic curation over associate expertise.
North America Cosmetics Market Segmentation
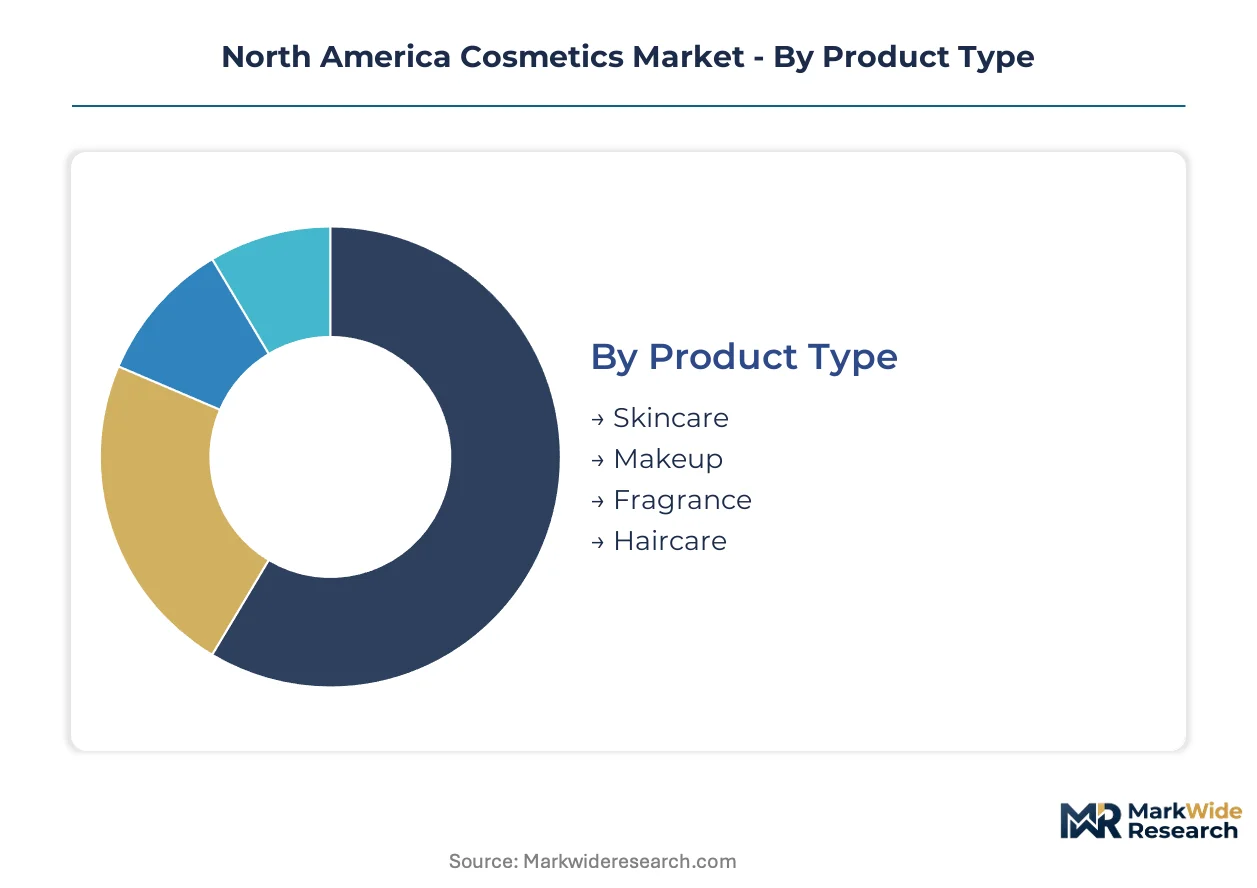
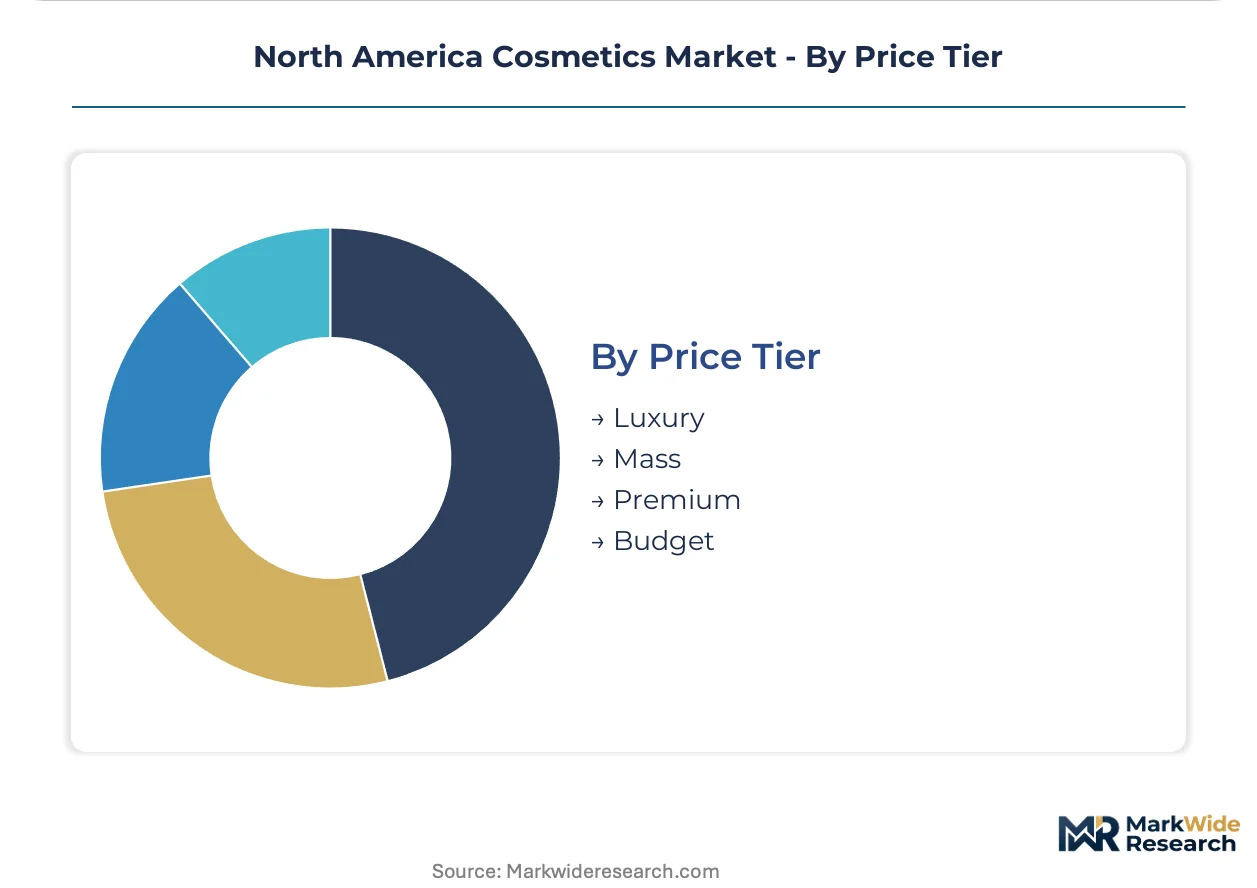
Segmentation in North American cosmetics reflects divergent compliance burdens and channel economics. FDA MoCRA disclosure rules and state-level Prop 65 mandates reshape how brands configure product portfolios across price tiers and customer profiles.
Product Type:
FDA MoCRA mandates on fragrance allergen labeling and facility registration hit formulation-heavy categories hardest.
- Skincare:Emulsions, serums, and sun care formulations carry the highest active ingredient densities. California, New York, and Ontario metropolitan corridors concentrate demand for clinical-positioned products with repeat-purchase economics.
- Makeup:Pigment suspension systems and long-wear polymers dominate formulation complexity. Shade range inclusivity and gender-neutral branding are reshaping SKU proliferation strategies in the United States and Canada.
- Fragrance:Volatile organic compound regulations and expanded allergen disclosure requirements elevate compliance costs.
- Haircare:Silicones, conditioning agents, and color-protecting chemistries face parallel PFAS scrutiny from Health Canada and the EPA.
Skincare handles the majority of throughput; Makeup is expanding most quickly on share.
Distribution Channel:
Margin extraction patterns separate digital-native discovery from consultation-dependent conversion.
- Online Retail:Direct-to-consumer infrastructure captures first-party data and bypasses specialty store margin extraction. TikTok-driven discovery is compressing traditional awareness-to-purchase funnels in California and New York.
- Specialty Stores:Sephora and Ulta anchor prestige distribution through exclusive brand access and virtual try-on tools. Personalized consultation services retain margin concentration despite digital channel encroachment.
- Department Stores:Controlled distribution partnerships sustain luxury positioning but face foot traffic erosion.
- Drugstores:Mass-market scale competes on streamlined supply chains and impulse purchase placement.
Online Retail captures volume growth fastest; Specialty Stores retain the highest margin per transaction.
Customer Type:
Demographic targeting is fragmenting as gender-neutral positioning captures previously underserved demand pockets.
- Unisex:Gender-neutral branding and inclusive shade ranges are displacing binary product lines. Brooklyn and Austin indie brands lead formulation innovation for this segment.
- Female:Traditional core demand concentrates in prestige skincare and color cosmetics across metropolitan corridors.
- Male:Grooming and skincare adoption is accelerating, though from a smaller base than unisex expansion.
- Professional:Salon and spa channels require bulk formats and wholesale pricing structures.
Female remains the volume anchor; Unisex climbs the fastest on share expansion.
Price Tier:
R&D investment recovery and ingredient transparency costs stratify competitive positioning.
- Luxury:Biotechnology-derived actives and fermentation platforms justify premium positioning. L'Oréal's New Jersey R&D campus and Estée Lauder's controlled distribution sustain innovation velocity.
- Premium:Clean beauty credentials and verified sustainability claims command pricing power in California and Ontario.
- Mass:Procter & Gamble's scale economies offset agility disadvantages through consolidated North America-wide formulations.
- Budget:Private label and value positioning face compressed margins from compliance cost absorption.
Mass handles the majority of unit throughput; Premium gains share fastest on clean beauty conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA MoCRA mandates anchor regulatory complexity across North America, forcing brands to navigate divergent state-level disclosure rules while maintaining cross-border supply chain continuity. Metropolitan corridors in California, New York, and Ontario concentrate prestige demand, while Mexico's maquiladora zones offer tariff-advantaged manufacturing capacity.
United States
California's Proposition 65 and Safer Consumer Products regulations drive ingredient transparency investments among millennial and Gen Z consumers. The FDA's adverse event reporting and facility registration requirements compress formulation-to-shelf timelines. Brooklyn and Austin indie brands deploy precision fermentation platforms for hyper-local peptide and ceramide production.
Canada
Health Canada PFAS restrictions align with EPA timelines, forcing three-tier compliance documentation for cross-border product lines. Ontario metropolitan corridors concentrate demand for clinical-positioned serums with verified sustainability credentials. Toronto anchors prestige distribution partnerships for controlled luxury brand access.
Mexico
Maquiladora zones near the United States border offer tariff-advantaged production capacity for brands serving both North American markets. ANVISA-aligned regulatory pathways streamline cross-border facility registrations. Mexico City Metro anchors emerging demand for gender-neutral branding and inclusive shade ranges.
California
State-level disclosure burdens under Proposition 65 de facto become national benchmarks for ingredient transparency. Los Angeles and San Francisco metropolitan corridors concentrate clean beauty adoption and biotechnology-derived active ingredient demand. Precision fermentation startups miniaturize bioreactor operations for distributed manufacturing.
New York
TikTok-driven discovery compresses traditional awareness-to-purchase funnels in metropolitan retail corridors. State-level fragrance allergen labeling requirements add compliance layers to MoCRA mandates. Manhattan anchors prestige department store distribution and proprietary online channel infrastructure for luxury positioning.
North America Cosmetics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America cosmetics market. Consolidated multinational conglomerates with dedicated R&D campuses compete against agile indie brands leveraging distributed fermentation platforms. Three strategic archetypes dominate: biotechnology-forward innovators, mass-market scale operators, and clean beauty specialists. M&A activity concentrates on fermentation technology acquisitions, while geographic expansion targets Mexico maquiladora capacity.
Within the multinational tier, L'Oréal S.A. and The Estée Lauder Companies Inc. occupy positions as archetypal R&D-intensive players with controlled distribution strategies. Procter & Gamble exemplifies the scale-driven archetype competing through streamlined supply chains. These three entities represent distinct competitive positioning vectors: biotechnology investment, prestige channel control, and mass-market operational efficiency.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| The Estée Lauder Companies Inc. |
| Procter & Gamble |
| Unilever |
| Johnson & Johnson |
| Shiseido |
| Beiersdorf AG |
| Coty Inc. |
| Kao Corporation |
| Others |
Pricing and Supply Chain Analysis
Ninety-day formulation-to-shelf timelines under FDA MoCRA compress inventory windows while amplifying pricing power for brands with captive R&D infrastructure. This lead-time compression concentrates margin recovery among multinational conglomerates with integrated New Jersey and Ontario facilities, while indie formulators absorb expedited compliance costs through premium positioning.
Pricing Analysis
California-to-Ontario price spreads for clinical-positioned serums reflect divergent compliance cost absorption and channel control intensity. Three-tier pricing structure across premium, standard, and economy levels stratifies by biotechnology-derived active density and verified sustainability certification tier. Pricing pressure stems from talent scarcity inflating cosmetic chemist compensation at formulation-heavy entrants. Mass-market buyers exhibit highest price sensitivity, while prestige skincare purchasers prioritize ingredient transparency over unit economics.
Supply Chain Analysis
Port congestion at Los Angeles-Long Beach and container availability constraints on Asia-Pacific trade lanes elevate inbound logistics costs for fermentation-derived actives and specialty chemical feedstocks. Supply concentrates in China for peptide precursors, South Korea for bioreactor equipment, and New Jersey for formulation finishing. Raw material dependencies span palm-derived emulsifiers, petrochemical-based polymers, and lab-grown collagen substrates. Single-source vulnerability runs through precision fermentation platform providers. Distribution runs through controlled specialty retail partnerships and direct-to-consumer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. FDA facility registration and MoCRA compliance documentation create switching costs that lock in incumbent advantages while raising entrant capital thresholds.
For Market Incumbents: Shield formulation pipelines by deepening backward integration into precision fermentation capacity in New Jersey and Ontario corridors. Acquire boutique biotechnology platforms before fermentation-derived actives commoditize. MoCRA's adverse event reporting infrastructure advantages scale operators with existing ERP integration.
For New Entrants and Emerging Players: Anchor in Mexico maquiladora zones for tariff-advantaged production serving cross-border demand. Target unisex segment white space with gender-neutral branding and inclusive shade ranges previously underserved by binary product lines. Deploy TikTok-native discovery as primary go-to-market channel, bypassing specialty store margin extraction.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because fermentation technology acquisitions and regulatory compliance scale advantages favor concentrated ownership. Target acquisition archetype: mid-cap clean beauty specialists with California Prop 65-compliant formulations and established direct-to-consumer infrastructure. Monitor Health Canada-EPA PFAS alignment timelines as inflection signal for cross-border formulation standardization urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Buildout | Biotechnology-derived actives displace petrochemical feedstocks in L'Oréal's New Jersey R&D pipeline. |
| MoCRA Compliance Infrastructure Investment | FDA facility registration and adverse event reporting systems lock in incumbent scale advantages. |
| Mexico Maquiladora Manufacturing Expansion | Tariff-advantaged production capacity captures cross-border United States and Canada demand. |
| Unisex Product Line Extension | Gender-neutral branding captures Brooklyn and Austin consumer segments previously underserved. |
| Direct-to-Consumer Channel Development | First-party data capture enables personalization while bypassing Sephora and Ulta margin extraction. |
Research Methodology
The analysis maps skincare, makeup, fragrance, and haircare segments, each validated through cosmetic chemists, brand formulation directors, specialty retail buyers, and regulatory affairs specialists. Primary interviews with R&D executives at multinational conglomerates and indie brand founders combined with secondary validation from FDA MoCRA guidance documents, Health Canada PFAS restriction notices, California Proposition 65 regulatory updates, and SEC 10-K filings from listed cosmetics entities. Bottom-up SKU-level modeling and top-down market sizing triangulated through Nielsen retail audit data and customs import records.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, customer type, and price tier, with biotechnology adoption intensity as an industry-specific overlay. CAGRs derived from historical trajectory analysis and regulatory impact elasticity assumptions, incorporating cosmetic chemist wage inflation and clean beauty premium capture rates as forecast inputs.
Underlying assumptions cover MoCRA implementation timelines, Health Canada-EPA regulatory alignment, and Gen Z purchasing power maturation, with deviation risk concentrated in state-level ingredient ban momentum and precision fermentation platform commoditization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Asia Pacific Beauty Fridges Market
Beauty & Personal Care
Luxury Bath and Body Products Market
Beauty & Personal Care
Global Heated Eyelash Curlers Market
Beauty & Personal Care
Europe Beauty and Personal Care Products Market
Beauty & Personal Care
Middle East Herbal Shampoo Market
Beauty & Personal Care
Oil Control Shampoo Market
Beauty & Personal Care
Advanced Night Repair Serum Market
Beauty & Personal Care
Deodorant Wipes Market
Beauty & Personal Care
US Skincare Market
Beauty & Personal Care
Kids Shampoo Market
Beauty & Personal Care
Global Bath Bomb Market
Beauty & Personal Care
US Sexual Wellness Market
Beauty & Personal Care
Anti-Aging Cosmetics Market
Beauty & Personal Care
Beauty Products Market
Beauty & Personal Care
Natural Cosmetics Market
Beauty & Personal Care
Anti-Dandruff Shampoo Market