
 South America Deodorants Market | 2026-2036
South America Deodorants Market Size, Share, and Industry Trends Forecast 2026-2036
South America Deodorants Market Analytics
Subscription-based deodorant replenishment services is repositioning how brands build recurring revenue and customer lock-in across South America. Unilever PLC leverages its direct-to-consumer platforms to sustain repeat purchase rates in Brazil's major cities. Natura & Co Holding SA anchors its market presence through consultant-driven distribution networks that dominate door-to-door channels. Grupo Boticário competes aggressively via pharmacy-exclusive lines that control premium shelf positioning.
Deodorants are topical personal care formulations containing antimicrobial agents, fragrance compounds, and moisture-absorbing bases designed to inhibit bacterial growth and mask body odor; products typically specify aluminum salt concentrations or natural mineral alternatives as active ingredients. Sprays lead volume sales across mass-market tiers due to convenience and lower per-unit pricing, while natural formulation segments capture expanding margin pools as ingredient transparency becomes a purchase determinant. Roll-ons retain strength in pharmacy channels where dermatological positioning drives premium pricing, and online retail growth for unisex variants signals shifting household purchasing patterns.
ANVISA governs cosmetic ingredient safety and labeling requirements in Brazil, while Argentina's national food and drug administration enforces parallel standards that affect cross-border product registration timelines. REACH-aligned frameworks in Chile and Peru are elevating documentation burdens for imported formulations containing synthetic actives. Stakeholders must monitor evolving preservative restrictions and decide whether to reformulate regionally or maintain separate product portfolios by country.
Market Dynamics
ANVISA's updated cosmetic safety protocols are rewriting formulation disclosure requirements across Brazil's deodorant supply base, forcing manufacturers to revalidate ingredient sourcing and accelerate transparency investments.
Growth Catalysts
- Urban young adult adoption:Brazil's metropolitan corridors are seeing concentrated demand from consumers aged 18-34 who prioritize daily personal care routines and premium product accessibility.
- REACH-aligned frameworks:Chile and Peru are elevating documentation standards for imported formulations, creating competitive moats for compliant domestic producers.
- Subscription replenishment services:Direct-to-consumer platforms are locking in recurring revenue streams through automated delivery models in São Paulo and Rio de Janeiro.
Market Restraints
- Aluminum salt input volatility:Synthetic active ingredient costs fluctuate with petrochemical feedstock prices, compressing margin pools for standard-tier producers.
- Cross-border registration friction:Argentina's national food and drug administration enforces parallel standards that extend product launch timelines by 8-14 months for regional exporters.
- Natural mineral substitute availability:Potassium alum and other plant-derived actives face supply concentration in Andean mining regions, limiting formulation flexibility.
Strategic Opportunities
- Pharmacy channel premium positioning:Dermatologist-endorsed roll-on formats command 40-60% price premiums in Brazil's southeastern corridor.
- Unisex variant expansion:Online retail growth for gender-neutral formulations signals household purchasing consolidation opportunities.
- Consultant-driven distribution:Door-to-door networks in secondary Brazilian cities remain underpenetrated relative to metropolitan saturation.
Industry Challenges
- Preservative reformulation complexity:ANVISA's evolving restrictions on parabens and phenoxyethanol demand accelerated R&D cycles without guaranteed regulatory clearance timelines.
- Legacy supply chain reconfiguration:Separate product portfolios by country require duplicated quality systems and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Deodorants Market |
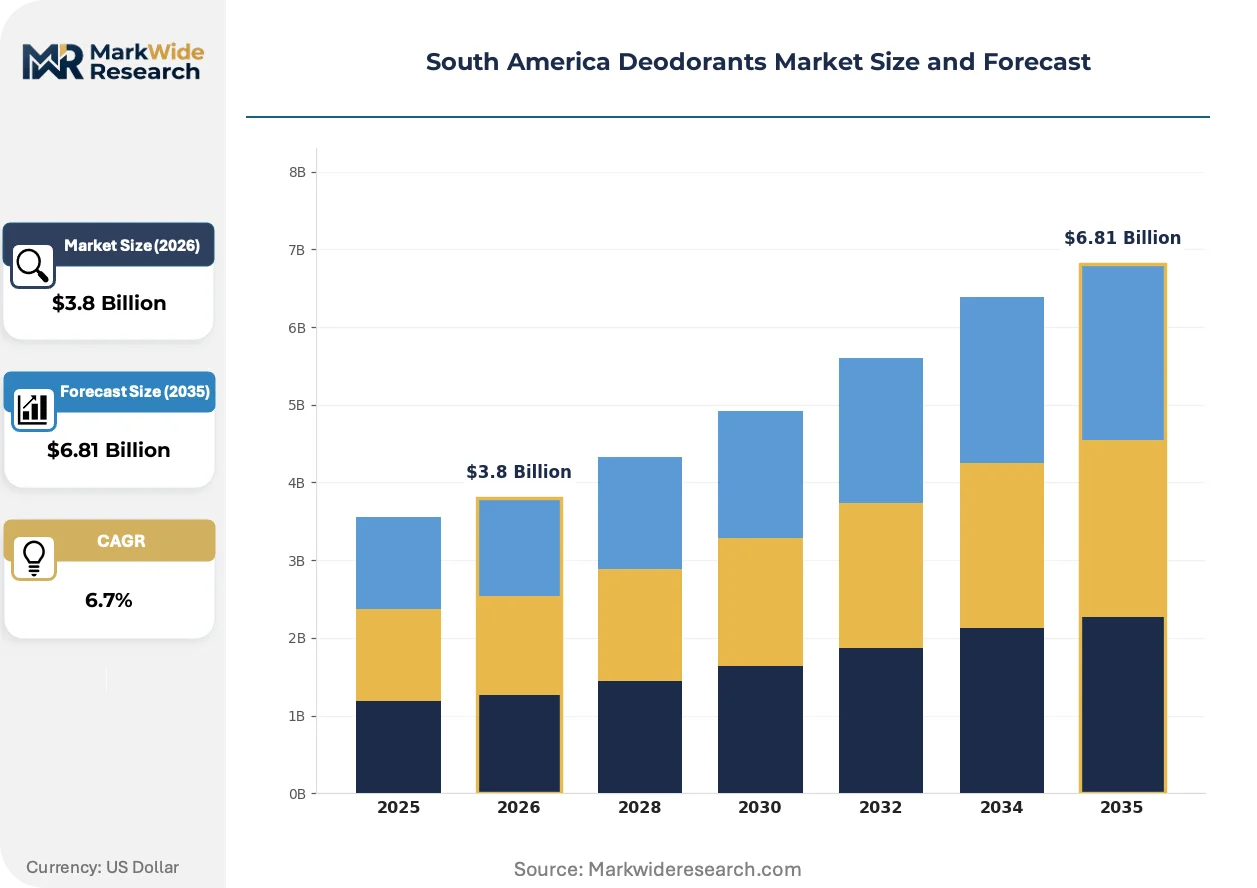
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roll-ons, Sprays, Sticks, Gels Formulation: Natural, Antiperspirant, Alcohol-Free, Scented End User: Men, Women, Unisex, Teens Sales Channel: Supermarkets, Online Retail, Specialty Stores, Pharmacies |
| Companies Covered | Unilever PLC, Procter & Gamble Company, Natura & Co Holding SA, Beiersdorf AG, L’Oréal SA, Grupo Boticário, Henkel AG and Co KGaA, Colgate-Palmolive Company, Avon Products, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Deodorants Market Evolving Landscape
Formulation transparency and channel digitization are converging to reshape competitive positioning across South America's deodorant landscape, with regulatory pressure and consumer scrutiny accelerating investment priorities.
Biodegradable fragrance encapsulation technology is rewriting scent delivery economics in spray formats. Brazilian mass-market manufacturers are piloting starch-based microspheres that release active compounds gradually. This innovation is compressing the cost gap between standard and extended-wear formulations.
ANVISA's updated cosmetic safety protocols mandate granular ingredient disclosure down to 0.01% concentration thresholds. Manufacturers must now submit complete supply chain documentation for antimicrobial agents. Brazil's pharmacy channel is responding fastest, leveraging dermatological credibility to justify premium pricing.
Household purchasing consolidation around unisex variants is fragmenting traditional gender-segmented shelf strategies. E-commerce platforms in São Paulo and Buenos Aires are displacing supermarket impulse purchases with subscription-driven replenishment. Brazil's urban corridor shows the clearest signal of this channel rotation.
South America Deodorants Market Segmentation
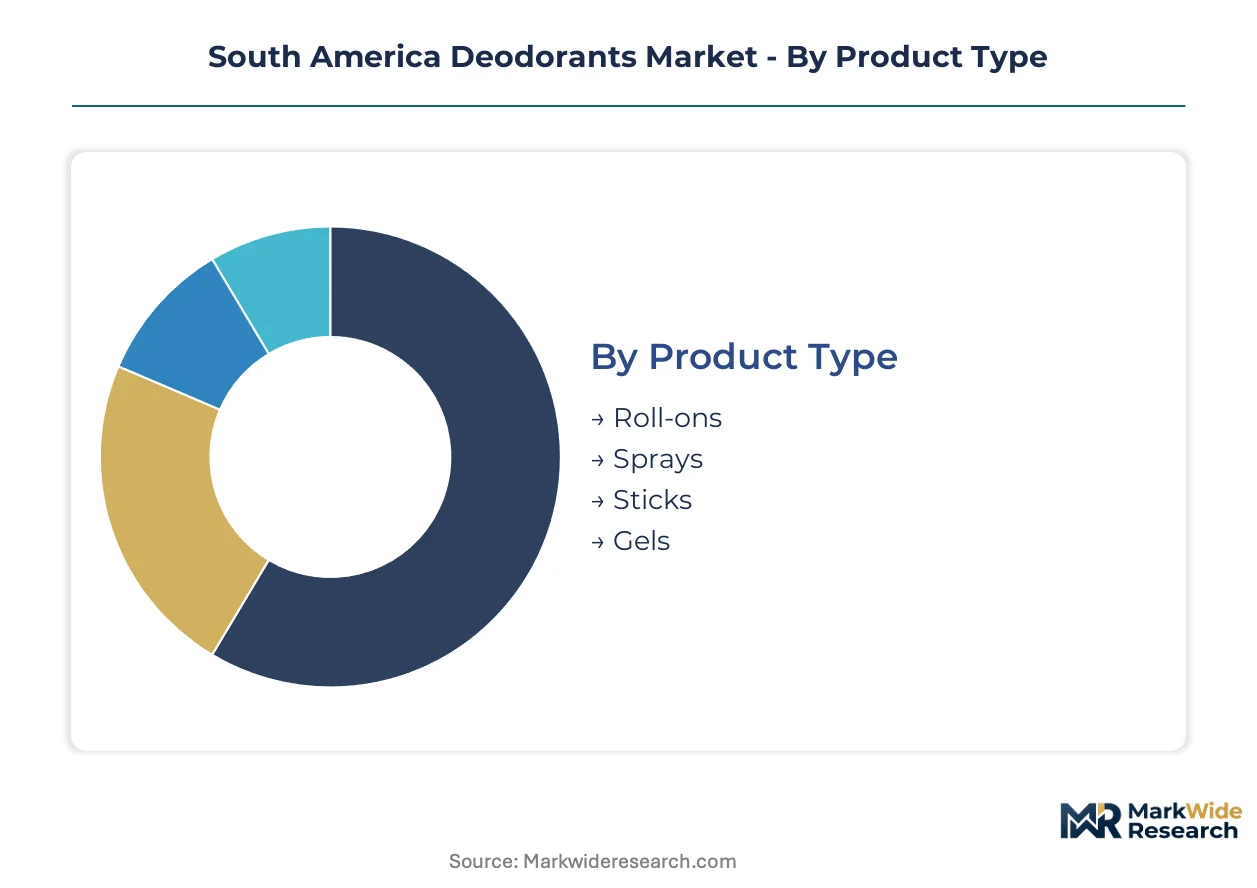
Deodorant purchasing in South America splits across four critical dimensions that determine margin capture and channel strategy. Product format dictates manufacturing infrastructure requirements while formulation type governs regulatory compliance burdens. End-user targeting shapes marketing spend allocation, and sales channel selection determines geographic reach and price realization.
Product Type:
Urban convenience preferences and pharmacy channel access drive format selection across Brazilian metropolitan corridors.
- Sprays:Aerosol and pump-dispensed formats dominate mass-market volume through lower per-unit pricing and rapid application. São Paulo's supermarket and convenience channels concentrate demand here, though ANVISA's propellant regulations are forcing reformulation investments.
- Roll-ons:Liquid formulations in ball-applicator packaging command dermatological credibility and premium shelf positioning. Brazil's southeastern pharmacy corridor shows concentrated adoption where clinical endorsement justifies 40-60% price premiums over spray alternatives.
- Sticks:Solid wax-based carriers deliver extended wear through slow-release active embedding. Secondary Brazilian cities show underpenetrated distribution relative to metropolitan saturation.
- Gels:Transparent quick-drying formulations target professional consumers seeking residue-free application. Argentina's urban centers demonstrate stronger per-capita uptake than Andean markets.
Volume sits with Sprays; growth tilts toward Roll-ons.
Formulation:
Ingredient transparency mandates from ANVISA and consumer scrutiny are restructuring R&D priorities and supply chain documentation.
- Natural:Mineral-based actives including potassium alum and plant-derived antimicrobials bypass synthetic chemical restrictions. Supply concentration in Andean mining regions limits formulation flexibility for Brazilian manufacturers seeking regional sourcing.
- Antiperspirant:Aluminum salt formulations block sweat ducts through astringent action. Petrochemical feedstock volatility compresses margin pools for standard-tier producers dependent on synthetic active imports.
- Alcohol-Free:Glycol-based carriers replace ethanol to reduce skin irritation sensitivity. Pharmacy channels in Rio de Janeiro and Buenos Aires show disproportionate stocking rates for post-procedure and sensitive-skin positioning.
- Scented:Fragrance-forward formulations leverage biodegradable encapsulation technology for extended release. Starch-based microsphere pilots among Brazilian manufacturers are compressing cost gaps with standard wear formulations.
Antiperspirant captures current volume leadership; Natural formulations are climbing the fastest on transparency tailwinds.
End User:
Household purchasing consolidation and gender-neutral marketing are fragmenting traditional demographic segmentation.
- Women:Historically targeted through floral fragrance profiles and skincare-adjacent positioning. Brazil's consultant-driven door-to-door networks retain strength in this segment through personalized recommendation.
- Men:Sport and performance-oriented messaging dominates, though scent profiles are diversifying beyond traditional woody bases. São Paulo's young professional cohort shows rising experimentation with crossover unisex alternatives.
- Unisex:Gender-neutral formulations signal household purchasing consolidation as shared bathroom products replace individual allocations. E-commerce subscription models in Buenos Aires and São Paulo are displacing supermarket impulse segmentation.
- Teens:Entry-level pricing and social-media-influenced brand discovery characterize this cohort. Brazil's urban 18-24 demographic shows concentrated daily routine adoption driving trial-to-loyalty conversion.
Women retain volume dominance; Unisex is gaining share fastest on channel rotation and household consolidation.
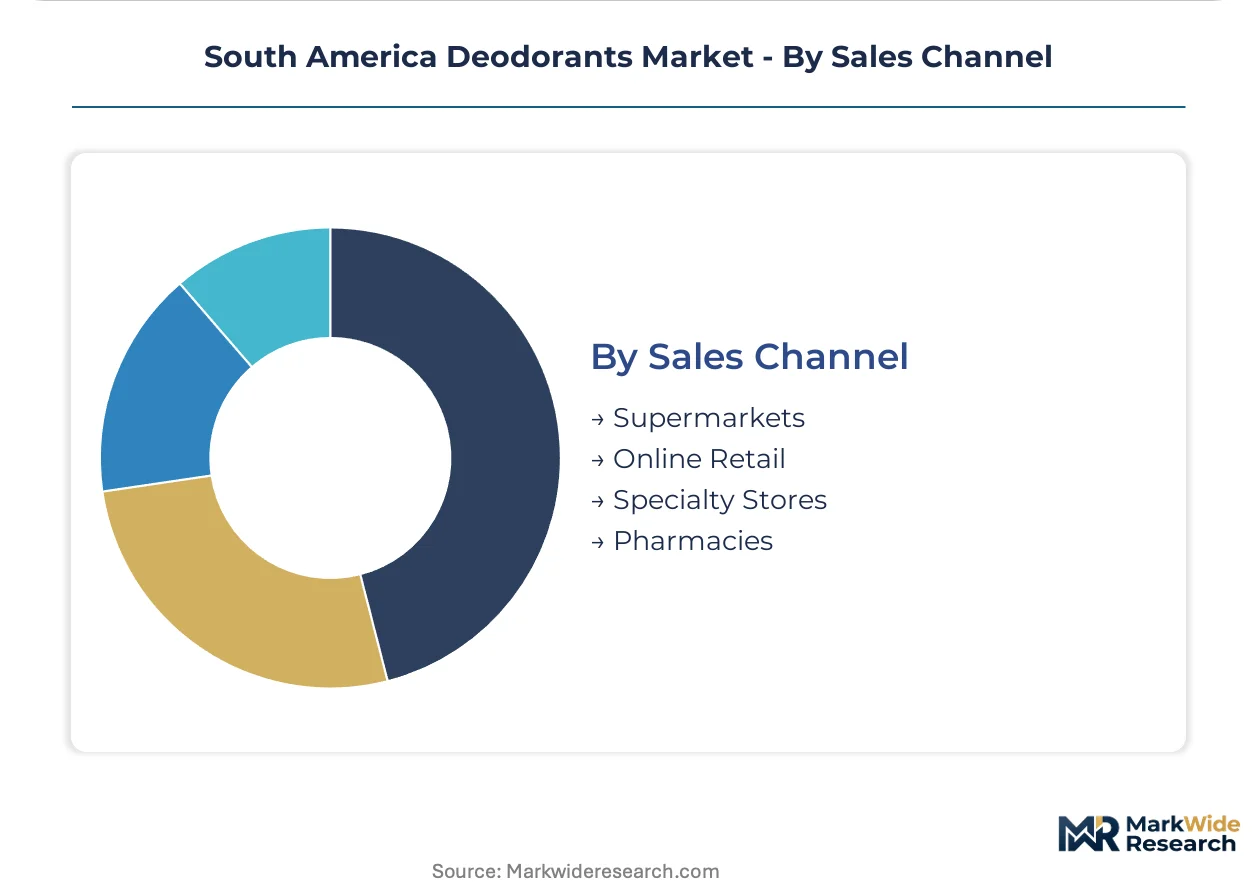
Sales Channel:
Digital platform penetration and pharmacy credentialing are redistributing margin capture across the value chain.
- Supermarkets:Mass-market volume concentration through impulse placement and promotional stacking. Brazil's southeastern metropolitan corridor shows clearest channel rotation toward digital alternatives among younger cohorts.
- Pharmacies:Dermatological endorsement and premium positioning control highest price realization. ANVISA's ingredient disclosure mandates are accelerating pharmacy channel response through pre-existing clinical credibility infrastructure.
- Online Retail:Subscription replenishment and unisex variant discovery are consolidating household purchasing. São Paulo and Rio de Janeiro show automated delivery model penetration exceeding secondary city availability.
- Specialty Stores:Curated natural and niche fragrance assortments target ingredient-conscious consumers. Argentina's cross-border registration friction limits imported specialty brand presence relative to domestic pharmacy alternatives.
Supermarkets hold installed volume base; Online Retail shows steepest expansion trajectory on subscription lock-in mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's metropolitan corridor anchors South American deodorant demand through concentrated young adult adoption and pharmacy channel density. Brazil's southeastern belt generates the majority of regional volume, with regulatory pressure from ANVISA reshaping formulation standards across neighboring markets.
Brazil
Urban consumers aged 18-34 in Rio de Janeiro and São Paulo drive daily personal care routine penetration. ANVISA mandates granular ingredient disclosure down to 0.01% concentration thresholds, forcing manufacturers to revalidate supply chain documentation. The southeastern pharmacy corridor shows concentrated adoption of dermatologist-endorsed roll-on formats commanding premium price realization.
Argentina
Buenos Aires households consolidate purchasing around unisex variants through e-commerce subscription models. The national food and drug administration enforces parallel cosmetic safety standards that extend product launch timelines by 8-14 months for regional exporters. Urban centers demonstrate stronger per-capita uptake of alcohol-free formulations than Andean markets.
Chile
REACH-aligned frameworks elevate documentation burdens for imported formulations containing synthetic actives. Santiago's professional consumer base favors transparent quick-drying gel formats for residue-free application. Domestic producers gain competitive moats through pre-established compliance infrastructure.
Peru
Andean mining regions concentrate supply of potassium alum and plant-derived actives for natural formulation segments. Lima's pharmacy channels respond fastest to regulatory transparency mandates through existing clinical credibility infrastructure. Secondary city distribution remains underpenetrated relative to metropolitan saturation.
Colombia
Bogotá's young professional cohort shows rising experimentation with crossover unisex alternatives beyond traditional gender-segmented positioning. National regulators monitor evolving preservative restrictions across the Andean community. Urban convenience preferences accelerate spray format adoption in mass-market tiers.
South America Deodorants Market Competitive Landscape
Capital-heavy producers with integrated manufacturing compete with asset-light brand architects licensing formulation technology. The vendor base clusters around three tiers: multinational FMCG conglomerates with direct-to-consumer platforms, domestic pharmacy-channel specialists leveraging dermatological credibility, and consultant-driven door-to-door networks dominating secondary city penetration. Strategic moves concentrate on subscription replenishment infrastructure and preservative reformulation R&D cycles.
Within the multinational tier, Unilever PLC and Procter & Gamble Company exemplify scale-driven platform operators. Natura & Co Holding SA anchors the consultant-driven archetype through Brazilian door-to-door networks. Grupo Boticário occupies a position as the pharmacy-channel specialist with premium shelf positioning control.
| Leading Market Players |
|---|
| Unilever PLC |
| Procter & Gamble Company |
| Natura & Co Holding SA |
| Beiersdorf AG |
| L'Oréal SA |
| Grupo Boticário |
| Henkel AG and Co KGaA |
| Colgate-Palmolive Company |
| Avon Products |
| Others |
Value Network & Pricing Analysis
ANVISA's preservative disclosure mandates gate qualified supply access and premium-tier pricing realization for deodorant manufacturers across Brazil's pharmaceutical corridor. Formulators meeting granular documentation thresholds command dermatological endorsement premiums while non-compliant producers face shelf exclusion from pharmacy channels.
Pricing Analysis
Clinical efficacy claims anchor value-based pricing for dermatologist-endorsed roll-on formats in Brazil's southeastern metropolitan markets. Three-tier pricing structure across premium dermatological, standard mass-market, and economy spray tiers reflects certification grade and channel positioning. Price differentiation stems from ANVISA compliance documentation depth and pharmacy channel exclusivity arrangements. Pricing pressure intensifies in standard-tier sprays as petrochemical feedstock volatility compresses aluminum salt input margins, while premium roll-on segments show lowest buyer price sensitivity due to clinical credibility premiums.
Supply Chain Analysis
Skilled formulation chemist availability constrains manufacturing scale-up in São Paulo and Rio de Janeiro production corridors. Active ingredient sourcing concentrates in Brazil's petrochemical hubs for synthetic antimicrobials and Andean mining regions for potassium alum mineral substitutes. Raw material dependencies include aluminum chloride feedstocks, fragrance compound imports, and starch-based biodegradable encapsulation materials. Supply chain risk centers on single-source vulnerability for Andean mineral actives subject to export licensing variability. Distribution runs through pharmacy wholesale networks in metropolitan corridors, consultant-driven door-to-door channels in secondary cities, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America deodorants market sits in a formulation technology transition as biodegradable fragrance encapsulation displaces conventional extended-wear chemistries. Starch-based microsphere delivery systems are rewriting cost economics for sustained-release positioning.
For Market Incumbents: Anchor pharmacy channel exclusivity through accelerated ANVISA documentation investments before preservative restrictions tighten further. Defend against subscription-platform disintermediation by locking automated replenishment contracts with São Paulo and Rio de Janeiro households. Prioritize backward integration into Andean mineral active sourcing to reduce potassium alum supply concentration risk.
For New Entrants and Emerging Players: Enter via underpenetrated secondary Brazilian cities where consultant-driven distribution networks retain door-to-door dominance. Target unisex variant white space in Buenos Aires e-commerce subscription channels where household purchasing consolidation accelerates. Pursue dermatological co-development partnerships with pharmacy chains seeking exclusive house-brand positioning.
For Investors and Strategic Acquirers: ANVISA clearance acceleration for preservative-free formulations is the leading indicator that natural-mineral positioning will capture expanding margin pools. Five-to-ten year viability favors domestic manufacturers with integrated compliance infrastructure over import-dependent brand licensors. Monitor Andean mining region export licensing policy shifts as the critical supply-side inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Preservative Reformulation R&D | ANVISA's evolving restrictions on parabens demand accelerated clearance timelines for compliant alternatives. |
| Pharmacy Channel Exclusivity | Dermatologist-endorsed roll-on formats in Brazil's southeastern corridor command 40-60% price premiums. |
| Subscription Platform Launch | Automated replenishment models in São Paulo and Rio de Janeiro lock recurring revenue and customer retention. |
| Andean Mineral Active Sourcing | Potassium alum supply concentration in mining regions creates backward integration opportunities for Brazilian formulators. |
| Unisex Variant Expansion | Gender-neutral formulations signal household purchasing consolidation in Buenos Aires and São Paulo e-commerce channels. |
Research Methodology
Trade customs databases, ANVISA regulatory filings, and pharmaceutical channel sales audits formed the secondary backbone for this analysis. Primary interviews with brand managers at multinational FMCG operators, category buyers at Brazilian pharmacy chains, supply planners at fragrance compound importers, and technical R&D directors at domestic manufacturers combined with secondary validation. Bottom-up and top-down triangulation reconciled formulation-level production estimates against channel shipment data.
Bottom-up modeling built country-level projections from product format, formulation type, end-user demographic, and sales channel segmentation across the analysis window. Top-down validation cross-checked aggregate figures against petrochemical feedstock consumption patterns and retail audit data. CAGRs derived from volume trajectory analysis incorporating urban young adult adoption curves, regulatory compliance cost pass-through assumptions, and subscription platform penetration rates.
Revisions become necessary when ANVISA implements unannounced preservative restrictions, Andean mineral export licensing shifts, or petrochemical feedstock price dislocations materialize. Forecasts reflect documented assumptions regarding regulatory clearance timelines and channel migration velocities. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Global Organic Personal Care and Cosmetic Products Market
Beauty & Personal Care
Mens Intimate Care Products Market
Beauty & Personal Care
India Cosmetics Products Market
Beauty & Personal Care
Cosmetic Oil Market
Beauty & Personal Care
Body Mist Market
Beauty & Personal Care
Europe Hair Conditioner Market
Beauty & Personal Care
Middle East and Africa Hair Styling Products Market
Beauty & Personal Care
Personal Care Shower and Bath Market
Beauty & Personal Care
Europe Lip Care Products Market
Beauty & Personal Care
South America Hair Styling Products Market
Beauty & Personal Care
Rice Shampoo Bar Market
Beauty & Personal Care
US Personal Care Products Market
Beauty & Personal Care
Asia Pacific Herbal Beauty Products Market
Beauty & Personal Care
Middle East Herbal Shampoo Market
Beauty & Personal Care
Natural Cosmetics Market
Beauty & Personal Care
Bath and Body Products Market