
 India Herbal Shampoo Market | 2026-2036
India Herbal Shampoo Market Size, Share, and Industry Trends Forecast 2026-2036
India Herbal Shampoo Market Foresight
The India herbal shampoo category is decoupling into two distinct tiers: premium formulations with certified organic credentials and mass-market sachet packs competing on unit economics. Dabur India Ltd. leverages its Ayurvedic heritage to anchor the premium shelf in modern trade formats. Patanjali Ayurved Ltd. competes through aggressive rural distribution and price positioning below multinational benchmarks. CavinKare Pvt. Ltd. dominates the South Indian market with regional language branding and deep kirana store penetration.
India herbal shampoo denotes a surfactant-based cleansing preparation incorporating botanical extracts such as saponin-rich shikakai, tannin-heavy amla, or azadirachtin-bearing neem as functional actives rather than mere fragrance additives, manufactured through cold-process maceration or supercritical CO2 extraction to preserve heat-sensitive phytochemicals, with primary purpose being scalp cleansing without synthetic silicone buildup. The moisturizing and anti-dandruff product types occupy the largest volume pools, while hair fall control commands disproportionate shelf space due to consumer anxiety positioning. Amla and neem ingredient segments sustain the strongest consumer recognition, though aloe vera formulations are gaining traction among professional end users seeking post-chemical treatment recovery solutions.
BIS mandatory certification and Ministry of AYUSH quality parameters govern ingredient authenticity claims, while FSSAI oversight on cosmetic safety standards shapes product testing protocols for manufacturers. The Drugs and Cosmetics Act provisions on misbranded Ayurvedic claims create compliance thresholds that filter out unorganized competitors. Stakeholders must monitor regulatory tightening on heavy metal limits in herbal extracts, as testing infrastructure expansion will likely reshape supplier qualification criteria across the value chain.
Market Dynamics
Certification requirements from the Ministry of AYUSH and BIS are compressing the supplier base, forcing unorganized manufacturers toward compliance investments while rewarding established players with authenticated ingredient sourcing.
Growth Catalysts
- Urban Millennial Demand:Metro city consumers in Mumbai and Bangalore prioritize chemical-free scalp care, pulling premium formulations into modern trade shelves.
- PLI Scheme Incentives:India's production-linked incentive scheme for personal care manufacturing reduces capital costs for domestic extraction equipment.
- AYUSH Export Protocols:Standardized quality parameters enable cross-border shipment of certified herbal actives to Middle Eastern markets.
Market Restraints
- Wild-Harvested Input Volatility:Shikakai and amla supply concentrates in Maharashtra's seasonal collection cycles, creating price spikes during monsoon disruptions.
- Heavy Metal Testing Costs:FSSAI-mandated screening for arsenic and lead in botanical extracts raises per-batch qualification expenses for small processors.
- Synthetic Substitute Pressure:Silicone-based conditioners from multinational brands undercut herbal positioning on immediate tactile performance.
Strategic Opportunities
- Tier-Two City Penetration:Organized retail expansion into Jaipur and Lucknow creates shelf space for mid-priced Ayurvedic variants.
- Post-Chemical Recovery Positioning:Aloe vera formulations target salon professionals seeking scalp rehabilitation after coloring treatments.
- Kirana Digital Integration:Direct-to-retailer apps bypass distributor margins in Tamil Nadu's dense grocery network.
Industry Challenges
- Phytochemistry Expertise Gap:Formulation chemists with dual competency in Ayurvedic texts and surfactant science command premium salaries that strain mid-tier R&D budgets.
- Cold-Process Capacity Constraints:Supercritical CO2 extraction equipment requires capital outlays that exceed typical family-owned manufacturer balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Herbal Shampoo Market |
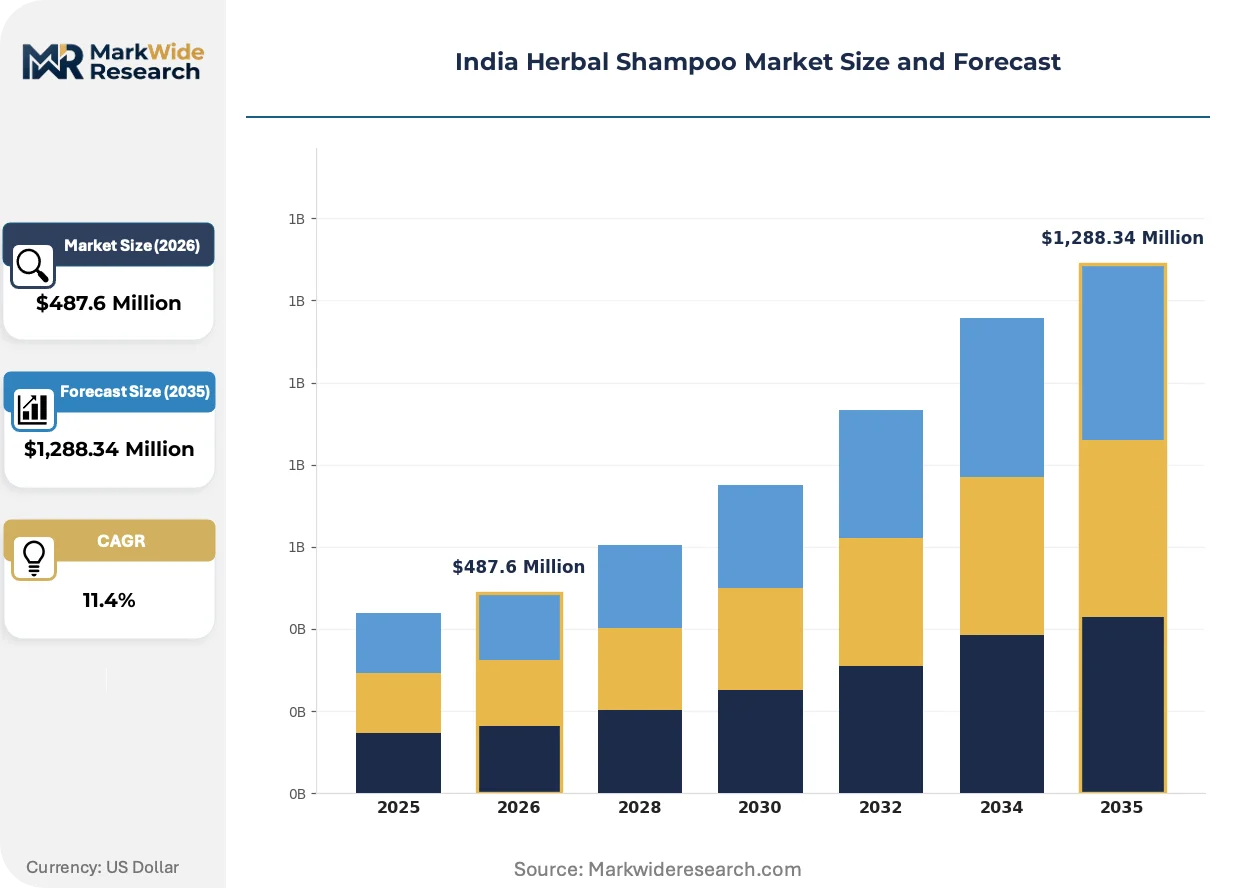
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizing, Anti-Dandruff, Strengthening, Hair Fall Control Ingredients: Amla, Neem, Aloe Vera, Hibiscus End User: Men, Women, Children, Professionals Packaging Type: Bottles, Pouches, Jars, Sachets |
| Companies Covered | Unilever PLC, Emami Ltd., Dabur India Ltd., Lotus Herbals Pvt. Ltd., CavinKare Pvt. Ltd., Patanjali Ayurved Ltd., Honasa Consumer Pvt. Ltd., Bio Veda Action Research Co., Himalaya Global Holdings Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Herbal Shampoo Market Shifts & Advancements
Ingredient authentication technologies and channel restructuring are reconfiguring how botanical efficacy reaches Indian consumers, compressing traditional supply hierarchies.
Supercritical CO2 extraction is expanding into mainstream herbal shampoo production as equipment costs decline. Mid-sized manufacturers in Karnataka adopt this solvent-free method to preserve heat-sensitive azadirachtin in neem extracts. The technology is expanding into previously price-locked segments, enabling certified organic claims at mass-market price points.
BIS mandatory certification for heavy metal limits in herbal cosmetics tightens supplier qualification criteria. Testing infrastructure expansion across state laboratories accelerates batch clearance timelines. Maharashtra-based formulators invest in in-house atomic absorption spectroscopy to preempt regulatory rejection.
Professional salon channels now drive ingredient transparency demands beyond retail consumers. Stylists in Bangalore and Chennai request complete botanical sourcing documentation before shelf placement. This behavior concentrates premium volume in South Indian metros where technical training institutions embed Ayurvedic trichology modules.
India Herbal Shampoo Market Segmentation
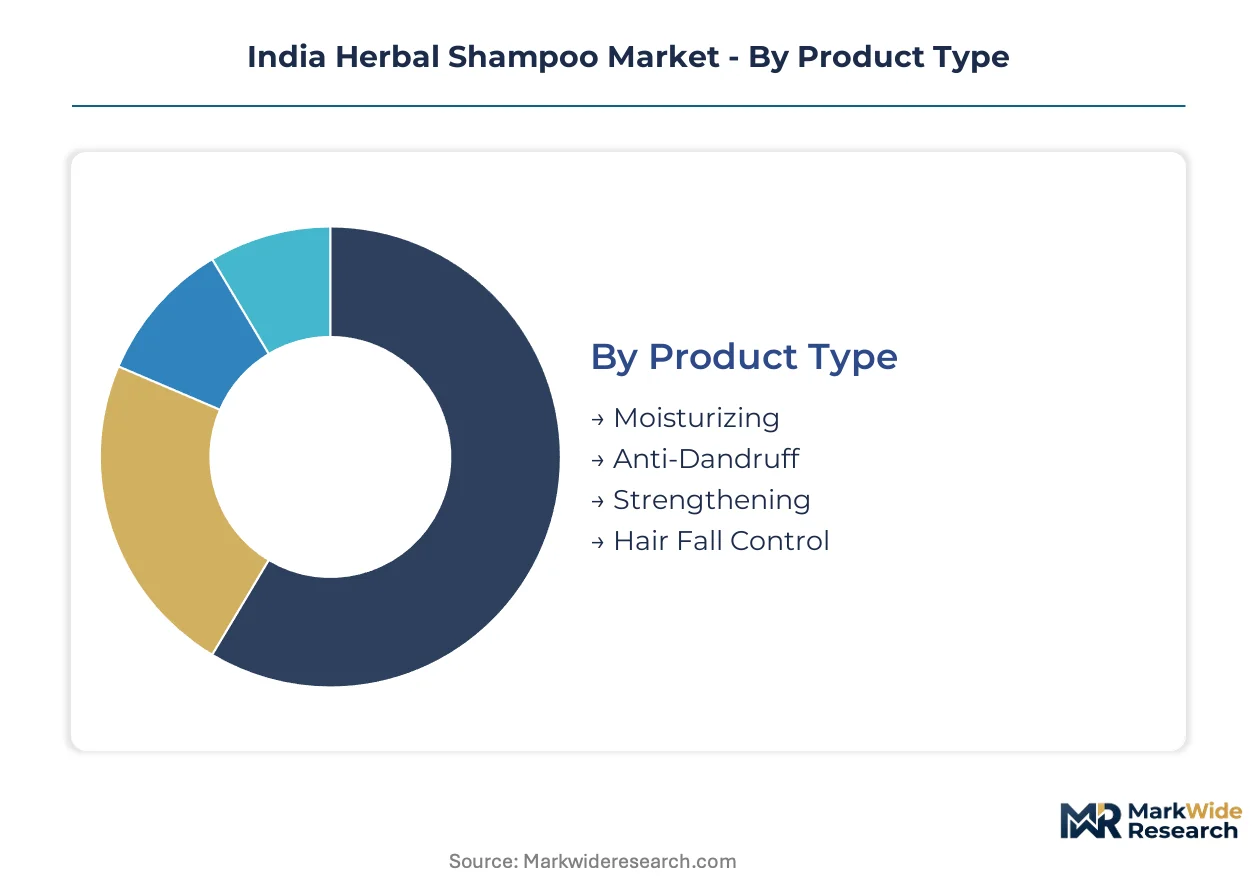
Herbal shampoo segmentation in India reflects divergent sourcing economics across botanical supply chains and distinct consumer willingness-to-pay thresholds. Category boundaries increasingly blur as formulators cross-position ingredients across multiple benefit claims to capture fragmented demand.
Product Type:
Supply concentration for functional actives determines which benefit claims manufacturers can scale profitably.
- Moisturizing:Glycerin and aloe vera base formulations dominate production volumes due to year-round raw material availability. Maharashtra-based contract manufacturers run continuous lines for this segment, serving both branded players and private label programs for modern trade chains.
- Anti-Dandruff:Neem and tea tree oil combinations require cold-process stabilization to preserve azadirachtin potency. Karnataka extraction facilities specializing in solvent-free methods supply this segment, with batch qualification timelines stretching lead times versus moisturizing variants.
- Strengthening:Protein-fortified variants using hydrolyzed wheat or soy derivatives target salon professionals in South Indian metros.
- Hair Fall Control:Bhringraj and amla concentrates anchor positioning, with BIS certification for heavy metal limits adding compliance overhead.
Today's leader: Moisturizing. Tomorrow's challenger: Anti-Dandruff.
Ingredients:
Cost tier separation emerges from wild-harvested versus cultivated sourcing models and extraction technology intensity.
- Amla:Tannin-rich dried fruit powder from Uttar Pradesh and Madhya Pradesh orchards supplies mass-market formulations. Seasonal price volatility during monsoon collection windows compresses margins for processors lacking forward contracts with farming cooperatives.
- Neem:Azadirachtin-bearing leaf and seed extracts command premium positioning due to supercritical CO2 extraction requirements. Gujarat and Rajasthan cultivation clusters supply certified organic grades to export-oriented manufacturers.
- Aloe Vera:Cultivated plantations in Tamil Nadu and Andhra Pradesh enable consistent supply for post-chemical recovery positioning.
- Hibiscus:Anthocyanin-rich flower extracts from Kerala home gardens serve regional niche brands with limited national scaling.
Volume dominance: Amla. Margin expansion: Neem.
End User:
Application context shapes formulation complexity and channel access requirements.
- Women:Multi-step regimen positioning drives higher per-capita consumption and cross-selling to conditioner and oil categories. Urban working professionals in Bangalore and Mumbai prioritize AYUSH-certified variants for workplace grooming standards.
- Men:Simplified benefit communication and convenience formats dominate, with two-in-one conditioning shampoo hybrids gaining traction in gym and travel channels.
- Children:Tear-free pH balancing and synthetic fragrance elimination govern formulation protocols, with pediatric dermatologist endorsements required for modern trade placement.
- Professionals:Salon stylists in Chennai and Hyderabad demand complete botanical sourcing documentation, creating a technical specification layer absent in retail channels.
Primary volume engine: Women. Specification intensity: Professionals.
Packaging Type:
Customer type and geography dictate format economics and distribution infrastructure requirements.
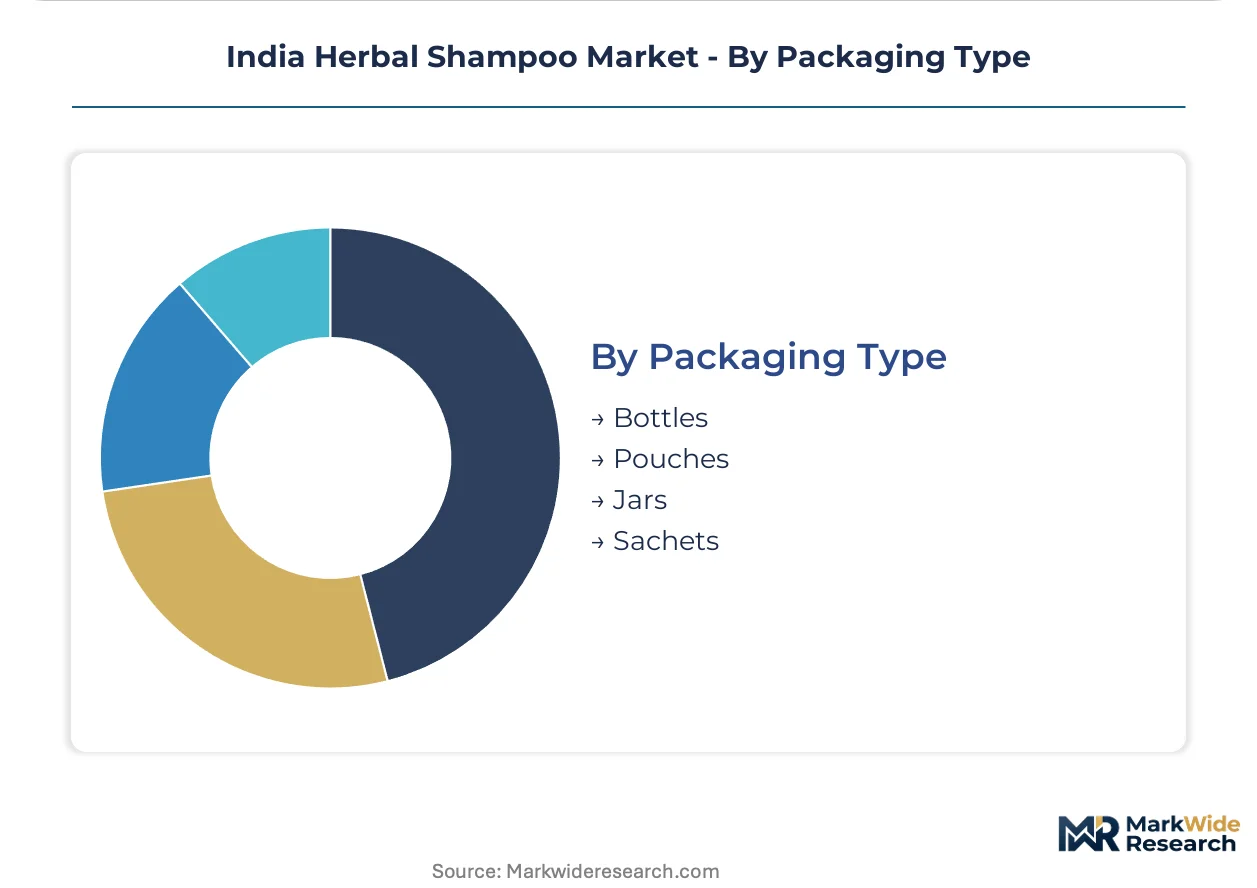
- Sachets:Single-use pouches dominate rural kirana penetration and price-sensitive trial conversion. Tamil Nadu's dense grocery network moves significant volume through direct-to-retailer digital integration, bypassing traditional distributor margins.
- Bottles:PET and HDPE containers anchor modern trade and e-commerce fulfillment, with pump dispensers commanding shelf space in premium urban retail.
- Pouches:Flexible refill formats reduce per-unit material costs and target eco-conscious positioning among metro millennials.
- Jars:Wide-mouth containers serve professional salon backbar usage and bulk family sizing in tier-two city general trade.
Unit economics champion: Sachets. Brand equity carrier: Bottles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra commands disproportionate herbal shampoo volume against Karnataka's extraction specialization, with both states anchoring distinct supply chain functions while northern markets lag in organized retail penetration.
Maharashtra
Mumbai and Pune metro consumers drive premium AYUSH-certified demand through modern trade channels. The state's FSSAI-mandated testing infrastructure expansion accelerates batch clearance for Maharashtra-based formulators. Nashik and Nagpur serve as collection hubs for wild-harvested shikakai during post-monsoon windows.
Karnataka
Bangalore's urban millennials prioritize chemical-free scalp care, pulling supercritical CO2-extracted neem formulations into premium shelves. BIS certification requirements compress supplier bases, rewarding Karnataka processors with authenticated sourcing. Mysore extraction facilities specialize in solvent-free azadirachtin preservation for anti-dandruff variants.
Tamil Nadu
Chennai salon professionals demand complete botanical documentation, creating specification intensity unmatched in retail channels. The state's dense kirana network moves sachet volume through direct-to-retailer digital integration. Coimbatore and Madurai cultivation clusters supply consistent aloe vera for post-chemical recovery positioning.
Gujarat
Surat and Ahmedabad consumers respond to price-positioned Ayurvedic variants below multinational benchmarks. Gujarat's neem cultivation clusters supply certified organic grades to export-oriented manufacturers. PLI scheme incentives reduce capital costs for domestic extraction equipment investments in Vadodara industrial zones.
Delhi-NCR
Gurgaon and Noida working professionals cross-purchase conditioner and oil categories through multi-step regimen positioning. Ministry of AYUSH quality parameters strengthen consumer trust in premium formulations. Ghaziabad contract manufacturers serve private label programs for modern trade chains expanding into tier-two satellite cities.
India Herbal Shampoo Market Competitive Landscape
Top-tier vendors anchor modern trade and premium digital channels, while regional specialists and unorganized processors compete on kirana penetration and unit economics. The market structures around heritage Ayurvedic houses, FMCG conglomerates with herbal extensions, and insurgent price disruptors. Strategic archetypes include certified organic premium players, aggressive rural distributors, and South Indian regional champions. Competitive moves concentrate on AYUSH certification acquisition and supercritical extraction capacity expansion.
Within the heritage Ayurvedic tier, Dabur India Ltd. and Patanjali Ayurved Ltd. exemplify divergent channel strategies, with the former leveraging modern trade placement and the latter dominating rural distribution economics. CavinKare Pvt. Ltd. occupies a distinct regional position, anchoring South Indian market penetration through Tamil and Telugu language branding. Among FMCG conglomerates, Unilever PLC represents multinational herbal extension strategies, while Himalaya Global Holdings Ltd. and Lotus Herbals Pvt. Ltd. sit within the specialist botanical positioning archetype.
| Leading Market Players |
|---|
| Unilever PLC |
| Emami Ltd. |
| Dabur India Ltd. |
| Lotus Herbals Pvt. Ltd. |
| CavinKare Pvt. Ltd. |
| Patanjali Ayurved Ltd. |
| Honasa Consumer Pvt. Ltd. |
| Bio Veda Action Research Co. |
| Himalaya Global Holdings Ltd. |
| Others |
Supply & Pricing Matrix
Amla-neem tier divergence separates certified organic formulations commanding shelf premiums from wild-harvested commodity grades competing on unit economics. This bifurcation manifests in Maharashtra processors investing in BIS-mandated heavy metal testing infrastructure while Karnataka extraction facilities absorb supercritical CO2 equipment costs to preserve azadirachtin potency for anti-dandruff positioning.
Pricing Analysis
Capacity additions in Gujarat neem cultivation clusters are reshaping price floors for certified organic grades. Three-tier pricing structure across premium AYUSH-certified, standard BIS-compliant, and economy unbranded levels stratifies the market. Price differentiation rests on Ministry of AYUSH certification status and cold-process extraction technology intensity. Cost compression in mass-market sachet tiers is intensifying because Tamil Nadu kirana networks bypass distributor margins through direct-to-retailer digital integration. Rural trial consumers exhibit highest price sensitivity, while Bangalore salon professionals accept premiums for complete botanical documentation.
Supply Chain Analysis
Domestic-content mandates under the PLI scheme for personal care manufacturing are reshaping sourcing toward in-house extraction equipment investments. Supply concentrates in Maharashtra for shikakai wild-harvesting, Karnataka for neem supercritical processing, and Tamil Nadu for aloe vera plantation cultivation. Raw material dependencies span monsoon-sensitive amla collection cycles, azadirachtin-bearing neem leaf supply, and glycerin base formulations. Single-source vulnerability concentrates in Maharashtra's seasonal shikakai collection windows. Distribution runs through kirana networks in South India, modern trade in Mumbai-Pune corridors, and professional salon channels in Chennai-Hyderabad clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India herbal shampoo functions as a stable compounder anchored by urban millennial demand for chemical-free scalp care in metro cities. AYUSH certification standards create durable competitive moats that filter unorganized competitors while rewarding compliance investments.
For Market Incumbents: Extend AYUSH certification coverage into tier-two city retail expansion before price disruptors establish kirana presence. Deepen backward integration into neem cultivation clusters in Gujarat and Rajasthan to preempt wild-harvested input volatility. Channel control through direct-to-retailer digital platforms in Tamil Nadu defends margin position against distributor margin compression.
For New Entrants and Emerging Players: Capture post-chemical recovery positioning among Bangalore and Chennai salon professionals seeking aloe vera formulations with complete botanical sourcing documentation. Jaipur and Lucknow organized retail expansion creates shelf space for mid-priced Ayurvedic variants lacking established brand heritage. Go-to-market angle: pediatric dermatologist endorsements for tear-free children's formulations in modern trade chains.
For Investors and Strategic Acquirers: Consolidation pressure builds where family-owned manufacturers lack balance sheet capacity for supercritical CO2 extraction equipment. Long-term viability favors processors with authenticated ingredient sourcing and in-house heavy metal testing infrastructure. Acquisition target archetype: Karnataka-based extraction facilities with solvent-free azadirachtin preservation capabilities. Signal to watch: BIS regulatory tightening on heavy metal limits accelerating supplier base compression.
| Strategic Initiative | Industry Significance |
|---|---|
| AYUSH Certification Acquisition | Ministry certification unlocks premium shelf placement in Mumbai modern trade formats. |
| Supercritical CO2 Capacity Expansion | Karnataka facilities preserve heat-sensitive phytochemicals for organic claims at scale. |
| Direct-to-Retailer Digital Integration | Tamil Nadu kirana networks bypass traditional distributor margin layers entirely. |
| Backward Integration into Cultivation | Gujarat neem plantations secure certified organic supply for export-oriented manufacturers. |
| Salon Professional Channel Development | Chennai stylists demand technical documentation unavailable in retail channels. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement spanned brand managers at heritage Ayurvedic houses, category buyers at modern trade chains, extraction facility technical directors, and salon professional stylists in South Indian metros. Secondary validation drew from Ministry of AYUSH certification databases, FSSAI cosmetic safety filings, BIS standards documentation, and organized retail expansion records. Bottom-up volume modeling triangulated against top-down category spend estimates.
Segment-weighting across product type, ingredient sourcing tier, end-user application context, and packaging format anchored the analytical framework. CAGRs were derived from trajectory analysis of certified organic premium growth versus mass-market sachet volume stability. Forecast inputs incorporated PLI scheme incentive uptake rates and AYUSH export protocol adoption patterns across the projection horizon.
Regulatory enforcement intensity, monsoon disruption severity, and synthetic substitute innovation velocity are the dominant revision risks. Forecasts reflect documented assumptions on certification penetration curves and extraction technology cost decline rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Sunless Tanners Market
Beauty & Personal Care
Global Lash Extension Market
Beauty & Personal Care
Makeup Egg Market
Beauty & Personal Care
At Home Hair Dye Market
Beauty & Personal Care
Europe Hair and Skincare Market
Beauty & Personal Care
Handmade False Eyelash Market
Beauty & Personal Care
Magnetic Eyelashes Market
Beauty & Personal Care
Body Balm Market
Beauty & Personal Care
Artificial Nails Market
Beauty & Personal Care
Netherlands Sustainable Personal Care Market
Beauty & Personal Care
Aluminium-Free Deodorants Market
Beauty & Personal Care
Facial Rollers Market
Beauty & Personal Care
Body Mist Market
Beauty & Personal Care
Europe Professional Beauty Services Market
Beauty & Personal Care
Scalp Massager Market
Beauty & Personal Care
Hair Styling Equipment Market