
 Global Bath Salts Market | 2026-2036
Global Bath Salts Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bath Salts Market Analysis
Clean-label formulation is fragmenting the traditional bath salts technology stack as brands abandon synthetic fragrances and petroleum-derived carriers. Westlab leverages its direct-source relationships with Himalayan and Dead Sea suppliers to sustain ingredient traceability claims. SaltWorks competes through vertical control of harvesting, milling, and packaging operations across multiple mineral sites. Unilever PLC anchors mass-market penetration through supermarket and pharmacy shelf dominance in North America and Western Europe.
Bath salts comprise water-soluble mineral crystals—primarily magnesium sulfate, sodium chloride, or potassium-rich compounds—dissolved in warm water to facilitate dermal mineral absorption and muscular relaxation. Industrial production involves solar evaporation, vacuum pan crystallization, or mechanical harvesting from ancient seabed deposits, followed by grading by granule size and mineral assay. Epsom salt occupies the largest volume position due to its established therapeutic positioning and lower raw material cost structure. Himalayan salt commands premium shelf pricing through pink coloration and trace mineral marketing, though aromatherapy-grade blends with essential oils represent the fastest-expanding margin pool as consumers seek multi-sensory home spa experiences.
The FDA regulates cosmetic bath preparations under the Federal Food, Drug, and Cosmetic Act, while the EU Cosmetics Regulation enforces safety dossier requirements and bans animal testing for finished products. REACH compliance in Europe further constrains fragrance additive selection, pushing formulators toward GRAS-listed botanical extracts. Stakeholders must monitor evolving state-level clean beauty legislation in California and New York, where ingredient disclosure mandates are tightening faster than federal standards.
Market Dynamics
Clean-label mandates from EU REACH and California's ingredient disclosure laws are fragmenting the bath salts technology stack, forcing formulators to abandon synthetic fragrance carriers and petroleum-derived solubilizers that dominated industrial production for decades.
Growth Catalysts
- Thermal Spa Infrastructure:Germany's Baden-Württemberg and Bavaria regions maintain over 350 accredited thermal facilities, creating institutional bulk demand for magnesium sulfate and Dead Sea mineral compounds.
- REACH Compliance:The EU's chemical safety framework bans animal testing for finished cosmetic products, accelerating botanical extract substitution and GRAS-listed essential oil adoption across European formulation labs.
- Solar Evaporation Yields:Advances in multi-pond crystallization sequences at Himalayan and Dead Sea extraction sites are improving mineral assay consistency and reducing downstream grading costs.
Market Restraints
- Input Cost Volatility:Magnesium sulfate prices fluctuate with sulfuric acid and magnesium oxide feedstock availability, compressing margins for commodity-grade Epsom salt producers.
- Supply Concentration Risk:Pakistan's Khewra Salt Mine and Jordan's Dead Sea Works control over 60% of premium pink and mineral-rich raw material flows, creating geographic chokepoints.
- Regulatory Friction:India's BIS certification requirements for imported cosmetic minerals impose 90-120 day testing timelines, delaying product launches in the subcontinent's emerging wellness retail channel.
Strategic Opportunities
- Underpenetrated Geography:Indonesia's nascent wellness tourism sector around Bali and Lombok lacks domestic therapeutic-grade salt production, creating import substitution potential for Australian and Indian suppliers.
- Regulatory Tailwind:The EU Green Deal's circular economy action plan incentivizes post-industrial salt recovery from desalination brine, opening new feedstock streams for cosmetic-grade mineral processing.
- Technology Convergence:Encapsulation of essential oils within hollow salt crystals combines aromatherapy delivery with controlled dissolution rates, enabling time-release home spa formulations.
Industry Challenges
- Certification Timeline Compression:Cosmetic Product Safety Reports under EU Regulation (EC) No 1223/2009 require toxicological dossiers that strain in-house regulatory affairs capacity at mid-sized formulators.
- Supply Chain Reconfiguration Friction:Shifting from synthetic to botanical fragrance sources forces reformulation of stability-tested base salts, invalidating existing shelf-life claims and requiring accelerated aging studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bath Salts Market |
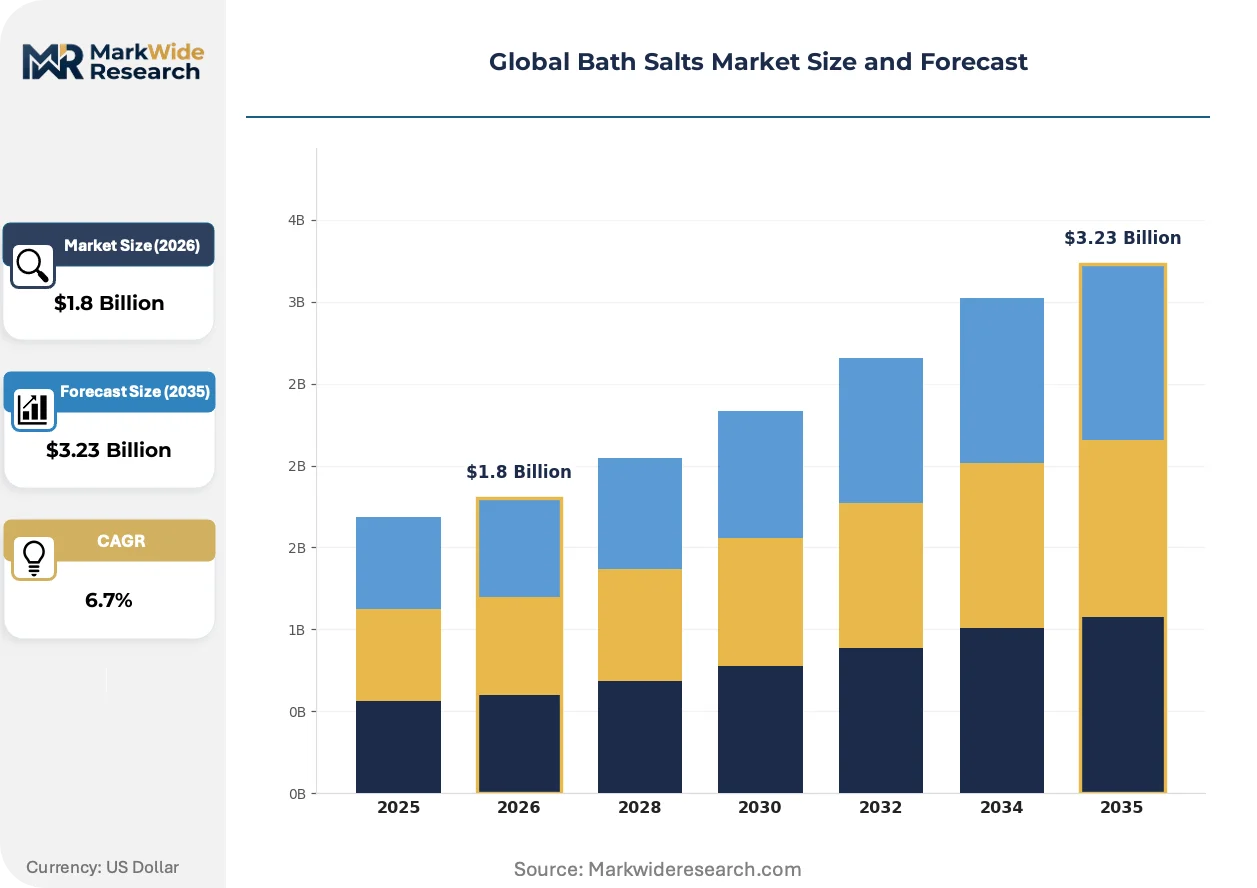
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dead Sea Salt, Epsom Salt, Himalayan Salt, Sea Salt Usage Type: Therapeutic, Aromatherapy, Relaxation, Skin Care Distribution Channel: Online, Specialty Stores, Supermarkets, Pharmacies Consumer Group: Health Enthusiasts, Spa Users, Gift Shoppers, Regular Consumers |
| Companies Covered | Westlab, Unilever PLC, L'Occitane en Provence, San Francisco Salt Company, SaltWorks, PDC Brands, Bathclin Corporation, Dead Sea Ltd., Kneipp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bath Salts Market Emerging Trajectories
Formulation chemistry and mineral sourcing protocols are undergoing parallel transformation as brands respond to tightening disclosure mandates and wellness consumers demand traceable, multi-sensory bath experiences.
Encapsulation technology using hollow-crystal magnesium sulfate matrices is rendering obsolete conventional surface-sprayed essential oil blends that suffer from rapid volatilization and uneven scent distribution. Premium hospitality amenity suppliers in Dubai and Singapore are adopting these structures for guest room bath programs. The shift compresses reformulation cycles from 18 months to 6 months as stability testing requirements simplify.
REACH Annex XVII restrictions on microplastic-containing rinse-off cosmetics entered force in October 2023, prohibiting synthetic glitter and polyethylene scrub particles in bath salt formulations. EU-based contract manufacturers have reformulated over 200 SKU lines to comply, substituting mineral-derived mica and biodegradable cellulose alternatives. Color cosmetic salt blends now face 12-18 month safety dossier preparation timelines versus 6 months for unadorned mineral crystals.
Direct-to-consumer subscription models for personalized bath salt regimens are displacing pharmacy and supermarket impulse purchasing in North American and Western European urban markets. Algorithmic skin-type matching and quarterly scent curation replace static SKU selection. This pattern concentrates in metropolitan clusters around Los Angeles, London, and Amsterdam where wellness app penetration exceeds 40% among women aged 25-45.
Global Bath Salts Market Segmentation
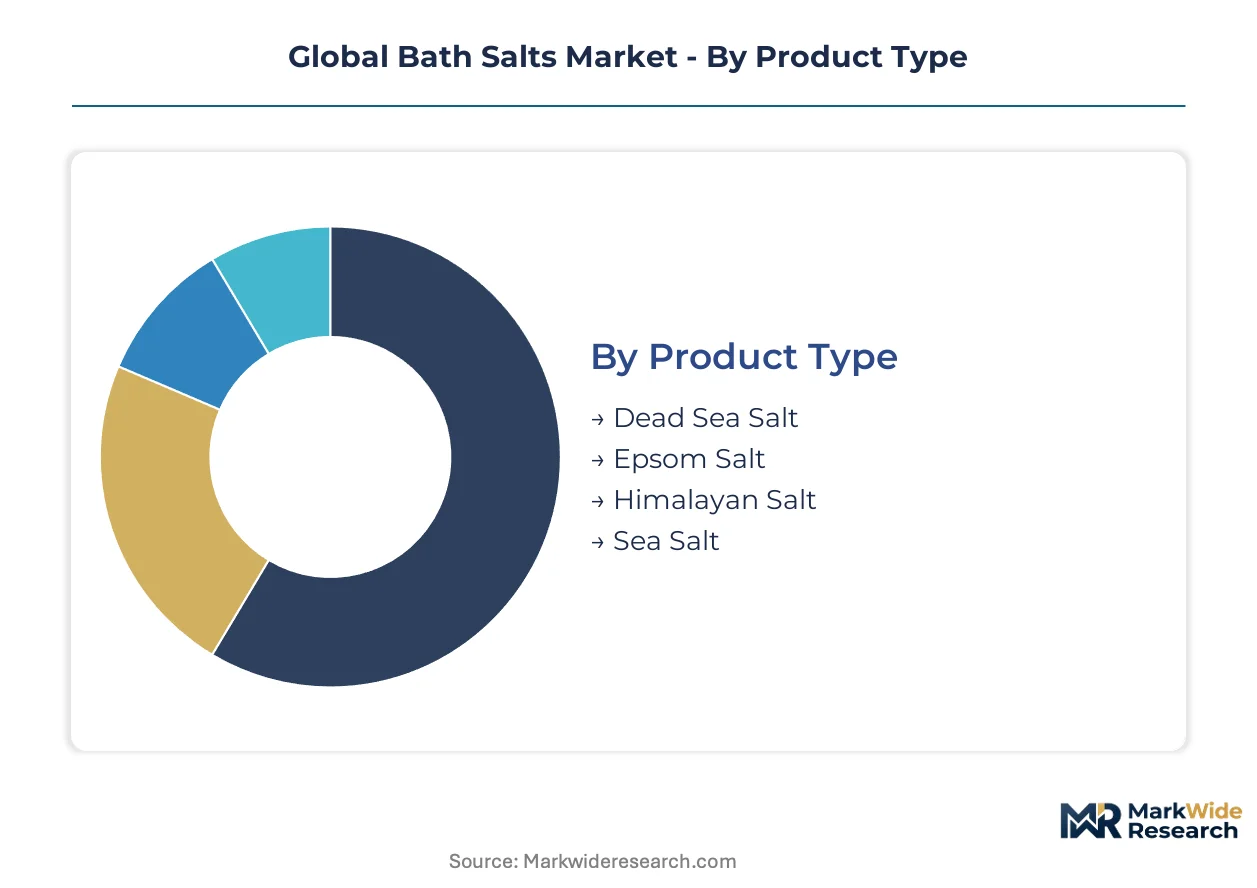
Segmentation in the bath salts market reveals how mineral composition, therapeutic intent, and purchase context shape pricing power and channel strategy. Distinct consumer missions—clinical recovery versus sensory indulgence—drive formulation priorities and retail placement decisions across the value chain.
Product Type:
Mineral provenance defines the use-case spectrum, from clinical-grade magnesium sulfate to color-differentiated ancient seabed deposits.
- Dead Sea Salt:Potassium and magnesium-rich mineral complexes harvested from Jordan's evaporative ponds. German thermal spa chains in Baden-Baden and Bad Wörishofen specify Dead Sea compounds for dermatological treatment protocols, though supply concentration at the Dead Sea Works creates procurement vulnerability.
- Epsom Salt:Magnesium sulfate heptahydrate produced through synthetic reaction of magnesium oxide and sulfuric acid, then crystallized via vacuum pan evaporation. Volume demand concentrates in North American pharmacy and supermarket channels where therapeutic positioning and lower unit economics sustain mass-market penetration.
- Himalayan Salt:Pink-hued sodium chloride with trace iron oxide deposits from Pakistan's Khewra Salt Mine. Premium shelf positioning relies on color differentiation and unrefined mineral marketing rather than substantiated therapeutic claims.
- Sea Salt:Solar-evaporated sodium chloride from coastal harvesting operations in France, Spain, and California. Lower mineral complexity limits therapeutic positioning but supports clean-label aromatherapy base formulations.
The dominant share belongs to Epsom Salt, while Himalayan Salt is closing the gap fastest.
Usage Type:
Application intent segments the market across clinical efficacy claims, sensory experience design, and cosmetic benefit positioning.
- Therapeutic:Clinically positioned mineral soaks targeting muscular recovery, inflammation reduction, and dermatological conditions. German and Austrian health insurance reimbursement for prescribed balneotherapy sustains institutional procurement volumes.
- Aromatherapy:Essential oil-infused formulations emphasizing olfactory experience over mineral absorption. Encapsulation technology at Dubai hospitality suppliers is displacing surface-sprayed alternatives.
- Relaxation:Stress-reduction positioning combining warm water immersion with ritualized home spa experiences. Subscription curation services in Los Angeles and Amsterdam concentrate demand among urban wellness consumers.
- Skin Care:Exfoliation and hydration claims targeting facial and body treatment regimens. REACH microplastic bans have forced reformulation away from polyethylene scrub particles toward mineral-derived mica.
Therapeutic applications command the highest volume, though aromatherapy blends are expanding most quickly.
Distribution Channel:
Channel selection determines margin capture, with direct-to-consumer models displacing traditional retail in premium segments.
- Online:Algorithmic personalization and subscription replenishment models. Quarterly scent curation and skin-type matching concentrate in metropolitan wellness clusters.
- Specialty Stores:Curated retail environments with trained staff and sampling infrastructure. Clean-label certification visibility drives placement decisions.
- Supermarkets:Mass-market Epsom salt placement with impulse-oriented packaging and price-point accessibility.
- Pharmacies:Therapeutic-grade positioning with pharmacist endorsement and insurance documentation support.
Online channels are gaining share fastest, while supermarkets retain the dominant volume position.
Consumer Group:
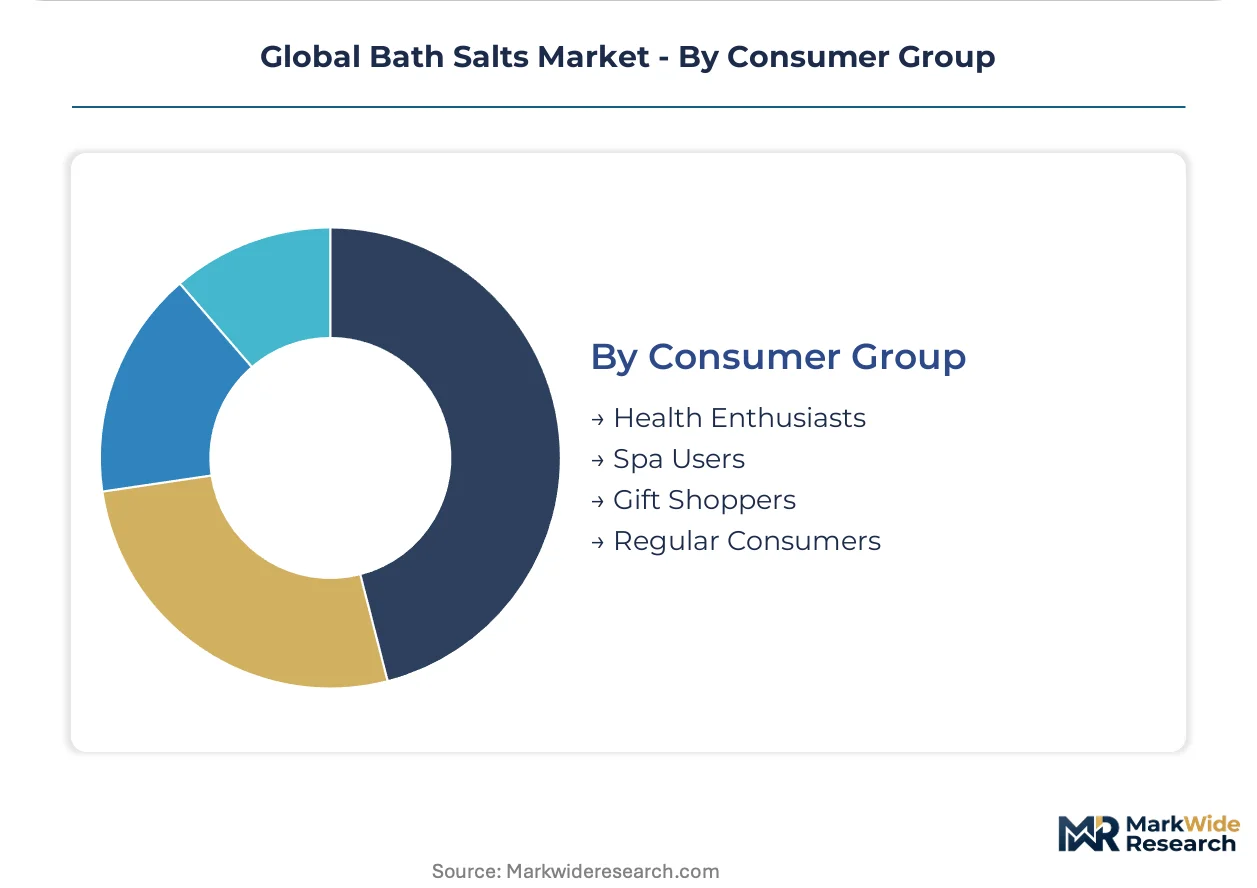
Purchase motivation segments buyers across health optimization, professional service integration, gifting rituals, and habitual replenishment.
- Health Enthusiasts:Biohacking-oriented consumers tracking mineral absorption and recovery metrics. Demand concentrates in California and Colorado wellness corridors.
- Spa Users:Professional treatment seekers extending institutional experiences through home regimen replication. Thermal spa discharge in Germany and Austria sustains premium salt familiarity.
- Gift Shoppers:Occasion-driven purchasers prioritizing packaging aesthetics and scent novelty over mineral specification. Seasonal concentration peaks in fourth-quarter retail cycles.
- Regular Consumers:Habitual bathers with established brand loyalty and replenishment patterns. Price sensitivity increases with purchase frequency.
Health Enthusiasts represent the fastest-expanding segment, while Regular Consumers anchor the volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pakistan's Khewra Salt Mine supplies raw pink-hued crystals to premium formulators across Germany, the United States, and the United Arab Emirates. Jordan's Dead Sea Works exports mineral-rich compounds to European thermal spa chains and Asian hospitality suppliers. These trade corridors concentrate high-value procurement decisions in specific national markets with distinct regulatory and consumption patterns.
Germany
Thermal spa infrastructure in Baden-Württemberg and Bavaria sustains institutional bulk demand for magnesium sulfate and Dead Sea mineral compounds. REACH compliance through ECHA mandates toxicological dossiers for all cosmetic-grade mineral imports, extending certification timelines for Pakistani and Jordanian suppliers. The Baden-Baden cluster hosts formulation labs that blend therapeutic-grade salts for hospital-affiliated wellness programs.
United States
FDA oversight under the Federal Food, Drug, and Cosmetic Act governs cosmetic bath preparations while California's ingredient disclosure laws tighten faster than federal standards. Los Angeles and New York metropolitan areas concentrate direct-to-consumer subscription services with algorithmic skin-type matching. Epsom salt volume demand anchors supermarket and pharmacy channels through established therapeutic positioning.
United Arab Emirates
Dubai hospitality chains specify encapsulated essential oil formulations for guest amenity programs, importing premium salts from Himalayan and Dead Sea sources. MOHAP cosmetic safety requirements align with GCC standardization protocols for mineral product registration. The Dubai Design District clusters luxury wellness retailers sourcing traceable, clean-label bath salt collections.
India
BIS certification requirements for imported cosmetic minerals impose 90-120 day testing timelines, delaying product launches in emerging wellness retail channels. Maharashtra and Gujarat host domestic salt processing facilities seeking import substitution opportunities for Australian and Indian suppliers. Mumbai's premium hospitality sector drives demand for aromatherapy-grade blends in boutique hotel amenities.
Australia
TGA oversight of therapeutic goods creates dual classification pathways for mineral soaks with clinical positioning versus cosmetic claims. Solar evaporation operations along the Great Australian Bight supply sodium chloride base materials to clean-label formulators. Sydney and Melbourne wellness corridors concentrate health enthusiast demand for biohacking-oriented mineral absorption products.
Global Bath Salts Market Vendor Landscape
Channel-controlling players compete with product-specialist players across mass-market and premium tiers. The market structure fragments between multinational consumer goods conglomerates with supermarket and pharmacy shelf dominance and vertically integrated mineral specialists with direct-source harvesting relationships. Three archetypes dominate: mass-market brand owners with distribution scale, direct-source mineral specialists with traceability claims, and hospitality-focused amenity suppliers with encapsulation technology. Competitive moves concentrate on backward integration into harvesting operations and reformulation cycles accelerated by clean-label mandates.
Within the direct-source specialist tier, Westlab and SaltWorks exemplify mineral-provenance positioning through supply chain transparency claims. Unilever PLC anchors mass-market penetration through retail channel control in North America and Western Europe. These three companies occupy distinct competitive spaces without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Westlab |
| Unilever PLC |
| L'Occitane en Provence |
| San Francisco Salt Company |
| SaltWorks |
| PDC Brands |
| Bathclin Corporation |
| Dead Sea Ltd. |
| Kneipp |
| Others |
Supply Flow & Price Mechanics
The Karachi-Hamburg container corridor carries Himalayan pink salt shipments where freight cost volatility intersects with Khewra Mine supply concentration to widen spreads between therapeutic-grade and cosmetic-grade mineral pricing. Downstream buyers in German thermal spa chains and Dubai hospitality programs absorb these differentials through volume commitments that lock in assay consistency premiums.
Pricing Analysis
Conventional surface-sprayed aromatherapy blends, hollow-crystal encapsulated formulations, and unprocessed mineral crystals occupy distinct pricing tiers based on technology generation and stability performance. Three-tier pricing structure across premium, standard, and economy levels reflects mineral assay certification, essential oil encapsulation technology, and hospitality channel exclusivity. Cost compression in commodity Epsom salt is intensifying because sulfuric acid and magnesium oxide feedstock volatility squeezes synthetic producers without captive mineral sources. Pharmacy and supermarket channels exhibit highest price sensitivity, while Dubai hospitality amenity suppliers show lowest sensitivity due to guest experience ROI calculations.
Supply Chain Analysis
Magnesium oxide and sulfuric acid feedstock for synthetic Epsom production, ancient seabed sodium chloride from Pakistan's Khewra Mine, and evaporative potassium-magnesium complexes from Jordan's Dead Sea Works anchor upstream material flows. Pakistan, Jordan, and Germany concentrate high-value mineral extraction and processing capacity, with solar evaporation yields improving at Dead Sea Works through multi-pond crystallization sequences. Single-source vulnerability at Khewra Mine creates procurement chokepoint exposure for premium pink salt formulators. Distribution runs through thermal spa institutional procurement networks, direct-to-consumer subscription platforms, and hospitality amenity supply contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label formulation mandates are fragmenting competitive space, creating specialist niches where traceability claims and encapsulation technology replace mass-market scale advantages. Subscription curation models and hospitality amenity specifications represent distinct demand-side shifts opening entry corridors.
For Market Incumbents: Build regulatory dossier capacity as a moat against mid-sized formulators strained by EU Cosmetics Regulation toxicological requirements. Invest in backward integration into Himalayan and Dead Sea harvesting operations to secure assay consistency for thermal spa contracts. Accelerate reformulation cycles through encapsulation technology adoption to compress stability testing timelines from 18 months to 6 months. For New Entrants and Emerging Players: Indonesia's nascent wellness tourism sector around Bali and Lombok represents the most penetrable entry point, lacking domestic therapeutic-grade salt production and creating import substitution demand for Australian suppliers. Algorithmic skin-type matching subscription services in secondary North American metropolitan clusters offer lower customer acquisition cost entry than saturated Los Angeles and New York markets. Pursue hospitality amenity supply contracts as anchor demand before direct-to-consumer expansion. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational consumer goods conglomerates divesting non-core mineral personal care lines under portfolio rationalization pressure. Five-to-ten year viability hinges on clean-label certification infrastructure and direct-source supply relationships rather than brand equity alone. Monitor EU Green Deal circular economy action plan implementation for post-industrial salt recovery feedstock economics as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Harvesting Operations | Captive supply from Khewra Mine or Dead Sea Works secures assay consistency for thermal spa procurement. |
| Encapsulation Technology Licensing | Hollow-crystal essential oil delivery commands hospitality amenity premiums in Dubai and Singapore. |
| Clean-Label Certification Investment | REACH-compliant toxicological dossiers unlock German pharmacy and thermal spa institutional channels. |
| Direct-to-Consumer Subscription Launch | Algorithmic curation captures Los Angeles and Amsterdam wellness corridor demand with recurring revenue. |
| Post-Industrial Salt Recovery Partnership | EU Green Deal desalination brine processing opens cosmetic-grade mineral feedstock streams. |
Methodological Framework
Cross-validation between primary interviews and customs trade data anchors the qualitative findings on supply concentration and procurement patterns. Conversations with thermal spa procurement directors, cosmetic formulators, hospitality amenity buyers, salt processing plant managers, and EU regulatory affairs consultants informed supply chain structure assessments. Secondary validation drew from ECHA REACH registration databases, BIS certification timelines for Indian imports, FDA cosmetic labeling guidance, and thermal spa industry association membership directories. Bottom-up mineral volume estimates and top-down wellness expenditure allocations were reconciled through iterative triangulation.
Calibration against historical thermal spa admission trends and hospitality amenity spend patterns refined projection assumptions across the analysis window. Segmentation modeling incorporated mineral provenance, therapeutic versus sensory application intent, distribution channel format, and consumer mission archetype dimensions. CAGRs were derived from mineral volume trajectories and pricing trend extrapolation, with specific inputs including solar evaporation yield improvements at Dead Sea Works and REACH compliance cost pass-through elasticity.
Macroeconomic conditions sit as an overlay; deviation in sulfuric acid pricing, container freight rates, or EU regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions on clean-label adoption curves and thermal spa infrastructure investment continuity. Cross-checking against hospitality sector capex disclosures and desalination brine recovery pilot data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Bangladesh Hair Oil Market
Beauty & Personal Care
Makeup Egg Market
Beauty & Personal Care
Beard Grooming Products Market
Beauty & Personal Care
Middle East and Africa Hair Styling Products Market
Beauty & Personal Care
Asia Pacific Herbal Beauty Products Market
Beauty & Personal Care
Cosmetics and Toiletries Market
Beauty & Personal Care
Global Personal Care Emollients Market
Beauty & Personal Care
Facial Oil Market
Beauty & Personal Care
China Antibacterial Soap Market
Beauty & Personal Care
Sunless Tanners Market
Beauty & Personal Care
Leave-In Conditioner Market
Beauty & Personal Care
Makeup Brushes Market
Beauty & Personal Care
North America Hair Conditioner Market
Beauty & Personal Care
Oil Control Lotion Market
Beauty & Personal Care
Waterless Cosmetics Market
Beauty & Personal Care
Hair Color Spray Market