
 Cosmetics Face Serum Market | 2026-2036
Cosmetics Face Serum Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetics Face Serum Market Analysis
Aftermarket professional consultation revenue is reconfiguring margin pools away from pure product sales toward protocol-based regimen bundling. SkinCeuticals leverages its physician-dispensed channel heritage to anchor premium positioning in dermatology clinics. Obagi Medical competes through prescription-strength retinol concentrations that sustain loyalty among acne-prone demographics. Shiseido controls East Asian distribution networks, extending its reach into duty-free travel retail where serum SKUs occupy high-visibility placement.
Cosmetics face serums are concentrated, low-viscosity topical formulations typically delivering active ingredients at concentrations between 5% and 20% in aqueous or lipid-based carriers, designed for rapid dermal penetration prior to moisturizer occlusion. Their primary commercial purpose centers on targeted correction of specific skin concerns—hydration, photodamage, hyperpigmentation, or barrier dysfunction—through single-mechanism or multi-actives layering protocols. Anti-aging serums containing retinol and peptide complexes represent the deepest margin pool as consumers accept sustained premium pricing for clinically positioned age-intervention claims. Brightening formulations with stabilized vitamin C derivatives represent the fastest-growing ingredient-led segment as post-inflammatory hyperpigmentation concerns expand across Fitzpatrick skin type ranges previously underserved by mass-market offerings.
Regulators including the FDA, the EU's ECHA under REACH, and Japan's MHLW through quasi-drug classification shape formulation freedom, labeling requirements, and market access timelines across the three largest developed demand centers. Compliance with China's NMPA cosmetic registration requirements now determines entry feasibility for brands seeking direct distribution rather than cross-border e-commerce workarounds. Stakeholders must monitor divergence between the EU's evolving fragrance allergen disclosure mandates and the US's comparatively permissive cosmetic ingredient review pace when prioritizing formulation platform standardization versus regional customization investments.
Market Dynamics
The EU's MDR and REACH frameworks are compressing formulation cycles as manufacturers accelerate reformulation to meet tightening ingredient disclosure mandates, forcing simultaneous compliance investments across multiple regulatory jurisdictions.
Growth Catalysts
- Med-spa channel expansion:Premium skin clinics are displacing mass retail as the primary volume driver for professional-grade formulations, concentrating demand in physician-dispensed channels.
- REACH compliance acceleration:The EU's evolving fragrance allergen disclosure mandates are pushing manufacturers toward cleaner label architectures that command price premiums.
- K-beauty innovation pipelines:Seoul-Incheon corridor R&D centers are feeding global private-label sourcing networks with rapid iteration capabilities.
Market Restraints
- Raw material concentration:Stabilized vitamin C derivative supply concentrates among three specialty chemical producers in Germany and Japan, creating input vulnerability.
- NMPA registration timelines:China's cosmetic registration requirements extend market entry feasibility assessments to 18-24 months for direct distribution models.
- Peptide synthesis capacity:Contract manufacturing for high-potency retinol and peptide complexes faces bottlenecks at GMP-certified facilities.
Strategic Opportunities
- Fitzpatrick type IV-VI expansion:Post-inflammatory hyperpigmentation formulations for previously underserved melanin-rich skin profiles represent unclaimed white space in North American dermatology clinics.
- Duty-free travel retail:Shiseido's high-visibility placement models demonstrate margin capture potential in airport corridors connecting Seoul, Tokyo, and Singapore.
- Protocol bundling services:Aftermarket professional consultation revenue streams are reconfiguring margin pools beyond pure product transactions.
Industry Challenges
- Formulation chemist scarcity:Expertise in lipid-based carrier systems compatible with both retinol stability and dermal penetration requirements concentrates among aging specialist workforces in France and Switzerland.
- Cross-border e-commerce workaround exposure:Brands relying on indirect China access face regulatory reclassification risk as SAMR tightens enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetics Face Serum Market |
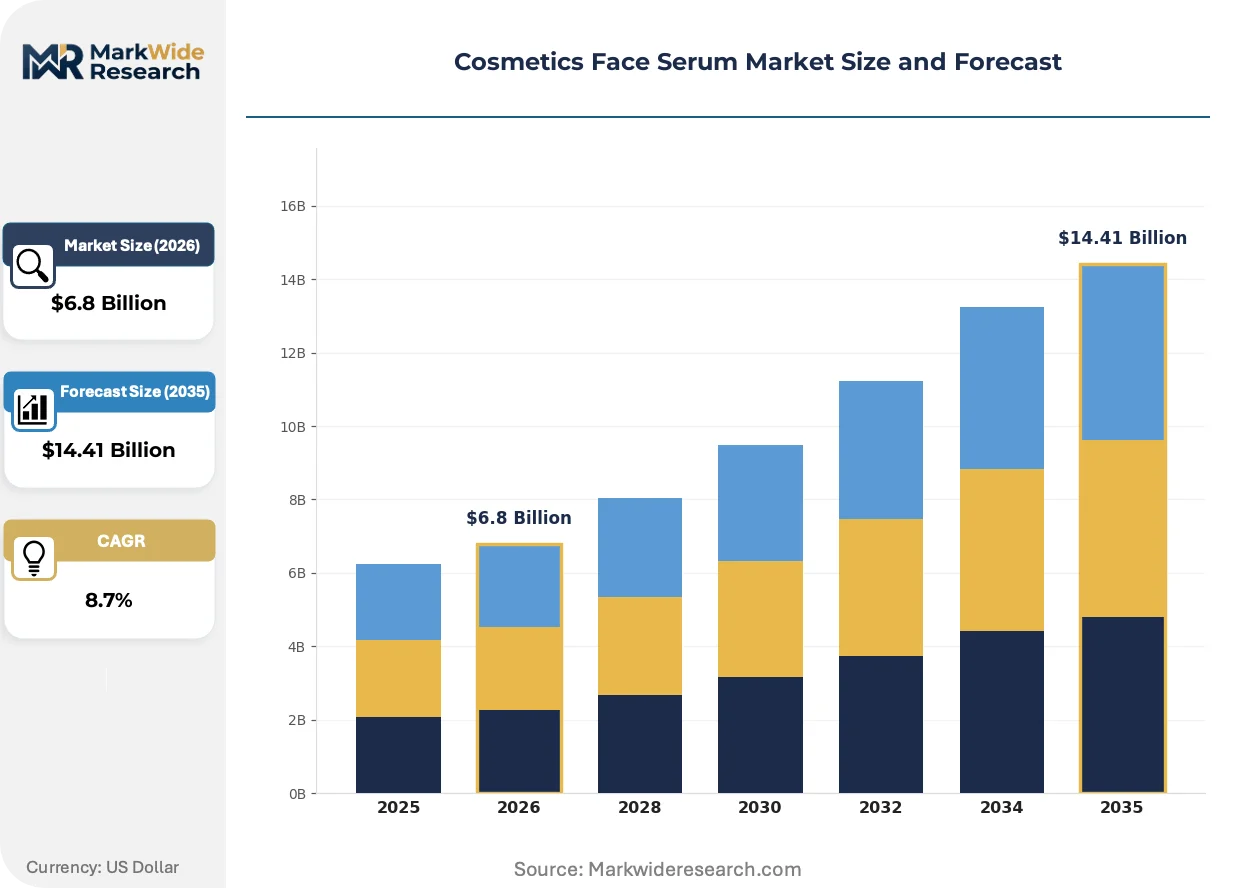
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizing, Anti-Aging, Brightening, Acne Treatment Ingredient: Hyaluronic Acid, Vitamin C, Retinol, Peptides Application Type: Daily Use, Night Use, Intensive Treatment, Professional Use Packaging Type: Pumps, Dropper Bottles, Jars, Sachets |
| Companies Covered | Obagi Medical, NEOCUTIS, SkinCeuticals, Shiseido, Sunday Riley, EltaMD, Revision Skincare, RainShadow Labs, SkinMedica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetics Face Serum Market Emerging Trajectories
Active ingredient delivery systems are converging with digital skin diagnostics, creating feedback loops that personalize regimen protocols and compress repurchase cycles in premium channels.
Encapsulation technology is hybridizing retinol and peptide actives within lipid nanoparticle architectures that protect potency through shelf life while enabling controlled dermal release. Dermatology clinics in South Korea and the United States are adopting these dual-mechanism formulations at twice the pace of European med-spas. The convergence is compressing traditional single-active product lifecycles and forcing reformulation investments across legacy portfolios.
The EU's MDR medical device classification expansion is capturing certain high-concentration retinol formulations previously regulated as cosmetics, requiring clinical evidence submissions. Manufacturers serving the German and French markets are restructuring quality management systems to accommodate notified body oversight. Acne-prone demographic targeting has shifted toward prescription-adjacent positioning to exploit regulatory arbitrage between cosmetic and quasi-drug frameworks.
Clinician-guided regimen building is displacing self-directed single-SKU purchases in premium segments, with Seoul-based skin clinics pioneering subscription protocols that bundle diagnostic imaging with quarterly formula adjustments. This behavior change is most visible among consumers aged 35-50 in East Asian urban centers, where loyalty programs tied to professional consultation frequency now determine repurchase rates more than brand equity alone.
Cosmetics Face Serum Market Segmentation
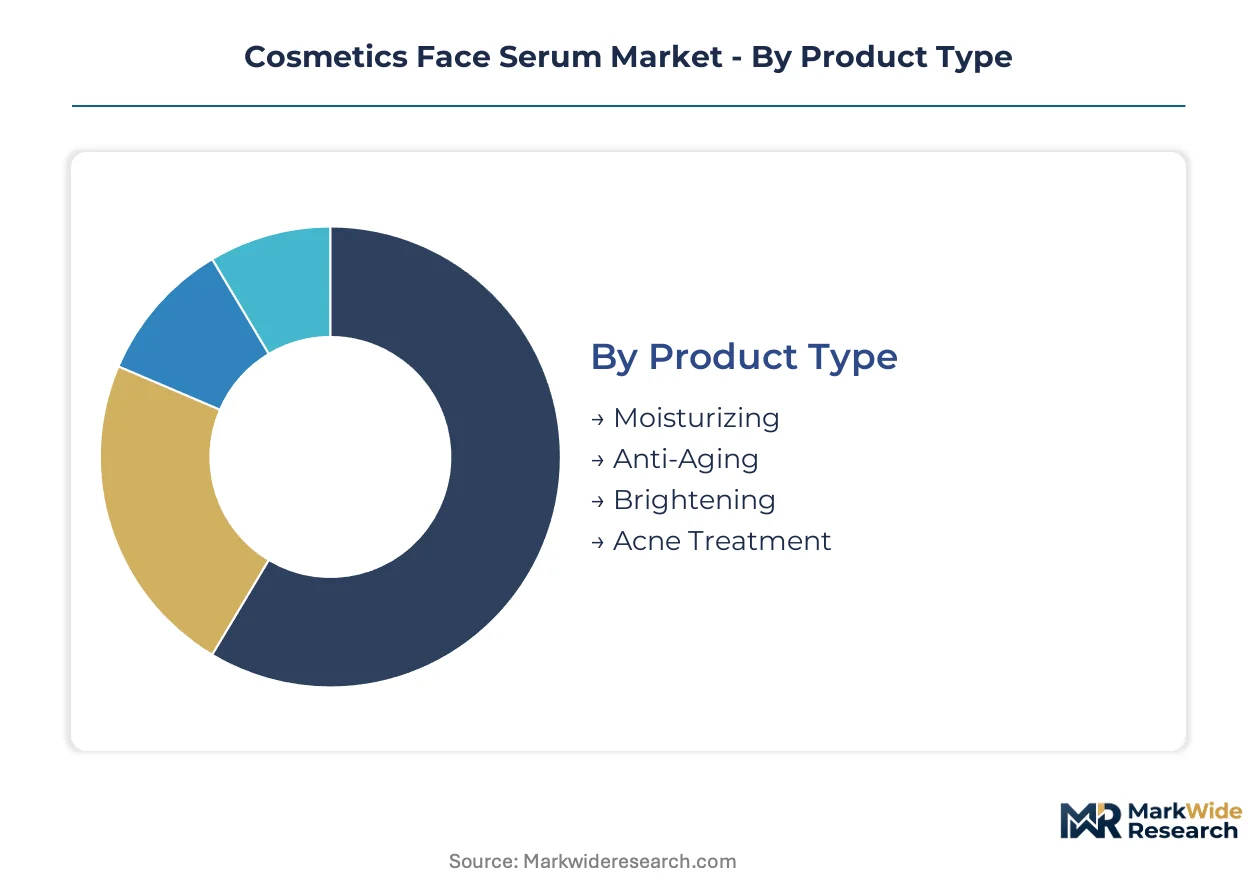
Segmentation in cosmetics face serums reveals how formulation chemistry, usage rituals, and channel economics split margin pools across distinct consumer workflows. Each dimension carries implications for R&D investment priority, packaging format selection, and professional versus retail channel placement.
Product Type:
Mature anti-aging formulations coexist with emerging brightening SKUs as manufacturers balance proven retinol stability against vitamin C derivative innovation cycles.
- Moisturizing:Hyaluronic acid and glycerin-based aqueous carriers dominate this foundational category, with demand concentrating in mass retail channels where consumers seek entry-level hydration protocols. South Korean OEMs supply private-label volumes to North American drugstore chains seeking rapid shelf replenishment.
- Anti-Aging:Retinol and peptide complexes at 0.3% to 1% concentrations define this deepest-margin segment, where physician-dispensed channels in Germany and France sustain premium pricing through clinical positioning. Loyalty concentrates among consumers aged 40-55 who accept multi-step regimen complexity.
- Brightening:Stabilized ascorbic acid and arbutin formulations target post-inflammatory hyperpigmentation across Fitzpatrick skin types IV-VI, with Seoul-based clinics pioneering protocol bundling.
- Acne Treatment:Niacinamide and salicylic acid blends serve prescription-adjacent positioning in Japanese quasi-drug frameworks.
Anti-aging retains volume leadership; brightening holds the steepest expansion curve.
Ingredient:
Cost tier stratification separates commodity humectants from specialty actives requiring GMP-certified synthesis capacity.
- Hyaluronic Acid:Cross-linked and low-molecular-weight variants span economy to premium tiers, with Chinese fermentation capacity supplying global mass-market formulators. German specialty chemical producers capture margin in medical-grade grades for clinic-dispensed lines.
- Vitamin C:Ethyl ascorbic acid and magnesium ascorbyl phosphate derivatives command price premiums for oxidation stability, with Japanese and German suppliers controlling stabilized derivative output. Concentration in three producers creates procurement vulnerability for mid-tier brands.
- Retinol:Encapsulation technologies from Swiss lipid nanoparticle specialists protect potency through shelf life.
- Peptides:Signal peptide and carrier peptide synthesis concentrates among French and Swiss contract manufacturers facing capacity constraints.
Hyaluronic acid commands absolute volume; vitamin C derivatives are expanding most quickly.
Application Type:
Customer workflow patterns split between self-directed daily rituals and clinician-supervised intensive protocols.
- Daily Use:Lightweight, fast-absorbing aqueous serums dominate morning routines, with Japanese consumers showing highest adherence to multi-step layering sequences. Tokyo-Osaka corridor retailers merchandise these SKUs adjacent to sunscreen for protocol completion.
- Night Use:Lipid-based retinol carriers exploit overnight occlusion windows, with South Korean skin clinics prescribing concentration escalation schedules tied to tolerance monitoring.
- Intensive Treatment:Higher active loads at 15-20% concentrations target episodic skin stress events.
- Professional Use:Pre- and post-procedure formulations require clinical evidence submissions under EU MDR frameworks.
Daily use retains volume leadership; professional use gains share fastest.
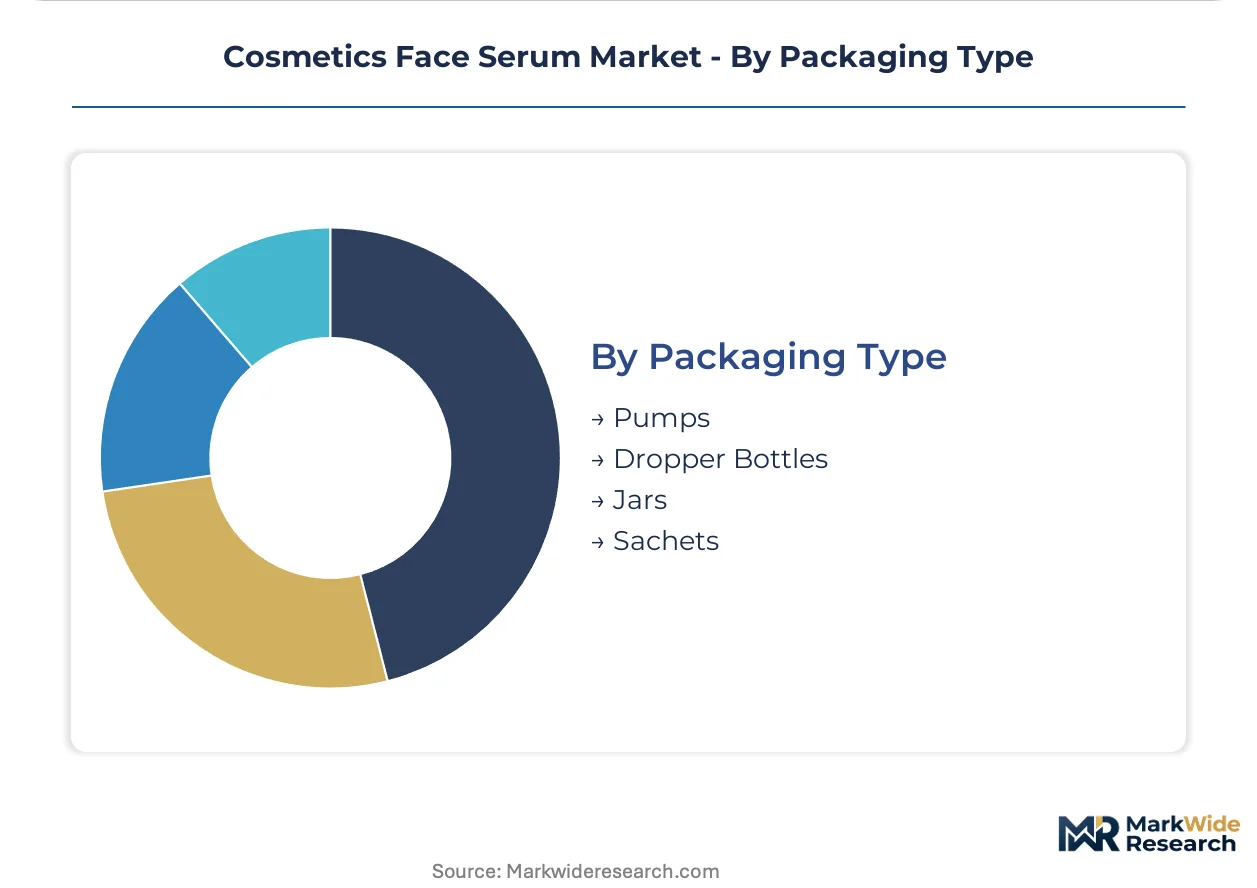
Packaging Type:
Supply concentration in Asian molding and glasswork shapes format availability and sustainability positioning.
- Pumps:Airless pump mechanisms from South Korean and Chinese manufacturers protect oxidation-sensitive actives, with demand concentrating in mass-market brightening SKUs where consumer convenience drives repurchase. European brands face extended lead times for PCR-content pump components.
- Dropper Bottles:Amber and cobalt glass from Italian and German suppliers signals premium positioning in retinol and vitamin C segments, with apothecary aesthetics reinforcing clinical credibility in French pharmacy channels.
- Jars:Wide-mouth formats persist in peptide cream-serum hybrids targeting older demographics.
- Sachets:Single-dose foil laminates serve travel retail and sampling programs.
Pumps retain volume leadership; dropper bottles hold the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Med-spa channel penetration varies sharply by geography, with South Korean consumers embracing clinician-supervised protocols while German consumers favor pharmacy-dispensed self-directed regimens. This consumption-mix differential shapes formulation requirements and margin capture mechanisms across demand centers.
United States
Physician-dispensed channels concentrate volume in dermatology clinics across California and New York, where prescription-adjacent retinol positioning commands sustained premium pricing. FDA cosmetic ingredient review maintains comparatively permissive timelines versus EU counterparts. The Greater Boston corridor houses contract manufacturing capacity for peptide synthesis serving clinic-exclusive lines.
South Korea
Seoul-Incheon corridor skin clinics pioneer subscription protocols bundling diagnostic imaging with quarterly formula adjustments, compressing repurchase cycles among consumers aged 35-50. MFDS quasi-drug frameworks enable rapid iteration of brightening actives. Busan-Ulsan manufacturing clusters supply private-label volumes to North American and Southeast Asian buyers.
Germany
Pharmacy channels sustain premium positioning for retinol and peptide complexes through clinical credibility reinforced by apothecary aesthetics. ECHA REACH fragrance allergen disclosure mandates accelerate reformulation investments. Bavaria-based specialty chemical producers control medical-grade hyaluronic acid output for clinic-dispensed lines.
Japan
Tokyo-Osaka corridor retailers merchandise daily-use aqueous serums adjacent to sunscreen for protocol completion, sustaining highest adherence to multi-step layering sequences. MHLW quasi-drug classification shapes niacinamide and salicylic acid blend positioning. Kanto region fermentation capacity supplies cross-linked hyaluronic acid variants spanning economy to premium tiers.
China
Cross-border e-commerce workarounds currently dominate access for international brands, though SAMR enforcement tightening elevates NMPA direct registration feasibility assessments to 18-24 month timelines. Shanghai and Beijing urban centers concentrate demand for brightening formulations targeting post-inflammatory hyperpigmentation. Yangtze River Delta OEMs supply airless pump components to European brands facing extended lead times.
Cosmetics Face Serum Market Vendor Landscape
Capability concentration sits with physician-dispensed heritage brands; scale advantage sits with diversified beauty conglomerates controlling East Asian distribution networks. The market structures around three tiers: clinic-exclusive formulators with prescription-adjacent positioning, prestige beauty houses leveraging duty-free travel retail visibility, and private-label suppliers feeding mass-market replenishment cycles. Dominant competitive moves include vertical integration into encapsulation technology sourcing and strategic partnerships with Seoul-based skin diagnostics platforms.
Within the clinic-exclusive tier, SkinCeuticals and Obagi Medical exemplify physician-dispensed channel heritage that anchors premium positioning in dermatology settings. Shiseido occupies a position at the diversified conglomerate end, with distribution network control extending into duty-free travel retail corridors. These three represent distinct archetypes: clinical credibility anchoring, prescription-strength formulation concentration, and East Asian market access leverage respectively.
| Leading Market Players |
|---|
| Obagi Medical |
| NEOCUTIS |
| SkinCeuticals |
| Shiseido |
| Sunday Riley |
| EltaMD |
| Revision Skincare |
| RainShadow Labs |
| SkinMedica |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor's freight cost volatility directly shapes margin allocation between German specialty chemical suppliers and mass-market formulators, compressing price differentiation between clinic-dispensed retinol complexes and drugstore hyaluronic acid SKUs while amplifying procurement leverage for buyers with volume scale.
Pricing Analysis
Long-term offtake agreements dominate procurement for stabilized vitamin C derivatives, locking Korean and Japanese manufacturers into 12-18 month supply commitments that insulate against spot market volatility. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified peptide synthesis from fermentation-grade hyaluronic acid and commodity glycerin carriers. Pricing pressure stems from REACH compliance costs accelerating reformulation investments. Mass retail buyers exhibit highest price sensitivity; dermatology clinics accept sustained premiums for prescription-adjacent positioning.
Supply Chain Analysis
Extended payment terms from South Korean OEMs to Yangtze River Delta molding suppliers are compressing working capital cycles across airless pump component networks. Encapsulation technology concentrates in Switzerland and France; stabilized ascorbic acid synthesis anchors in Germany and Japan. Single-source vulnerability concentrates in lipid nanoparticle specialist capacity serving retinol stability requirements. Distribution runs through Seoul-Incheon corridor private-label networks feeding North American and Southeast Asian buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU's MDR medical device classification expansion captures high-concentration retinol formulations, creating regulatory arbitrage opportunities that reward rapid quality management system restructuring and clinical evidence generation capabilities.
For Market Incumbents: Build physician-dispensed channel moats through exclusive formulation partnerships with Seoul-based skin diagnostics platforms. Secure GMP-certified peptide synthesis capacity in the Greater Boston corridor before contract manufacturing bottlenecks intensify. The MFDS quasi-drug framework acceleration threatens formulation freedom for legacy portfolios lacking rapid iteration infrastructure.
For New Entrants and Emerging Players: Establish a beachhead in Fitzpatrick skin type IV-VI brightening protocols for North American dermatology clinics, where post-inflammatory hyperpigmentation formulations remain underpenetrated. Target subscription-based regimen bundling in the 35-50 demographic segment. Partner with Busan-Ulsan OEM clusters for private-label cost structure advantages.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified beauty conglomerates seeking to divest non-core clinic-exclusive lines amid channel consolidation pressure. Long-term viability hinges on regulatory compliance infrastructure capable of navigating divergence between EU fragrance allergen mandates and FDA review timelines. Monitor SAMR enforcement tightening as the signal indicating direct China registration feasibility shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Technology Licensing | Swiss lipid nanoparticle specialists enable retinol stability through shelf life for clinic-dispensed lines. |
| Physician-Dispensed Channel Partnership | California and New York dermatology clinics anchor premium pricing for prescription-adjacent positioning. |
| REACH Compliance Certification | ECHA fragrance allergen disclosure mandates accelerate cleaner label architecture investments. |
| Seoul-Based Diagnostics Integration | Subscription protocols bundling imaging with formula adjustments compress repurchase cycles. |
| NMPA Direct Registration Pathway | Shanghai and Beijing market access requires 18-24 month feasibility assessments versus cross-border alternatives. |
Methodological Framework
Cross-validation between primary interviews with formulation chemists, dermatology clinic procurement managers, and OEM supply planners and secondary validation through ECHA REACH substance registrations, MFDS quasi-drug filings, and customs trade data anchors the qualitative findings. Bottom-up SKU-level volume estimates triangulate against top-down channel revenue assessments across physician-dispensed, pharmacy, mass retail, and duty-free travel retail segments.
Calibration against historical CAGRs from adjacent dermocosmetic categories and active ingredient price indices shapes the projection framework across the analysis window. Segmentation dimensions include product type, active ingredient concentration tier, application ritual, packaging format, and channel archetype. Peptide synthesis capacity utilization rates and encapsulation technology adoption curves inform demand elasticity assumptions.
Stress conditions across raw material concentration, regulatory reclassification timelines, and med-spa channel penetration rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding REACH implementation pace and NMPA registration throughput. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Cosmetic Serum Market
Beauty & Personal Care
Advanced Night Repair Serum Market
Beauty & Personal Care
North America Beauty and Personal Care Products Market
Beauty & Personal Care
Global Body Wash and Shower Gel Market
Beauty & Personal Care
Facial Make-Up Market
Beauty & Personal Care
Post-Shave Care Market
Beauty & Personal Care
Nail Lamps Market
Beauty & Personal Care
Beard Oil Market
Beauty & Personal Care
Frizz Control Shampoo Market
Beauty & Personal Care
Home Use Anti-Aging Beauty Device Market
Beauty & Personal Care
Deodorant Products Market
Beauty & Personal Care
Brazil Sustainable Personal Care Market
Beauty & Personal Care
Asia-Pacific Beauty and Personal Care Products Market
Beauty & Personal Care
Natural Hair Care Product Market
Beauty & Personal Care
UV Nail Gel Lamp Market
Beauty & Personal Care
Hair Salon Equipment Market