
 Global Personal Care Market | 2026-2036
Global Personal Care Market Size, Share, and Industry Trends Forecast 2026-2036
Global Personal Care Market Outlook
Plant-derived surfactants is realigning cost structures across mass-market cleansers as petrochemical feedstock volatility persists. L'Oréal S.A. leverages biotechnology partnerships to secure fermentation-based ingredient pipelines. Beiersdorf AG anchors its European manufacturing with certified palm-oil-free emulsifier systems. Procter & Gamble competes through captive oleochemical processing in Southeast Asian supply nodes.
Personal care encompasses formulated products applied to skin, hair, and body for hygiene, aesthetic enhancement, or dermatological protection, typically incorporating emulsifiers, active ingredients, and preservation systems at pH ranges between 4.5 and 7.0. Skincare commands the largest value pool due to premiumization of anti-aging serums and clinical-positioned moisturizers. Online Retail captures the fastest volume growth as direct-to-consumer subscription models displace traditional pharmacy foot traffic in developed economies. Synthetic formulations retain mass-market dominance though Natural and Organic segments extract disproportionate margin premiums through clean-label certification requirements.
FDA cosmetic registration mandates under the Modernization of Cosmetics Regulation Act reshape ingredient disclosure obligations for US market access. ECHA REACH restrictions on microplastic additives and fragrance allergens compel European manufacturers to reformulate rinse-off products. China's NMPA cosmetic registration requirements and GB standards for imported personal care items create compliance thresholds that favor established multinationals with dedicated regulatory affairs teams. Stakeholders must monitor divergent preservative approval lists across FDA, ECHA, and NMPA jurisdictions when designing unified global product platforms.
Market Dynamics
Biotechnology-based ingredient pipelines are compressing development timelines while EU Green Deal chemical restrictions force simultaneous portfolio reformulation across mass-market and premium tiers.
Growth Catalysts
- EU Green Deal chemical restrictions:REACH microplastic bans and fragrance allergen limits accelerate clean-label innovation, opening premium positioning for compliant formulations.
- India tier-two city expansion:Rising disposable incomes in secondary urban centers generate new volume demand for mid-tier skincare and haircare products.
- Direct-to-consumer subscription models:Online Retail channel capture displaces traditional pharmacy foot traffic in developed economies, improving customer lifetime value metrics.
Market Restraints
- Petrochemical feedstock volatility:Crude oil price swings destabilize surfactant cost structures for synthetic formulation manufacturers.
- Southeast Asian oleochemical supply concentration:Captive processing assets cluster in Malaysia and Indonesia, creating geographic dependency for major producers.
- Preservative approval divergence:FDA, ECHA, and NMPA maintain incompatible approved substance lists, complicating unified global product platform design.
Strategic Opportunities
- Brazil ANVISA regulatory harmonization:Emerging alignment with EU cosmetic safety standards reduces duplicate testing costs for multinational entry.
- Fermentation-based active ingredient production:Biotechnology convergence with traditional cosmetic chemistry enables novel peptide and ceramide synthesis at scale.
- Clinical-positioned moisturizer segment:Dermatological endorsement channels create pricing power in anti-aging and barrier-repair formulations.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in natural emulsifier stabilization and pH-balanced preservation systems commands premium compensation.
- Dual regulatory compliance timelines:Simultaneous FDA MoCRA registration and ECHA REACH dossier preparation strains regulatory affairs bandwidth.
- Legacy synthetic-to-bio-based manufacturing retooling:Capital equipment replacement for plant-derived surfactant processing requires multi-year depreciation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Personal Care Market |
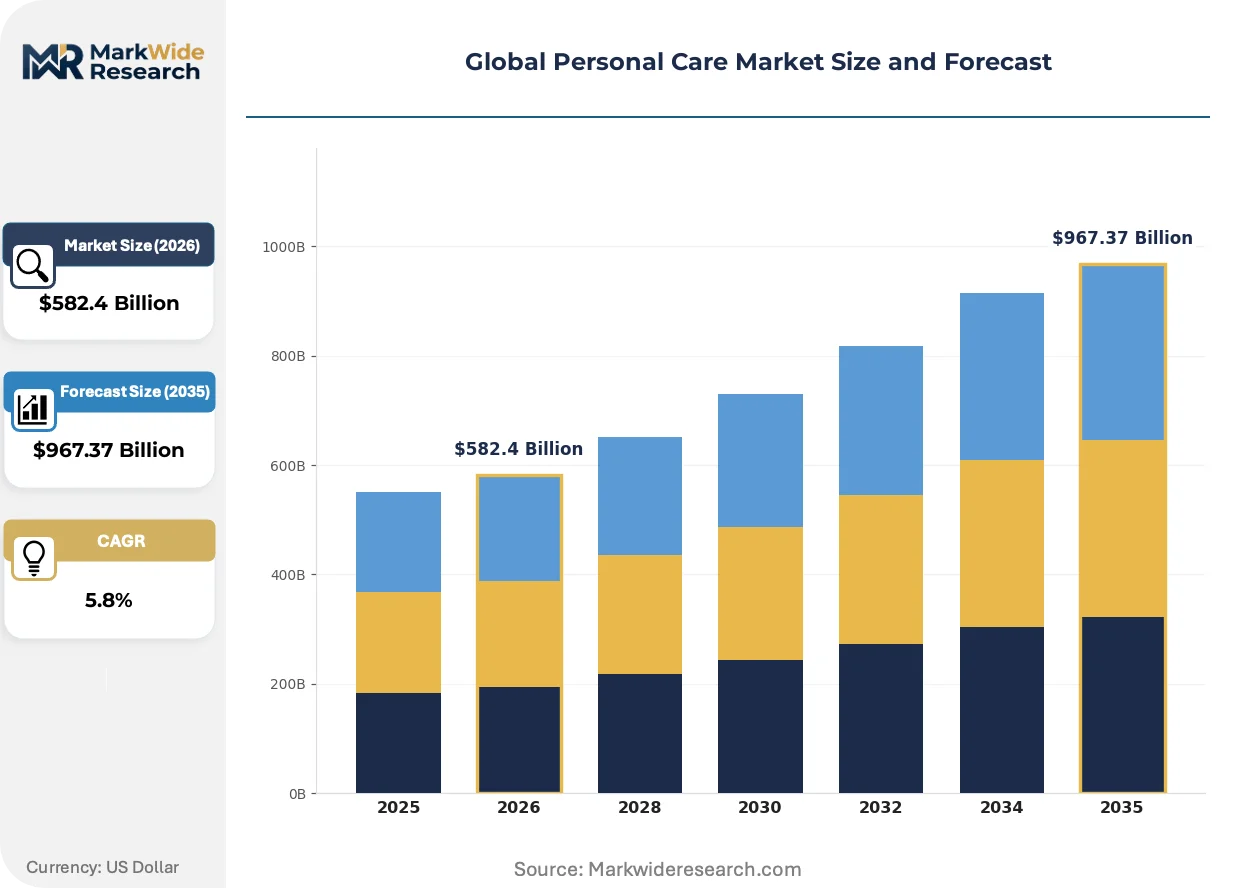
| Market Size in 2026 | $582.4 Billion |
| Market Size in 2035 | $967.37 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Fragrance, Cosmetics Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Pharmacies Customer Type: Men, Women, Children, Seniors Formulation: Organic, Natural, Synthetic, Herbal |
| Companies Covered | The Estée Lauder Companies Inc., Beiersdorf AG, L'Oréal S.A., Coty Inc., Henkel AG & Co. KGaA, Unilever PLC, Shiseido Company Limited, Johnson & Johnson Services, Inc., Procter & Gamble, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Personal Care Market Strategic Shifts
Active ingredient sourcing is pivoting from petroleum derivatives to fermentation and plant cell culture outputs, restructuring supply relationships and cost accounting across the value chain.
Biotechnology-derived ceramides and peptides are converging with traditional cosmetic formulation science to enable clinical-grade efficacy claims in mass-market price tiers. Premium skincare brands in South Korea and France adopt these inputs fastest, compressing the historical gap between dermatological prescription products and over-the-counter positioning. This convergence is forcing legacy petrochemical suppliers to develop bio-based alternatives or exit the personal care segment entirely.
ECHA REACH restrictions on microplastic additives and fragrance allergens compel European manufacturers to reformulate rinse-off products before enforcement deadlines. The industrial consequence is accelerated R&D spending on biodegradable exfoliants and natural fragrance encapsulation technologies. Haircare and body wash segments face the steepest compliance costs, with German and French manufacturers leading substitution efforts.
Subscription-based replenishment models displace single-purchase behavior in developed market skincare routines. Direct-to-consumer platforms capture recurring revenue from millennial and Gen-Z demographics, while traditional pharmacy and department store channels lose foot traffic. This channel rotation is most visible in US and UK urban markets, where algorithm-driven personalization engines drive retention metrics above conventional loyalty programs.
Global Personal Care Market Segmentation
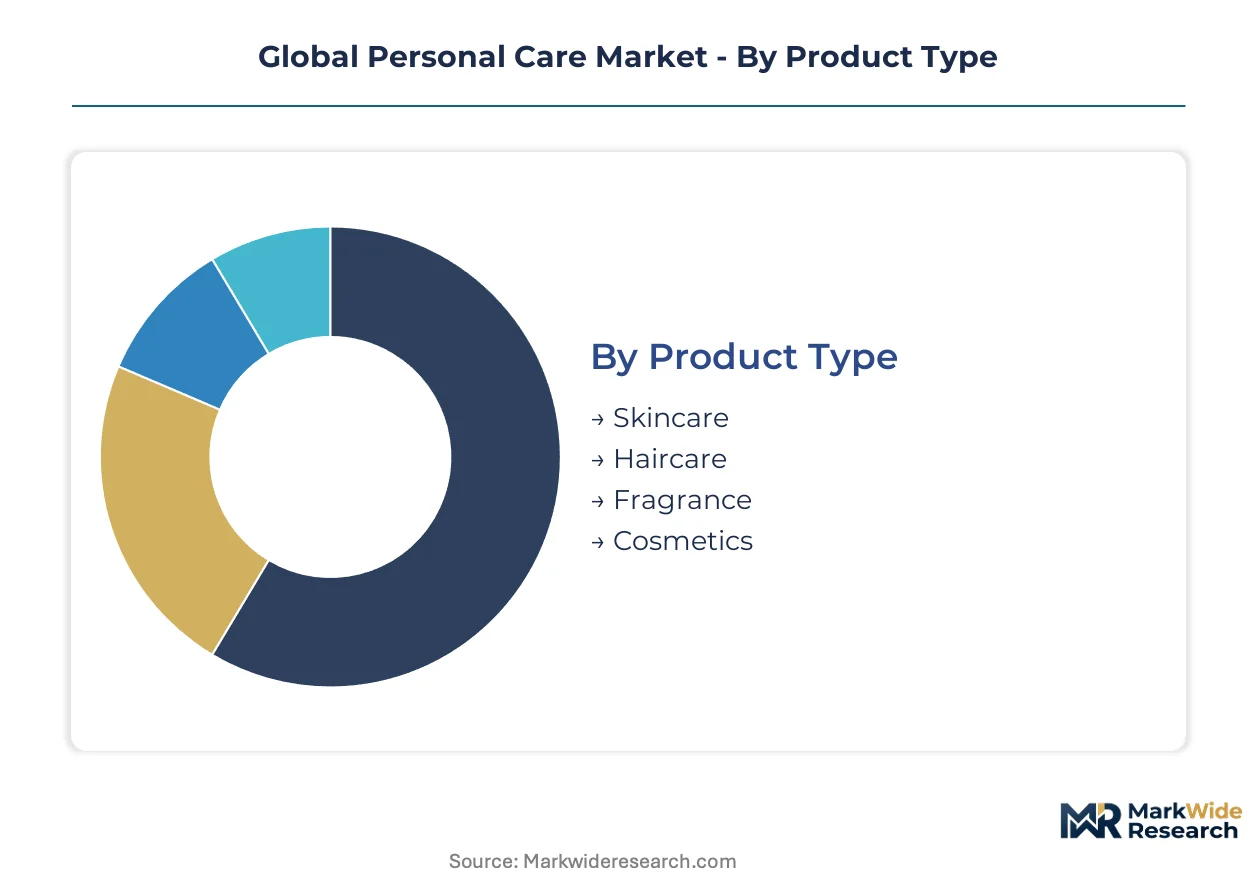
Personal care purchasing decisions hinge on formulation credibility, channel accessibility, and demographic-specific efficacy claims. Segmentation reveals where margin extraction concentrates and which technology platforms command pricing power across distinct consumer archetypes.
Product Type:
Premiumization intensity varies sharply by category, with clinical positioning and ingredient transparency driving willingness-to-pay differentials.
- Skincare:Anti-aging serums and barrier-repair moisturizers incorporate biotechnology-derived ceramides and peptides at pH-calibrated formulations between 4.5 and 7.0. Demand concentrates in South Korea and France where dermatological endorsement channels sustain price premiums. Clinical-grade efficacy claims now penetrate mass-market tiers.
- Haircare:Rinse-off products face acute reformulation pressure from ECHA REACH microplastic bans, accelerating biodegradable exfoliant adoption. German and French manufacturers lead substitution efforts. Clean-label certification requirements extract disproportionate margin premiums in this segment.
- Fragrance:Natural fragrance encapsulation technologies command R&D investment as EU allergen limits tighten.
- Cosmetics:Color cosmetics integrate skin-nourishing actives to justify premium positioning against functional skincare hybrids.
Skincare leads on scale; haircare leads on momentum as regulatory deadlines force portfolio overhaul.
Distribution Channel:
Channel selection determines customer acquisition economics and lifetime value capture, with algorithmic personalization reshaping retention mechanics.
- Online Retail:Direct-to-consumer subscription models displace single-purchase behavior through algorithm-driven personalization engines. US and UK urban markets show the steepest channel rotation. Recurring revenue structures improve unit economics against traditional retail.
- Specialty Stores:Curated assortments and in-skin diagnostic services justify premium positioning for clinical-grade product lines.
- Supermarkets:Mass-market cleansers and basic hygiene products dominate volume throughput.
- Pharmacies:Foot traffic erosion accelerates as millennials and Gen-Z migrate to digital replenishment platforms.
Online Retail commands the steepest expansion trajectory; pharmacies face structural compression.
Customer Type:
Demographic targeting requires distinct formulation architectures, with male-specific and age-adaptive products commanding specialized R&D investment.
- Women:The core volume base for anti-aging and aesthetic enhancement categories across all price tiers.
- Men:Grooming adoption accelerates across Asia-Pacific markets, with India's tier-two cities generating new volume demand for mid-tier products. Male-specific formulations emphasize simplified routines and functional positioning over aesthetic complexity.
- Children:Hypoallergenic and preservative-minimal formulations dominate, with safety certification requirements limiting supplier pools.
- Seniors:Barrier-repair and dermatological protection claims align with skin aging physiology and moisture retention needs.
Women anchor absolute revenue; men provide the sharpest growth inflection.
Formulation:
Raw material sourcing strategy separates margin structures, with petrochemical dependency creating volatility exposure that bio-based alternatives mitigate.
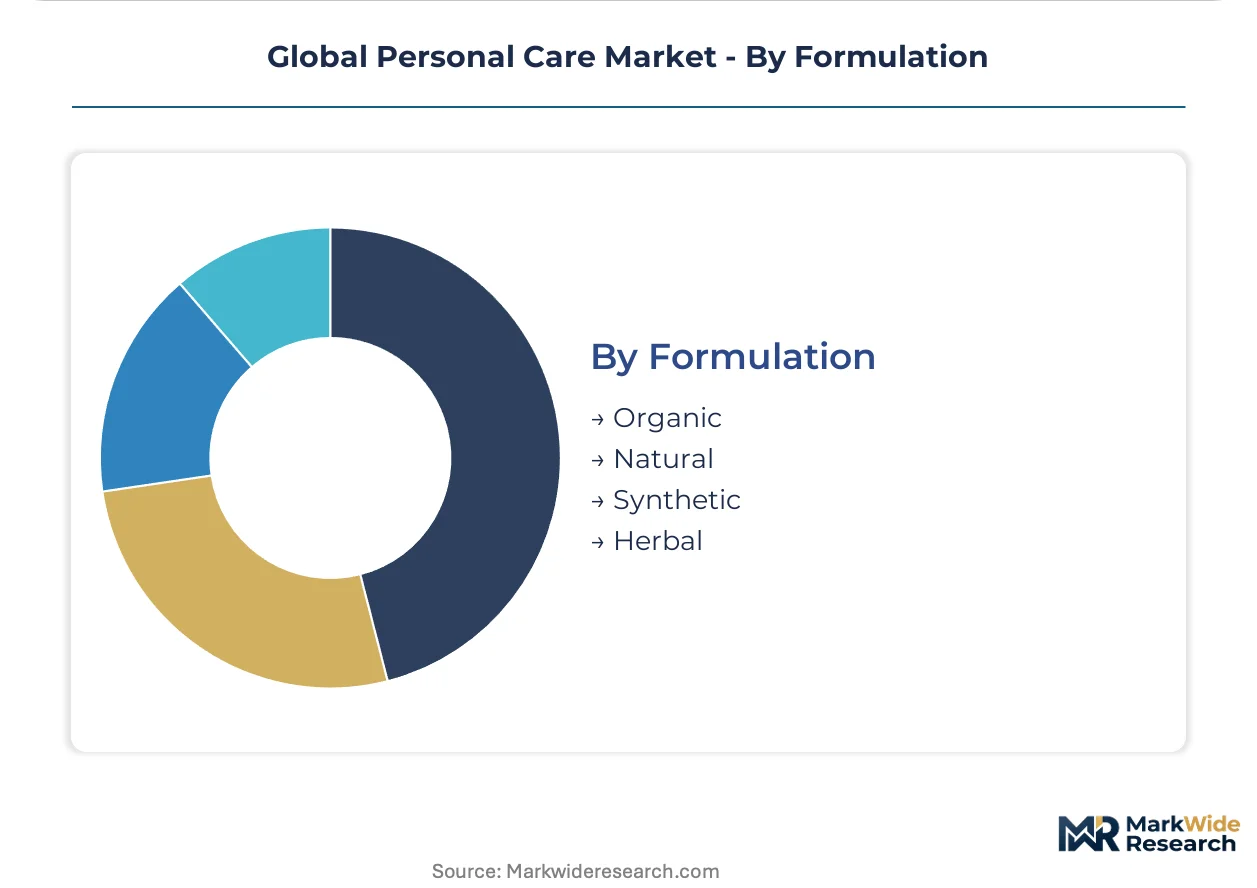
- Natural:Plant-derived surfactants and certified palm-oil-free emulsifier systems realign cost structures as petrochemical feedstock volatility persists. Clean-label certification requirements enable premium positioning against synthetic alternatives.
- Organic:Third-party verification standards limit supplier qualification and concentrate procurement among certified agricultural networks.
- Synthetic:Mass-market dominance persists though margin compression follows crude oil price swings. Captive oleochemical processing in Southeast Asian supply nodes provides defensive cost control.
- Herbal:Traditional medicine positioning resonates in India and China, with ayurvedic and TCM ingredient stories supporting regional brand equity.
Synthetic formulations retain volume leadership; natural segments extract superior margin per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paris anchors the global personal care innovation ecosystem, with Île-de-France hosting the densest concentration of dermatological research institutes and fragrance houses. The industry's geographic footprint stretches across manufacturing clusters in Southeast Asia, regulatory laboratories in Western Europe, and emerging consumption centers in South Asian secondary cities.
United States
Direct-to-consumer subscription models and algorithmic personalization engines drive channel rotation in urban coastal markets. FDA MoCRA cosmetic registration mandates reshape ingredient disclosure obligations for domestic and imported formulations. Greater New York and Los Angeles metropolitan areas concentrate headquarters operations for multinational beauty conglomerates and indie brand incubators.
Germany
Clean-label certification requirements and sustainability-driven procurement patterns elevate demand for palm-oil-free emulsifier systems. ECHA REACH microplastic bans and fragrance allergen limits accelerate reformulation timelines for rinse-off products. The Rhine-Ruhr industrial corridor hosts specialized manufacturing assets for certified natural and organic personal care production.
China
Domestic biotechnology firms and fermentation-based ingredient suppliers expand capacity to serve local premium skincare brands. NMPA cosmetic registration requirements and GB standards for imported items create compliance thresholds favoring established multinationals. Shanghai and Guangzhou anchor e-commerce logistics networks that distribute to tier-two and tier-three city consumers.
India
Rising disposable incomes in secondary urban centers generate volume demand for mid-tier skincare and haircare products tailored to local climate conditions. BIS standards and DGFT import regulations shape competitive access for foreign versus domestic manufacturers. Mumbai and Bengaluru emerge as hubs for ayurvedic-inspired formulation development and digital-native brand launches.
Brazil
ANVISA regulatory harmonization with EU cosmetic safety standards reduces duplicate testing costs for multinational market entry. Tropical climate adaptation drives specialized product development in sun care and antiperspirant categories. São Paulo concentrates distribution infrastructure and professional beauty service channels that influence consumer trial and brand adoption.
Global Personal Care Market Competitive Environment
Global majors compete with regional champions across formulation credibility and channel accessibility, producing a tiered structure where scale-driven conglomerates, biotechnology-anchored specialists, and digital-native indies occupy distinct competitive positions. Market concentration remains moderate, with top-tier players commanding premium pricing through dermatological endorsement and clean-label certification while mid-tier competitors defend volume through retail partnership density. Strategic moves cluster around captive oleochemical processing investments, biotechnology licensing arrangements, and direct-to-consumer platform acquisitions.
Within the scale-driven tier, L'Oréal S.A. and Unilever PLC occupy positions defined by integrated supply chains and multi-brand portfolio architectures. Beiersdorf AG exemplifies the European specialist archetype with concentrated manufacturing assets and regional regulatory expertise. These three entities represent contrasting strategic postures: diversified global reach, mass-market volume optimization, and focused premium positioning respectively.
| Leading Market Players |
|---|
| The Estée Lauder Companies Inc. |
| Beiersdorf AG |
| L'Oréal S.A. |
| Coty Inc. |
| Henkel AG & Co. KGaA |
| Unilever PLC |
| Shiseido Company Limited |
| Johnson & Johnson Services, Inc. |
| Procter & Gamble |
| Others |
Value Chain & Pricing Dynamics
Plant-derived surfactant costs cascade through personal care pricing tiers as petrochemical feedstock volatility destabilizes synthetic formulation economics, compressing margins at the mass-market tier while enabling premium positioning for bio-based alternatives. Clean-label certification requirements extract disproportionate pricing power from natural and organic segments as buyers absorb ingredient transparency premiums.
Pricing Analysis
Input-cost pass-through from oleochemical and fermentation-based ingredient sourcing is reshaping pricing structures across premium, standard, and economy tiers. Price differentiation rests on certification grade—EU Ecolabel and COSMOS standards command measurable premiums—and geographic delivery cost from Southeast Asian processing nodes. Pricing pressure stems from captive oleochemical concentration in Malaysia and Indonesia, which limits supplier negotiation leverage. Mass-market synthetic formulations exhibit highest buyer price sensitivity; clinical-positioned skincare with dermatological endorsement shows lowest elasticity.
Supply Chain Analysis
Workforce availability constraints in German and French specialty chemical manufacturing elevate compensation premiums for formulation chemists with natural emulsifier stabilization expertise. Geographic supply concentration centers on Malaysia, Indonesia, and Germany for oleochemical processing and certified natural production. Raw material dependencies draw from palm oil derivatives, fermentation feedstocks, and petroleum-based surfactants. Single-source vulnerability persists in Southeast Asian oleochemical assets clustered around Kuala Lumpur and Hamburg processing corridors. Distribution runs through direct-to-consumer platforms in US and UK urban markets alongside traditional retail pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The personal care market compounds steadily as regulatory-driven reformulation cycles perpetuate R&D reinvestment and sustain incumbent pricing power across clean-label segments.
For Market Incumbents: Cement formulation credibility through biotechnology licensing arrangements that secure fermentation-based ceramide and peptide pipelines against petrochemical feedstock volatility. Expand captive oleochemical processing in Southeast Asian supply nodes to defend margin position from surfactant cost swings. Prioritize ECHA REACH pre-compliance for microplastic-free rinse-off portfolios ahead of enforcement deadlines. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route into developed market skincare routines, displacing pharmacy foot traffic through algorithm-driven personalization engines. Target India's tier-two cities for mid-tier male grooming and climate-adapted skincare formulations. Pursue ayurvedic-inspired ingredient stories for regional brand equity in Mumbai and Bengaluru. For Investors and Strategic Acquirers: Consolidation pressure builds where dual regulatory compliance timelines strain mid-tier regulatory affairs bandwidth. Long-term viability favors biotechnology-anchored specialists with fermentation capacity and dermatological endorsement channels. Monitor ECHA REACH dossier preparation rates as early signal for reformulation cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Licensing Arrangement | Fermentation-based peptide pipelines secure ingredient supply against petrochemical volatility. |
| Captive Oleochemical Processing Expansion | Malaysian and Indonesian assets reduce surfactant cost exposure for mass-market cleansers. |
| Direct-to-Consumer Platform Launch | Algorithmic personalization captures recurring revenue from millennial and Gen-Z demographics. |
| ECHA REACH Pre-Compliance Investment | Microplastic-free reformulation ahead of deadlines opens premium positioning in European rinse-off. |
| Clinical-Grade Efficacy Certification | Dermatological endorsement channels sustain pricing power in anti-aging and barrier-repair segments. |
Study Parameters
Multiple input streams—primary interviews with brand managers, category buyers at retailers, formulation R&D directors, and supply chain planners; secondary validation through Nielsen retail audit data, customs and trade records, SEC 10-K filings, and ECHA REACH dossier databases—were reconciled through bottom-up and top-down triangulation to construct market estimates.
Historical volume and value trajectories were cross-referenced against expert panel inputs to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, customer demographic, and formulation sourcing strategy. CAGRs were derived from trend extrapolation moderated by regulatory event timing and biotechnology adoption curves. Industry-specific forecast inputs incorporated ECHA REACH enforcement schedules and NMPA cosmetic registration throughput rates.
The model assumes a particular technology adoption path; alternative pathways for fermentation-based active ingredient production would alter the outlook if scale-up timelines accelerate or bioreactor capital costs decline faster than projected. Practitioners should monitor ECHA REACH microplastic ban enforcement rigor and India tier-two city disposable income trajectories for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Shaving Foam Market
Beauty & Personal Care
Netherlands Sustainable Personal Care Market
Beauty & Personal Care
Brazil Beauty and Personal Care Products Market
Beauty & Personal Care
Brazil Sustainable Personal Care Market
Beauty & Personal Care
US Skincare Market
Beauty & Personal Care
Luxury Personal Care and Cosmetics Market
Beauty & Personal Care
Germany Lip Care Products Market
Beauty & Personal Care
Bath Oil Market
Beauty & Personal Care
Asia Pacific Beauty Fridges Market
Beauty & Personal Care
US Natural Personal Care Market
Beauty & Personal Care
Anti-Acne Facial Serum Market
Beauty & Personal Care
Body Balm Market
Beauty & Personal Care
Nail Lamps Market
Beauty & Personal Care
Digitalization of Beauty Industry Market
Beauty & Personal Care
Organic Liquid Soaps Market
Beauty & Personal Care
LAMEA Hair Removal Wax Market