
 Nail Art Tools and Accessories Market | 2026-2036
Nail Art Tools and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Nail Art Tools and Accessories Market Foresight
ISO 22716 Good Manufacturing Practices certification is bifurcating the competitive landscape between salon-grade suppliers and unverified commodity importers. OPI Products leverages its vertically integrated pigment labs to sustain color consistency across professional tool lines. KOBOS anchors its position through precision stainless-steel manufacturing in Solingen-style cutlery clusters. Sally Beauty competes on channel density, occupying North American retail corridors with private-label accessory sets.
Nail art tools and accessories comprise handheld instruments and supplementary items engineered from stainless steel alloys, medical-grade silicone, or laminated hardwoods, manufactured through CNC grinding, injection molding, or hand-finishing processes to enable decorative lacquer application, cuticle management, and surface texturing on human nails. The professional use application segment dominates absolute volume as licensed technicians replace disposable tools at regulated intervals, while the silicone material category captures expanding margin pools due to hypoallergenic properties and dishwasher-safe durability demanded by mobile service providers. DIY application trails in value per unit but extends reach through social commerce channels where individual purchasers replicate salon techniques.
FDA cosmetic labeling requirements and EU REACH substance restrictions govern nickel release thresholds from metal implements and phthalate content in plastic handles, compelling manufacturers to reformulate alloys or migrate toward compliant polymer substitutes. South Korea's MFDS maintains separate cosmetic-grade tool standards that exceed baseline ISO specifications, creating a dual-certification burden for exporters targeting Seoul's premium salon supply chains. Stakeholders must monitor evolving state-level cosmetology board regulations in the United States, where Texas and California periodically tighten sterilization protocol mandates that determine which tool categories require single-use disposability versus autoclave-compatible construction.
Market Dynamics
Platform-based booking infrastructure is compressing the traditional salon supply chain by enabling independent technicians to source tools directly, bypassing wholesale distributors and forcing manufacturers to build direct-to-professional fulfillment capabilities.
Growth Catalysts
- REACH substance restrictions:EU nickel release thresholds are accelerating migration toward medical-grade polymer handles, opening margin expansion for compliant alloy reformulators.
- Mobile service providers:Platform-booked nail technicians now represent the fastest-expanding buyer segment, demanding portable sterilization-compatible tool kits.
- Seoul's district-level academies:South Korea's influencer-driven tool aesthetics command premium positioning, pulling global design standards toward specialized finishes.
Market Restraints
- Solingen-style cutlery cluster concentration:Precision stainless-steel manufacturing remains geographically concentrated, creating single-source vulnerability for specialized implements.
- Dual-certification burden:Exporters targeting Seoul's premium supply chains must satisfy MFDS cosmetic-grade standards exceeding baseline ISO 22716 specifications.
- Silicone raw material volatility:Medical-grade silicone feedstock costs fluctuate with semiconductor sector demand, compressing margin predictability for hypoallergenic tool lines.
Strategic Opportunities
- Texas and California sterilization mandates:State-level cosmetology board regulations tightening autoclave-protocol requirements create first-mover advantage for single-use disposable specialists.
- Social commerce channel emergence:DIY application segments replicate salon techniques through video-driven tutorials, enabling direct-to-consumer tool bundling.
- ISO 22716 certification gap:Unverified commodity importers face bifurcation pressure, creating acquisition targets for salon-grade suppliers seeking backward integration into pigment labs.
Industry Challenges
- Multi-jurisdiction compliance timelines:Manufacturers must sequence FDA cosmetic labeling updates, EU REACH reformulations, and MFDS cosmetic-grade submissions without product line fragmentation.
- CNC grinding talent scarcity:Hand-finishing craftsmanship clusters in Solingen-style regions face generational transition gaps as automated injection molding displaces traditional apprenticeship pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nail Art Tools and Accessories Market |
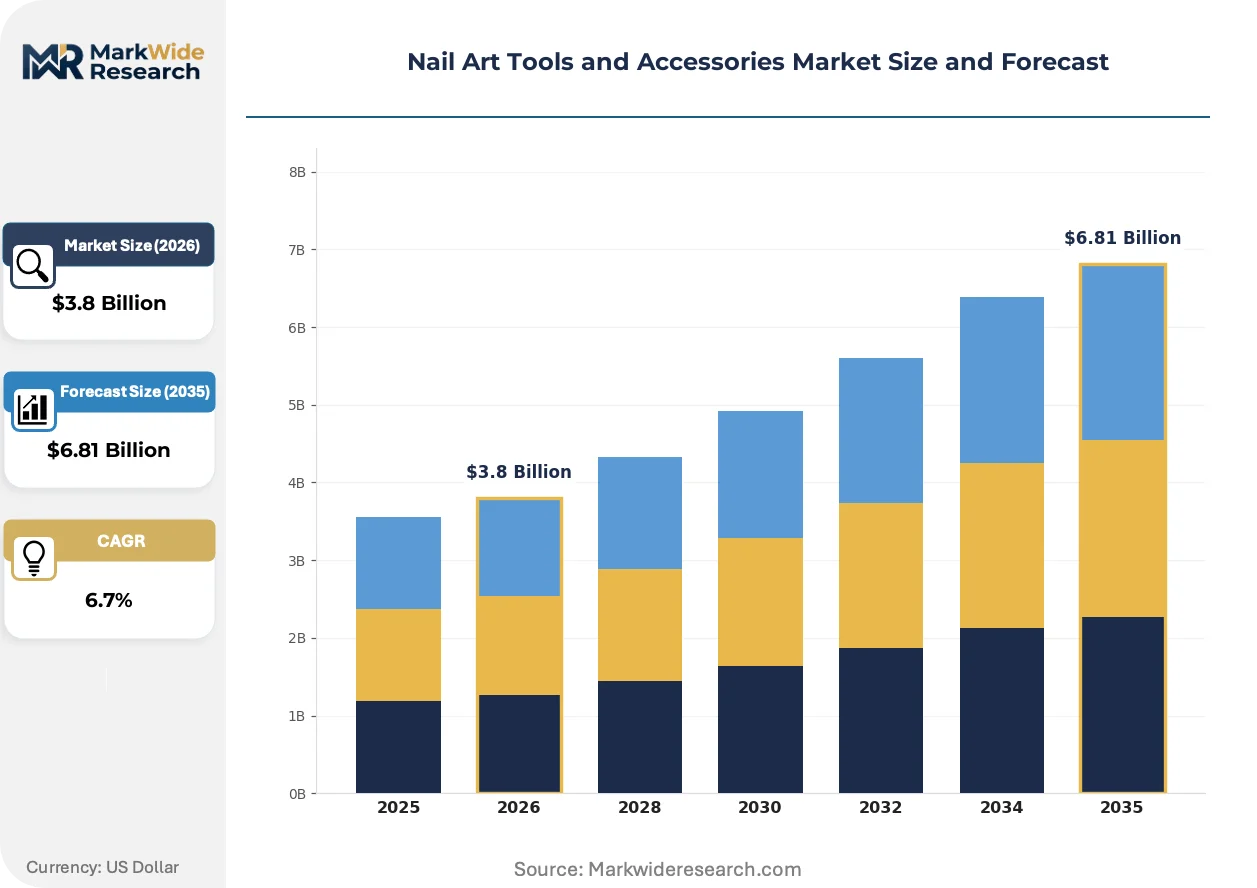
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nail Brushes, Nail Folders, Dotting Tools, Stampers Application: Professional Use, DIY, Nail Salons, Mobile Services Material: Plastic, Metal, Wood, Silicone Customer Type: Individuals, Beauticians, Retailers, Wholesalers |
| Companies Covered | KAI, OPI Products, KOBOS, CND (Creative Nail Design), Sally Beauty, Kowell, Wusthof, Victorinox, Zwilling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nail Art Tools and Accessories Market Shifts & Advancements
Active reshaping of this market stems from three convergent forces: material science breakthroughs in hypoallergenic substrates, regulatory fragmentation across major economies, and platform-mediated disintermediation of traditional wholesale channels.
Medical-grade silicone is supplanting nickel-alloy implements in professional-grade cuticle pushers and nail drills. Licensed technicians operating mobile service platforms are adopting dishwasher-safe silicone alternatives at accelerating rates. This substitution is compressing traditional metal-tool replacement cycles while opening premium pricing tiers for hypoallergenic certification.
EU REACH substance restrictions are tightening nickel release thresholds from metal implements and phthalate content in plastic handles. Manufacturers must reformulate alloys or migrate toward compliant polymer substitutes to maintain European market access. South Korean exporters targeting dual-certification status face the most complex compliance burden, as MFDS standards exceed baseline REACH specifications.
Platform-based booking systems are fragmenting buyer concentration across thousands of independent technicians. Traditional wholesale distributors serving salon chains are losing volume to direct-to-professional e-commerce channels. This disintermediation is most visible in Seoul's district-level academy networks, where influencer-curated tool aesthetics drive purchase decisions outside conventional supply relationships.
Nail Art Tools and Accessories Market Segmentation
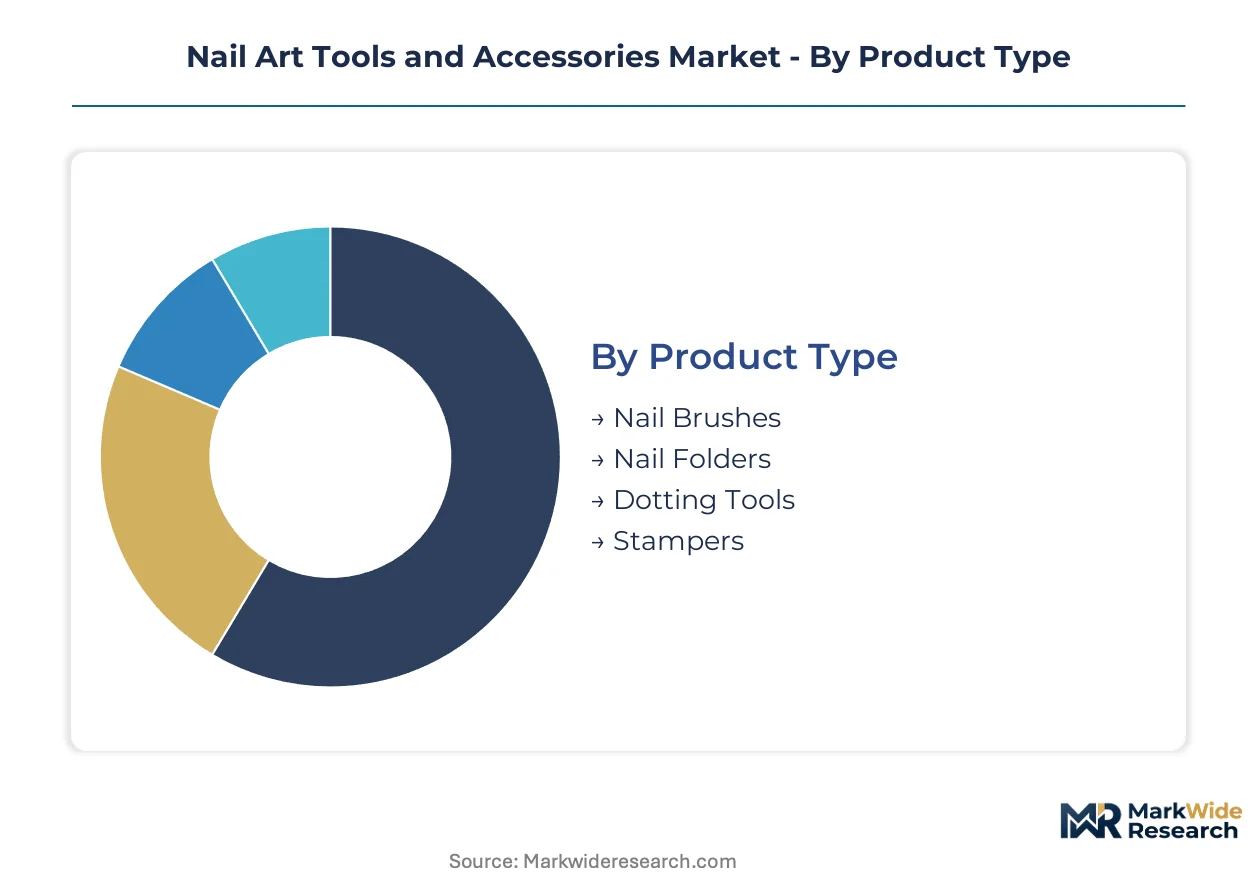
Segmentation in nail art tools and accessories determines sourcing strategy, certification requirements, and channel economics. Material composition dictates regulatory jurisdiction, while application context shapes sterilization protocols and replacement cycles. Understanding these divisions reveals where margin pools concentrate and which buyer segments are fragmenting traditional distribution.
Product Type:
Professional-grade implements flow through salon supply distributors and direct-to-technician platforms, while consumer tools dominate social commerce and mass retail channels.
- Nail Brushes:Synthetic and natural filament varieties engineered for gel, acrylic, and polish application with tapered or flat profiles. Demand clusters in South Korea's district-level academies where influencer-curated brush shapes command premium positioning.
- Nail Folders:Abrasive implements constructed from glass, crystal, or coated metals for edge shaping and surface smoothing. Professional salons in Texas and California drive volume as state sterilization mandates accelerate replacement cycles.
- Dotting Tools:Dual-ended instruments with spherical metal or plastic tips for decorative pattern creation.
- Stampers:Silicone-tipped implements for transferring etched designs from metal plates to nail surfaces.
Nail brushes dominate installed base. Stampers are where expansion concentrates.
Application:
Cost tier stratification separates single-use disposables from autoclave-compatible capital equipment, with regulatory compliance costs widening the gap between professional and consumer price points.
- Professional Use:Licensed technicians operating under state cosmetology board oversight require ISO 22716-certified implements with traceable sterilization histories. EU REACH nickel thresholds and FDA cosmetic labeling rules are accelerating migration toward medical-grade polymer substitutes.
- Mobile Services:Platform-booked independent technicians demand portable, dishwasher-safe tool kits optimized for travel between client locations. This segment is expanding most quickly as booking infrastructure compresses traditional salon supply chains.
- DIY:Individual purchasers replicating salon techniques through video tutorials, sourcing through social commerce channels.
- Nail Salons:Established brick-and-mortar operations with fixed sterilization equipment and wholesale distributor relationships.
Professional use dominates installed base. Mobile services are where expansion concentrates.
Material:
Volume concentration in metal alloys is shifting as regulatory pressure and mobile service needs drive substitution toward polymers and silicone.
- Silicone:Medical-grade formulations for hypoallergenic cuticle pushers, stampers, and drill bits with dishwasher-safe durability. Licensed technicians on mobile platforms are adopting these alternatives at accelerating rates as sterilization portability becomes critical.
- Metal:Stainless steel alloys from Solingen-style cutlery clusters for precision implements requiring edge retention. EU REACH nickel release thresholds are forcing alloy reformulation or market exit for non-compliant suppliers.
- Plastic:Injection-molded handles and disposable implements subject to FDA phthalate content restrictions.
- Wood:Laminated hardwoods for ergonomic handles and traditional finishing tools.
Metal dominates installed base. Silicone is where expansion concentrates.
Customer Type:
Procurement authority is fragmenting as platform-based booking empowers individual technicians to source directly, bypassing traditional wholesale intermediaries.
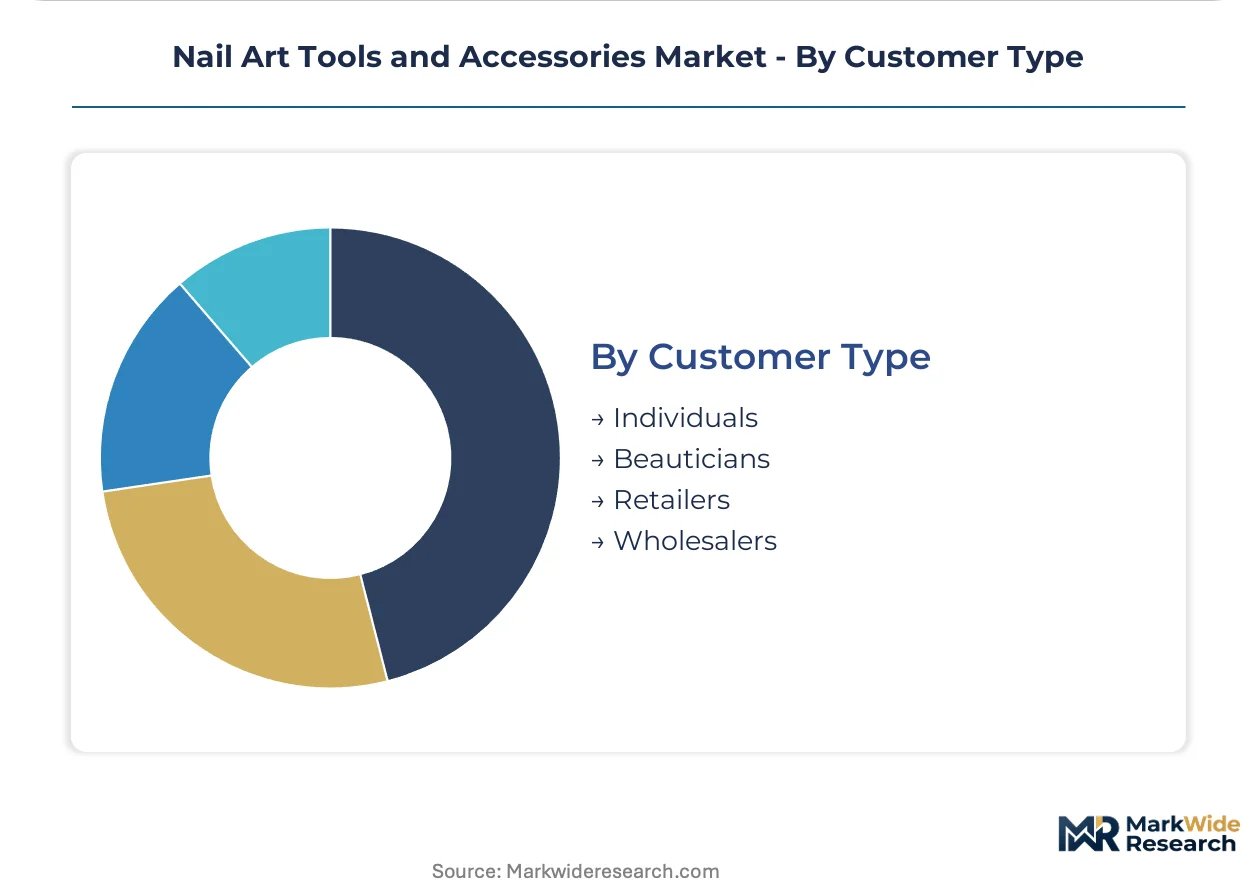
- Beauticians:Licensed professionals with recurring tool replacement obligations under state sterilization mandates. This segment captures expanding margin pools as certification requirements bifurcate the supplier landscape between verified and unverified sources.
- Individuals:End consumers purchasing through social commerce and mass retail for DIY application.
- Retailers:Beauty supply chains and specialty stores curating private-label accessory sets.
- Wholesalers:Traditional distributors serving salon chains, losing volume to direct-to-professional channels.
Beauticians dominate installed base. Individuals are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH substance restrictions in the European Union are accelerating alloy reformulation across export-dependent manufacturers, while South Korea's MFDS cosmetic-grade standards create dual-certification thresholds that reshape competitive access.
United States
State cosmetology boards in Texas and California mandate autoclave-compatible construction for reusable implements, compressing replacement cycles for metal tools. FDA cosmetic labeling rules govern phthalate content in plastic handles, forcing polymer substitution in imported accessories. Sally Beauty occupies dense retail corridors across North American metropolitan markets with private-label distribution.
Germany
Solingen-style cutlery clusters anchor precision stainless-steel manufacturing for specialized nail implements requiring edge retention. ECHA nickel release thresholds under REACH compel alloy reformulation or market exit for non-compliant suppliers. Zwilling and Wusthof exemplify heritage metalworking consolidation in this industrial concentration.
South Korea
Seoul's district-level nail academies drive influencer-curated tool aesthetics that command premium positioning in professional supply chains. MFDS cosmetic-grade standards exceed baseline ISO 22716 specifications, creating dual-certification burdens for exporters targeting premium salons. KOBOS and Kowell represent domestic manufacturing leverage in this regulatory environment.
Japan
KAI anchors precision blade manufacturing for cuticle implements through established metalworking expertise. METI industrial standards intersect with cosmetic-grade tool specifications, shaping export compliance architecture. Tokyo-Osaka salon networks sustain demand for autoclave-compatible professional-grade instruments.
China
Injection-molded plastic handle production concentrates in Yangtze River Delta manufacturing zones serving global accessory demand. SAMR cosmetic labeling convergence with international standards reduces friction for export-oriented fabricators. CNC grinding capacity expansion targets mid-tier professional implement segments.
Nail Art Tools and Accessories Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with ISO 22716 Good Manufacturing Practices bifurcating verified salon-grade suppliers from unverified commodity importers. The vendor base stratifies between heritage metalworking conglomerates, vertically integrated pigment laboratories, and platform-native direct-to-professional distributors. Three archetypes dominate: Solingen-style precision manufacturers, cosmetic-chemistry-integrated tool lines, and channel-dense retail consolidators. Competitive moves concentrate on backward integration into pigment supply and direct-to-technician fulfillment capability construction.
Among heritage metalworking specialists, Zwilling, Wusthof, and KAI exemplify blade-precision manufacturing archetypes that leverage established cutlery expertise for professional implement segments. OPI Products and CND occupy positions tied to cosmetic-chemistry integration, while Sally Beauty represents channel-density retail consolidation across North American corridors. KOBOS and Kowell anchor South Korean domestic manufacturing leverage against import dependency.
| Leading Market Players |
|---|
| KAI |
| OPI Products |
| KOBOS |
| CND (Creative Nail Design) |
| Sally Beauty |
| Kowell |
| Wusthof |
| Victorinox |
| Zwilling |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day inventory cycles for Solingen-style precision implements compress pricing power for stainless steel alloy suppliers while amplifying margin capture for medical-grade silicone formulators with shorter replenishment horizons.
Pricing Analysis
Certification level creates the primary spread between ISO 22716-verified salon-grade implements and unverified commodity imports. Three-tier pricing structure across premium certified, standard compliant, and economy unverified levels dominates transactional models. Cost compression in economy metal tiers intensifies because REACH nickel reformulation raises alloy input costs. Mobile service providers exhibit lowest price sensitivity due to sterilization portability premiums, while DIY social commerce buyers drive volume at thin margins.
Supply Chain Analysis
Inventory cycles for Solingen-style cutlery cluster outputs run sixty-to-ninety days, constraining responsiveness to demand spikes from platform-booked technicians. Manufacturing concentrates in Germany, South Korea, and China for distinct tiers: precision metalworking, influencer-curated aesthetics, and injection-molded handles respectively. Feedstock draws from medical-grade silicone suppliers whose pricing fluctuates with semiconductor sector demand. Single-source vulnerability pervades Solingen-style stainless steel specialization. Distribution runs through direct-to-professional e-commerce channels that disintermediate traditional wholesale distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-based booking infrastructure represents an early-cycle expansion tailwind as independent technicians fragment procurement authority and create addressable white space for specialized tool suppliers.
For Market Incumbents: Fortify certification moats by accelerating ISO 22716 audit coverage for backward-integrated pigment labs before unverified commodity importers consolidate. Expand captive silicone formulation capacity to offset medical-grade feedstock volatility threatening margin stability. Defend against direct-to-professional platform disintermediation by building proprietary technician-facing fulfillment capabilities. For New Entrants and Emerging Players: Anchor in mobile service provider segments where sterilization-portable tool kits face supply shortages from legacy manufacturers optimized for salon chain volumes. Target Seoul's district-level academy networks where influencer-curated aesthetics command premium positioning absent from Western catalogs. Pursue go-to-market partnerships with booking platforms that aggregate technician demand for bundled kit procurement. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified beauty conglomerates with underoptimized nail tool divisions lacking ISO 22716 certification infrastructure. Long-term viability hinges on regulatory compliance architecture rather than brand heritage alone. Monitor Texas and California sterilization mandate tightening as inflection signal for single-use disposable specialists.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 22716 Certification Investment | Salon-grade suppliers bifurcate market access from unverified commodity importers facing REACH exclusion. |
| Direct-to-Professional Platform Launch | Booking infrastructure enables manufacturer bypass of wholesale distributors serving declining salon chains. |
| Medical-Grade Silicone Backward Integration | Captive formulation secures margin against semiconductor sector demand volatility in feedstock markets. |
| Seoul Academy Network Partnership | Influencer-curated tool aesthetics command premium positioning in fastest-expanding professional segment. |
| Single-Use Disposable Specialization | Texas and California sterilization mandates create first-mover advantage in regulated replacement cycles. |
Research Methodology
Desk research of customs trade databases, EU ECHA substance restriction filings, and FDA cosmetic labeling guidance preceded structured interviews with salon supply distributors, platform booking executives, mobile nail technicians, and cutlery cluster manufacturing managers. Secondary validation drew from South Korea MFDS cosmetic-grade standards documentation, state cosmetology board regulatory updates, and ISO certification registry records. Bottom-up technician demand modeling and top-down supply chain value aggregation were triangulated against trade flow data.
Variance decomposition across material substitution rates, platform adoption curves, and regulatory compliance timelines shaped analytical framework construction over the projection horizon. Segmentation dimensions modeled include product type, application context, material composition, and customer procurement authority alongside jurisdiction-specific certification tier. CAGRs were derived from fitted adoption curves rather than linear extrapolation. Forecast inputs incorporated silicone feedstock cost volatility indices and state-level sterilization mandate implementation schedules.
Decision-makers should treat outputs as directional under assumptions of continued platform disintermediation and stable REACH nickel threshold enforcement; material deviation in regulatory timelines or booking platform consolidation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Beauty Tools Market
Beauty & Personal Care
Middle East Herbal Shampoo Market
Beauty & Personal Care
Bangladesh Shampoo Market
Beauty & Personal Care
Mass Beauty & Personal Care Products Market
Beauty & Personal Care
Online Cosmetics Market
Beauty & Personal Care
Switzerland Haircare Market
Beauty & Personal Care
Canada Dermocosmetics Market
Beauty & Personal Care
Colombia Hair Care Market
Beauty & Personal Care
Beauty Devices Market
Beauty & Personal Care
South America Hair Styling Products Market
Beauty & Personal Care
Artificial Nails Market
Beauty & Personal Care
Hair Wig Market
Beauty & Personal Care
Depilatories Market
Beauty & Personal Care
Anti-Aging Beauty Device Market
Beauty & Personal Care
Europe Hair Styling Products Market
Beauty & Personal Care
South Korea Beauty Fridges Market