
 US Personal Care Contract Manufacturing Market | 2026-2036
US Personal Care Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
US Personal Care Contract Manufacturing Market Intelligence
Direct-to-consumer distribution is tilting toward turnkey contract manufacturers that bundle formulation with fulfillment. Fareva leverages integrated R&D and manufacturing campuses to anchor large-volume programs for national retail accounts. Intercos S.p.A. competes through color cosmetics specialization and speed-to-market capabilities. Eco Lips, Inc. occupies a defensible niche in lip balm contract manufacturing, sustaining regional brand relationships.
US personal care contract manufacturing covers the outsourced production of topical consumer products including emulsions, surfactant-based cleansers, and anhydrous balms, typically involving compounding, filling, and secondary packaging under client specifications. The primary commercial purpose is enabling brand owners to scale production without capital-intensive facility investments. Skin care commands the largest formulation service volume given complex active ingredient handling and stability testing requirements. Custom formulation represents the fastest-growing service segment as indie brands seek differentiated ingredient stories. Private label remains mature, with margin pools compressing amid retailer consolidation.
FDA oversees cosmetic ingredient safety under the Modernization of Cosmetics Regulation Act, while state attorneys general in California enforce Proposition 65 chemical disclosure mandates that shape formulation choices. EPA regulations on volatile organic compounds affect aerosol and fragrance manufacturing processes, altering equipment requirements. OSHA standards govern batching facility worker exposure limits, influencing plant design and automation investments. Stakeholders must monitor evolving state preemption debates and ingredient ban proposals to anticipate reformulation demand cycles.
Market Dynamics
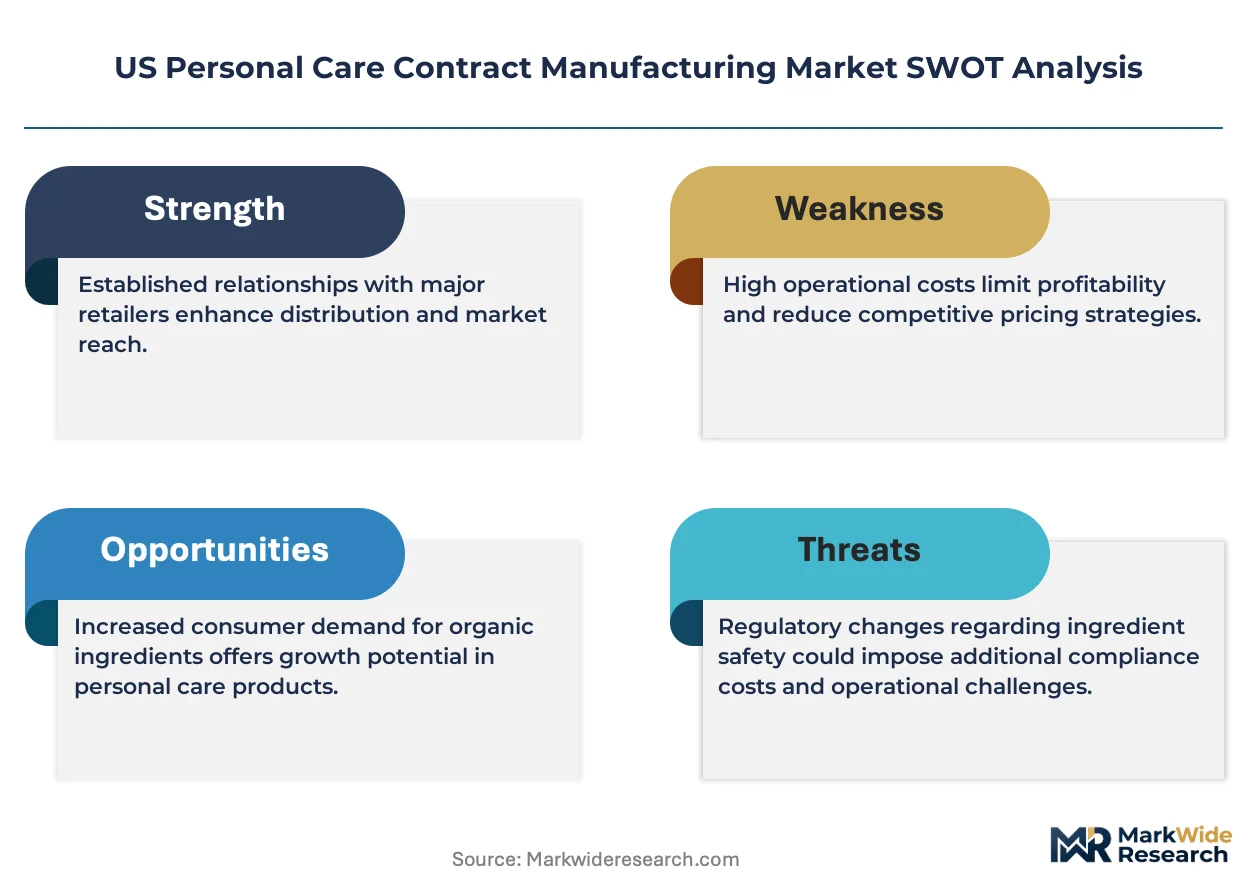
Clean beauty certification requirements are compressing formulation timelines and forcing contract manufacturers to integrate stability testing and regulatory documentation into standard service bundles. This structural pressure favors manufacturers with captive analytical laboratories and pre-validated ingredient libraries.
Growth Catalysts
- California Proposition 65 enforcement:State attorneys general actions on chemical disclosure are pushing indie brands toward compliant contract manufacturers with established documentation systems.
- Direct-to-consumer channel expansion:Digital-native skin care brands require turnkey production partners that bundle formulation with fulfillment infrastructure and inventory management.
- Biotechnology-derived actives:Peptide and postbiotic ingredient handling demands specialized compounding equipment that contract manufacturers amortize across multiple client programs.
Market Restraints
- Specialty chemical import concentration:Key emulsifiers and preservative systems source primarily from German and Swiss suppliers, exposing US manufacturers to trans-Atlantic logistics volatility.
- Modernization of Cosmetics Regulation compliance costs:FDA facility registration and adverse event reporting requirements impose fixed administrative burdens that disproportionately constrain small-batch manufacturers.
- Equipment substitution limitations:Aerosol propellant alternatives to volatile organic compounds require capital-intensive pressurized filling lines that few contract manufacturers maintain.
Strategic Opportunities
- Men's grooming formulation services:Underdeveloped contract manufacturing capacity for male-targeted skin and hair care creates white space for manufacturers with gender-specific positioning expertise.
- Texas and Florida production expansion:Lower facility costs and favorable tax treatment in southern states attract manufacturers seeking alternatives to California and New Jersey concentration.
- Waterless and solid format innovation:Anhydrous balm and shampoo bar production leverages existing equipment while meeting sustainability-driven brand positioning requirements.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise in natural preservative systems and clean label stability remains concentrated among practitioners with 15-plus years of experience.
- Good Manufacturing Practice certification timelines:Third-party audits for ISO 22716 compliance extend 8-14 months, delaying new manufacturer market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Personal Care Contract Manufacturing Market |
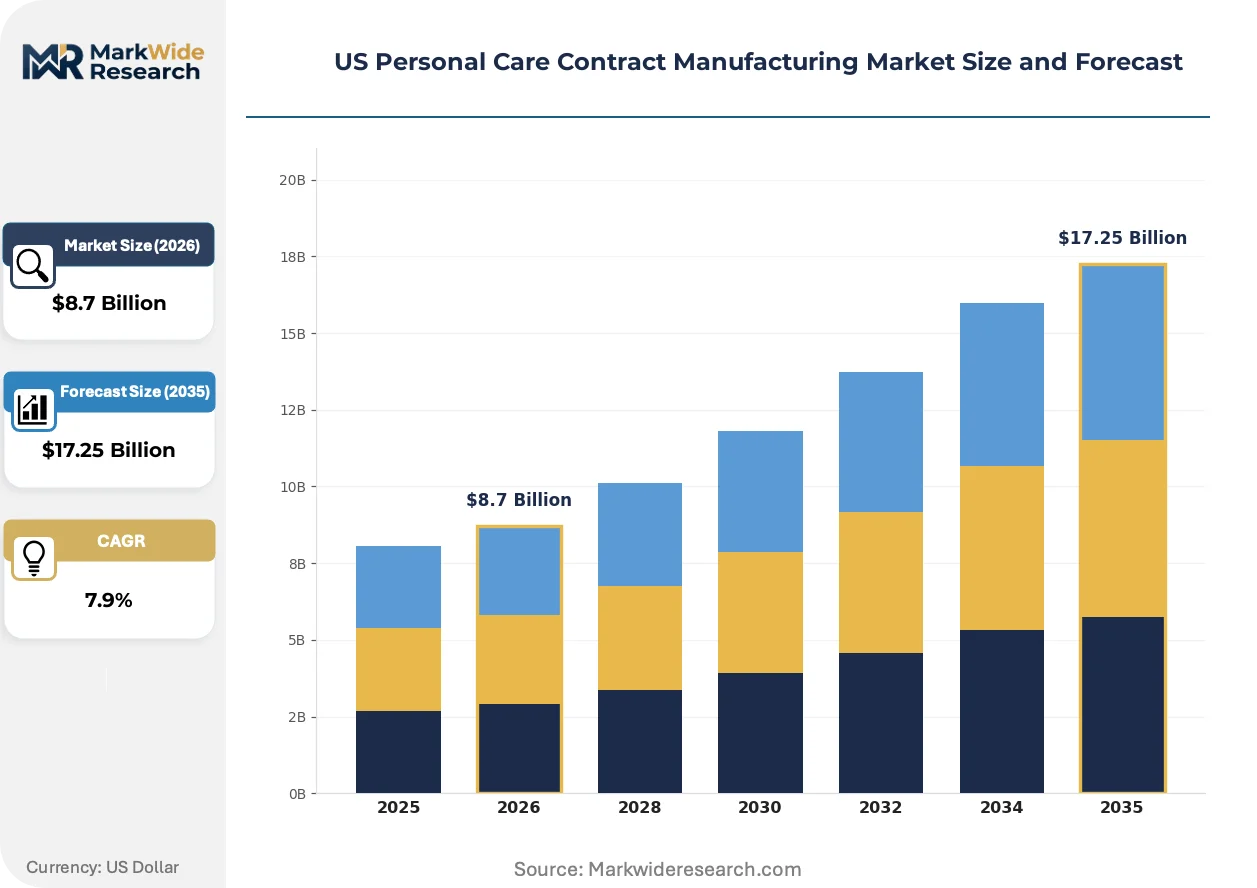
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.25 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skin Care, Hair Care, Oral Care, Body Care Packaging Type: Tubes, Bottles, Jars, Pouches Service Type: Private Label, Custom Formulation, Filling Services, Labeling End User: Retailers, E-Commerce, Distributors, Specialty Stores |
| Companies Covered | Eco Lips, Inc., Fareva, Intercos S.p.A., Biogenesis, NuWorld, 220 Laboratories, Accupack Midwest, Inc., Bright International, Verla International Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Personal Care Contract Manufacturing Market Strategic Shifts & Innovations
Digital formulation platforms are compressing the traditional sample-and-revision cycle, enabling brands to specify performance targets and receive validated prototypes without iterative bench work. This technological shift is redistributing value from manual compounding expertise toward algorithmic ingredient matching and predictive stability modeling.
Artificial intelligence-driven formulation software is virtualizing the initial development phase for emulsion-based skin care products. Indie brands with limited technical staff adopt these platforms to generate starter formulas that contract manufacturers refine for scale-up. The technology is virtualizing the traditional role of in-house cosmetic chemists and compressing the value captured by full-service formulation houses.
EPA volatile organic compound regulations for aerosol and fragrance manufacturing are mandating equipment retrofits and process revalidations. Manufacturers serving prestige fragrance clients face capital allocation decisions between compliance upgrades and format diversification into pump sprays and solid perfumes. California-based contract manufacturers bear the strictest enforcement burden, creating geographic differentiation in regulatory compliance costs.
Brand procurement teams now specify outcome-based service agreements that tie manufacturer fees to stability test passage rates and on-time delivery performance. Direct-to-consumer brands with subscription models prioritize inventory flexibility over unit cost minimization. This behavioral shift is most pronounced among New Jersey and California-based brands with high SKU velocity and seasonal demand spikes.
US Personal Care Contract Manufacturing Market Segmentation
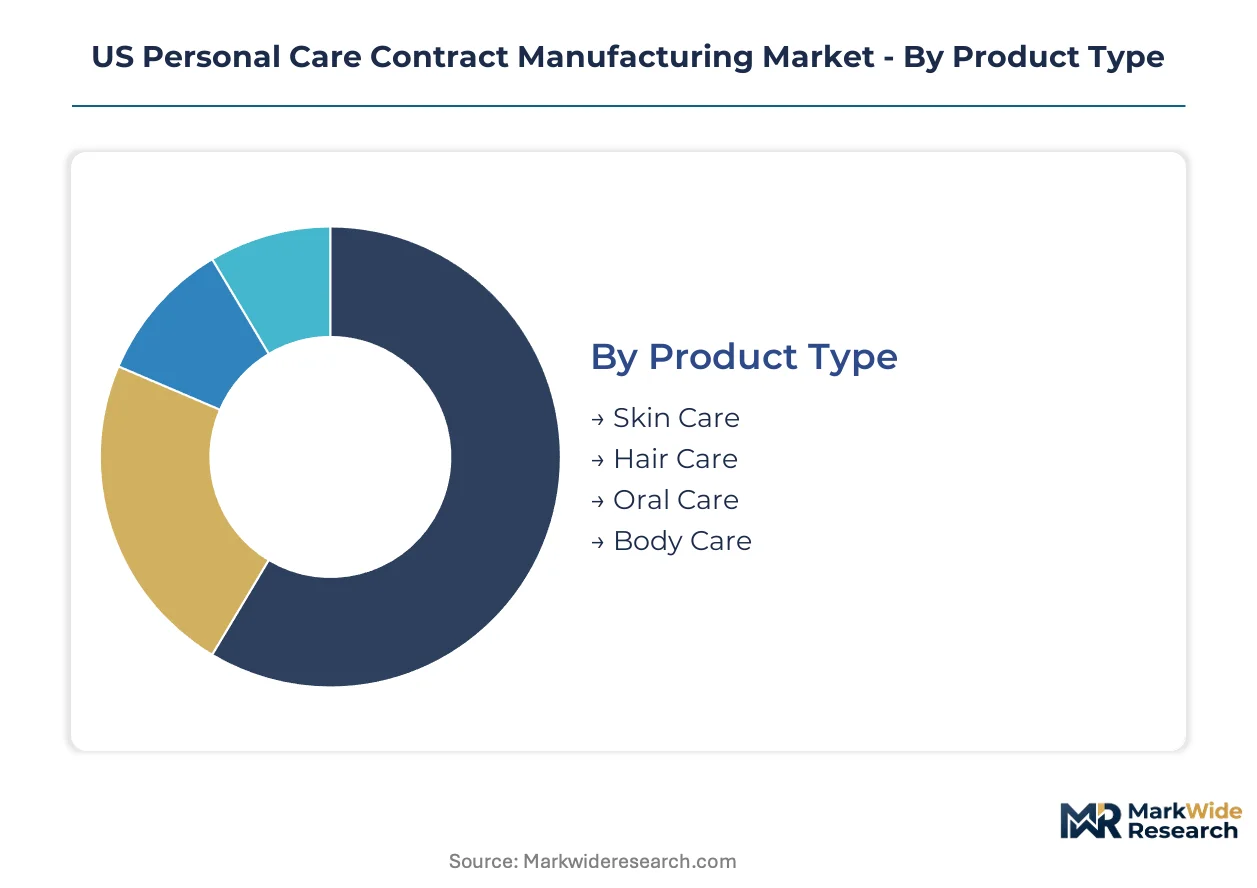
Contract manufacturing services in US personal care fragment across four operational dimensions. Each segmentation axis reveals distinct margin profiles, equipment requirements, and client relationship structures that shape competitive positioning.
Product Type:
Application focus determines formulation complexity, stability testing burdens, and regulatory documentation intensity across manufacturing contracts.
- Skin Care:Emulsion-based products demand sophisticated active ingredient handling and extended stability protocols. California-based indie brands drive demand for peptide and retinoid compounding services that require specialized R&D infrastructure.
- Hair Care:Surfactant systems and conditioning polymers require pH-controlled batching equipment with viscosity management capabilities. New Jersey formulation clusters serve direct-to-consumer brands with high-SKU velocity programs.
- Oral Care:FDA-regulated dentifrice and mouthwash production requires validated manufacturing environments with microbial control systems.
- Body Care:Lower-complexity lotions and washes compete primarily on throughput and packaging integration speed.
Skin Care holds installed capacity. Custom Formulation is rotating up the share rankings.
Packaging Type:
Format selection constrains filling line configuration, automation investment, and downstream logistics partnerships.
- Tubes:Laminate and extruded tube filling demands heat-sealing equipment and crimp verification systems. E-commerce brands in California prioritize tube formats for shipping durability and shelf presence.
- Bottles:PET and glass bottle lines accommodate the broadest viscosity range across personal care categories. Retailer consolidation pressures manufacturers toward high-speed rotary fillers with changeover flexibility.
- Jars:Wide-mouth containers require precision dosing for anhydrous balms and cream formulations.
- Pouches:Flexible format production leverages existing food packaging infrastructure with modified sealing parameters.
Tubes anchor premium positioning. Pouches are climbing the fastest as sustainability credentials reshape procurement criteria.
Service Type:
Service depth defines client relationship duration, intellectual property arrangements, and margin capture mechanics.
- Private Label:Catalog-based production of established formulations minimizes development timelines and regulatory risk. Margin compression intensifies as retailer consolidation concentrates buying power among fewer accounts.
- Custom Formulation:Bespoke development from concept to commercialization commands premium pricing and longer contract tenures. Biotechnology-derived actives and clean beauty certifications extend project timelines while deepening manufacturer-client interdependence.
- Filling Services:Toll manufacturing of client-supplied bulk material operates on capacity utilization metrics with limited differentiation.
- Labeling:Secondary packaging and regulatory text compliance represents the lowest-margin, highest-volume service tier.
Private Label dominates volume throughput. Custom Formulation delivers the steepest expansion trajectory as indie brand proliferation accelerates.
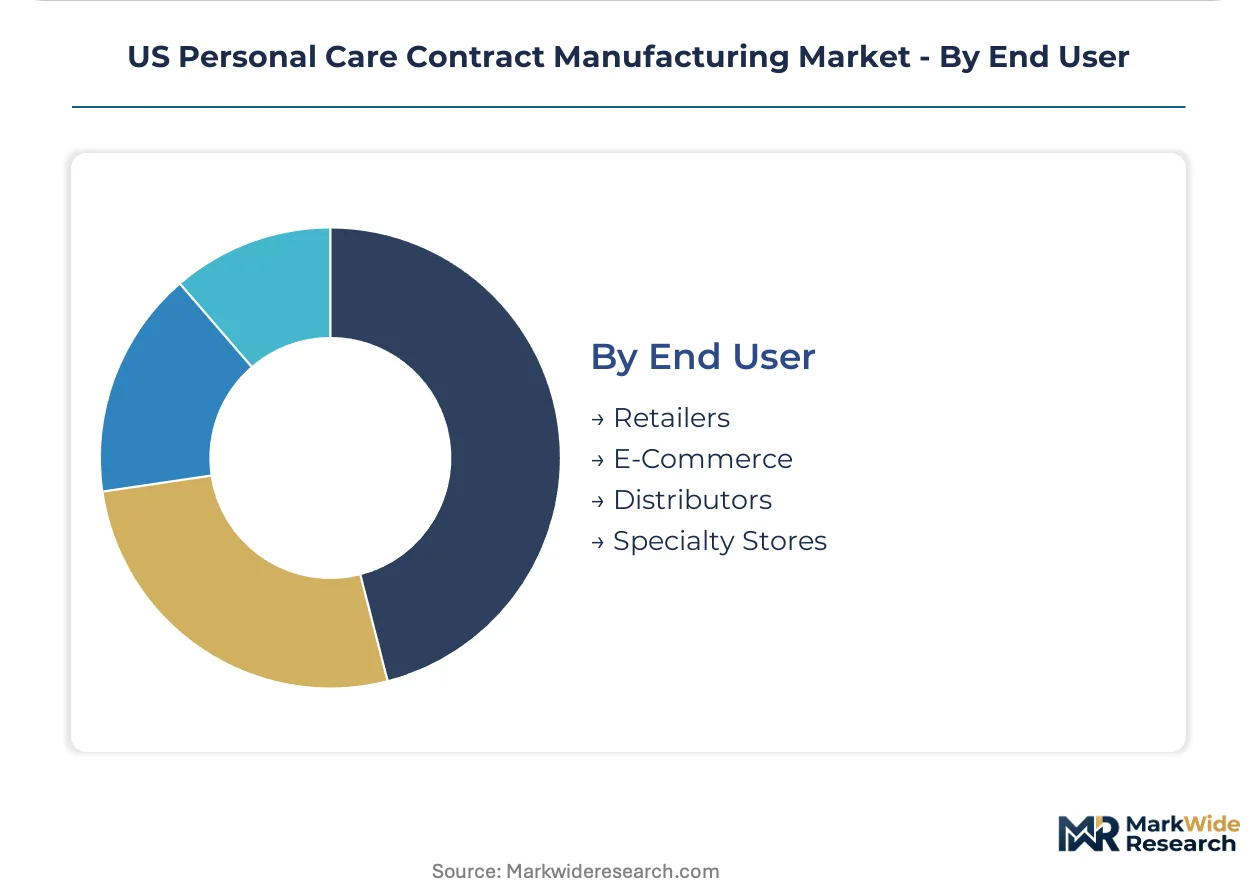
End User:
Channel structure dictates order patterns, SKU complexity tolerance, and inventory management requirements.
- Retailers:Mass and prestige retail accounts demand seasonal volume spikes with strict delivery windows. Proposition 65 compliance documentation requirements from California attorneys general actions elevate manufacturer selection criteria.
- E-Commerce:Direct-to-consumer brands prioritize turnkey bundles combining formulation, fulfillment, and inventory management. Subscription model adoption in New Jersey and California concentrates demand for flexible minimum order quantities.
- Distributors:Middle-tier channel partners seek private label programs with rapid turnaround and minimal development investment.
- Specialty Stores:Curated retail environments value exclusive formulations and limited-batch positioning.
Retailers maintain legacy volume concentration. E-Commerce is gaining share fastest as digital-native brands bypass traditional distribution infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California manufacturers command premium pricing for clean beauty formulation services, while Texas operators undercut by 15-20 percent on comparable batch production. This pricing-power asymmetry reflects regulatory compliance cost differentials and talent concentration effects.
California
Indie skin care brands and direct-to-consumer startups drive formulation demand for peptide and retinoid compounding. State attorneys general enforce Proposition 65 chemical disclosure mandates that elevate documentation requirements. Los Angeles and Orange County clusters host captive analytical laboratories serving brands with subscription-based distribution models.
New Jersey
High-SKU velocity hair care programs and seasonal volume spikes characterize retailer-facing production. FDA facility registration requirements under MoCRA impose fixed administrative burdens on batch manufacturers. The Meadowlands-to-Princeton corridor concentrates turnkey service providers bundling formulation with fulfillment infrastructure.
Texas
Lower facility costs and favorable tax treatment attract manufacturers seeking alternatives to coastal concentration. OSHA standards on batching facility worker exposure limits still apply but enforcement intensity varies regionally. The Dallas-Fort Worth metro anchors emerging production capacity for men's grooming and mass-market body care lines.
Illinois
Midwest retail distribution networks and private label programs sustain volume throughput for catalog-based manufacturers. EPA volatile organic compound regulations affect aerosol production equipment decisions. Chicago-area facilities leverage existing food packaging infrastructure for flexible pouch format diversification.
Florida
Sun care and anhydrous balm production aligns with regional brand positioning and tourism-adjacent retail channels. State-level cosmetic safety statutes complement federal oversight without the stringency of California enforcement. Miami and Tampa Bay formulation clusters serve Latin American market access strategies for US-based brand owners.
US Personal Care Contract Manufacturing Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper technical positioning. The US personal care contract manufacturing base fragments across three structural tiers: multinational integrated networks, regional turnkey providers, and single-format niche operators. Strategic archetypes include R&D-forward formulation houses, capacity-maximizing toll manufacturers, and certification-heavy compliance specialists. Dominant competitive moves center on captive laboratory acquisition and southern-state facility expansion to escape coastal cost structures.
Within the integrated platform tier, Fareva anchors large-volume programs through multi-campus R&D and manufacturing coordination. Intercos S.p.A. occupies a position exemplifying color cosmetics specialization and speed-to-market capabilities. Eco Lips, Inc. represents the defensible niche archetype, sustaining regional brand relationships in lip balm contract manufacturing without direct competition from full-service operators.
| Leading Market Players |
|---|
| Eco Lips, Inc. |
| Fareva |
| Intercos S.p.A. |
| Biogenesis |
| NuWorld |
| 220 Laboratories |
| Accupack Midwest, Inc. |
| Bright International |
| Verla International Ltd. |
| Others |
Cost & Logistics Intelligence
Tariff exposure on German and Swiss specialty chemical imports compresses margin structures across formulation tiers while simultaneously forcing geographic diversification in raw material sourcing. This trans-Atlantic logistics vulnerability widens the spread between premium compliant manufacturers and standard-tier operators while reshaping inventory positioning strategies.
Pricing Analysis
The customization-premium spread separates turnkey formulation bundles from private label catalog pricing by 25-40 percent. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with ISO 22716-compliant manufacturers commanding tier-one positioning. Cost compression in the standard tier is intensifying because retailer consolidation concentrates buying power among fewer accounts. Indie direct-to-consumer brands exhibit the lowest price sensitivity, prioritizing speed-to-market and regulatory documentation over unit cost minimization.
Supply Chain Analysis
Trans-Atlantic logistics volatility on specialty chemical lanes dominates supply chain risk assessment for US contract manufacturers. Key emulsifiers and preservative systems draw from German, Swiss, and limited domestic production capacity. Single-source vulnerability concentrates in peptide and postbiotic active ingredients with limited qualified suppliers. Distribution runs through California and New Jersey formulation clusters serving direct-to-consumer brands, with emerging hub development in Texas and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across service tiers creates defendable niche positions as direct-to-consumer channel expansion multiplies buyer archetypes with divergent technical requirements. Clean beauty certification mandates and biotechnology-derived active handling needs are spawning specialist sub-segments faster than integrated platforms can absorb them.
For Market Incumbents: Insulate formulation expertise through captive analytical laboratory acquisition and pre-validated ingredient library expansion. Acquire regional turnkey providers in Texas and Florida to escape coastal cost structures. ISO 22716 certification timelines create barriers that favor early movers consolidating compliant capacity. For New Entrants and Emerging Players: Build out waterless and solid format production capabilities using existing equipment retrofits rather than greenfield investment. Men's grooming formulation services represent the most penetrable white space, with gender-specific positioning expertise scarce among established operators. Pursue outcome-based service agreements tying fees to stability test passage rates as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors R&D-forward formulation houses with captive laboratory infrastructure. Long-term viability hinges on regulatory compliance capability deepening rather than pure scale expansion. Watch MoCRA enforcement intensity and state-level ingredient ban proposals as the signal for reformulation demand cycle inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Laboratory Acquisition | Pre-validated ingredient libraries compress development timelines for clean beauty certification requirements. |
| Southern State Facility Expansion | Texas and Florida production capacity exploits 15-20 percent cost differentials versus California operators. |
| Digital Formulation Platform Integration | Algorithmic ingredient matching virtualizes traditional cosmetic chemist roles for indie brand clients. |
| Men's Grooming Service Line Launch | Underdeveloped contract manufacturing capacity creates first-mover positioning in male-targeted skin care. |
| Waterless Format Equipment Retrofit | Anhydrous balm and shampoo bar production leverages sustainability-driven brand procurement criteria. |
Research Approach
A spread of perspectives from cosmetic chemists, brand procurement managers, contract manufacturing executives, and regulatory affairs specialists converged on the working assumptions. Primary interviews with formulation directors and direct-to-consumer brand founders combined with secondary validation against FDA facility registration databases, EPA volatile organic compound compliance records, and state attorney general Proposition 65 enforcement actions. Bottom-up capacity utilization modeling and top-down demand aggregation triangulated volume estimates across the analysis window.
Demand-supply-balance framing anchored the analytical framework, with segmentation dimensions spanning product type, service depth, packaging format, and end-user channel structure. CAGRs derived from fitted growth curves reflecting biotechnology-derived active adoption rates and clean beauty certification penetration trajectories. Inventory flexibility requirements from subscription-model brands and seasonal volume spike patterns from retailer accounts informed demand-side elasticity assumptions throughout the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by German and Swiss chemical suppliers or accelerated FDA enforcement under MoCRA would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
China Electric Face Cleanser Market
Beauty & Personal Care
Liquid Soap Market
Beauty & Personal Care
Organic Liquid Soaps Market
Beauty & Personal Care
GCC Male Grooming Products Market
Beauty & Personal Care
North America Hair Removal Wax Market
Beauty & Personal Care
North America Beauty Devices Market
Beauty & Personal Care
Russia Beauty and Personal Care Market
Beauty & Personal Care
Organic Shampoo Market
Beauty & Personal Care
India Herbal Shampoo Market
Beauty & Personal Care
Brazil Dermocosmetics Market
Beauty & Personal Care
Facial Steamer Market
Beauty & Personal Care
Loofah Bath Sponge Market
Beauty & Personal Care
Hair Serums Ingredient Market
Beauty & Personal Care
Makeup Brush and Tool Market
Beauty & Personal Care
Global and North America Organic and Natural Feminine Care Market
Beauty & Personal Care
Asia-Pacific Beauty and Personal Care Products Market