
 Global Marijuana Market | 2026-2036
Global Marijuana Market Size, Share, and Industry Trends Forecast 2026-2036
Global Marijuana Market Outlook
Precision-controlled indoor cultivation with automated environmental monitoring is tilting production economics toward pharmaceutical-grade consistency. Curaleaf leverages multi-state operational scale to sustain margins across volatile wholesale pricing. Green Thumb Industries anchors retail presence through controlled vertical real estate in limited-license jurisdictions. Tilray Brands competes on EU-GMP certified export capacity for medical cannabis channels.
Marijuana comprises dried Cannabis sativa or Cannabis indica flower and derived extracts containing cannabinoids such as THC and CBD, cultivated under controlled photoperiod and humidity conditions for therapeutic or adult-use consumption. The analysis tracks product type, end user, form, and distribution channel as structural dimensions. Flower retains volume leadership in North American retail, though oil and concentrates capture expanding margin pools as extraction technology improves. Medical patients and recreational users diverge sharply in purchase frequency and price sensitivity, with research institutions representing a thin but high-specification demand layer served through tightly regulated procurement.
FDA maintains Schedule I classification for cannabis at the federal level in the United States, fragmenting banking access and interstate commerce while state-level frameworks proliferate. Health Canada enforces mandatory testing for microbial contaminants and THC potency labeling under the Cannabis Act, shaping product standardization for export-oriented producers. Germany's BfArM and Australia's TGA both operate special access schemes for medical cannabis, creating parallel prescription pathways that favor GMP-certified suppliers. Stakeholders must calibrate compliance investment against jurisdiction-specific licensing timelines as regulatory divergence deepens between medical and adult-use frameworks.
Market Dynamics
Precision-controlled cultivation infrastructure is compressing production costs while pharmaceutical-grade certification requirements are fragmenting supplier tiers across medical and adult-use channels.
Growth Catalysts
- Germany's BfArM pharmacy distribution mandate:Medical patients now access cannabis through regulated pharmacy channels, creating structured demand for EU-GMP certified suppliers.
- Extraction technology maturation:Supercritical CO2 and ethanol processing methods are improving cannabinoid recovery rates and enabling standardized oil formulations for medical applications.
- California's track-and-trace infrastructure:Seed-to-sale compliance systems have established de facto quality benchmarks that influence product specifications in adjacent markets.
Market Restraints
- FDA Schedule I classification:Federal prohibition in the United States fragments banking access and prevents interstate commerce, forcing state-siloed supply chains.
- Energy input cost volatility:Indoor cultivation's dependence on HVAC and LED systems exposes producers to electricity price swings that compress operating margins.
- Input concentration in proprietary genetics:Elite cultivar IP concentrates among limited breeding operations, creating supply bottlenecks for consistent phenotype expression.
Strategic Opportunities
- Australia's TGA special access scheme:Expanding patient eligibility criteria are opening prescription pathways for imported GMP-certified medical cannabis products.
- Minor cannabinoid isolation:CBG and CBN extraction capabilities are creating differentiated product lines for targeted therapeutic applications beyond THC-CBD formulations.
- Direct-to-patient telehealth channels:Remote consultation platforms are collapsing traditional pharmacy intermediaries in jurisdictions with liberalized prescribing rules.
Industry Challenges
- EU-GMP certification timeline compression:Facility validation and batch release protocols require 18-24 month compliance cycles that delay market entry.
- Cross-border payment infrastructure gaps:Banking exclusion forces reliance on cash-intensive transactions and cryptocurrency workarounds that increase security overhead.
- Batch consistency under biological variability:Living plant inputs create inherent chemical variation that conflicts with pharmaceutical standardization requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Marijuana Market |
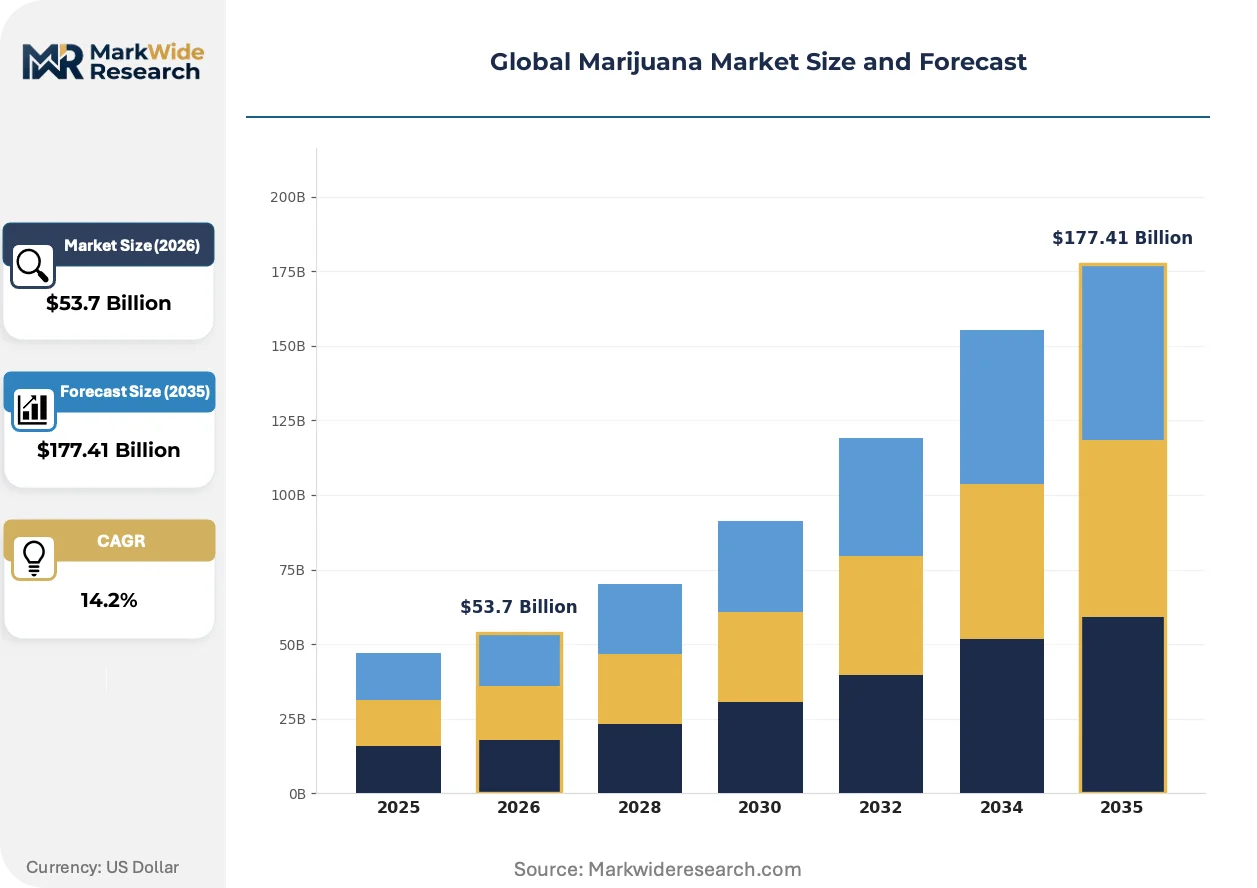
| Market Size in 2026 | $53.7 Billion |
| Market Size in 2035 | $177.41 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flower, Oil, Edibles, Concentrates End User: Recreational Users, Medical Patients, Research Institutions, Dispensaries Form: Loose Leaf, Pre-Rolls, Capsules, Tinctures Distribution Channel: Retail Stores, Online, Pharmacies, Direct Sales |
| Companies Covered | Curaleaf, Green Thumb Industries, Trulieve, Canopy Growth Corporation, Tilray Brands, Cresco Labs, Aurora Cannabis, Verano Holdings, Cronos Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Marijuana Market Strategic Shifts
Automation and data capture systems are penetrating cultivation operations while regulatory divergence between medical and adult-use frameworks is forcing parallel compliance architectures.
Environmental monitoring platforms integrating IoT sensors with cloud-based analytics are digitizing climate control decisions across commercial grow operations. Large-scale producers in Canada and the Netherlands are deploying these systems to reduce labor inputs and compress deviation response times from hours to minutes. This digitization is enabling real-time yield optimization that was previously impossible under manual monitoring regimes.
Health Canada's mandatory microbial and potency testing requirements under the Cannabis Act are reshaping product release protocols for export-oriented producers. Batch retention and third-party laboratory verification now extend production cycles by 7-14 days. Australian importers and German distributors are prioritizing suppliers with in-house analytical capabilities to compress total delivery timelines.
Medical patients are consolidating purchasing around cannabinoid-specific formulations rather than strain-based flower selection. Dispensary buyers in California and Colorado are responding with SKU rationalization that emphasizes consistent dosing over varietal diversity. This specification-driven procurement is most visible in chronic pain and pediatric epilepsy segments where physicians require documented cannabinoid profiles for treatment calibration.
Global Marijuana Market Segmentation
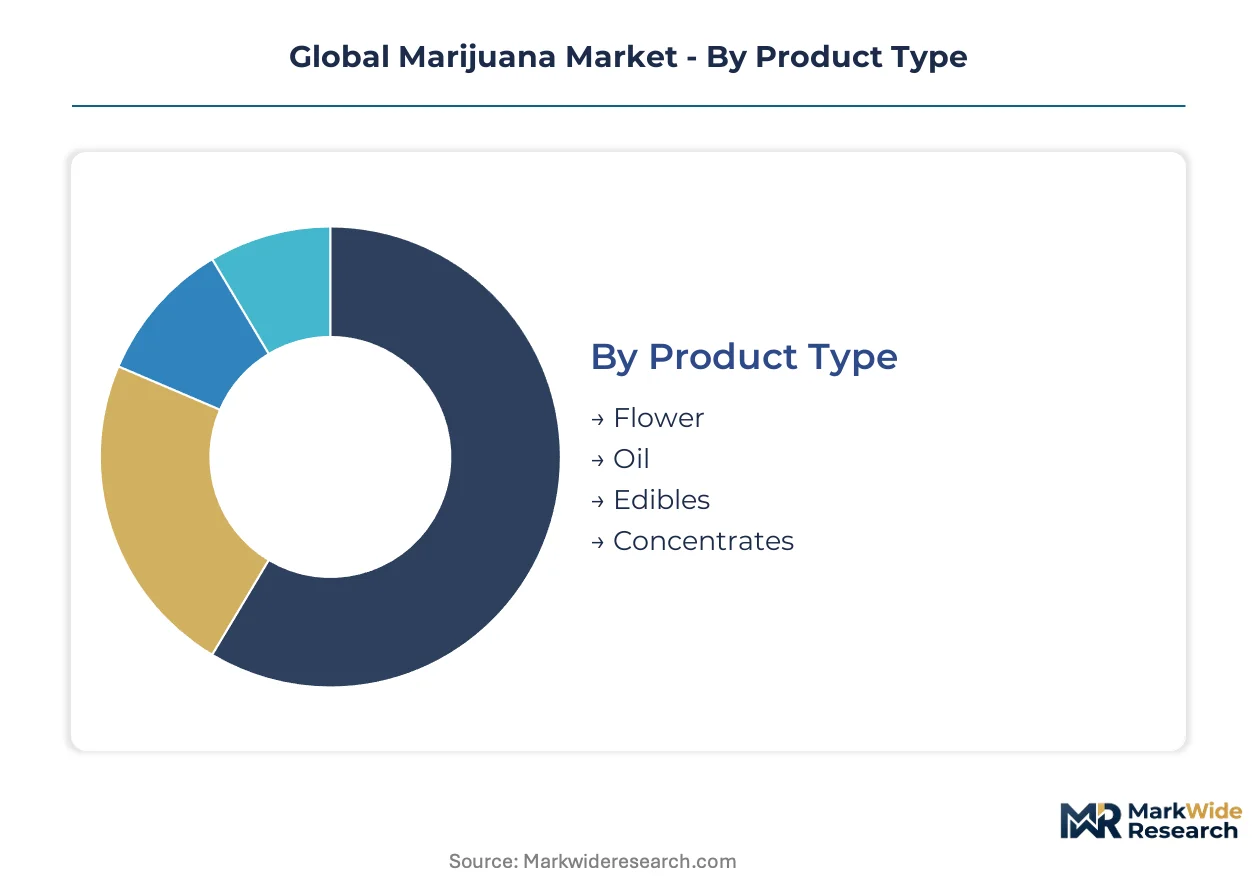
Segmentation in the marijuana market reflects divergent compliance architectures between medical and adult-use channels, with each dimension carrying distinct margin structures and regulatory burdens. Product form and distribution pathway choices directly determine facility certification requirements and customer access protocols.
Product Type:
Cost tier alignment separates commodity flower from value-added derivatives, with extraction complexity driving capital intensity and margin capture.
- Flower:Dried cannabis inflorescence containing intact trichome structures with variable cannabinoid profiles. Volume concentrates in California's dispensary network and Canada's provincial retail systems, where testing mandates for microbial contaminants and potency labeling have standardized quality thresholds. Flower holds installed capacity. Concentrates is rotating up the share rankings.
- Oil:Lipid-soluble cannabinoid extracts suspended in carrier mediums for precise dosing applications. Demand clusters in Germany's BfArM pharmacy distribution and Australia's TGA special access scheme, where EU-GMP certification requirements favor pharmaceutical-grade suppliers with validated extraction protocols.
- Edibles:Food-matrix products incorporating standardized cannabinoid infusions for discrete consumption.
- Concentrates:High-potency extracts including wax, shatter, and live resin produced through solvent or mechanical separation methods.
Extraction-based products capture expanding margin pools as technology improves recovery rates and formulation consistency.
End User:
Customer type determines pricing tolerance, purchase frequency, and regulatory documentation requirements across divergent access frameworks.
- Recreational Users:Adult consumers purchasing through licensed retail channels in jurisdictions with federal or state-level legalization. Canada's Cannabis Act framework and California's Bureau of Cannabis Control oversight shape product availability and marketing restrictions. Medical Patients holds installed capacity. Recreational Users is rotating up the share rankings.
- Medical Patients:Prescription-holding consumers accessing cannabis through pharmacy or clinic channels under physician supervision. Germany's BfArM and Australia's TGA operate parallel special access schemes requiring GMP-certified supply chains and documented cannabinoid profiles for treatment calibration.
- Research Institutions:Universities and pharmaceutical laboratories conducting controlled studies under restricted substance licenses.
- Dispensaries:Licensed retail intermediaries managing inventory, compliance, and patient education in vertically integrated or open-market jurisdictions.
Medical channels sustain premium pricing through certification requirements that exclude commodity suppliers.
Form:
Application convenience drives format selection, with pre-dosed products gaining share in medical segments and combustion alternatives expanding in adult-use markets.
- Loose Leaf:Unprocessed flower requiring grinding and combustion or vaporization equipment for consumption. Traditional format dominates legacy markets, though health concerns and odor restrictions limit adoption in smoke-free housing and employment contexts.
- Pre-Rolls:Machine-rolled joints with standardized weights and filter configurations for immediate use. Manufacturing concentrates in automated facilities serving California, Colorado, and Ontario retail networks, where convenience positioning commands per-gram premiums over loose flower. Pre-Rolls holds installed capacity. Tinctures is rotating up the share rankings.
- Capsules:Gelatin or vegetable-based shells containing measured oil doses for precise titration and discrete ingestion.
- Tinctures:Alcohol or oil-based liquid extracts administered sublingually for rapid onset without pulmonary exposure.
Ready-to-use formats compress the path from purchase to consumption, reducing equipment barriers for new adopters.
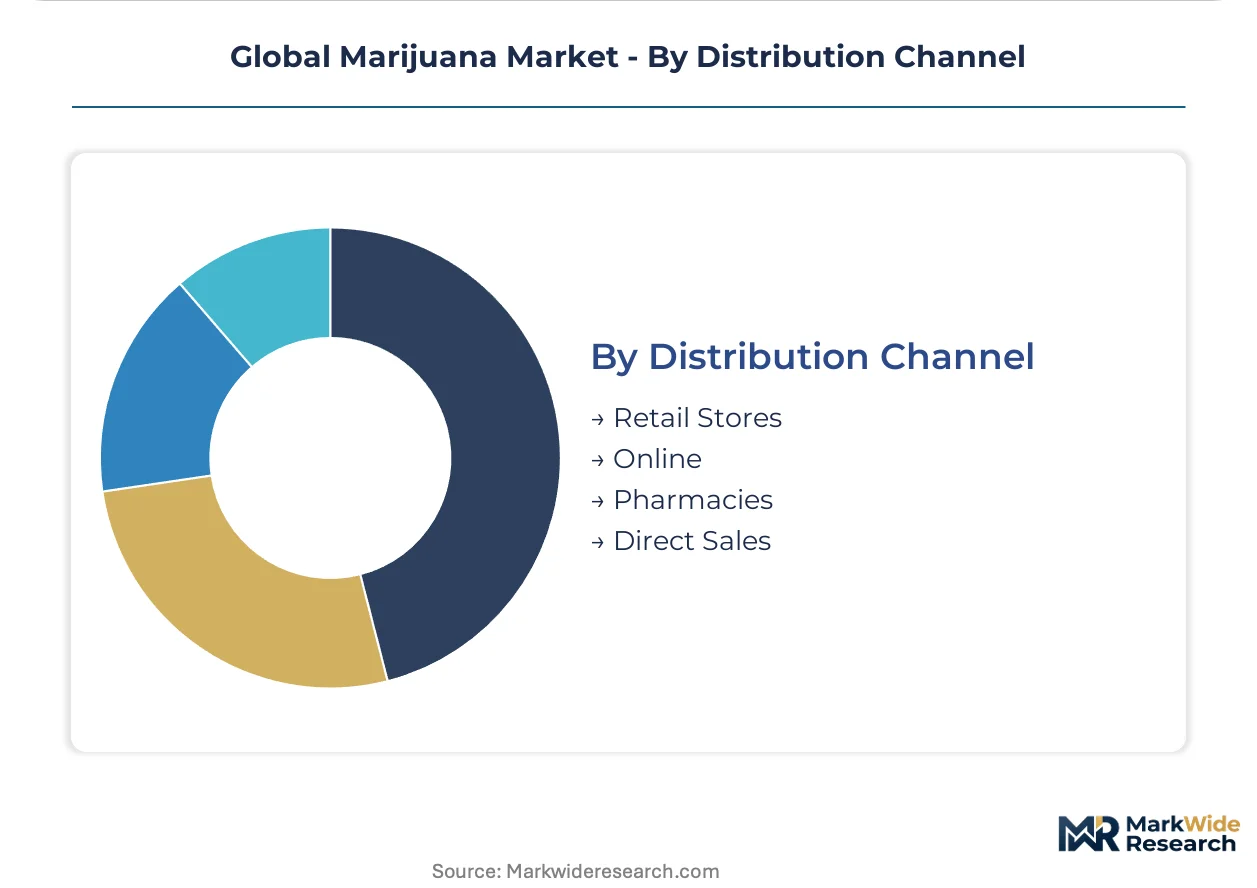
Distribution Channel:
Geography and regulatory maturity determine channel viability, with pharmacy access reserved for medical frameworks and direct models emerging in liberalized jurisdictions.
- Retail Stores:Physical dispensaries with age verification, product consultation, and immediate fulfillment. California's track-and-trace infrastructure and Canada's provincial retail monopolies represent contrasting regulatory models for brick-and-mortar expansion. Retail Stores holds installed capacity. Online is rotating up the share rankings.
- Online:E-commerce platforms with age-gated access and delivery logistics. Health Canada permits direct-to-consumer shipping from licensed producers, while US state frameworks fragment interstate digital commerce under FDA Schedule I constraints.
- Pharmacies:Regulated drug distribution points with pharmacist oversight and insurance integration potential. Germany's BfArM mandate channels all medical cannabis through this tier, creating structured demand for EU-GMP certified inventory.
- Direct Sales:Producer-to-patient relationships cultivated through telehealth consultations and subscription models.
Channel diversification reflects jurisdictional variation in licensing density and consumer access preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian licensed producers supply Germany's BfArM pharmacy channel and Australia's TGA special access scheme, establishing the dominant medical cannabis trade corridor while California's mature dispensary network sets quality benchmarks for adjacent markets.
United States
California's track-and-trace infrastructure and Colorado's mature dispensary networks anchor North American demand. FDA Schedule I classification fragments banking access and prevents interstate commerce, forcing state-siloed supply chains. Los Angeles and Denver clusters concentrate vertically integrated operators serving both medical and adult-use segments under divergent state frameworks.
Germany
Medical patients access cannabis exclusively through BfArM-regulated pharmacy channels, creating structured demand for EU-GMP certified imports. Germany's statutory health insurance reimbursement system expanded patient eligibility criteria. Berlin and Cologne distribution hubs handle bulk imports from Canadian and Dutch suppliers for nationwide pharmacy fulfillment.
Canada
Federal legalization under the Cannabis Act enables both domestic retail expansion and export-oriented production for medical channels. Health Canada enforces mandatory microbial and potency testing that shapes product standardization. Ontario and British Columbia cultivation clusters supply provincial retail monopolies while Alberta and Quebec facilities target EU-GMP certification for German and Australian exports.
Australia
TGA special access schemes opened prescription pathways for imported GMP-certified medical cannabis, with patient eligibility expanding for chronic pain and pediatric epilepsy. Domestic production remains limited by licensing timelines. Sydney and Melbourne clinical trial networks drive demand for documented cannabinoid profiles from Canadian and European suppliers.
Netherlands
Bedrocan operates as the sole government-contracted producer under the Office of Medicinal Cannabis framework, supplying standardized medical cannabis to German and Italian pharmacy channels. Dutch greenhouse cultivation expertise informs EU-GMP facility design across Europe. Wageningen research clusters advance controlled-environment agriculture protocols adopted by export-oriented producers.
Global Marijuana Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented licensing environments. The vendor base separates into three tiers: multi-state operators with retail real estate control, pharmaceutical-grade exporters with EU-GMP certification, and regional cultivators serving single-state wholesale markets. Dominant competitive moves include backward integration into cultivation capacity and geographic expansion through limited-license acquisitions.
Within the multi-state operator tier, Curaleaf and Green Thumb Industries exemplify retail-anchored expansion strategies, while Tilray Brands occupies a position among pharmaceutical-grade exporters targeting EU medical channels. These three companies represent contrasting archetypes: retail density versus certification-driven medical access versus hybrid adult-use and pharmaceutical positioning.
| Leading Market Players |
|---|
| Curaleaf |
| Green Thumb Industries |
| Trulieve |
| Canopy Growth Corporation |
| Tilray Brands |
| Cresco Labs |
| Aurora Cannabis |
| Verano Holdings |
| Cronos Group |
| Others |
Value Chain & Pricing Dynamics
Amsterdam-Rotterdam-Antwerp corridor freight costs cascade through EU-GMP certified supply chains, compressing margins for Canadian exporters while amplifying price premiums for pharmacy-distributed medical products against California dispensary benchmarks.
Pricing Analysis
Cost-plus contracts with electricity indexation dominate cultivation supply agreements, linking input costs to regional grid tariffs. Three-tier pricing structure across pharmaceutical-grade, premium adult-use, and wholesale commodity levels separates EU-GMP certified oils from track-and-trace verified flower and untested biomass. Pricing pressure stems from energy input volatility in Dutch and Canadian greenhouse operations. Medical patients demonstrate lowest price sensitivity due to insurance reimbursement, while recreational bulk buyers in California's wholesale tier face acute margin compression.
Supply Chain Analysis
Contract manufacturing concentration sits with Canadian licensed producers, Dutch greenhouse operators, and German pharmaceutical compounders holding validated EU-GMP capacity. Geographic supply anchors in Canada, the Netherlands, and Germany feed medical channels, while California, Colorado, and Oregon cultivation clusters serve North American adult-use retail. Raw material dependencies center on elite cultivar genetics, specialized LED horticultural lighting, and pharmaceutical-grade extraction solvents. Single-source vulnerability concentrates in proprietary breeding operations controlling consistent phenotype expression. Distribution runs through pharmacy channels under BfArM oversight for medical patients, with direct-to-consumer platforms emerging in Health Canada-permitted jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
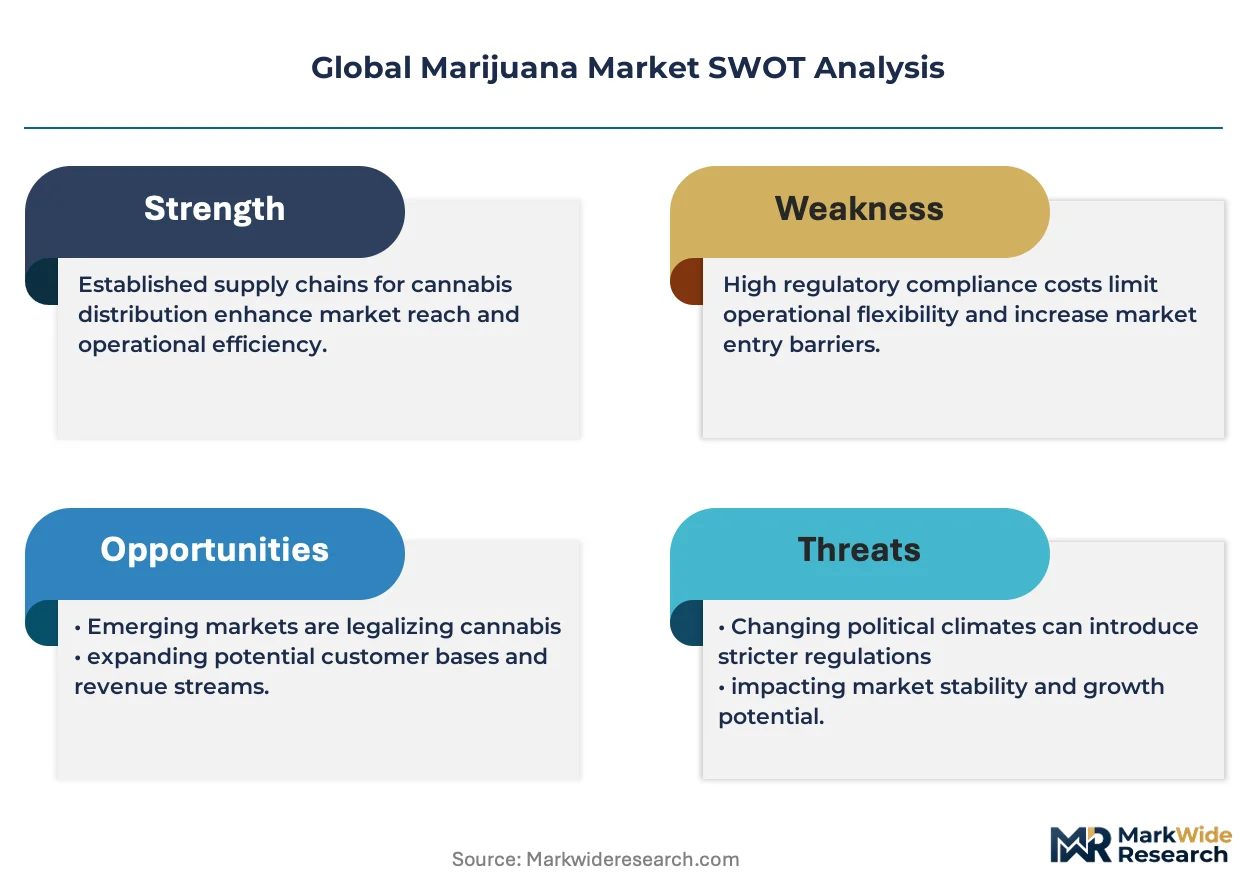
EU-GMP certification bottlenecks constrain supply-side expansion, creating asymmetric returns for operators possessing validated pharmaceutical infrastructure versus commodity cultivators facing margin erosion from energy cost volatility and wholesale price compression.
For Market Incumbents: Entrench pharmacy channel control through backward integration into EU-GMP certified cultivation capacity in Ontario and British Columbia, defending against German import quota expansion and Australian TGA eligibility broadening that favors incumbent certification holders. Prioritize batch release protocol automation to compress 18-24 month compliance cycles and preempt emerging Dutch and Portuguese competitors. For New Entrants and Emerging Players: Australia's TGA special access scheme expansion for chronic pain and pediatric epilepsy represents the most penetrable entry point for GMP-certified imports, with direct-to-patient telehealth platforms collapsing traditional pharmacy intermediaries in jurisdictions with liberalized prescribing rules. Minor cannabinoid isolation capabilities for CBG and CBN formulations offer differentiation without competing on THC-CBD volume. For Investors and Strategic Acquirers: Mid-scale Canadian licensed producers with dormant EU-GMP certification and established German distributor relationships represent the highest-conviction acquisition archetype for medical channel exposure. Monitor Health Canada export permit issuance velocity and BfArM import quota expansion announcements as inflection indicators for capacity utilization rates across certified facilities.| Strategic Initiative | Industry Significance |
|---|---|
| EU-GMP Certification Acceleration | Compressed facility validation timelines unlock German BfArM pharmacy channel access before competitor capacity comes online. |
| Minor Cannabinoid Extraction Scale-Up | CBG and CBN isolation capabilities create therapeutic product differentiation beyond commoditized THC-CBD formulations. |
| Direct-to-Patient Telehealth Integration | Remote consultation platforms collapse pharmacy intermediaries in Australia's TGA and Germany's liberalized prescribing frameworks. |
| Energy Cost Hedging Infrastructure | On-site renewable generation and grid-tariff agreements insulate Dutch and Canadian greenhouse margins from electricity volatility. |
| Proprietary Genetics Lock-Up | Exclusive licensing agreements with elite breeding operations secure consistent phenotype expression for pharmaceutical standardization. |
Study Parameters
Cross-validation between licensed producer shipment disclosures and Health Canada export permit records anchors the qualitative findings, combining primary interviews with cultivation operations directors, EU-GMP quality assurance leads, German pharmacy procurement managers, and Australian TGA regulatory consultants with secondary validation through FDA enforcement actions, EMA GMP inspection databases, BfArM import statistics, and provincial retail sales disclosures. Bottom-up facility capacity modeling and top-down channel volume reconciliation triangulate supply-side estimates.
Calibration against historical price series for flower, oil, and concentrate tiers across California, Canada, and Germany informs elasticity assumptions across the projection horizon. Segmentation dimensions span product form, end-user category, distribution channel, and certification grade. CAGRs derive from installed capacity ramp schedules, patient eligibility expansion trajectories, and jurisdiction-specific licensing velocity. Forecast inputs incorporate electricity tariff regimes, EU-GMP inspection backlogs, and track-and-trace system adoption rates.
Practitioners should monitor German statutory health insurance reimbursement decisions, Australian TGA scheduling amendments, and FDA rescheduling proceedings for early signals requiring forecast revision. Quarterly review of Health Canada export permit issuance, BfArM import quota utilization, and California wholesale price indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Australia Legal Cannabis Market
Cannabis/Marijuana
Missouri Legal Cannabis Market
Cannabis/Marijuana
Global Cannabis Extract Market
Cannabis/Marijuana
North America Medical Cannabis Market
Cannabis/Marijuana
North America Legal Cannabis Market
Cannabis/Marijuana
Europe CBD Patch Market
Cannabis/Marijuana
Legal Marijuana Market
Cannabis/Marijuana
Mexico Hemp CBD Market
Cannabis/Marijuana
Hemp Derivatives Market
Cannabis/Marijuana
Mexico Medical Cannabis Market
Cannabis/Marijuana
Africa Medical Cannabis Market
Cannabis/Marijuana
Cannabinoid CB2 Products Market
Cannabis/Marijuana
Marijuana Sensors Market
Cannabis/Marijuana
Global Cannabis Industry Software Market
Cannabis/Marijuana
Germany and Netherlands Medical Marijuana Market
Cannabis/Marijuana
Missouri Medical Cannabis Market